
 Portable Battery Station Market | 2026-2036
Portable Battery Station Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Battery Station Market Insights
Subscription-based power management software is consolidating what portable battery station vendors monetize beyond hardware. EcoFlow leverages firmware-enabled capacity expansion to sustain recurring revenue. Jackery anchors its brand strength through proprietary solar panel pairing protocols. Anker Innovations competes on channel control, dominating Amazon marketplace visibility for sub-1000Wh units.
A portable battery station is a self-contained electrochemical energy storage device, typically employing lithium iron phosphate or nickel manganese cobalt cell chemistry within a 500Wh to 2000Wh enclosure, designed to deliver AC and DC output for off-grid or backup power scenarios. The lithium-ion battery segment captures premium margin pools as energy density improvements reduce weight-to-capacity ratios. Solar generators represent the fastest-growing product category as panel integration becomes standard. Emergency services applications command higher price points due to ruggedization requirements and rapid-deployment specifications.
EPA Tier 4 emissions standards constrain gasoline generator deployment in populated areas, directly expanding addressable demand for battery alternatives. FCC Part 15 certification requirements govern inverter noise emissions, creating compliance barriers for new entrants. NHTSA regulations on transported battery quantities shape logistics costs for cross-border fulfillment. Stakeholders must monitor evolving UN 38.3 lithium transport classifications and UL 2743 safety standards as capacity thresholds climb and thermal runaway testing protocols tighten.
Market Dynamics
EPA Tier 4 emissions standards are compressing gasoline generator deployment in populated zones, redirecting backup power demand toward electrochemical storage systems with zero direct emissions and lower lifecycle operating costs.
Growth Catalysts
- Recreational Vehicle Electrification:RV owners in the United States are replacing onboard propane generators with lithium iron phosphate stations to comply with national park noise restrictions and fuel transport limitations.
- Remote Work Infrastructure:Distributed workforces require reliable off-grid power for mobile workstations, expanding addressable demand beyond traditional outdoor recreation into professional services.
- IRA Clean Energy Credits:The Inflation Reduction Act's residential clean energy credit structure reduces effective acquisition costs for battery storage paired with solar generation systems.
Market Restraints
- Lithium Carbonate Volatility:Cathode material input costs fluctuate with South American brine extraction volumes and Chinese processing capacity constraints, compressing margin visibility for manufacturers.
- Cell Supply Concentration:Cylindrical and prismatic lithium-ion cell production concentrates in East Asian facilities, creating geographic single-source risk for non-integrated assemblers.
- Energy Density Physics:Theoretical limits of lithium-ion chemistry cap gravimetric energy density below 300 Wh/kg, restricting runtime extension without weight penalties that degrade portability.
Strategic Opportunities
- Grid-Forming Inverter Integration:Bidirectional power electronics enabling vehicle-to-home discharge are converging with stationary storage architectures, opening whole-home backup substitution for premium buyers.
- Subscription Firmware Monetization:Capacity expansion and performance optimization delivered through over-the-air updates create recurring revenue streams beyond hardware margins.
- Emergency Services Ruggedization:First responder agencies require MIL-STD-810H compliant enclosures with rapid-deployment specifications, commanding price premiums above consumer segments.
Industry Challenges
- Thermal Runaway Testing Protocols:UL 2743 certification timelines extend as capacity thresholds climb and nail penetration test requirements tighten, delaying product launch windows.
- UN 38.3 Logistics Friction:Lithium battery transport classifications impose quantity limits on cross-border fulfillment, fragmenting inventory positioning and elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Battery Station Market |
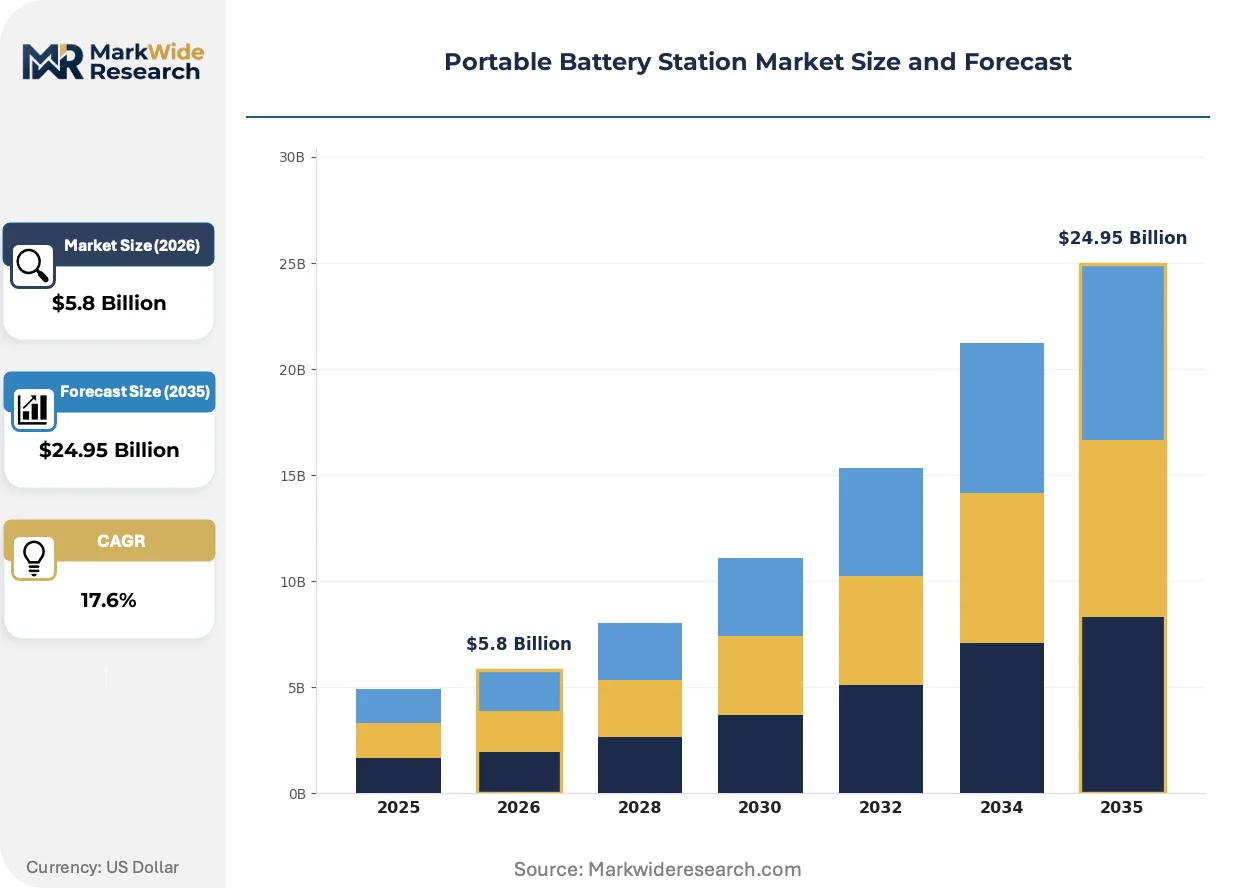
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $24.95 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Generators, UPS Systems, Lithium-ion Batteries, Lead-acid Batteries End User: Outdoor Enthusiasts, Remote Workers, Emergency Services, Residential Users Application: Camping, Off-Grid Power, Emergency Backup, Events Capacity: 500Wh, 1000Wh, 1500Wh, 2000Wh |
| Companies Covered | Goal Zero, Jackery, EcoFlow, Anker Innovations, Bluetti Power, Lion Energy, Duracell, Klein Tools, Yoshino Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Battery Station Market Trends and Innovations
Solid-state cell architectures and silicon-anode chemistries are approaching commercial viability, promising step-change improvements in safety and energy density that would redefine portable power form factors.
Solid-state batteries are integrating ceramic electrolyte layers that eliminate flammable liquid components while enabling lithium metal anodes. Military and aerospace procurement programs are piloting early production volumes for field-deployable power systems. This technology is integrating into next-generation product roadmaps as manufacturers position against impending thermal safety regulations.
REACH substance restrictions on nickel and cobalt compounds are compelling European vendors to accelerate lithium iron phosphate adoption despite energy density trade-offs. The industrial consequence is a bifurcation in cell chemistry strategies between EU-facing and other markets. Residential backup systems in Germany and the Netherlands are most affected, with distributors now requiring full material disclosure documentation.
Direct-to-consumer solar pairing bundles are displacing standalone battery transactions as the default purchase configuration. Specialty retailers and outdoor recreation channels are ceding volume to integrated ecosystem vendors who control panel compatibility protocols. This pattern is most visible in the United States and Japan, where rooftop solar penetration and recreational vehicle ownership intersect.
Portable Battery Station Market Segmentation
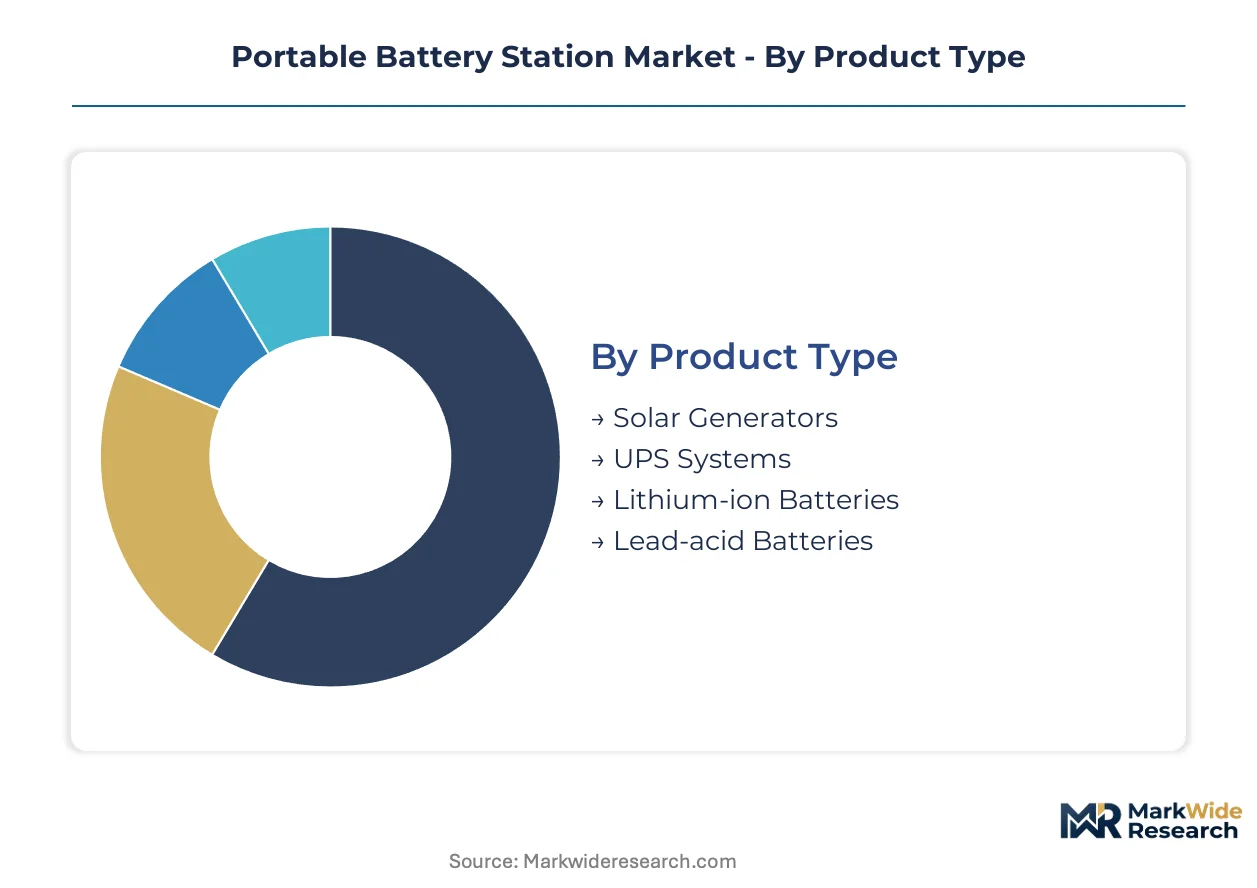
Portable battery station segmentation reveals divergent capital requirements across product architectures. Cell chemistry choices and capacity configurations determine manufacturing investment intensity. End-user applications impose distinct ruggedization and certification burdens.
Product Type:
Lithium-ion battery production demands the heaviest upfront capital deployment for cell assembly lines and dry-room facilities. Solar generator integration requires lower manufacturing intensity but higher R&D spend on power electronics.
- Solar Generators:Integrated photovoltaic-battery systems with proprietary panel compatibility protocols. Demand concentrates in the United States and Japan where rooftop solar penetration intersects with recreational vehicle ownership. IRA clean energy credits reduce effective acquisition costs for residential buyers pairing solar with storage.
- Lithium-ion Batteries:Self-contained electrochemical storage employing lithium iron phosphate or nickel manganese cobalt cell chemistries within 500Wh to 2000Wh enclosures. Outdoor enthusiasts and remote workers in Germany and the United States drive premium segment demand as EPA Tier 4 emissions standards compress gasoline generator deployment.
- UPS Systems:Uninterruptible power supply architectures with instant-switching inverters for sensitive electronics protection.
- Lead-acid Batteries:Legacy flooded and AGM chemistries with lower energy density but reduced thermal runaway risk profiles.
Most installed capacity flows through Lithium-ion Batteries. Expansion is steepest in Solar Generators.
End User:
Customer type determines pricing tolerance and procurement channel. Emergency services buyers accept substantial premiums for MIL-STD-810H compliance while residential users prioritize cost efficiency.
- Emergency Services:First responder agencies requiring rapid-deployment specifications and ruggedized enclosures. Demand concentrates in Japan and Germany where civil defense preparedness intersects with frequent natural disaster exposure. MIL-STD-810H thermal and shock testing protocols command price premiums above consumer segments.
- Remote Workers:Distributed professionals requiring reliable off-grid power for mobile workstations. The United States leads adoption as distributed workforce policies normalize and national park proximity drives recreational-professional hybrid use cases.
- Outdoor Enthusiasts:Camping and overlanding participants prioritizing weight-to-capacity ratios.
- Residential Users:Homeowners seeking backup power for grid outage scenarios.
Emergency Services capture the highest margin pools. Remote Workers are gaining share fastest as professional applications expand beyond traditional recreation.
Application:
Use case intensity shapes duty cycle requirements and warranty exposure. Continuous off-grid operation demands deeper discharge tolerance than intermittent backup scenarios.
- Off-Grid Power:Sustained autonomous operation for remote dwellings and mobile workstations. Germany and the Netherlands show concentration as residential solar-plus-storage adoption accelerates under EU Green Deal incentives. REACH substance restrictions on nickel and cobalt compounds compel lithium iron phosphate chemistry selection despite energy density trade-offs.
- Emergency Backup:Grid-failure standby power with instant-switching requirements. Japan anchors demand following grid reliability concerns from seismic events and typhoon exposure. METI safety standards govern installation protocols for residential battery quantities.
- Camping:Recreational outdoor power for lighting and small appliance operation.
- Events:Temporary power for outdoor gatherings and production activities.
Off-Grid Power absorbs the greatest installed base. Emergency Backup climbs the fastest as climate-related grid instability intensifies.
Capacity:
Energy density physics constrains runtime extension without weight penalties. Higher capacity tiers face escalating UL 2743 certification timelines as nail penetration test requirements tighten.
- 2000Wh:Whole-home backup substitution and extended off-grid operation. The United States leads adoption as bidirectional vehicle-to-home discharge capabilities converge with stationary storage architectures. FCC Part 15 certification requirements govern inverter noise emissions for grid-interactive operation.
- 1000Wh:Mobile workstation and multi-day camping power. Germany shows concentration among remote professionals requiring laptop and connectivity equipment operation. ECHA substance disclosure documentation now accompanies commercial distribution.
- 500Wh:Entry-tier portable power for lighting and small electronics.
- 1500Wh:Mid-tier capacity bridging recreational and professional applications.
1000Wh configurations move the greatest unit volume. 2000Wh systems are expanding most quickly as grid-forming inverter integration enables whole-home backup substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging regulatory compliance costs by shifting assembly toward jurisdictions with streamlined battery transport classifications and less stringent emissions oversight for production facilities.
United States
RV electrification and remote work infrastructure dominate demand as national park noise restrictions compress gasoline generator deployment. The Inflation Reduction Act's residential clean energy credit structure reduces effective acquisition costs for solar-plus-storage configurations. Austin and Denver anchor distributor concentration for outdoor recreation and professional hybrid use cases.
Germany
REACH substance restrictions on nickel and cobalt compounds accelerate lithium iron phosphate adoption despite energy density trade-offs. The EU Green Deal incentivizes residential solar-plus-storage systems in the Netherlands-adjacent border regions. Stuttgart and Munich host the densest clusters of remote professionals requiring mobile workstation power.
Japan
Seismic and typhoon exposure drives civil defense preparedness procurement for emergency backup systems with rapid-deployment specifications. METI safety standards govern residential battery installation protocols and quantity limits. Tokyo and Osaka concentrate demand for grid-failure standby power among disaster-prone metropolitan populations.
China
Cell supply concentration in East Asian facilities creates geographic single-source risk for non-integrated assemblers sourcing cylindrical and prismatic lithium-ion components. Dual carbon goals and MIIT industrial policy shape domestic manufacturing capacity allocation. Shenzhen and Dongguan anchor the deepest supplier ecosystems for power electronics integration.
Australia
Off-grid dwelling proliferation and mining camp electrification expand addressable demand for sustained autonomous operation systems. TGA-equivalent electrical safety standards and state-level solar feed-in tariffs influence procurement economics. Perth and Brisbane concentrate distribution for remote resource extraction and rural residential applications.
Portable Battery Station Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier vendors capturing margin through firmware-enabled differentiation while volume producers compete on channel access and procurement scale. The vendor base clusters around three strategic archetypes: ecosystem integrators controlling solar pairing protocols, marketplace-optimized brands dominating algorithmic retail visibility, and ruggedization specialists serving emergency services procurement. Dominant competitive moves include backward integration into cell supply and subscription-based recurring revenue attachment to hardware transactions.
Among the named specialists, EcoFlow and Jackery exemplify the ecosystem-integrator archetype, while Anker Innovations occupies a position calibrated to algorithmic retail channel optimization. These three anchors demonstrate how competitive positioning stratifies across firmware monetization capability, proprietary compatibility protocol control, and marketplace visibility engineering rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Goal Zero |
| Jackery |
| EcoFlow |
| Anker Innovations |
| Bluetti Power |
| Lion Energy |
| Duracell |
| Klein Tools |
| Yoshino Technology |
| Others |
Pricing and Supply Chain Analysis
Power electronics engineering talent concentration in Shenzhen and Dongguan establishes labor-cost differentials that widen pricing-tier spreads between premium firmware-enabled units and commodity-assembled alternatives.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for cylindrical lithium-ion cell supply. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810H certified emergency services units from consumer-grade camping equipment and entry-tier lighting power banks. Price differentiation hinges on UL 2743 certification grade and firmware-enabled capacity expansion subscriptions. Pricing pressure stems from lithium carbonate volatility compressing margin visibility for non-integrated assemblers. Residential users exhibit highest price sensitivity while emergency services buyers accept substantial premiums for rapid-deployment specifications.
Supply Chain Analysis
Returns and refurbishment flows for end-of-life battery stations concentrate in Chinese processing facilities recovering cobalt and nickel compounds. Cell production draws from China, South Korea, and Japan, with cylindrical and prismatic lithium-ion component supply tethered to East Asian dry-room assembly capacity. Raw material dependencies center on Chilean and Argentine lithium brine, Indonesian nickel laterite, and DRC cobalt concentrates. Single-source vulnerability in cathode precursor processing elevates working capital requirements for cross-border fulfillment. Distribution runs through Amazon marketplace algorithms for sub-1000Wh units and specialty outdoor recreation channels for solar generator bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by emergency services procurement shifting toward MIL-STD-810H ruggedization specifications that command durable margin premiums.
For Market Incumbents: Lock in backward integration into lithium iron phosphate cell supply to neutralize South American brine extraction volatility and Chinese processing capacity constraints. Secure proprietary solar panel pairing protocols before integrated ecosystem vendors consolidate direct-to-consumer bundle economics. Firmware-enabled recurring revenue attachment defends against marketplace-optimized brands competing on Amazon algorithmic visibility. For New Entrants and Emerging Players: Launch via subscription-based power management software tiers rather than hardware margin dependence. Target remote worker segments in Germany and the United States where distributed workforce policies normalize recreational-professional hybrid use cases. Penetrate through UL 2743 certification investment in 2000Wh grid-forming inverter architectures enabling whole-home backup substitution. For Investors and Strategic Acquirers: Power tool manufacturers and outdoor recreation conglomerates represent the most active acquirer in this space seeking firmware monetization capability. Long-term viability centers on solid-state cell architecture commercialization and silicon-anode chemistry transitions. Monitor EPA Tier 4 emissions standard enforcement intensity and IRA clean energy credit renewal signals as inflection indicators for gasoline generator substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Supply | Captive lithium iron phosphate production neutralizes cathode material cost volatility from Chilean brine extraction. |
| Firmware-Enabled Subscription Launch | Over-the-air capacity expansion creates recurring revenue streams beyond transactional hardware margins. |
| UL 2743 Certification Investment | Nail penetration test compliance unlocks premium-tier 2000Wh whole-home backup substitution demand. |
| Solar Pairing Protocol Control | Proprietary panel compatibility bundling displaces standalone battery transactions in United States and Japan. |
| Emergency Services Ruggedization | MIL-STD-810H thermal and shock testing commands price premiums above consumer segments in Japan and Germany. |
Research Methodology
Bottom-up remote worker and emergency services demand modeling reconciled against top-down lithium-ion cell supply tracking forms the analytical core of this study. Primary interviews with power electronics engineers, outdoor recreation channel buyers, first responder procurement officers, and solar installer network managers combined with secondary validation from EIA residential storage data, EPA Tier 4 compliance filings, UN 38.3 transport classification updates, and Amazon marketplace algorithmic visibility metrics.
Historical trendline analysis of lithium carbonate pricing and lithium iron phosphate adoption rates informed projection parameters across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement channel, application duty cycle intensity, and capacity tier with associated certification burden. CAGRs derived from unit volume trajectory reconciliation against value capture from firmware subscription attachment. Solid-state cell commercialization timelines and REACH substance restriction enforcement intensity served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price spike scenarios or UL 2743 certification timeline extensions. Forecasts reflect documented assumptions regarding IRA credit continuity and EPA enforcement intensity. Practitioners should monitor South American brine extraction volumes and METI residential battery quantity limit revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Coin Cell Lithium Batteries Market
Batteries
Power Battery Sealant Market
Batteries
Inverter Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Solid Electrolyte Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Battery Plate Market
Batteries
Italy Rechargeable Battery Market
Batteries
Nas Battery Market
Batteries
Utility Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
Custom Battery Pack Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
SLI Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Marine Powerboat Battery Market