
 Global Zinc Air Batteries Market | 2026-2036
Global Zinc Air Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zinc Air Batteries Market Outlook
EU Battery Regulation is restructuring the cost-of-entry calculus for zinc air cell producers selling into European medical and consumer channels. Duracell International leverages its hearing aid battery dominance to sustain premium shelf positioning across German and French retail pharmacies. Varta AG anchors its European manufacturing footprint with in-house zinc air electrode production, while Energizer Holdings competes through direct-to-audiologist distribution networks in North America.
Zinc air batteries generate electrical energy through the electrochemical oxidation of zinc metal in ambient oxygen, typically delivering 1.4V per cell with energy densities exceeding 400 Wh/kg in primary configurations. These cells power hearing aids, remote sensors, and rail signaling equipment where long shelf life and stable discharge profiles outweigh rechargeability requirements. Primary batteries occupy the largest revenue pool due to established hearing aid demand, while rechargeable batteries attract R&D investment from automotive OEMs exploring auxiliary power modules. Electric vehicle applications remain nascent but carry outsized margin potential as energy storage systems developers test zinc air for grid-scale backup.
FDA medical device standards in the United States, EU Battery Regulation sustainability mandates, and Japan's METI circular economy guidelines collectively shape product chemistry disclosures and recycling infrastructure obligations. REACH compliance in Europe adds material traceability costs that favor producers with captive zinc refining or certified supply partnerships. Stakeholders must monitor how solid-electrolyte research at NantEnergy and Zinc8 Energy Solutions alters the rechargeable segment's technical feasibility threshold.
Market Dynamics
Medical device energy density mandates from German and Japanese regulators are compressing qualification timelines for zinc air cell suppliers, forcing electrode chemistry disclosures and captive zinc refining investments that reshape cost structures across the hearing aid supply chain.
Growth Catalysts
- REACH material traceability:European battery producers face mandatory supply chain documentation that rewards certified zinc partnerships and accelerates consolidation among compliant electrode manufacturers.
- Hearing aid miniaturization:German and Japanese medical device OEMs demand higher energy density cells for next-generation implantable audio processors, pulling primary zinc air procurement volumes upward.
- East Asian cluster economies:Cell assembly lines in South Korea and Taiwan serve dual consumer electronics and electric vehicle auxiliary markets, generating scale efficiencies that lower per-unit electrode costs.
Market Restraints
- Zinc price volatility:Spot market fluctuations for refined zinc metal create margin compression for producers without captive smelting capacity or long-term offtake agreements.
- Rechargeable lithium-ion substitution:Automotive OEMs testing auxiliary power modules increasingly favor solid-state lithium cells for their established recycling infrastructure and faster charge rates.
- EU Battery Regulation compliance costs:Extended producer responsibility mandates and carbon footprint disclosure requirements add administrative burden that disadvantages smaller electrode chemistry specialists.
Strategic Opportunities
- Indian hearing aid market penetration:CDSCO medical device registration pathways are streamlining, creating first-mover advantage for zinc air suppliers establishing audiologist distribution in tier-two cities.
- Grid-scale backup testing:Energy storage system developers in Germany and Japan are piloting zinc air modules for utility-scale backup, opening margin-rich contracts outside consumer electronics.
- Solid-electrolyte convergence:NantEnergy and Zinc8 Energy Solutions research programs are advancing rechargeable zinc air feasibility, potentially unlocking electric vehicle auxiliary power segments previously closed to primary cell architectures.
Industry Challenges
- Electrochemist talent scarcity:Zinc air electrode formulation expertise concentrates among aging specialists in German and Japanese industrial labs, constraining R&D expansion for new market entrants.
- ISO 13485 medical certification timelines:Hearing aid battery qualification cycles extend eighteen to twenty-four months, freezing product iteration speed and locking out agile competitors.
- Legacy mercury-free chemistry transitions:Producers must reformulate anode compositions to eliminate residual mercury content while maintaining shelf stability, requiring capital-intensive pilot line validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zinc Air Batteries Market |
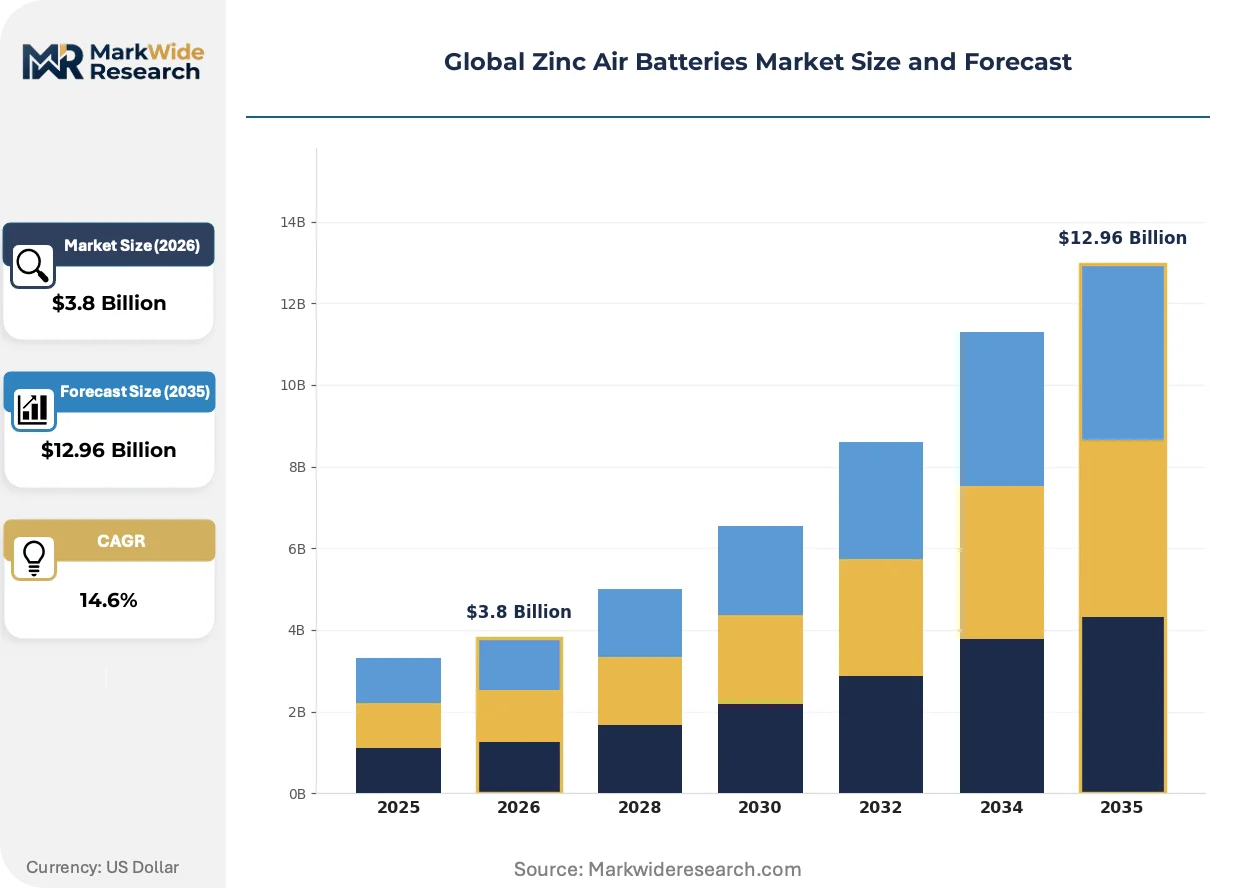
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Rechargeable Batteries, Stack Batteries, Specialty Batteries End User: Consumer Electronics, Automotive OEMs, Medical Devices, Renewable Energy Systems Application: Hearing Aids, Electric Vehicles, Portable Electronics, Energy Storage Systems Distribution Channel: Online Retail, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Duracell International Inc., Energizer Holdings Inc., Varta AG, GP Batteries International Ltd., Panasonic Corporation, Zinc8 Energy Solutions, Phinergy, ZAF Energy Systems, NantEnergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zinc Air Batteries Market Strategic Shifts
Electrode manufacturing automation and regulatory chemistry disclosure mandates are converging to reshape competitive barriers, while procurement behavior shifts toward certified supply partnerships that privilege vertically integrated producers.
Roll-to-roll electrode coating is automating precision zinc anode deposition for hearing aid cells. German medical device OEMs are adopting these lines to meet tightened energy density specifications from national regulators. The technology is automating throughput scaling that previously required manual assembly floor expansion, compressing capital recovery timelines for qualified suppliers.
EU Battery Regulation extended producer responsibility rules now mandate recycling infrastructure financing for all chemistries sold above volume thresholds. Battery producers face binding collection rate targets and carbon footprint documentation that favors in-house zinc refining over spot market purchasing. Hearing aid cell specialists with German manufacturing footprints are responding by integrating backward into electrode production to control material provenance.
Audiologist networks are consolidating procurement authority previously dispersed through retail pharmacy channels. German and French hearing aid dispensers now negotiate direct volume contracts with cell producers, displacing wholesale distributor intermediaries. This concentration is most visible in North American markets where Energizer Holdings has built dedicated clinical sales teams to capture account-level contracts.
Global Zinc Air Batteries Market Segmentation
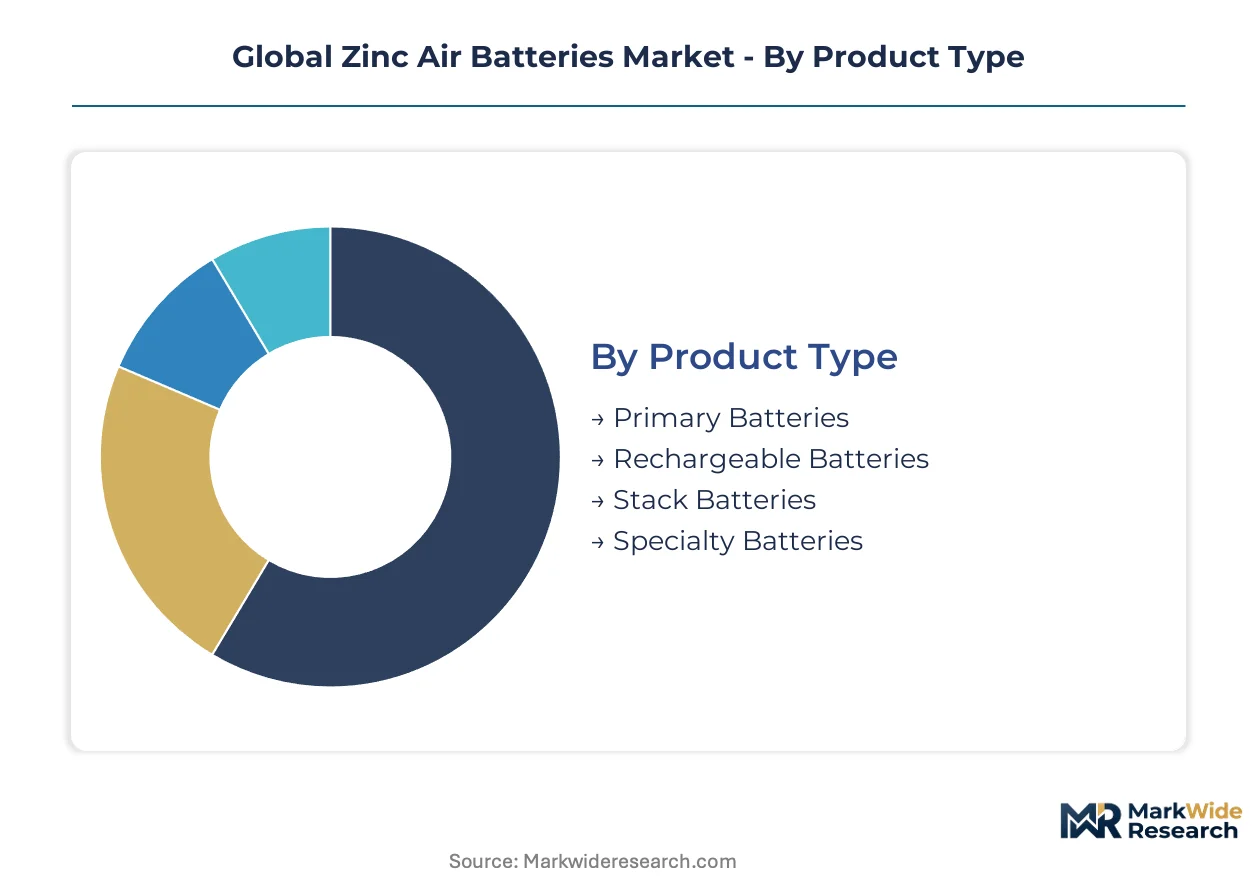
Zinc air battery producers configure product portfolios around electrochemical architecture, end-use certification requirements, and channel access economics. Segment boundaries harden where regulatory qualification timelines and captive electrode investments create switching costs for both suppliers and buyers.
Product Type:
Electrode chemistry and cell architecture concentrate manufacturing expertise among German and Japanese industrial labs, locking in supply-side specialization that shapes competitive entry barriers.
- Primary Batteries:Non-rechargeable cells utilizing zinc metal anodes and ambient oxygen cathodes deliver 1.4V with energy densities exceeding 400 Wh/kg. Hearing aid manufacturers in Germany and Japan anchor procurement volumes as medical device regulators tighten energy density mandates for implantable audio processors.
- Rechargeable Batteries:Solid-electrolyte architectures from NantEnergy and Zinc8 Energy Solutions are advancing cycle stability for automotive auxiliary power modules. Automotive OEMs in South Korea and Taiwan pilot these cells for electric vehicle backup systems where established lithium-ion recycling infrastructure creates substitution pressure.
- Stack Batteries:Multi-cell configurations for rail signaling and industrial remote monitoring require matched voltage discharge profiles.
- Specialty Batteries:Custom form factors serve military and aerospace applications with extended temperature range specifications.
Primary batteries absorb the bulk of installed capacity; rechargeable batteries are expanding most quickly.
End User:
Customer procurement authority varies sharply across certification regimes, with medical device OEMs demanding eighteen-to-twenty-four-month qualification cycles that freeze supplier switching.
- Medical Devices:Hearing aid and implantable audio processor manufacturers command premium pricing for cells meeting FDA and EU MDR energy density specifications. German and Japanese audiologist networks now negotiate direct volume contracts, displacing wholesale distributor intermediaries.
- Consumer Electronics:Remote sensor and portable device OEMs prioritize shelf stability and low self-discharge rates over rechargeability.
- Automotive OEMs:Auxiliary power module developers test zinc air against solid-state lithium for electric vehicle backup applications.
- Renewable Energy Systems:Grid-scale backup developers in Germany pilot zinc air modules for utility-scale storage contracts.
Medical devices command the highest margin tier; automotive OEMs are climbing the fastest as energy storage testing accelerates.
Application:
Functional requirements segment the market by discharge profile demands and replacement cycle economics, with miniaturization trends pulling cell geometry toward button and coin formats.
- Hearing Aids:Button-cell zinc air configurations dominate due to volumetric energy density requirements for behind-the-ear and in-canal devices. German and French retail pharmacies maintain premium shelf positioning for qualified suppliers.
- Energy Storage Systems:Utility-scale backup applications in Germany and Japan test zinc air against flow battery alternatives for multi-hour discharge duration.
- Electric Vehicles:Auxiliary power modules for emergency systems represent a nascent testing segment with outsized margin potential.
- Portable Electronics:Remote sensors and rail signaling equipment favor primary cell reliability over rechargeability.
Hearing aids anchor current revenue concentration; energy storage systems are gaining share fastest.
Distribution Channel:
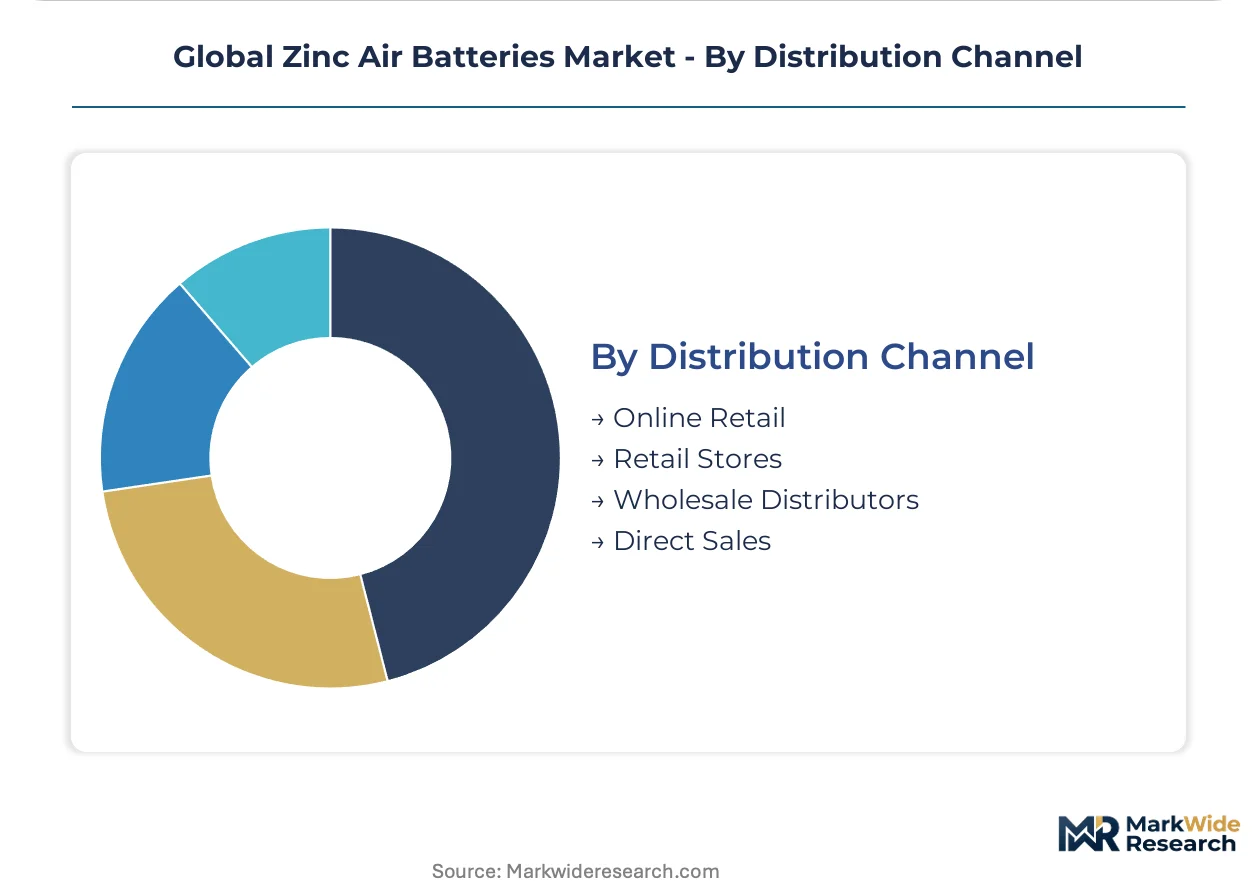
Channel economics fragment where audiologist network consolidation meets REACH compliance documentation requirements that favor direct manufacturer relationships.
- Retail Stores:German and French pharmacy chains stock premium zinc air cells for hearing aid users, with Duracell International sustaining dominant shelf positioning through brand equity investments.
- Direct Sales:Audiologist networks in North America and Europe negotiate account-level contracts that bypass wholesale markups.
- Online Retail:E-commerce penetration lags for medical device batteries where professional fitting creates purchase authority concentration.
- Wholesale Distributors:Traditional intermediaries face margin compression as procurement authority consolidates toward clinical endpoints.
Retail stores maintain the broadest geographic footprint; direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and Taiwan drive cell assembly concentration, while Germany's medical device corridor and Japan's METI-subsidized battery clusters anchor demand-side procurement authority.
United States
FDA medical device standards compress eighteen-to-twenty-four-month qualification timelines for hearing aid battery suppliers. The EPA oversees mercury-free chemistry transitions that force anode reformulation investments. Greater Boston hosts audiologist network consolidation that displaces wholesale distributor intermediaries.
Germany
EU Battery Regulation extended producer responsibility mandates reshape cost structures for zinc air electrode producers. REACH material traceability requirements favor certified zinc partnerships and backward integration. The Baden-Württemberg medical device corridor tightens energy density specifications for implantable audio processors.
Japan
METI circular economy guidelines shape recycling infrastructure obligations and product chemistry disclosures for battery producers. The Kansai industrial cluster sustains electrochemist expertise concentration among aging specialists. Osaka-based hearing aid OEMs expand procurement volumes for next-generation implantable power systems.
South Korea
MFDS medical device registration creates qualification pathways for zinc air cell suppliers targeting hearing aid markets. Government battery subsidies accelerate solid-electrolyte R&D programs for automotive auxiliary power modules. The Seoul Capital Area hosts cell assembly lines serving dual consumer electronics and electric vehicle markets.
China
NMPA medical device standards and MIIT dual carbon goals create overlapping compliance requirements for battery producers. GB standards govern zinc refining emissions and material traceability documentation. The Yangtze River Delta concentrates electrode manufacturing automation for hearing aid cell production.
Global Zinc Air Batteries Market Competitive Environment
German producers anchor one tier; East Asian specialists hold scale-driven manufacturing positions. The market structure consolidates around medical device certification holders and automotive R&D program participants. Three archetypes dominate: vertically integrated electrode manufacturers, audiologist network direct sellers, and solid-electrolyte technology developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure certified zinc supply partnerships.
Among Germany-based manufacturers, Varta AG exemplifies the vertically integrated archetype through captive electrode production. Duracell International occupies a position within the retail pharmacy shelf-positioning tier. Energizer Holdings sits within the clinical direct-sales vector, anchoring audiologist network penetration strategies in North American markets.
| Leading Market Players |
|---|
| Duracell International Inc. |
| Energizer Holdings Inc. |
| Varta AG |
| GP Batteries International Ltd. |
| Panasonic Corporation |
| Zinc8 Energy Solutions |
| Phinergy |
| ZAF Energy Systems |
| NantEnergy |
| Others |
Value Chain & Pricing Dynamics
Electrochemist expertise concentration in German and Japanese industrial labs feeds labor-cost differentials that widen pricing-tier spreads between premium hearing aid cells and commodity remote-sensor batteries. REACH material traceability investments and captive zinc refining requirements compress margins at the economy tier while sustaining premium positioning for qualified medical-device suppliers.
Pricing Analysis
Premium pricing attaches to eighteen-to-twenty-four-month lead times for ISO 13485-certified hearing aid cells, while spot inventory of consumer-grade batteries trades at compressed margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with FDA-tier medical cells commanding sustained premiums. Pricing pressure stems from rechargeable lithium-ion substitution in automotive auxiliary modules. Hearing aid OEMs show least price sensitivity due to regulatory lock-in, while remote-sensor buyers prioritize unit economics.
Supply Chain Analysis
Reverse-logistics flows for mercury-free chemistry transitions require specialized anode reformulation pilot lines that constrain refurbishment economics. Electrode manufacturing concentrates in Germany, South Korea, and Taiwan, with zinc metal sourcing drawing from certified partnerships rather than spot markets. Raw material dependencies include refined zinc metal, potassium hydroxide electrolyte, and oxygen-diffusion membrane substrates. Single-source vulnerability runs through German electrochemist expertise concentration. Distribution runs through consolidating audiologist networks displacing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zinc air battery market sits in a technology-transition phase where solid-electrolyte architectures from NantEnergy and Zinc8 Energy Solutions are displacing primary-cell dominance in automotive auxiliary power segments.
For Market Incumbents: Deepen backward integration into electrode production to control zinc provenance and satisfy REACH traceability mandates. Lock in long-term offtake agreements with certified smelters before spot price volatility compresses margins further. Prioritize capacity addition in Baden-Württemberg to anchor German medical-device corridor relationships against East Asian scale competitors.
For New Entrants and Emerging Players: CDSCO streamlined registration in India opens a window for audiologist network penetration in tier-two cities where qualified suppliers remain scarce. Target the hearing aid aftermarket with direct clinical sales teams that bypass wholesale markups. Pursue grid-scale backup pilot contracts in Germany where utility-scale testing creates first-mover positioning outside saturated consumer electronics channels.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated electrode manufacturers with captive zinc refining and ISO 13485 certification. Solid-electrolyte cycle stability breakthroughs signal inflection toward rechargeable segment viability. Long-term viability hinges on automotive OEM auxiliary power module adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Production | Captive zinc refining satisfies REACH mandates and insulates margin from spot volatility. |
| ISO 13485 Certification Investment | Eighteen-to-twenty-four-month qualification cycles lock out agile competitors from hearing aid supply chains. |
| Solid-Electrolyte R&D Partnership | Collaboration with NantEnergy or Zinc8 advances rechargeable feasibility for automotive auxiliary modules. |
| Audiologist Direct Sales Buildout | Channel consolidation in Greater Boston and German clinical networks displaces wholesale intermediaries. |
| Grid-Scale Backup Pilot Engagement | Utility-scale testing in Germany and Japan opens margin-rich contracts outside consumer electronics saturation. |
Study Parameters
Document review covered EU Battery Regulation implementation guidance, METI circular economy guidelines, FDA medical device standards, and SEC filings from listed battery producers, complemented by interviews with electrochemist specialists, hearing aid OEM procurement directors, audiologist network managers, zinc smelter supply planners, and energy storage system developers. Secondary sources included customs trade data for zinc metal flows, hospital procurement databases for hearing aid battery purchasing patterns, and patent filings for solid-electrolyte architectures. Bottom-up cell production estimates triangulated against top-down medical device market sizing.
Segment-level outputs across the analysis window reflect electrochemical architecture, end-use certification requirements, and distribution channel economics. The model projected primary and rechargeable battery trajectories separately, with CAGRs derived from hearing aid miniaturization pull, automotive auxiliary power testing acceleration, and grid-scale backup pilot expansion. Key inputs included electrode manufacturing automation adoption curves, REACH compliance cost pass-through rates, and lithium-ion substitution pressure indices.
The model assumes a particular technology adoption path; alternative pathways for solid-electrolyte rechargeable architectures would alter the outlook toward faster segment shifts. Forecasts reflect assumptions about regulatory timeline adherence and electrochemist workforce retention. Practitioners should monitor solid-electrolyte cycle stability breakthroughs and automotive OEM pilot contract awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Sodium Nickel Chloride Battery Market
Batteries
Silicon Battery Market
Batteries
Global Primary Cells Market
Batteries
Low Temperature Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Consumer Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Liquid Metal Battery Market
Batteries
Myanmar Battery Market
Batteries
Military Battery Packs Market
Batteries
Custom Battery Pack Market
Batteries
Forklift Battery Rental Market
Batteries
Elastic Battery Binders Market
Batteries
Europe Battery Cell Market