
 Global Solar Home Lighting Market | 2026-2036
Global Solar Home Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Home Lighting Market Outlook
Aftermarket service revenue is tilting from simple component replacement toward predictive maintenance contracts and remote system monitoring. Tata Power Solar Systems leverages its captive installation network across India to lock in recurring service income. Signify anchors its competitive position through proprietary wireless control protocols that reduce field-service dispatch rates. Shenzhen Yingli New Energy specializes in integrated lithium storage modules that extend product lifecycles and deepen customer retention.
Global solar home lighting comprises photovoltaic-powered illumination systems designed for domestic use, typically incorporating monocrystalline or polycrystalline panels with energy conversion efficiencies between 18% and 22%, paired with DC LED arrays and rechargeable battery banks for autonomous nighttime operation. LED product type configurations command the dominant share of new installations due to their lumen-per-watt superiority and declining semiconductor costs. Battery backup power source architectures are gaining fastest traction as grid instability and outright absence in rural clusters elevate reliability premiums over lowest-first-cost designs.
FDA product safety guidelines for lithium battery transport, India's BIS certification mandates for solar photovoltaic modules, and the EU Green Deal's embodied-carbon tracking requirements collectively shape component sourcing and cross-border market access. Kenya's Energy Regulatory Authority and Tanzania's Rural Energy Agency enforce quality standards that filter substandard imports from informal channels. Stakeholders must monitor how national storage-subsidy eligibility rules evolve as chemistry transitions accelerate and local content requirements tighten.
Market Dynamics
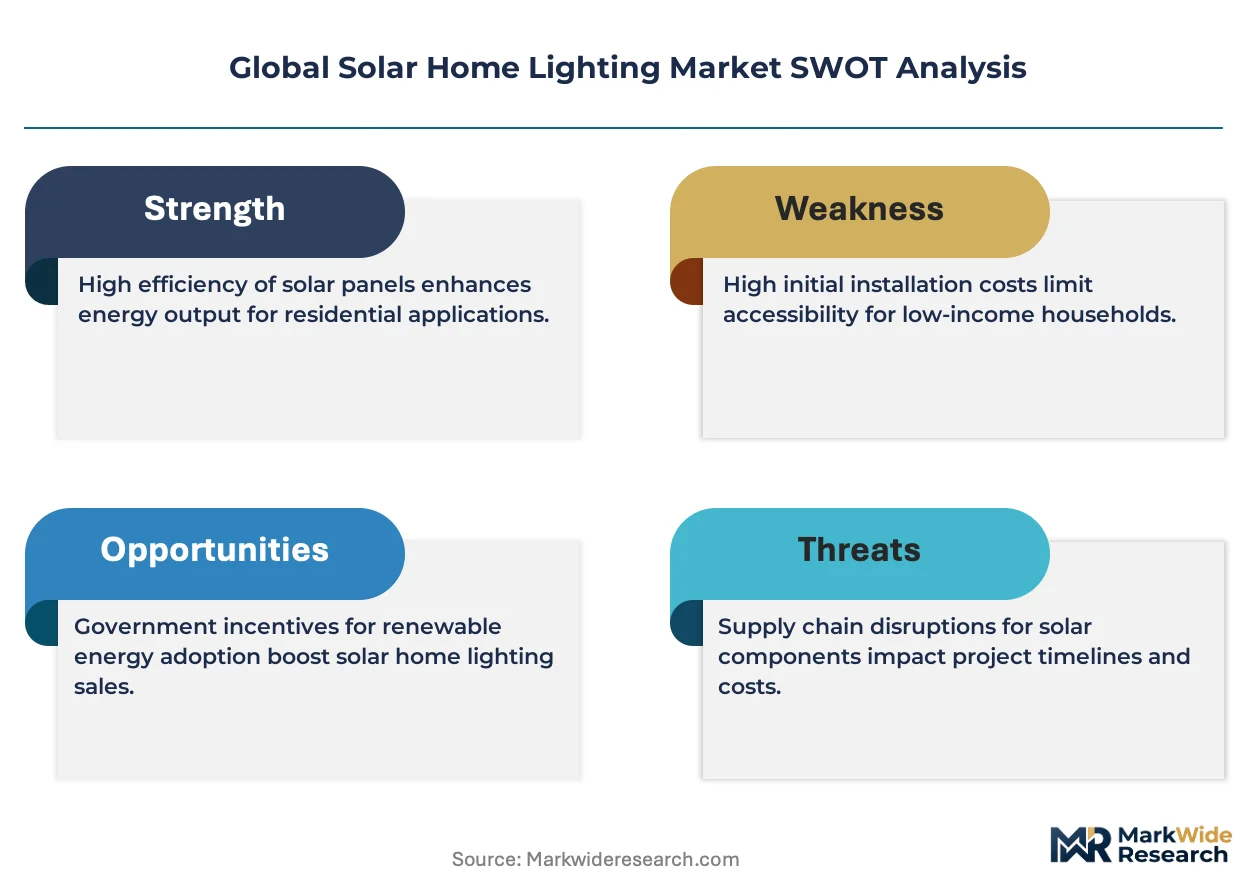
The solar home lighting sector is pivoting around battery chemistry substitution, with lithium iron phosphate systems eroding lead-acid's installed base and forcing supply chain recalibration across component tiers.
Growth Catalysts
- Sub-Saharan electrification mandates:Kenya's Rural Electrification Authority and Tanzania's Rural Energy Agency are channeling capital toward distributed solar kits, creating anchor demand for integrated lighting systems.
- BIS certification expansion:India's Bureau of Indian Standards mandates for photovoltaic modules are filtering substandard imports and consolidating procurement toward certified suppliers.
- Lithium storage cost curves:Cell-level price declines are compressing total system costs and expanding addressable household segments in off-grid clusters.
Market Restraints
- Raw material concentration:Lithium and cobalt processing capacity clusters in China, creating geographic supply vulnerability for non-integrated assemblers.
- Import tariff layering:India's DGFT duty structures on complete solar lanterns raise landed costs versus locally assembled alternatives.
- Lead-acid residual infrastructure:Existing recycling networks and technician familiarity slow conversion rates in replacement-heavy rural markets.
Strategic Opportunities
- Pay-as-you-go financing models:Mobile money-enabled installment structures are unlocking East African households excluded from upfront capital requirements.
- Productive use integration:Solar home systems bundled with DC appliances for small-scale agriculture and commerce extend revenue per installation.
- EU Green Deal embodied-carbon tracking:Compliance-ready supply chains gain preferential access to European development finance flows for emerging market projects.
Industry Challenges
- Field technician scarcity:Battery system diagnostics and lithium safety protocols require training programs that outpace current vocational pipeline output in rural deployment zones.
- Multi-standard certification burden:Navigating Kenya's Energy Regulatory Authority quality marks alongside Tanzania's Rural Energy Agency specifications fragments product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Home Lighting Market |
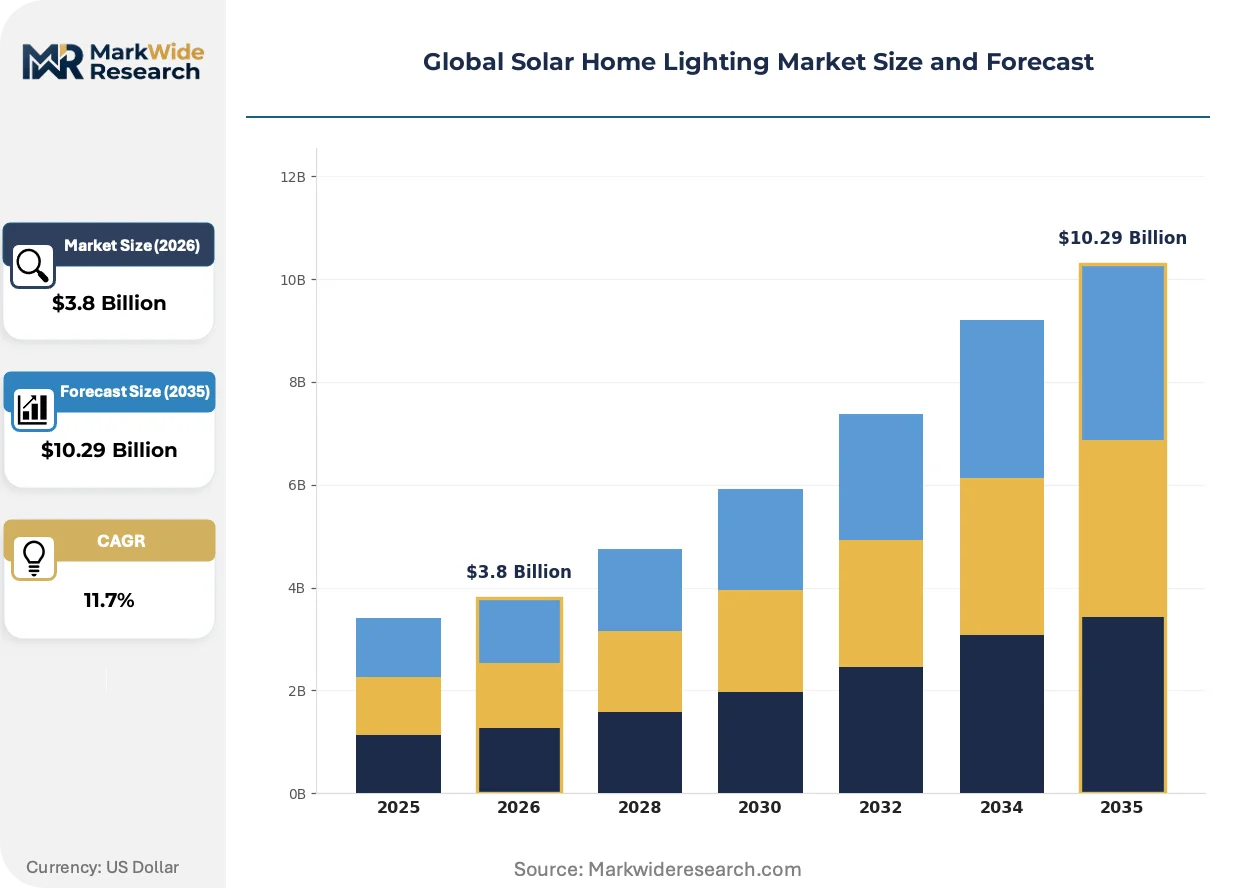
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, CFL, Halogen, Incandescent Power Source: Solar Panel, Battery Backup, Hybrid, Grid-Tied Installation Type: Fixed, Portable, Integrated, Adjustable Market Segment: Residential, Commercial, Institutional, Others |
| Companies Covered | Tata Power Solar Systems, Signify, Philips Lighting, Osram, Acuity Brands, Su-Kam, Shenzhen Yingli New Energy, Sharp, GE Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Home Lighting Market Strategic Shifts
Active transformation across this market centers on three vectors: electrochemical storage substitution, regulatory quality enforcement tightening, and financing mechanism digitization reshaping customer acquisition economics.
DC LED array efficiency is migrating from legacy 100-120 lumens per watt configurations toward 150+ lumen-per-watt chip-on-board designs. Rural electrification programs in Ethiopia and Nigeria are specifying these higher-efficiency tiers for new procurements. This migration from lower-grade imports is compressing supplier margins while extending runtime per watt-hour stored.
India's BIS certification mandates for solar photovoltaic modules entered enforcement phase, requiring third-party testing for crystalline and thin-film panels. Domestic manufacturers with captive testing facilities are absorbing compliance costs more efficiently than trading houses dependent on external laboratories. The mandate is accelerating consolidation among module suppliers serving the South Asian residential segment.
Household acquisition patterns are tilting from cash purchases toward mobile-enabled installment plans. Pay-as-you-go platforms in Kenya and Uganda are disintermediating traditional distributor credit relationships and capturing customer data for predictive service scheduling. This shift is most pronounced among agricultural income households with seasonal cash flow irregularities.
Global Solar Home Lighting Market Segmentation
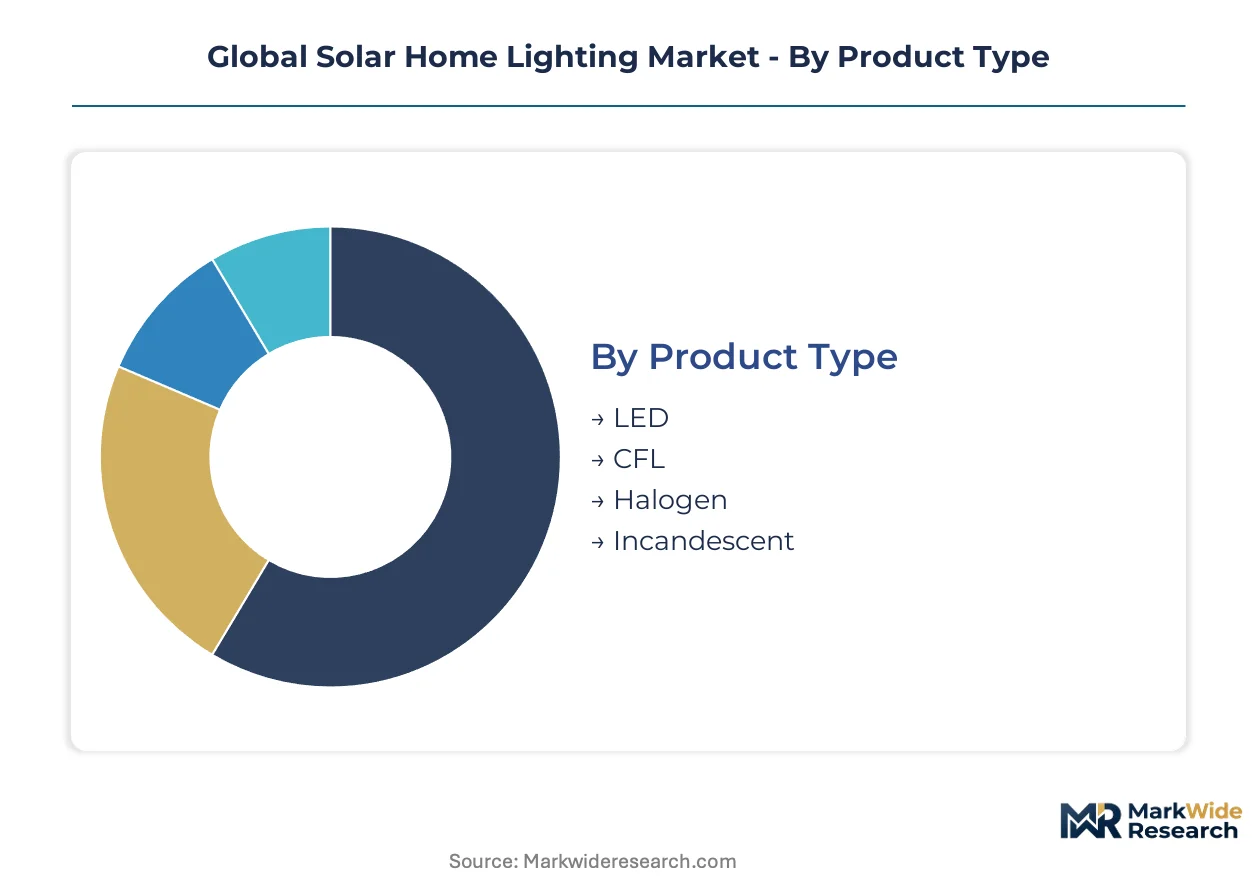
Solar home lighting procurement varies sharply by deployment context, with rural electrification programs favoring integrated fixed systems while urban backup applications drive portable and hybrid configurations. Segment-specific battery chemistry requirements and certification standards fragment supplier specialization across product tiers.
Product Type:
LED configurations turn over fastest as efficiency gains and lumen-per-watt improvements compress replacement cycles, while incandescent and halogen segments face accelerating obsolescence.
- LED:Monocrystalline and polycrystalline panel pairings with DC arrays achieving 150+ lumens per watt through chip-on-board designs. Rural electrification programs in Ethiopia and Nigeria specify these higher-efficiency tiers, compressing supplier margins while extending runtime per watt-hour stored.
- CFL:Legacy fluorescent tube configurations with higher power draw and shorter operational lifespans. Residual demand persists in price-sensitive replacement markets across South Asian rural clusters where existing inverter infrastructure limits LED retrofit compatibility.
- Halogen:Tungsten-filament designs with inferior energy conversion efficiency. Kenya's Rural Electrification Authority procurement specifications now exclude these from subsidized distributed solar kits.
- Incandescent:Obsolescent technology retained only in lowest-cost informal channel imports. Tanzania's Rural Energy Agency quality standards filter these from certified supplier lists.
LED anchors the volume base while CFL retains residual share in replacement-heavy rural markets, though halogen and incandescent segments are contracting most steeply as regulatory quality enforcement tightens.
Power Source:
Cost tier stratification separates premium lithium-integrated systems from lead-acid legacy architectures, with hybrid configurations commanding mid-tier positioning.
- Solar Panel:Direct photovoltaic-to-load systems without storage dependency. Daylight-only operation limits addressable use cases to agricultural and commercial daytime productivity applications in equatorial high-irradiance zones.
- Battery Backup:Rechargeable lithium iron phosphate or lead-acid banks enabling autonomous nighttime operation. Grid instability in sub-Saharan African urban peripheries and outright absence in rural clusters elevate reliability premiums for this architecture.
- Hybrid:Dual-mode systems switching between solar charging and grid supplementation. Indian residential segments with unreliable grid access favor these for cost-optimized backup during monsoon season cloud cover.
- Grid-Tied:Net-metering configurations feeding surplus generation into distribution networks. Kenya's Energy Regulatory Authority net-billing frameworks enable these for peri-urban households with existing grid connections.
Battery backup systems dominate revenue concentration while hybrid configurations expand most quickly as grid-intermittent zones proliferate across South Asia and East Africa.
Installation Type:
Application context determines fixture mobility requirements, with fixed installations correlating to productive-use bundled deployments and portable units serving seasonal agricultural labor mobility.
- Fixed:Permanent roof-mounted or wall-anchored configurations with weatherized housing. Sub-Saharan African PAYGO financing models standardize these for customer retention through hardware collateralization.
- Portable:Detachable lantern and task-lighting units with integrated small-format panels. Ugandan agricultural income households with seasonal cash flow irregularities favor these for field-to-housing mobility.
- Integrated:All-in-one designs combining panel, battery, and luminaire in single housing. India's BIS certification mandates accelerate consolidation toward certified integrated suppliers.
- Adjustable:Modular systems permitting panel angle and fixture repositioning. Ethiopian highland deployments with seasonal sun-angle variation specify these for optimization.
Fixed installations represent the maturity anchor while portable units climb fastest as mobile-enabled installment plans unlock excluded household segments.
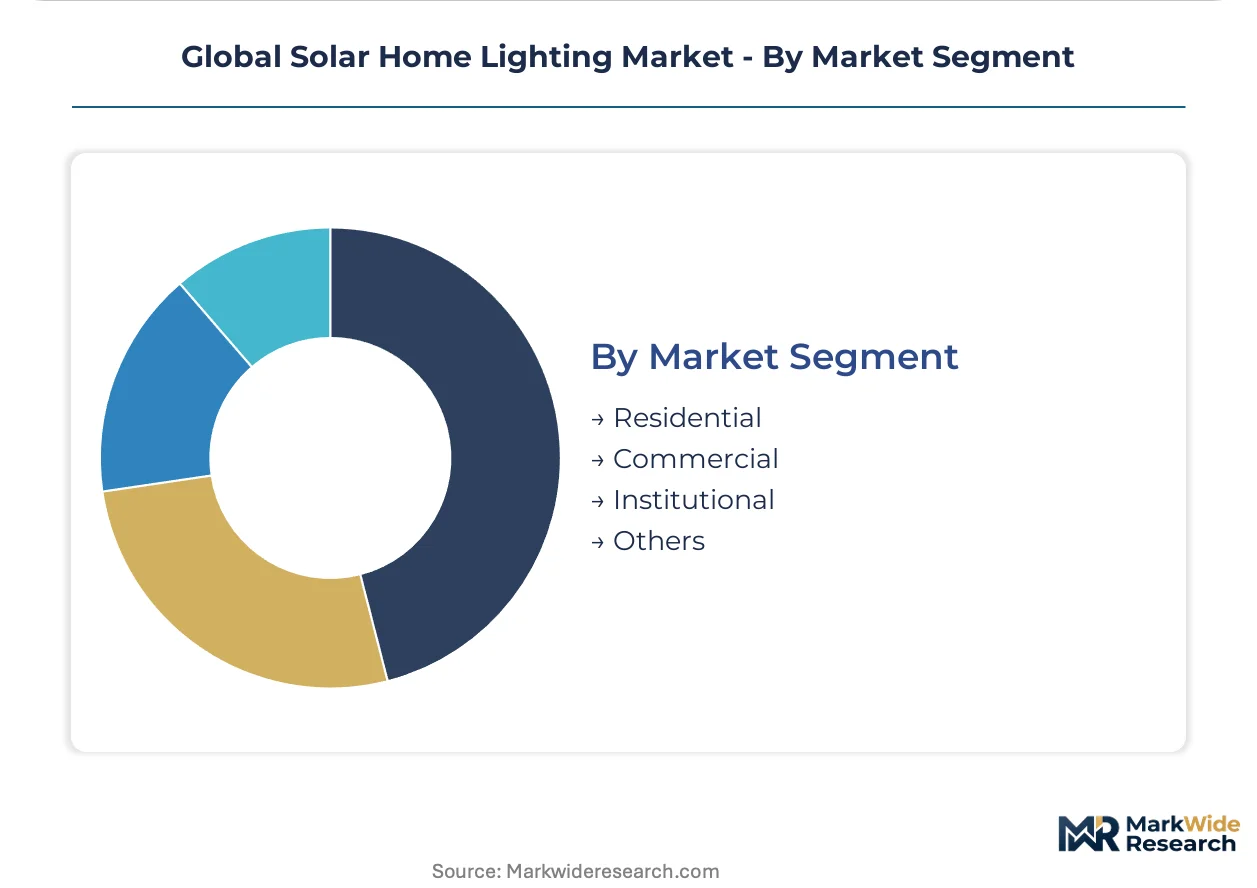
Market Segment:
Customer type stratification separates subsidized institutional procurement from commercially financed residential acquisition, with margin structure varying accordingly.
- Residential:Single-household domestic illumination systems with 10-100 watt panel configurations. Off-grid clusters in sub-Saharan Africa and South Asia drive uptake as electrification programs expand.
- Commercial:Small-enterprise productive-use bundles incorporating DC appliances for agriculture and commerce. Kenyan PAYGO platforms capture customer data from these deployments for predictive service scheduling.
- Institutional:Schools, health clinics, and community facilities with higher reliability requirements and centralized maintenance contracts. Tanzania's Rural Energy Agency channels capital toward these anchor installations.
- Others:Emergency relief, humanitarian, and temporary shelter applications with rapid-deployment specifications. EU Green Deal embodied-carbon tracking shapes component sourcing for these development finance-funded projects.
Residential segments anchor volume while commercial applications gain share at the steepest rate as productive-use bundling extends revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Sub-Saharan Africa treats solar home lighting as primary electrification infrastructure, while South Asian households deploy it as grid-backup resilience. Industrialized markets in East Asia and Europe emphasize premium integrated systems with smart controls.
India
Rural electrification gaps in Bihar and Uttar Pradesh drive fixed-installation demand through subsidized distributed solar kits. India's BIS certification mandates for photovoltaic modules filter substandard imports and consolidate procurement toward certified domestic suppliers. Gujarat's manufacturing corridor hosts crystalline panel fabrication clusters supplying residential segments.
Kenya
Mobile money-enabled pay-as-you-go financing unlocks agricultural income households excluded from upfront capital requirements. Kenya's Rural Electrification Authority channels capital toward distributed solar kits, creating anchor demand for integrated lighting systems. Nairobi's technology hub concentrates PAYGO platform development and predictive service scheduling capabilities.
China
Integrated lithium storage module production serves export markets as domestic rural electrification nears completion. The country's national quality regulator enforces GB standards for battery transport safety and photovoltaic module performance. Shenzhen's electronics manufacturing ecosystem specializes in chip-on-board LED arrays and lithium iron phosphate battery pack integration.
Tanzania
Seasonal cash flow irregularities among agricultural households favor portable lantern configurations with field-to-housing mobility. Tanzania's Rural Energy Agency enforces quality standards that filter substandard imports from informal channels. Dar es Salaam's port infrastructure handles bulk component imports for regional assembly operations.
Germany
EU Green Deal embodied-carbon tracking requirements shape component sourcing for development finance-funded emerging market projects. REACH and RoHS regulations restrict hazardous substance use in battery and semiconductor components. Bavaria's industrial automation sector supplies quality testing equipment for certification laboratories.
Global Solar Home Lighting Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base spans integrated energy conglomerates with captive installation networks, lighting specialists with proprietary control protocols, and Chinese fabricators with upstream battery integration. Three archetypes dominate: utility-affiliated solar developers, legacy lighting technology licensors, and lithium storage module specialists. Competitive moves center on backward integration into cell manufacturing and geographic expansion through mobile-enabled financing platforms.
Within the integrated energy tier, Tata Power Solar Systems anchors competitive positioning through captive installation density. Among lighting technology specialists, Signify occupies a position exemplifying proprietary wireless protocol development. Shenzhen Yingli New Energy represents the lithium storage specialization archetype, with module integration extending product lifecycles.
| Leading Market Players |
|---|
| Tata Power Solar Systems |
| Signify |
| Philips Lighting |
| Osram |
| Acuity Brands |
| Su-Kam |
| Shenzhen Yingli New Energy |
| Sharp |
| GE Renewable Energy |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Mombasa freight corridors shape cost dynamics across the solar home lighting value chain, concentrating pricing power with lithium cell manufacturers while downstream assemblers face margin compression from India's DGFT duty structures on complete lanterns versus locally assembled alternatives.
Pricing Analysis
Long-term offtake contracts between crystalline panel fabricators and rural electrification agencies anchor volume pricing, while spot procurement for lithium iron phosphate cells introduces volatility. Price differentiation rests on BIS certification tier and captive installation network density. Cost compression in entry-level integrated systems is intensifying as Chinese module exports absorb freight premiums. Agricultural income households in East Africa exhibit highest price sensitivity, while institutional procurement in Tanzania tolerates premium tiers for centralized maintenance contracts.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for non-integrated assemblers. Lithium processing and cell fabrication concentrate in China, with crystalline panel production splitting between Chinese provinces and Gujarat's manufacturing corridor. Raw material dependencies include lithium carbonate, polysilicon ingots, and chip-on-board LED arrays. Single-source vulnerability in lithium iron phosphate cathode supply feeds from Sichuan processing clusters. Distribution runs through Nairobi technology hubs for PAYGO platform fulfillment and Dar es Salaam port infrastructure for regional assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification standards and financing platform architectures creates niche entry points, as pay-as-you-go digitization splits customer acquisition economics from traditional distributor relationships.
For Market Incumbents: Build captive technician training moats to lock in predictive maintenance revenue. Tata Power Solar Systems demonstrates this through installation density across Indian states. Consolidate procurement toward certified domestic panel suppliers as BIS mandates tighten. Counter emerging lithium storage specialists by backward integration into cell pack assembly.
For New Entrants and Emerging Players: Pursue portable lantern configurations for Ugandan agricultural households with seasonal cash flow irregularities. Target unbundled DC appliance integration for Kenyan small-enterprise productive-use bundles. Leverage mobile money-enabled installment structures to bypass traditional credit relationships.
For Investors and Strategic Acquirers: Lithium storage module specialists with integrated battery management systems represent the most defensible acquisition archetype. Long-term viability hinges on chemistry transition completion and local content requirement compliance. Watch Kenya's Energy Regulatory Authority storage-subsidy eligibility rule evolution as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Cell Assembly | Captures margin compression from Chinese cathode processing concentration. |
| PAYGO Platform Geographic Expansion | Mobile money infrastructure in Ethiopia and Nigeria unlocks excluded household segments. |
| BIS Certification Pre-Positioning | Domestic testing facility investment filters substandard import competition. |
| Productive-Use DC Appliance Bundling | Kenyan agricultural commercial applications extend revenue per installation. |
| EU Green Deal Compliance Certification | Embodied-carbon tracking readiness secures European development finance access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including rural electrification agency procurement officers, PAYGO platform operations leads, lithium battery pack engineers, and crystalline panel fabrication plant managers. Secondary validation drew from India's BIS certification databases, Kenya's Energy Regulatory Authority quality mark registries, Tanzania's Rural Energy Agency procurement disclosures, and UN development finance project tracking systems. Bottom-up household demand modeling and top-down electrification program budget triangulation anchored volume estimates.
Calibration against historical deployment trajectories in sub-Saharan Africa and South Asia informed growth rate derivation across the projection horizon. Segmentation dimensions modeled include product type tier, power source architecture, installation mobility class, and customer segment stratification. Lithium storage cost curves and LED efficiency migration timelines served as technology-specific forecast inputs alongside mobile money penetration rates for financing mechanism adoption.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese lithium specialists or sudden BIS certification scope expansion would shift outcomes. Regulatory enforcement intensity and raw material processing capacity commissioning remain primary revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Chimney Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Hungary Renewable Energy Market