
 Taiwan Battery Market | 2026-2036
Taiwan Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Battery Market Analytics
Taiwan's southern industrial corridor is reshaping regional cell production capacity as Gigafactory-scale investments expand in Kaohsiung. E-One Moli Energy (Molicel) anchors high-discharge cylindrical cell supply for power tool and aviation markets. CSB Battery Technologies Inc specializes in sealed lead-acid designs for telecom backup and medical equipment. SYNergy ScienTech Corp leverages solid-state electrolyte research to differentiate in next-generation energy density targets.
A battery converts chemical energy into electrical energy through electrochemical reactions, with lithium-ion cells employing cobalt-nickel-manganese oxide cathodes and graphite anodes separated by microporous polyethylene films to achieve energy densities exceeding 250 Wh/kg for portable and stationary applications. Lithium-ion products lead the product type landscape due to their dominance in consumer electronics and emerging electric vehicle integration, while lead-acid retains margin pools in industrial uninterruptible power systems where replacement cycles are predictable. Solid-state technology within the technology dimension attracts the fastest development attention as manufacturers target thermal runaway elimination and extended cycle life beyond 1,000 charge events.
Taiwan's Bureau of Standards, Metrology and Inspection enforces CNS battery safety certifications that gate domestic sales and export eligibility for lithium-based systems. The Ministry of Economic Affairs Industrial Development Bureau administers power grid modernization subsidies that directly expand utility-scale storage procurement from local suppliers. Stakeholders must monitor how amendments to the Renewable Energy Development Act reshape storage-to-generation ratio mandates and redirect manufacturing priorities toward grid-balancing products.
Market Dynamics
Taiwan's battery sector faces structural pressure from the Bureau of Energy's tightening energy storage safety codes, which mandate enhanced cell certification and thermal runaway testing protocols for all grid-connected installations.
Growth Catalysts
- Grid Modernization Subsidies:The Ministry of Economic Affairs Industrial Development Bureau directs capital toward utility-scale storage procurement, expanding order pipelines for domestic manufacturers.
- Semiconductor Fab Demand:Hsinchu Science Park facilities require uninterruptible power systems with sub-millisecond switching, creating premium demand for lithium-ion backup solutions.
- Electric Vehicle Scale-Up:Taoyuan and Tainan assembly plants are placing multi-year purchase agreements for high-nickel cylindrical packs, anchoring cell production capacity.
Market Restraints
- Cathode Material Concentration:Cobalt and nickel supply chains concentrate in African mining jurisdictions and Chinese refining operations, exposing Taiwanese cell makers to price volatility and geopolitical disruption.
- Certification Friction:CNS battery safety certifications enforced by the Bureau of Standards, Metrology and Inspection impose 12-18 month approval timelines that delay product launches.
- Lead-Acid Substitution Ceiling:Industrial UPS replacement cycles favor sealed lead-acid designs for their predictable cost structure, limiting lithium-ion penetration in telecom and medical backup segments.
Strategic Opportunities
- Solid-State Convergence:SYNergy ScienTech Corp's electrolyte research positions Taiwanese suppliers to capture aviation and power tool markets demanding energy density above 300 Wh/kg.
- Renewable Storage Mandates:Amendments to the Renewable Energy Development Act will impose storage-to-generation ratio requirements, redirecting manufacturing toward grid-balancing products.
- Kaohsiung Port Logistics:Gigafactory-scale investments in Taiwan's southern industrial corridor enable direct export positioning to Southeast Asian markets with underdeveloped cell production.
Industry Challenges
- Electrochemical Engineering Talent:Solid-state and silicon-anode development requires specialized expertise that domestic universities are not yet producing at sufficient scale.
- Legacy System Integration:Semiconductor fabs and medical facilities operate 15-20 year equipment refresh cycles, forcing battery suppliers to engineer backward-compatible form factors and communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Battery Market |
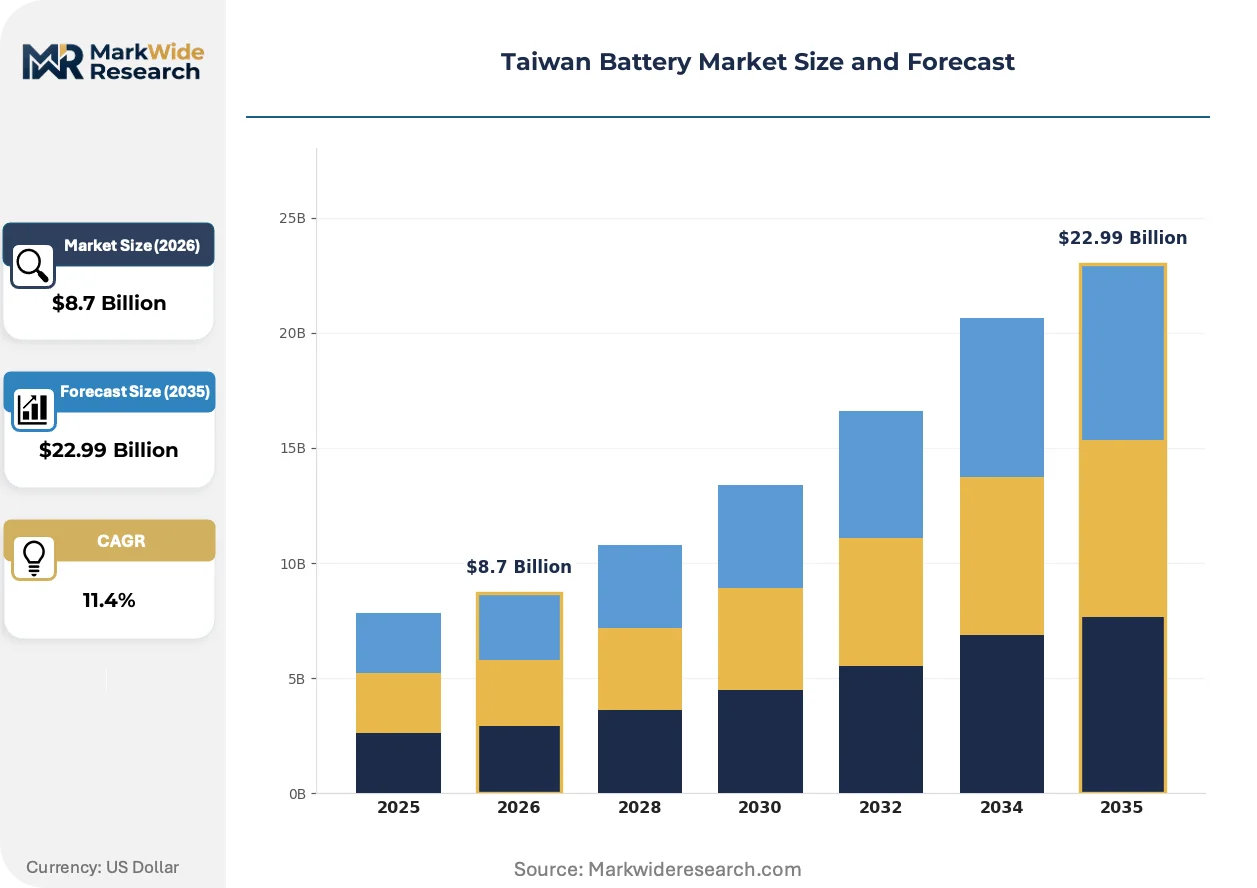
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Nickel-Metal Hydride Application: Consumer Electronics, Automotive, Industrial, Renewable Energy Technology: Solid-State, Flow Battery, Fuel Cell, Graphene-Based End User: Residential, Commercial, Utilities, Manufacturing |
| Companies Covered | Amita Technologies Inc, CSB Battery Technologies Inc, E-One Moli Energy (Molicel), Panasonic Corporation, SYNergy ScienTech Corp, Dynapack International, Simplo Technology, Duracell Inc, Kung Long Batteries Industrial Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Battery Market Evolving Landscape
Electrochemical architectures are undergoing rapid transformation as Taiwanese manufacturers pursue thermal runaway elimination and energy density thresholds that enable aviation electrification.
Solid-state electrolyte technology is collapsing the historical trade-off between energy density and cycle stability in lithium-based cells. Aviation battery pack assemblers in Taoyuan are adopting sulfide-based ceramic separators for their 400 Wh/kg prototype systems. This chemistry is collapsing development timelines for electric vertical take-off aircraft certification.
The Bureau of Energy's 2024 amendments to energy storage safety codes now require multi-layer thermal propagation testing for all grid-connected lithium-ion installations. Cell manufacturers must submit third-party validation of venting mechanisms and module-level fire suppression. Industrial UPS suppliers in Tainan are responding by redesigning rack architectures to accommodate these testing protocols.
Semiconductor fabs in Hsinchu are consolidating battery procurement through centralized technical specifications rather than site-by-site vendor selection. This buyer concentration is compressing supplier margins while rewarding cell makers with demonstrated CNS certification track records and localized service networks. The shift is most visible in 48V backup system contracts, where three-facility master agreements now dominate purchasing patterns.
Taiwan Battery Market Segmentation
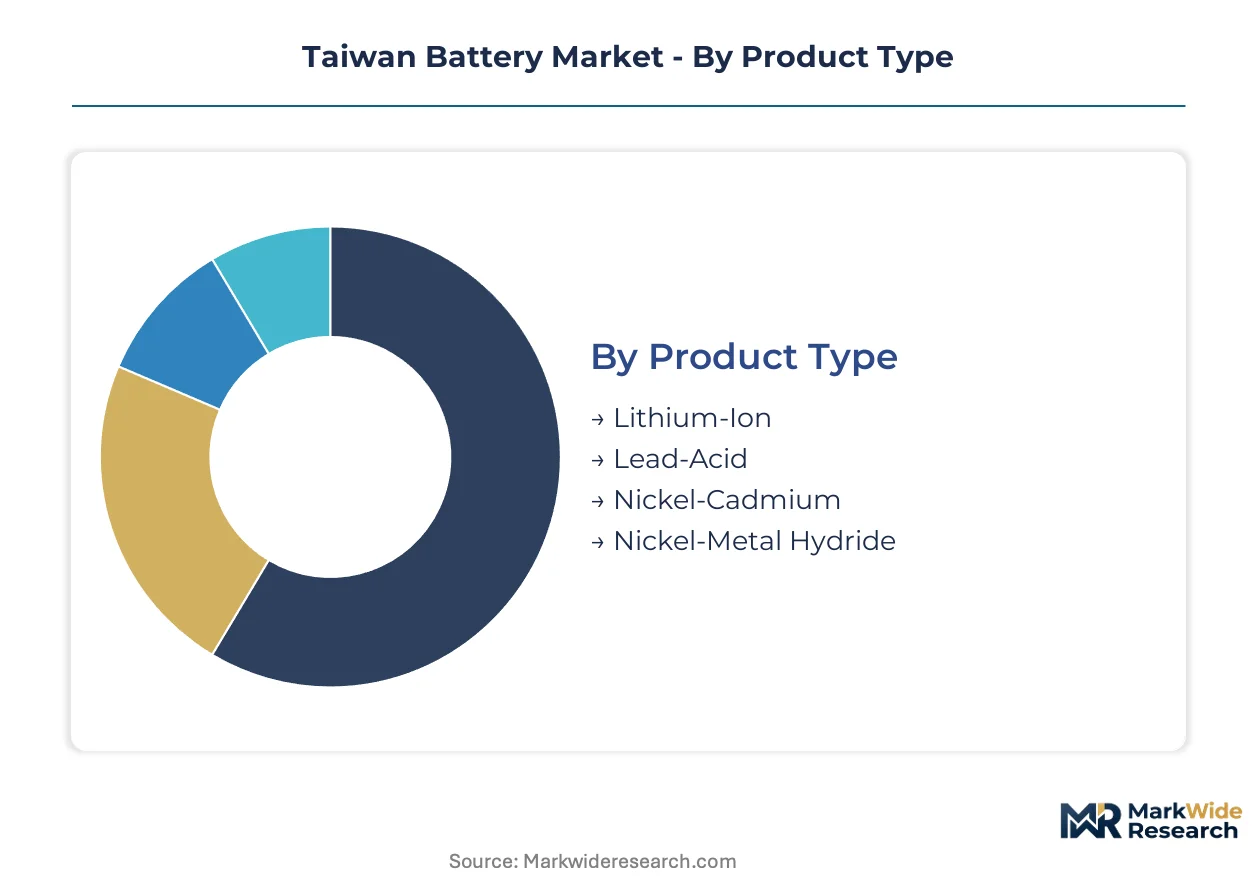
Taiwan's battery market segments reflect divergent technical requirements across semiconductor fabs, electric vehicle assembly plants, and grid-scale installations. Understanding these divisions clarifies where cell manufacturers must allocate R&D and certification resources.
Product Type:
Use-case spectrum spans portable consumer devices through multi-megawatt grid storage, demanding distinct electrochemical architectures and safety protocols.
- Lithium-Ion:Cobalt-nickel-manganese oxide cathodes paired with graphite anodes achieve energy densities exceeding 250 Wh/kg through microporous polyethylene separators. Hsinchu Science Park fabs demand sub-millisecond switching for uninterruptible power systems, while Taoyuan and Tainan EV plants anchor multi-year offtake agreements for high-nickel cylindrical packs.
- Lead-Acid:Sealed designs with predictable replacement cycles dominate telecom backup and medical equipment where cost stability outweighs energy density. CSB Battery Technologies Inc concentrates production in this segment for industrial UPS applications across Taiwan's southern corridor.
- Nickel-Cadmium:Aviation and rail signaling applications in Kaohsiung industrial zones retain demand for this chemistry's tolerance to extreme temperature cycling.
- Nickel-Metal Hydride:Hybrid vehicle auxiliary systems and power tool markets in Taoyuan maintain procurement of this intermediate-density technology.
Established volume favors Lead-Acid; emerging adoption favors Lithium-Ion.
Application:
Customer archetypes range from centralized semiconductor procurement offices to distributed residential solar installers, each imposing unique certification and service requirements.
- Consumer Electronics:Smartphones, laptops, and wearables demand cylindrical and pouch cells with 500+ cycle life. Taipei-based OEMs consolidate supplier qualification through centralized technical specifications rather than site-by-site selection.
- Automotive:Taoyuan and Tainan assembly plants require high-discharge cylindrical packs for electric vehicle integration, with thermal runaway testing mandated by Bureau of Energy safety codes.
- Industrial:Manufacturing facilities and telecom infrastructure favor sealed lead-acid for 15-20 year equipment refresh cycles, forcing backward-compatible form factors from suppliers.
- Renewable Energy:Utility-scale storage procurement expands through Ministry of Economic Affairs grid modernization subsidies, with amendments to the Renewable Energy Development Act imposing storage-to-generation ratio mandates.
Industrial procurement maintains the largest installed base; Renewable Energy contracts are climbing the fastest.
Technology:
Development maturity splits between commercialized electrochemical systems and laboratory-stage architectures targeting aviation electrification thresholds.
- Solid-State:Sulfide-based ceramic separators eliminate thermal runaway risk while pushing energy density toward 400 Wh/kg. SYNergy ScienTech Corp's electrolyte research positions Taiwanese suppliers for aviation battery pack assembly in Taoyuan.
- Flow Battery:Vanadium redox systems suit multi-hour grid balancing applications in utility procurement, though footprint requirements limit deployment in dense industrial zones.
- Fuel Cell:Hydrogen conversion systems for backup power face infrastructure constraints in Taiwan's current refueling network.
- Graphene-Based:Experimental anode materials promise enhanced conductivity but await CNS certification validation from the Bureau of Standards, Metrology and Inspection.
Commercial traction concentrates in Solid-State; pilot-scale deployment favors Flow Battery.
End User:
Procurement scale ranges from individual residential solar installations through centralized utility tenders exceeding 100 MWh.
- Residential:Home energy storage systems pair with rooftop solar, requiring compact form factors and plug-and-play installation protocols.
- Commercial:Office buildings and retail chains in Taipei and Kaohsiung prioritize peak shaving and demand charge reduction through 48V backup systems.
- Utilities:Taipower procurement drives utility-scale storage deployment, with grid-balancing products redirecting manufacturing priorities under evolving renewable mandates.
- Manufacturing:Semiconductor fabs in Hsinchu operate three-facility master agreements for battery procurement, compressing supplier margins while rewarding CNS certification track records.
Manufacturing commands premium pricing; Utilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity concentrates in East Asian industrial corridors where cathode material refining and pack assembly co-locate. Bureau of Energy safety codes and Ministry of Economic Affairs procurement subsidies reshape domestic demand patterns across Taiwan's metropolitan manufacturing zones.
Hsinchu Science Park Corridor
Semiconductor fabs demand sub-millisecond uninterruptible power systems for cleanroom operations. The Bureau of Standards, Metrology and Inspection enforces CNS battery safety certifications that gate supplier qualification. Three-facility master agreements now dominate 48V backup procurement, compressing margins for uncertified vendors.
Taoyuan Metropolitan Assembly Zone
Electric vehicle plants anchor multi-year offtake agreements for high-nickel cylindrical packs. The Ministry of Economic Affairs Industrial Development Bureau directs grid modernization subsidies toward utility-scale storage. Aviation battery pack assemblers are adopting sulfide-based ceramic separators for electric vertical take-off aircraft prototypes.
Tainan Southern Industrial Cluster
Industrial UPS replacement cycles favor sealed lead-acid designs where cost stability outweighs energy density. The Bureau of Energy's 2024 amendments mandate multi-layer thermal propagation testing for grid-connected lithium-ion installations. Telecom backup facilities operate 15-20 year equipment refresh cycles requiring backward-compatible form factors.
Kaohsiung Port Logistics Hub
Gigafactory-scale investments enable direct export positioning to Southeast Asian markets with underdeveloped cell production. The Renewable Energy Development Act amendments impose storage-to-generation ratio mandates redirecting manufacturing priorities. Vanadium redox flow battery systems suit multi-hour grid balancing applications in utility procurement.
Taiwan Battery Market Competitive Landscape
Cylindrical cell specialists and sealed lead-acid incumbents split the market along electrochemical architecture lines. The vendor base clusters around three strategic archetypes: high-discharge cylindrical manufacturers serving power tool and aviation markets, industrial UPS suppliers with predictable replacement cycle offerings, and solid-state electrolyte researchers targeting next-generation energy density thresholds. Dominant competitive moves include capacity expansion in Kaohsiung's southern corridor and technology licensing partnerships for sulfide-based ceramic separator production.
Among Taiwan-based manufacturers, E-One Moli Energy (Molicel) and CSB Battery Technologies Inc exemplify the cylindrical-versus-lead-acid split, while SYNergy ScienTech Corp occupies a position within the solid-state research tier. These entities represent contrasting strategic bets on thermal runaway elimination versus cost-stable industrial backup solutions.
| Leading Market Players |
|---|
| Amita Technologies Inc |
| CSB Battery Technologies Inc |
| E-One Moli Energy (Molicel) |
| Panasonic Corporation |
| SYNergy ScienTech Corp |
| Dynapack International |
| Simplo Technology |
| Duracell Inc |
| Kung Long Batteries Industrial Co Ltd |
| Others |
Value Network & Pricing Analysis
Kaohsiung's underutilized Gigafactory-scale capacity is pressuring cell manufacturers to absorb cathode material volatility rather than pass through costs, compressing margins while forcing selective customer prioritization. The Bureau of Energy's multi-layer thermal propagation testing mandates add certification overhead that suppliers with established CNS track records can leverage into pricing power against uncertified competitors.
Pricing Analysis
CNS battery safety certifications enforced by the Bureau of Standards, Metrology and Inspection dictate the pricing tier structure across Taiwan's battery market. Pricing stratifies across CNS-certified premium tiers, standard industrial grades, and economy lead-acid replacements. Price differentiation hinges on certification grade and volume scale, with three-facility master agreements in Hsinchu commanding steeper discounts than site-by-site procurement. Cost compression in the standard lithium-ion tier is intensifying because semiconductor fabs are consolidating procurement through centralized technical specifications. Industrial UPS buyers in Tainan exhibit the highest price sensitivity due to predictable replacement cycle economics, while aviation battery pack assemblers in Taoyuan show the least sensitivity given energy density thresholds above 300 Wh/kg.
Supply Chain Analysis
Cobalt and nickel feedstock draws from African mining jurisdictions and Chinese refining operations, exposing Taiwanese cell makers to price volatility and geopolitical disruption. Cathode precursor production rests on concentrate shipments from the Democratic Republic of Congo, Indonesia, and Australia. Graphite anode supply is anchored in Chinese processing capacity, creating single-source vulnerability for synthetic material grades. Distribution runs through Kaohsiung Port logistics infrastructure for Southeast Asian export positioning, with domestic last-mile delivery concentrated in the Hsinchu-Taoyuan-Tainan industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's battery market fragments along electrochemical architecture lines, with solid-state research, cylindrical high-discharge production, and sealed lead-acid incumbents occupying distinct competitive spaces. The Renewable Energy Development Act's storage-to-generation ratio mandates are creating specialized grid-balancing niches that reward targeted capability investments.
For Market Incumbents: Build certification moats through accelerated CNS validation pipelines for sulfide-based ceramic separators. Incumbent cylindrical cell specialists should expand capacity in Kaohsiung's southern corridor to capture Southeast Asian export demand. The Bureau of Energy's tightening thermal runaway testing protocols threaten uncertified competitors, creating acquisition opportunities for firms with demonstrated compliance track records. Backward integration into cathode precursor refining mitigates African supply concentration risk.
For New Entrants and Emerging Players: Aviation battery pack assembly in Taoyuan represents the most penetrable white-space target, with electric vertical take-off aircraft prototypes demanding 400 Wh/kg energy density that established suppliers have not yet commercialized. Solid-state electrolyte research partnerships with SYNergy ScienTech Corp provide a credible technology licensing entry point. New entrants should pursue Ministry of Economic Affairs grid modernization subsidy qualification as a go-to-market anchor for utility-scale storage contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial UPS suppliers with 15-20 year equipment refresh cycles and predictable replacement demand. Long-term viability across the next decade favors firms with dual capability in both certified lithium-ion production and legacy lead-acid service networks. Acquisition targets should demonstrate CNS certification track records plus localized service infrastructure in the Hsinchu Science Park corridor. The signal to watch is amendments to storage-to-generation ratio mandates accelerating utility procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CNS Certification Acceleration | Bureau of Standards validation compresses 12-18 month timelines for grid-connected lithium-ion installations. |
| Kaohsiung Capacity Buildout | Gigafactory-scale investments enable direct export positioning to Southeast Asian markets with underdeveloped cell production. |
| Solid-State Technology Licensing | SYNergy ScienTech Corp's sulfide-based ceramic separator research targets aviation electrification thresholds above 300 Wh/kg. |
| Utility-Scale Storage Partnership | Ministry of Economic Affairs subsidies expand order pipelines for domestic manufacturers under renewable energy mandates. |
| Backward Integration into Cathode Refining | Upstream control over cobalt-nickel processing mitigates African supply chain concentration and price volatility exposure. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing executives, utility procurement officers, semiconductor fab facilities managers, and aviation battery pack engineers and refined through secondary validation. Primary fieldwork combined structured interviews with Bureau of Energy regulatory affairs leads and Ministry of Economic Affairs industrial development officers. Secondary sources included CNS certification databases, customs trade records for cathode material imports, and Taipower utility procurement disclosures. Bottom-up cell production capacity estimates were triangulated against top-down renewable energy storage demand projections.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for solid-state, lithium-ion, and lead-acid chemistries. The forecast framework incorporated product type, application, technology maturity, and end-user procurement scale as core segmentation dimensions. CAGRs were derived from installation base growth rates and replacement cycle timing. Industry-specific inputs included Bureau of Energy safety code amendment timelines and Ministry of Economic Affairs subsidy allocation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese cell manufacturers or accelerated solid-state commercialization by Korean competitors would shift outcomes. Cross-checking against IEA battery supply chain tracking and BNEF energy storage market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Hybrid Flow Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Japan Rechargeable Battery Market
Batteries
South America Consumer Battery Market
Batteries
Secondary Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
East Asia Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Printed Batteries Market
Batteries
Seawater Battery Market
Batteries
PVT Battery Panel Market
Batteries
Global Solar Battery Charger Market
Batteries
Deep Cycle Battery Market