
 Mobile Battery Market | 2026-2036
Mobile Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Battery Market Outlook
High-energy-density tier cell specifications is rotating through the supply base as OEMs prioritize longer cycle life and faster charging. Samsung SDI Co., Ltd. leverages its vertical integration into cathode materials to secure cost advantages. LG Energy Solution anchors premium smartphone contracts through its cobalt-light chemistry leadership. CATL competes aggressively on manufacturing scale, extending gigafactory output into consumer electronics cells.
A mobile battery is an electrochemical energy storage device, typically employing lithium-ion or lithium-polymer chemistry with nominal voltages between 3.6V and 3.85V, designed to power portable electronic devices through reversible lithium-ion intercalation. Lithium polymer cells now dominate the premium smartphone segment due to their form-factor flexibility and gravimetric energy density exceeding 250 Wh/kg. The wearable devices application represents the fastest-growing demand pool, though margin pools remain concentrated in laptop and tablet segments where larger capacities justify premium pricing.
China's SAMR enforces GB 31241 safety standards that mandate nail penetration and thermal abuse testing for all domestic cell sales. The EU's REACH regulation restricts cobalt and nickel supply chains, while the EU Battery Directive shapes extended producer responsibility frameworks. Japan's METI oversees JIS C 8712 compliance for imported cells. Stakeholders must monitor how divergent chemistry disclosure rules across Beijing, Brussels, and Tokyo reshape supplier qualification timelines and regional sourcing strategies.
Market Dynamics
High-density lithium-polymer cell specifications are rotating through smartphone supply chains as 5G power consumption demands outpace legacy energy density curves. Cell manufacturers face compressed qualification timelines from OEMs seeking longer cycle life and faster charging protocols simultaneously.
Growth Catalysts
- 5G Handset Refresh Cycles:Smartphone OEMs are expanding orders for high-density cells to offset 5G modem power drain. South Korean and Japanese production clusters capture this demand concentration.
- GB 31241 Safety Certification:China's SAMR mandates nail penetration and thermal abuse testing for domestic cell sales, creating quality-tier differentiation that rewards certified suppliers.
- Wearable Device Proliferation:Smartwatches and hearables require ultra-thin flexible cells. Lithium polymer gravimetric energy density exceeding 250 Wh/kg enables form-factor innovation.
Market Restraints
- Cobalt Supply Concentration:DRC mining dominance creates geopolitical and ethical sourcing risk. EU REACH restrictions compound supply chain complexity.
- Electrolyte Thermal Runaway:Organic liquid electrolytes impose fundamental safety limits on fast-charging architectures. Solid-state alternatives remain pre-commercial.
- East Asian Production Lock-in:Cathode active material and separator manufacturing concentrates in South Korea, Japan, and China, limiting geographic diversification.
Strategic Opportunities
- Solid-State Electrolyte Convergence:Sulfide and oxide solid electrolytes paired with silicon anodes promise 400+ Wh/kg density. Early movers capture next-generation smartphone contracts.
- India Local Cell Assembly:PLI scheme incentives for electronics manufacturing create import-substitution potential for mid-tier smartphone batteries.
- Extended Producer Responsibility:EU Battery Directive mandates collection and recycling targets. Closed-loop material recovery creates captive feedstock advantages.
Industry Challenges
- Cell Formation Bottlenecks:Electrochemical conditioning requires 2-3 week aging cycles. Gigafactory scale-up strains formation equipment capacity.
- JIS C 8712 Compliance Complexity:Japan's METI oversees divergent testing protocols versus China's GB standards and EU REACH disclosure rules. Multi-market qualification extends launch timelines.
- Fast-Charging Degradation Trade-offs:Higher C-rate protocols accelerate lithium plating and cathode cracking. Warranty exposure expands with consumer charging behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Battery Market |
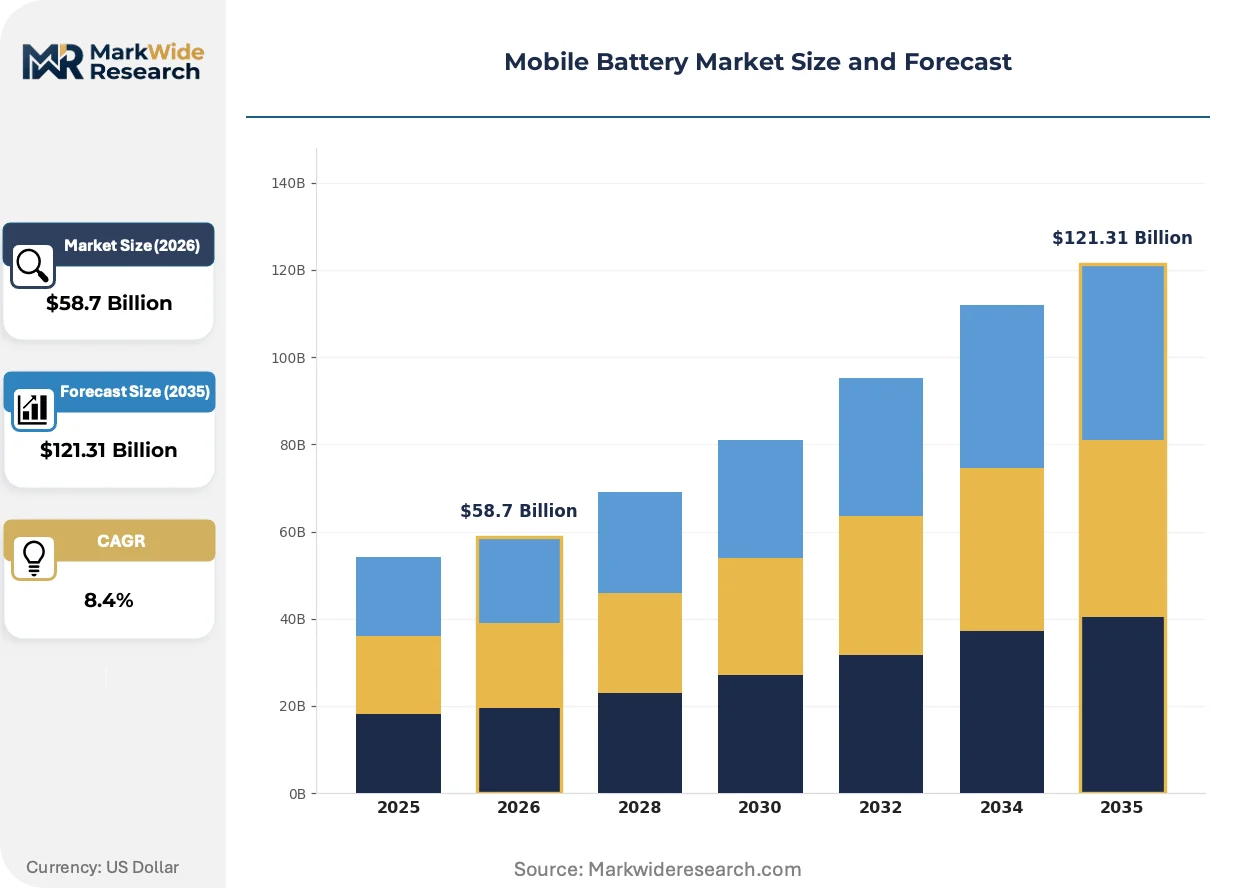
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lithium Polymer, Nickel-Cadmium, Nickel Metal Hydride Application: Smartphones, Tablets, Laptops, Wearable Devices End User: Consumer Electronics, Industrial Use, Medical Devices, Automotive Connectivity: Wired, Wireless, USB-C, Qi |
| Companies Covered | Samsung SDI Co., Ltd., LG Energy Solution, Contemporary Amperex Technology Co., Limited (CATL), BYD Company Ltd., Panasonic Corporation, Murata Manufacturing Co., Ltd., Sunwoda Electronic Co., Ltd., Amperex Technology Limited (ATL), Tianjin Lishen Battery Joint-Stock Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Battery Market Strategic Shifts
Solid-state and silicon-anode architectures are compressing conventional lithium-ion performance limits. Manufacturing scale and regulatory disclosure rules are reshaping competitive positioning simultaneously.
Silicon-composite anodes are miniaturizing graphite-dominated electrode designs. Premium smartphone OEMs are qualifying 10-15% silicon loadings for 2025 flagship launches. Volumetric energy density gains of 20-30% enable thinner handset profiles without capacity sacrifice.
REACH cobalt and nickel supply chain restrictions are forcing cathode chemistry pivots. Lithium iron phosphate and high-nickel low-cobalt formulations gain share in mid-tier segments. Cell suppliers face expanded due diligence burdens and third-party audit requirements.
Buyers are consolidating procurement around qualified cell vendors with multi-region certification. Tier-one smartphone OEMs are reducing supplier counts from 6-8 to 3-4 per platform. South Korean and Japanese manufacturers capture volume concentration as Chinese suppliers face EU and Japan market access friction.
Mobile Battery Market Segmentation
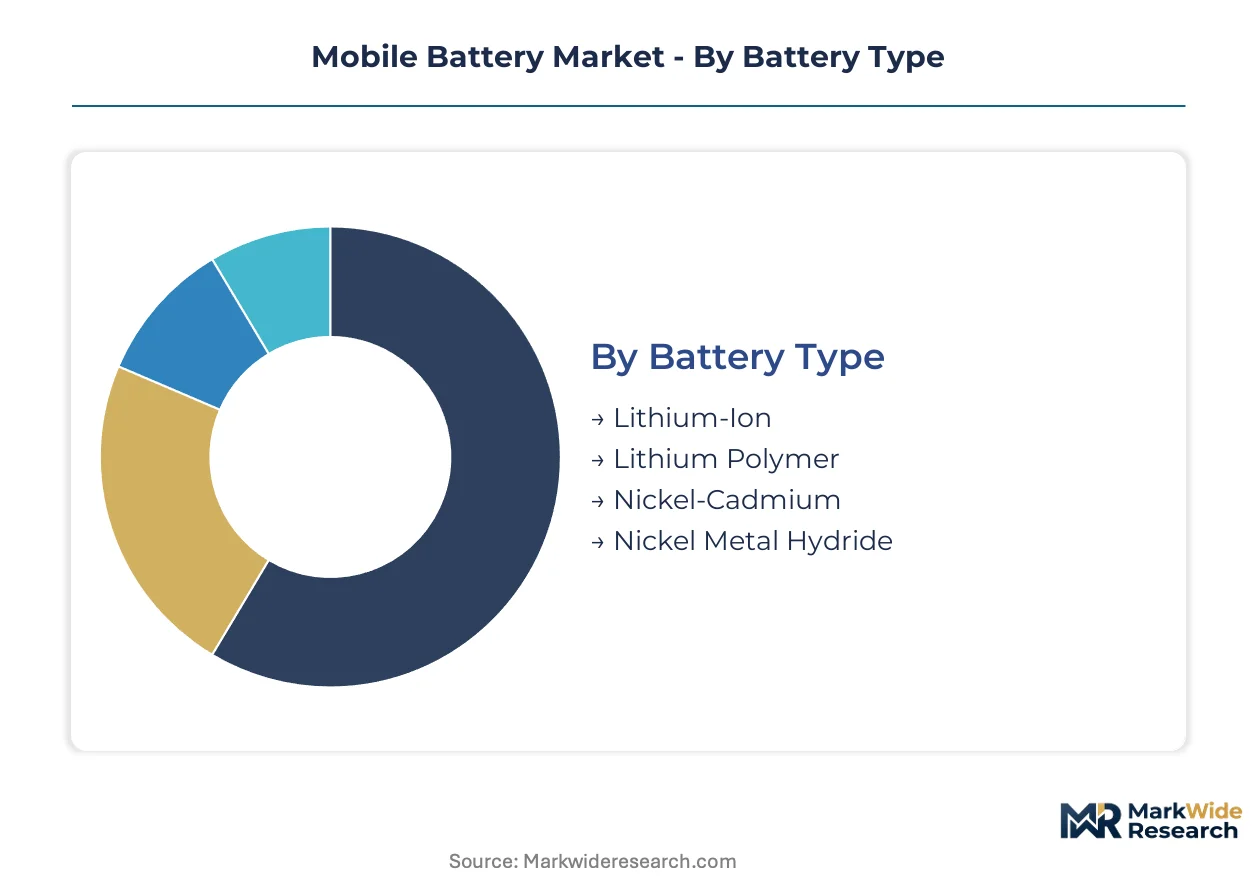
Mobile battery procurement strategies diverge sharply across chemistry, device category, and power interface specifications. OEMs qualify suppliers against distinct regulatory frameworks and performance thresholds for each segment tier.
Battery Type:
GB 31241 certification in China, JIS C 8712 compliance in Japan, and EU REACH disclosure rules create divergent qualification burdens for each chemistry family. Cell manufacturers must maintain parallel certification portfolios to serve multi-region OEMs.
- Lithium Polymer:Pouch-cell architecture with aluminum-laminate packaging enables sub-3mm thickness profiles. Premium smartphone OEMs in South Korea and Japan concentrate procurement here for flagships requiring 250+ Wh/kg gravimetric density and complex form factors.
- Lithium-Ion:Cylindrical and prismatic hard-case designs dominate laptop and power tool applications. China's domestic production clusters supply mid-tier consumer electronics with cost-optimized 18650 and 21700 formats under SAMR safety oversight.
- Nickel Metal Hydride:Legacy chemistry retains niche demand in medical device backup systems requiring stable discharge curves and minimal self-discharge. Japanese industrial OEMs maintain limited procurement for equipment with decade-long service life requirements.
- Nickel-Cadmium:Rugged temperature tolerance sustains aviation and emergency lighting applications despite cadmium toxicity restrictions. EU REACH compliance costs limit new design-ins to replacement markets.
Established volume favors Lithium-Ion; emerging adoption favors Lithium Polymer.
Application:
Power consumption profiles and form-factor constraints reshape cell specifications across device categories. 5G modem integration and foldable display mechanics drive divergent energy density and flexibility requirements.
- Smartphones:Dual-cell architectures and stepped battery designs accommodate camera modules and 5G antenna arrays. South Korean OEMs lead procurement of silicon-anode prototypes for next-generation flagships.
- Wearable Devices:Curved and rectangular cells below 500mAh enable smartwatch and hearable form factors. Japanese component suppliers specialize in ultra-thin polymer cells with sub-2mm Z-height for wrist-worn applications.
- Laptops:High-capacity 60-100Wh packs justify premium cell pricing and advanced battery management systems. Chinese ODMs drive consolidation around USB-C Power Delivery compatibility.
- Tablets:Mid-tier energy density requirements balance cost against cycle life for education and enterprise deployments. Indian PLI scheme incentives attract local assembly investment for this segment.
Wearable Devices command the steepest expansion trajectory; Laptops retain the deepest margin pools.
End User:
Reliability standards and procurement scale separate consumer from industrial and medical demand pools. Each vertical imposes distinct warranty, traceability, and chemistry disclosure requirements.
- Consumer Electronics:High-volume, short-lifecycle procurement with 300-500 cycle life specifications. Chinese OEMs dominate order books with aggressive cost positioning.
- Industrial Use:Extended temperature range and vibration tolerance requirements for field equipment. Japanese suppliers maintain qualification advantages for factory automation and instrumentation.
- Medical Devices:FDA and PMDA biocompatibility standards plus IEC 60601 compliance for patient-contact equipment. Cobalt-free cathode chemistries gain preference for implantable and wearable diagnostic tools.
- Automotive:12V auxiliary power and key fob applications with AEC-Q200 qualification. South Korean cell makers leverage EV gigafactory scale to cross-serve this adjacent segment.
Consumer Electronics anchors procurement volume; Medical Devices extract the highest certification premiums.
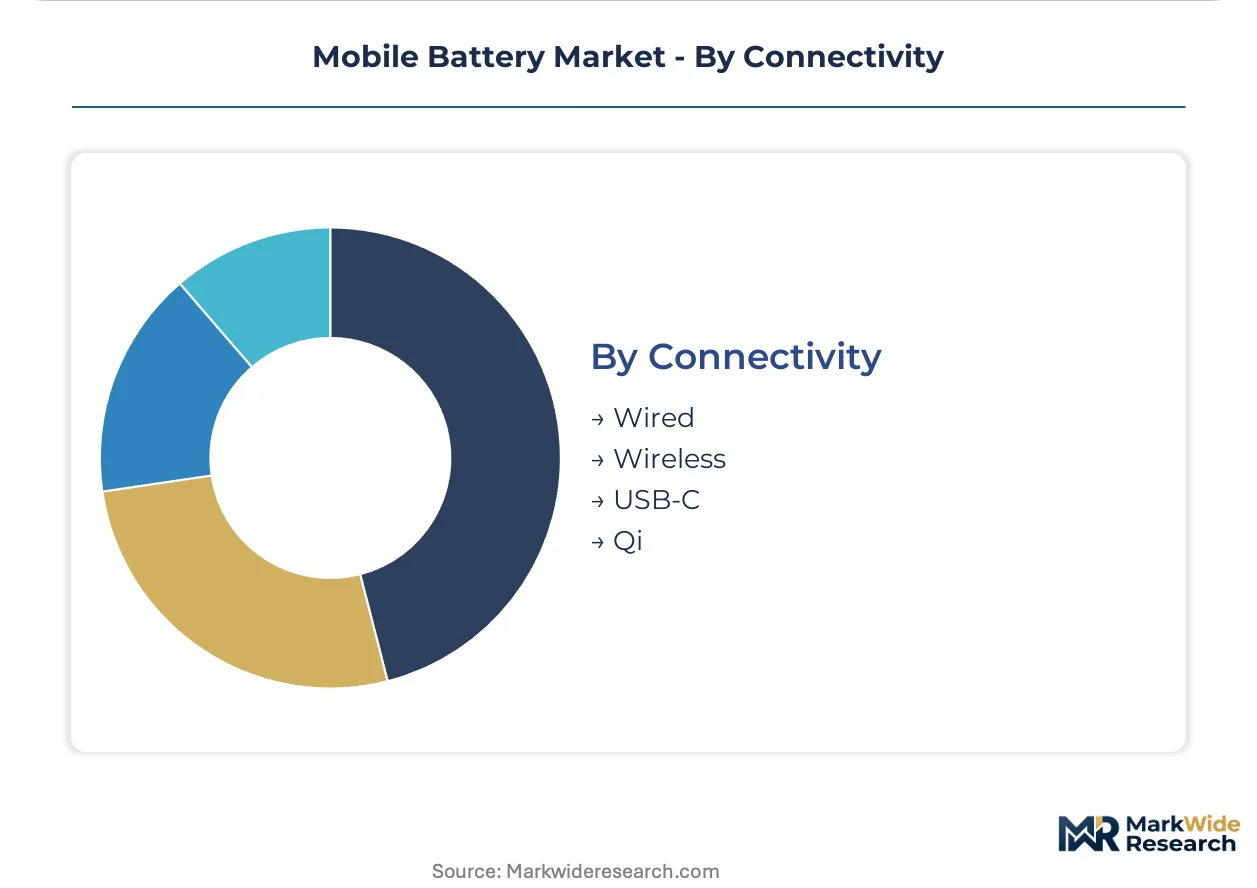
Connectivity:
Charging interface standardization and power delivery protocols determine cell management system complexity. OEMs face interoperability mandates across regional regulatory environments.
- USB-C:IEC 62680 standardization and EU common charger mandates drive universal adoption. Power Delivery 3.1 specifications enable 240W charging for laptop-class devices.
- Qi:Wireless Power Consortium certification for 5-15W inductive charging in smartphones and wearables. Coil alignment tolerances and foreign object detection add battery management complexity.
- Wired:Legacy proprietary connectors retain installed base replacement demand. Apple's Lightning ecosystem maintains significant though declining procurement in North American markets.
- Wireless:Emerging resonant and radio-frequency charging architectures for IoT and medical implants. Pre-commercial deployments focus on ultra-low-power sensor networks.
USB-C consolidates new design-ins; Wireless protocols gain share fastest in medical and IoT verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean cell exports flow into Vietnamese smartphone assembly plants serving North American and European OEMs. Japanese cathode material shipments feed Chinese gigafactory operations. Cross-border qualification protocols now govern regional trade corridors.
China
Domestic smartphone OEMs and EV-to-consumer-electronics cross-production drive cell demand. SAMR enforces GB 31241 nail penetration and thermal abuse testing for all domestic sales. Shenzhen and Dongguan production clusters house cathode active material plants supplying both local and export markets.
South Korea
Premium smartphone OEMs source high-density silicon-anode prototypes for flagship launches. METI-aligned JIS C 8712 compliance enables Japanese market access for certified suppliers. Ulsan and Gwangju industrial zones concentrate cathode coating and separator manufacturing capacity.
Japan
Medical device and industrial instrumentation OEMs require extended cycle life and temperature tolerance specifications. PMDA oversees biocompatibility standards for patient-contact battery applications. Osaka and Nagoya metropolitan areas host specialty polymer cell fabrication for ultra-thin wearable applications.
India
Mid-tier smartphone and tablet OEMs expand local assembly under electronics manufacturing incentives. BIS certification and PLI scheme subsidies attract import-substitution investment for consumer electronics cells. Tamil Nadu and Karnataka states host emerging pack assembly operations serving domestic and export demand.
United States
Medical device and industrial automation OEMs procure cobalt-free cathode chemistries for FDA-regulated applications. EPA and FCC frameworks govern battery disposal and electromagnetic compatibility. Austin and Boston metropolitan areas concentrate battery management system design and medical device integration engineering.
Mobile Battery Market Competitive Environment
Listed leaders compete with private specialists across certification portfolios and chemistry roadmaps. The supplier base consolidates around three to four qualified vendors per major smartphone platform. Three archetypes dominate: integrated material-to-cell manufacturers, pure-play cell specialists, and cross-sector battery conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs reduce supplier counts.
Within the integrated materials tier, Samsung SDI Co., Ltd. and LG Energy Solution exemplify backward integration strategies into cathode production. Contemporary Amperex Technology Co., Limited occupies a position as a scale-driven manufacturer extending automotive gigafactory output into consumer electronics. Among Japanese fabricators, Murata Manufacturing Co., Ltd. represents specialty polymer cell expertise for ultra-thin applications. BYD Company Ltd. and Sunwoda Electronic Co., Ltd. anchor Chinese private specialist archetypes competing on cost-optimized formation and domestic market access.
| Leading Market Players |
|---|
| Samsung SDI Co., Ltd. |
| LG Energy Solution |
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Ltd. |
| Panasonic Corporation |
| Murata Manufacturing Co., Ltd. |
| Sunwoda Electronic Co., Ltd. |
| Amperex Technology Limited (ATL) |
| Tianjin Lishen Battery Joint-Stock Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Twenty-one-day cathode active material lead times from South Korean suppliers concentrate pricing power among cell manufacturers with backward integration into precursor production. Days-of-inventory compression across Japanese separator producers tightens spot market availability for mid-tier buyers. This dynamic rewards qualified suppliers with GB 31241 and JIS C 8712 certifications while squeezing margin pools for import-dependent assemblers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the mobile battery market. Price differentiation rests on GB 31241 certification grade and cathode chemistry cobalt content, with medical device OEMs paying certification premiums and consumer electronics buyers driving volume discounts. Cost compression in standard-tier lithium-ion cells is intensifying because Chinese gigafactory overcapacity feeds global spot markets. Consumer electronics OEMs exhibit highest price sensitivity; medical device buyers show lowest sensitivity due to FDA and PMDA compliance requirements.
Supply Chain Analysis
China, South Korea, and Japan anchor cathode active material and separator manufacturing for mobile battery supply chains. Cell production draws from DRC cobalt concentrates, Australian lithium spodumene, and Chinese graphite anode feedstocks. Single-source vulnerability concentrates in electrolyte salt production where Japanese suppliers dominate LiPF6 capacity. Distribution runs through Shenzhen and Dongguan pack assembly clusters into Vietnamese smartphone integration plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward tier-one smartphone OEMs consolidating supplier counts from six-to-eight vendors to three-to-four per platform. This procurement consolidation squeezes margin pools and extends qualification timelines for non-certified suppliers.
For Market Incumbents: Secure multi-region certification portfolios spanning GB 31241, JIS C 8712, and EU REACH compliance to defend against emerging Chinese suppliers facing export market access friction. Invest in captive cathode precursor production to offset cobalt price volatility and DRC supply concentration risk. Extend formation capacity in South Korean and Japanese industrial zones to capture premium smartphone contract renewals. For New Entrants and Emerging Players: Lead with solid-state electrolyte prototypes targeting 400+ Wh/kg density specifications for next-generation flagship qualifications. India's PLI scheme subsidies for mid-tier smartphone and tablet cell assembly represent the most penetrable geography. Pursue joint qualification programs with domestic Indian OEMs seeking import-substitution partnerships under BIS certification pathways. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry consolidation play because cathode active material and separator manufacturing concentration creates acquisition targets with irreplaceable process knowledge. Focus on Japanese specialty polymer cell fabricators with PMDA medical device relationships and sub-2mm Z-height production capabilities. Watch silicon-anode qualification announcements from South Korean flagship OEMs as inflection indicator for next-generation chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Development | Sulfide and oxide solid electrolytes paired with silicon anodes promise 400+ Wh/kg density for premium smartphone contracts. |
| Multi-Region Certification Investment | Parallel GB 31241, JIS C 8712, and REACH compliance portfolios qualify suppliers for tier-one OEM procurement consolidation. |
| Backward Integration into Cathode Materials | In-house precursor production insulates margin pools from DRC cobalt price volatility and supply concentration risk. |
| India Local Cell Assembly Expansion | PLI scheme incentives and BIS certification pathways enable import-substitution positioning for mid-tier consumer electronics. |
| Closed-Loop Material Recovery Buildout | EU Battery Directive collection targets create captive feedstock advantages for cell manufacturers with recycling infrastructure. |
Study Parameters
A spread of perspectives from cell formation engineers, smartphone OEM procurement directors, cathode material plant managers, and medical device regulatory affairs leads converged on the working assumptions in this analysis. Primary fieldwork combined structured interviews with secondary validation through SAMR GB standard filings, METI JIS certification registries, EU REACH substance databases, and SEC 10-K disclosures from listed cell manufacturers. Bottom-up capacity modeling and top-down demand triangulation from smartphone shipment databases anchored volume and value estimates.
Segmentation dimensions modeled include battery chemistry family, device application category, end-user vertical, and charging interface protocol across the analysis window. CAGRs derived from weighted average of historical shipment growth, OEM procurement pipeline visibility, and replacement cycle assumptions. Silicon-anode loading percentages and solid-state electrolyte commercialization timelines served as chemistry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained 5G handset refresh cycles, stable cobalt concentrate supply, or unchanged GB 31241 certification timelines would require recalibration. Forecasts reflect documented assumptions about cell formation equipment capacity expansion and East Asian production cluster stability. Recalibration cycles align with material shifts in SAMR regulatory enforcement, EU Battery Directive implementation, and silicon-anode qualification announcements from flagship OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Wide Temperature Battery Market
Batteries
India SLI Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
India Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Europe Industrial Battery Market
Batteries
Global Industrial Battery Market
Batteries
Battery Plate Market
Batteries
South America Consumer Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Smart Battery Charger Market
Batteries
North Africa Battery Market
Batteries
Medical Batteries Market