
 Two Wheeler Lead Acid Batteries Market | 2026-2036
Two Wheeler Lead Acid Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Lead Acid Batteries Market Outlook
REACH compliance is rebalancing the cost-of-entry calculus for battery manufacturers serving European export channels. Exide Industries Limited leverages its integrated smelting capacity to absorb lead price volatility. Amara Raja Batteries Limited anchors its position through dense aftermarket distribution across South India. Chaowei Power Holdings Limited dominates OEM supply relationships with domestic motorcycle brands in China.
Two wheeler lead acid batteries store electrochemical energy through lead dioxide and sponge lead electrodes submerged in sulfuric acid electrolyte, typically delivering 12 volts with capacities ranging from 2.5 Ah to 14 Ah for starting, lighting, and ignition functions. VRLA designs now lead product mix shifts as sealed construction eliminates electrolyte maintenance for scooter operators in tropical climates. The E-Bike end user segment represents the fastest-growing demand pool, though motorcycles still occupy the largest absolute volume position. Wholesale distribution channels sustain margin concentration through fleet and workshop purchasing power.
India's BIS mandates tighter cold cranking amp verification, while China's GB standards enforce recycling traceability through MIIT oversight. ECHA's REACH restrictions on lead compound handling raise compliance costs for exporters to European aftermarket channels. Stakeholders must monitor how lithium-ion substitution pressures reshape OEM sourcing strategies for entry-level electric two-wheelers.
Market Dynamics
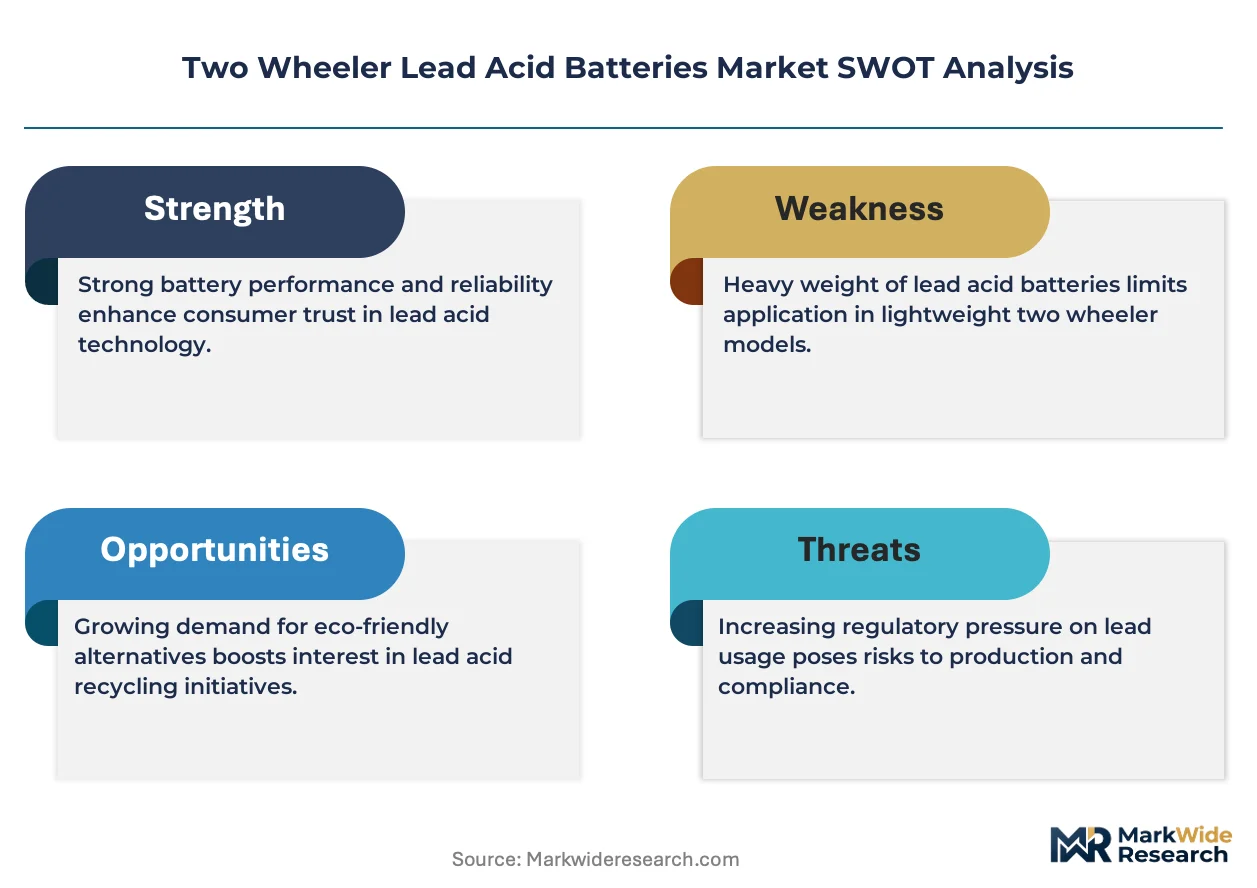
Lead price volatility and India's BIS certification tightening are compressing margin structures for battery manufacturers while accelerating VRLA adoption across tropical commuter markets. These dual pressures reshape competitive positioning between integrated smelters and aftermarket distributors.
Growth Catalysts
- Southeast Asia replacement cycles:Motorcycle commuter fleets in Indonesia, Vietnam, and Thailand generate sustained aftermarket demand as vehicle parc ages beyond four-year battery lifespans.
- India's BIS cold cranking mandates:Tighter verification standards force quality upgrades across northern and western state markets, elevating certified product penetration.
- VRLA sealed construction:Maintenance-free designs eliminate electrolyte topping requirements for scooter operators in high-humidity climates, accelerating product mix shifts.
Market Restraints
- Lead price volatility:London Metal Exchange lead futures create input cost instability for non-integrated manufacturers lacking captive smelting capacity.
- Lithium-ion substitution:Entry-level electric two-wheeler OEMs are sourcing lithium-ion packs for new vehicle platforms, eroding lead acid's historical dominance in starting applications.
- ECHA REACH compliance costs:European aftermarket exporters face elevated lead compound handling restrictions, raising cost-of-entry for battery producers serving EU channels.
Strategic Opportunities
- E-Bike segment expansion:Electric bicycle demand pools represent underpenetrated white space where lead acid retains cost advantages over lithium-ion for price-sensitive consumers.
- India PLI scheme alignment:Production-linked incentive frameworks for advanced chemistry cells create co-investment pathways for lead acid manufacturers diversifying into energy storage adjacent markets.
- Workshop direct distribution:Bypassing wholesale intermediaries to capture fleet and independent mechanic purchasing power unlocks margin expansion in dense urban service corridors.
Industry Challenges
- Recycling traceability compliance:China's MIIT oversight of GB standard recycling mandates requires investment in digital chain-of-custody systems for lead recovery documentation.
- Certification timeline compression:India's BIS laboratory testing queues extend product launch cycles, delaying revenue recognition for new capacity deployments.
- Skill gap in VRLA manufacturing:Sealed battery production demands precision welding and electrolyte filling automation expertise scarce in traditional flooded battery labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Lead Acid Batteries Market |
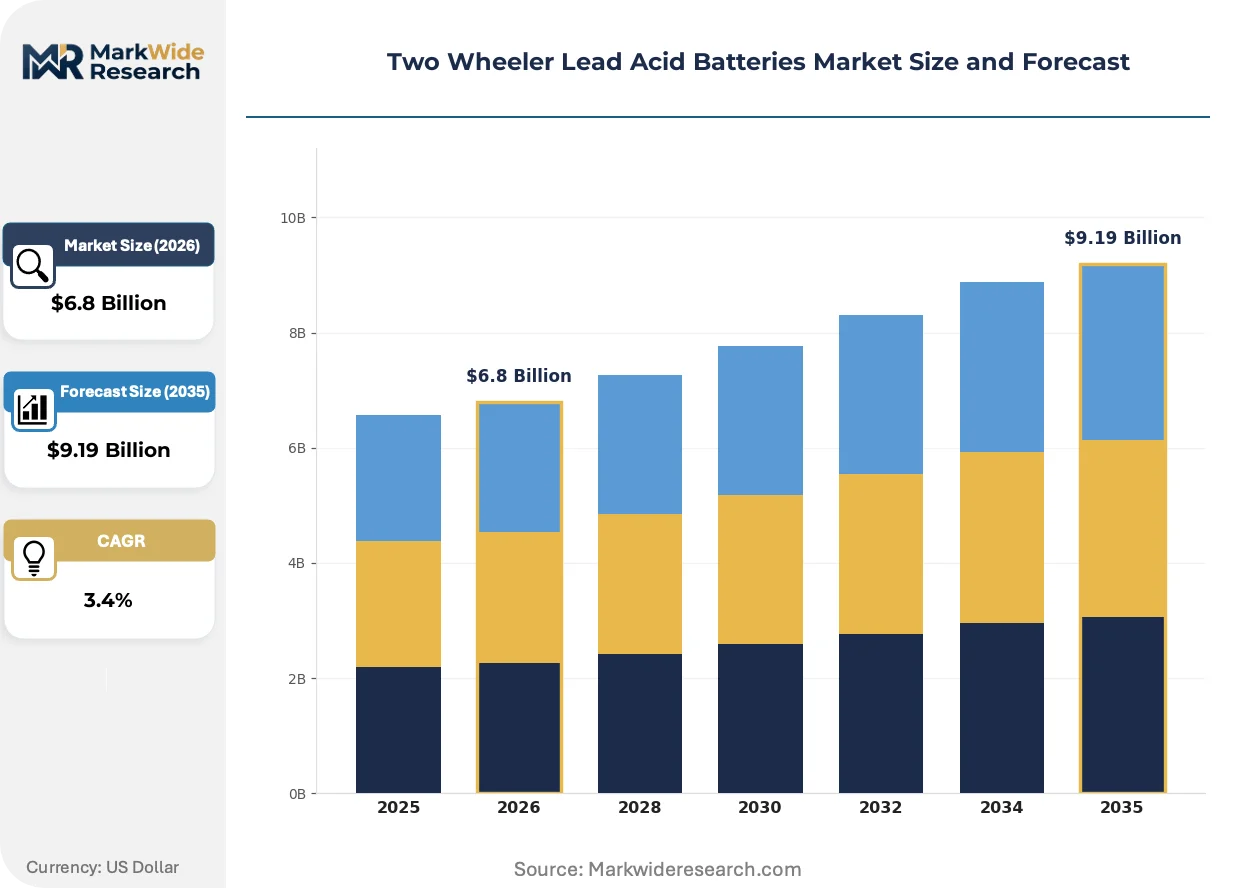
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA, VRLA, AGM, Conventional End User: Motorcycles, Scooters, E-Bikes, Delivery Vehicles Technological Type: Standard, Sealed, Maintenance-Free, High-Performance Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Exide Industries Limited, Amara Raja Batteries Limited, Clarios LLC, Chaowei Power Holdings Limited, EnerSys Inc., East Penn Manufacturing Co. Inc., Camel Group Co. Ltd., GS Yuasa Corporation, Sebang Global Battery Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Lead Acid Batteries Market Strategic Shifts
VRLA automation, regulatory tightening on lead handling, and channel restructuring are converging to reshape how two-wheeler batteries are manufactured, certified, and distributed across tropical commuter markets.
Automated electrolyte filling and precision welding systems are automating VRLA production consistency while reducing manual labor exposure to sulfuric acid. OEM suppliers in China and India are adopting these lines at accelerating pace to meet BIS and GB certification tolerances. This automation is compressing defect rates and enabling smaller batch sizes for regional battery specifications.
India's BIS mandates now require documented cold cranking amp verification across temperature ranges, forcing manufacturers to retest legacy product lines. The industrial consequence is consolidation of testing capacity among laboratories with thermal chamber infrastructure. Northern Indian states with highest two-wheeler density face the steepest compliance timelines as certification backlogs extend.
Fleet operators and workshop chains are consolidating purchasing power through direct supplier relationships, disintermediating traditional wholesale distributors. This channel compression is most visible in Indonesia's motorcycle taxi fleets and India's urban service corridors where volume concentration enables price negotiation. Distributors respond by bundling installation services and warranty administration to defend position.
Two Wheeler Lead Acid Batteries Market Segmentation
Two-wheeler lead acid battery manufacturers configure production lines around distinct technical specifications and channel economics. Each segmentation dimension carries different margin profiles and capital requirements that reshape competitive positioning across tropical commuter markets.
Product Type:
Capital intensity varies sharply across sealed versus flooded designs, with automation requirements driving facility investment thresholds.
- VRLA:Valve-regulated lead acid construction eliminates electrolyte maintenance through recombinant gas technology. Scooter operators in Indonesia and Vietnam drive replacement demand as sealed designs withstand high-humidity storage without topping requirements.
- AGM:Absorbent glass mat separators immobilize electrolyte in fiberglass matrices, enabling vibration resistance for motorcycle applications. OEM fitment in Chinese domestic brands concentrates demand as GB standard tolerances tighten.
- SLA:Sealed lead acid variants serve price-sensitive aftermarket replacement with lower manufacturing automation barriers.
- Conventional:Flooded wet-cell designs persist in rural Indian markets where electrolyte topping labor remains economical.
Most installed capacity flows through VRLA lines. Expansion is steepest in AGM as vibration-resistant specifications penetrate OEM supply contracts.
End User:
Application-specific duty cycles determine warranty exposure and technical specification differentiation across vehicle platforms.
- E-Bikes:Electric bicycle battery packs operate at lower discharge rates than starting applications, extending cycle life expectations. Northern Indian states with dense urban commuting corridors generate concentrated demand as price-sensitive consumers favor lead acid cost structures over lithium-ion alternatives.
- Motorcycles:Internal combustion engine starting applications demand high cold cranking amp outputs for reliable ignition. BIS certification mandates in Maharashtra and Gujarat force quality tier separation as thermal chamber testing extends lead times.
- Scooters:Automatic transmission platforms with under-seat battery placement favor compact VRLA footprints.
- Delivery Vehicles:Commercial fleet duty cycles with multiple daily starts accelerate replacement frequency in urban logistics corridors.
Volume concentrates in motorcycle replacement. E-Bike applications are climbing the fastest as electrification penetrates entry-level mobility segments.
Technological Type:
Performance tier separation aligns with certification grade differentiation and warranty liability structures.
- Maintenance-Free:Sealed construction eliminates consumer-accessible cells, reducing field failure rates from improper electrolyte handling. Tropical climate operators in Thailand and Philippines prioritize these specifications as ambient temperatures accelerate water loss in flooded designs.
- High-Performance:Enhanced plate alloys and separator materials deliver extended cycle life for commercial applications. Fleet operators in Indonesian motorcycle taxi services concentrate procurement as total cost-of-ownership calculations favor premium upfront pricing.
- Standard:Basic flooded construction serves cost-minimized replacement demand in price-sensitive rural markets.
- Sealed:Generic VRLA construction without enhanced alloys occupies mid-tier positioning between standard and maintenance-free grades.
Revenue mix tilts toward maintenance-free specifications. High-performance variants are gaining share fastest as fleet purchasing power consolidates.
Distribution Channel:
Channel selection determines working capital intensity and margin capture through intermediary layers.
- Wholesale:Distributor networks aggregate fragmented workshop demand across geographic territories. India's northern state battery markets concentrate volume through tier-two distributor hubs in Lucknow and Jaipur where fleet purchasing power negotiates volume discounts.
- Direct Sales:Manufacturer-to-fleet relationships bypass intermediary margins for high-volume accounts. Indonesian Gojek and Grab motorcycle taxi fleets consolidate procurement through direct supplier contracts as vehicle parc scales beyond ten thousand units.
- Retail:Counter sales to individual consumers carry highest per-unit margins but fragment order processing.
- Online:E-commerce penetration remains limited for hazardous goods requiring installation support and core exchange logistics.
Transaction volume flows through wholesale intermediaries. Direct sales channels are expanding most quickly as fleet concentration accelerates disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled battery assembly workforces concentrate in India's western industrial corridor and China's Pearl River Delta, anchoring production capacity for tropical climate specifications.
India
Motorcycle commuter fleets in Maharashtra and Gujarat generate replacement demand as vehicle parc exceeds four-year battery lifespans. BIS mandates tighter cold cranking amp verification across temperature ranges, forcing manufacturers to retest legacy product lines. Industrial clusters in Pune and Ahmedabad concentrate VRLA production lines serving northern and western state distribution hubs.
China
Domestic motorcycle OEMs and e-bike assemblers in the Yangtze River Delta sustain OEM supply contracts for sealed battery designs. MIIT oversight of GB standards enforces recycling traceability through digital chain-of-custody documentation requirements. Manufacturing concentration in Zhejiang and Jiangsu provinces accelerates automated electrolyte filling adoption for certification tolerance compliance.
Indonesia
Motorcycle taxi fleets operated by Gojek and Grab generate concentrated aftermarket procurement as commercial duty cycles compress replacement intervals. The country's national standards body enforces product safety marking for battery imports through SNI certification requirements. Jakarta and Surabaya urban corridors witness direct supplier-fleet contracting that disintermediates traditional wholesale distributors.
Vietnam
Scooter operators in Ho Chi Minh City and Hanoi drive VRLA replacement demand as high-humidity storage accelerates sealed construction preference. The Ministry of Science and Technology administers technical regulations for lead acid battery circulation and recycling. Manufacturing investment clusters in Binh Duong and Dong Nai provinces target export assembly for Southeast Asian distribution networks.
Thailand
Commercial delivery vehicle fleets in Bangkok metropolitan area sustain premium battery procurement as total cost-of-ownership calculations favor extended cycle life specifications. The Thai Industrial Standards Institute mandates TISI marking for automotive battery safety compliance. Eastern Economic Corridor industrial zones host assembly operations serving domestic replacement and Myanmar export channels.
Two Wheeler Lead Acid Batteries Market Competitive Environment
The competitive structure tilts toward integrated manufacturers with captive lead smelting capacity and dense aftermarket distribution networks. Three archetypes dominate: vertically integrated producers absorbing raw material volatility, regional distributors leveraging workshop relationships, and OEM specialists anchoring motorcycle brand supply contracts. Competitive moves concentrate on automation investment for VRLA production consistency and direct fleet contracting to bypass wholesale margin compression.
Among India-based manufacturers, Exide Industries Limited and Amara Raja Batteries Limited occupy positions reflecting distinct geographic distribution strengths. Exide exemplifies the integrated smelter archetype with upstream lead processing capabilities. Amara Raja represents the dense aftermarket network model with southern state workshop penetration. Chaowei Power Holdings Limited anchors the OEM specialist tier through domestic motorcycle brand relationships in China. These three illustrate how competitive positioning diverges across raw material control, channel density, and supply contract anchoring strategies.
| Leading Market Players |
|---|
| Exide Industries Limited |
| Amara Raja Batteries Limited |
| Clarios LLC |
| Chaowei Power Holdings Limited |
| EnerSys Inc. |
| East Penn Manufacturing Co. Inc. |
| Camel Group Co. Ltd. |
| GS Yuasa Corporation |
| Sebang Global Battery Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BIS-verified premium products and unmarked economy batteries splits both pricing power and procurement pathways across Indian state markets. This divergence concentrates margin capture among integrated manufacturers with captive laboratory testing capacity while compressing returns for distributors handling commodity-grade flooded cells.
Pricing Analysis
Installation-and-warranty bundling versus bare-unit transactional sales defines the dominant pricing split across Southeast Asian aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels aligns with BIS certification status and cold cranking amp verification tiers. Pricing pressure stems from lead price volatility transmitted through London Metal Exchange futures to non-integrated manufacturers. Fleet operators in Indonesian motorcycle taxi services exhibit lowest price sensitivity due to total cost-of-ownership calculations, while rural Indian replacement buyers drive volume at economy tiers.
Supply Chain Analysis
Core return and lead recovery flows anchor competitive economics through closed-loop smelting economics. Manufacturing concentrates in India, China, and Vietnam with assembly clusters in Pune, Zhejiang, and Binh Duong provinces. Supply chains draw from LME-traded lead ingots, locally sourced sulfuric acid, and polypropylene casing materials. Single-source vulnerability concentrates in laboratory testing capacity for BIS and GB certification compliance. Distribution runs through tier-two distributor hubs serving fragmented workshop networks across northern Indian states and Indonesian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS cold cranking mandates force quality-tier separation and accelerate certified product penetration across Maharashtra and Gujarat replacement cycles.
For Market Incumbents: Deploy automated VRLA production lines to absorb labor cost inflation and meet tightening certification tolerances. Capture margin compression from lead price volatility through backward integration into captive smelting capacity. Defend distributor relationships against fleet disintermediation by bundling installation services and warranty administration in Indonesian and Indian urban corridors. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the most penetrable white-space entry point for bypassing entrenched wholesale networks. Target E-Bike battery pack assembly for northern Indian states where price-sensitive consumers favor lead acid cost structures over lithium-ion alternatives. Anchor initial positioning through workshop-direct relationships in dense urban service corridors where volume concentration enables price negotiation. For Investors and Strategic Acquirers: Consolidation pressure builds where certification backlog delays revenue recognition and compresses working capital efficiency for sub-scale manufacturers. Frame long-term viability around five-to-ten year windows for lead acid retention in starting applications before lithium-ion substitution penetrates entry-level electric two-wheeler platforms. Target acquisition profiles favoring integrated smelters with BIS laboratory partnerships. Monitor lithium-ion pack pricing trajectories as the critical inflection signal for lead acid demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| VRLA Automation Investment | Precision welding and electrolyte filling systems reduce defect rates for BIS certification compliance. |
| Direct Fleet Contracting | Bypassing wholesale intermediaries captures margin expansion in Indonesian Gojek and Grab procurement channels. |
| Backward Integration into Smelting | Captive lead processing absorbs London Metal Exchange price volatility for margin stabilization. |
| Workshop Network Expansion | Dense southern Indian service coverage defends position against distributor disintermediation pressures. |
| E-Bike Pack Assembly Diversification | Lower discharge rate applications extend cycle life expectations in price-sensitive urban commuting segments. |
Study Parameters
Multiple input streams — executive interviews with battery manufacturing plant managers, procurement leads at Indian and Chinese OEMs, and aftermarket distributor principals — were reconciled against secondary validation from BIS certification records, MIIT recycling traceability filings, and customs trade data. Primary fieldwork engaged technical R&D directors at VRLA automation equipment suppliers and fleet procurement officers at Indonesian motorcycle taxi operators. Bottom-up volume modeling across product type, end user, and distribution channel segments was triangulated against top-down market sizing from lead consumption and vehicle parc data.
Cross-referencing historical shipment patterns against expert panel inputs anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product construction type, vehicle application platform, performance tier, and channel structure alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis of replacement cycle frequencies and vehicle fleet aging patterns. Industry-specific forecast inputs incorporated BIS laboratory testing queue durations and MIIT digital chain-of-custody implementation timelines for recycling compliance.
The model assumes a particular technology adoption path; alternative pathways for lithium-ion pack cost reduction would alter the outlook for lead acid retention in starting applications. Forecasts reflect underlying assumptions about certification timeline stability and raw material price transmission mechanisms. Practitioners should monitor lithium-ion substitution rates in entry-level electric two-wheeler OEM sourcing strategies and BIS laboratory capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Rechargeable Coin Cell Market
Batteries
Military Battery Packs Market
Batteries
Asia-Pacific Battery Market
Batteries
India Rechargeable Battery Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Grid-Scale Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Global Bio Compatible Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Custom Battery Pack Market
Batteries
North America Industrial Battery Market
Batteries
Breathing Battery Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Europe Lead-Acid Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Asia-Pacific Dual Carbon Battery Market