
 Valve Regulated Lead-Acid (VRLA) Batteries Market | 2026-2036
Valve Regulated Lead-Acid (VRLA) Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Regulated Lead-Acid (VRLA) Batteries Market Analytics
Subscription-based battery health monitoring is repositioning how VRLA vendors monetize long-term customer relationships. Clarios leverages its global service network to bundle predictive analytics with cell replacements. EnerSys sustains pricing power through captive recycling infrastructure that lowers lead input costs. Leoch International Technology anchors its competitive stance in Asia-Pacific through high-volume AGM production for telecom tower operators.
Valve Regulated Lead-Acid batteries are rechargeable lead-acid cells with internal oxygen recombination chemistry that eliminates free electrolyte spillage, typically constructed with absorbed glass mat separators or gelled electrolyte and operating at float voltages between 2.25 and 2.30 volts per cell. These cells serve primarily as uninterruptible backup power sources where maintenance access proves difficult or hazardous. The AGM product category dominates installed base across datacenter UPS installations due to superior high-rate discharge performance and lower internal resistance. Gel variants occupy niche positions in remote renewable energy storage where elevated ambient temperatures degrade standard AGM life cycles. Small-format cells face margin compression from lithium-ion substitution in portable applications, while large-format custom configurations retain stronger pricing in industrial marine and utility-scale deployments.
The US EPA governs lead smelting emissions and spent battery recycling through RCRA hazardous waste protocols, while India's BIS mandates IS 15549 performance standards for stationary VRLA cells used in telecom infrastructure. China's SAMR enforces GB/T 19638 national standards that restrict mercury content and mandate cycle-life testing for domestic manufacturers. Stakeholders must monitor how evolving carbon border adjustments and circular-economy mandates reshape lead sourcing economics across major producing regions.
Market Dynamics
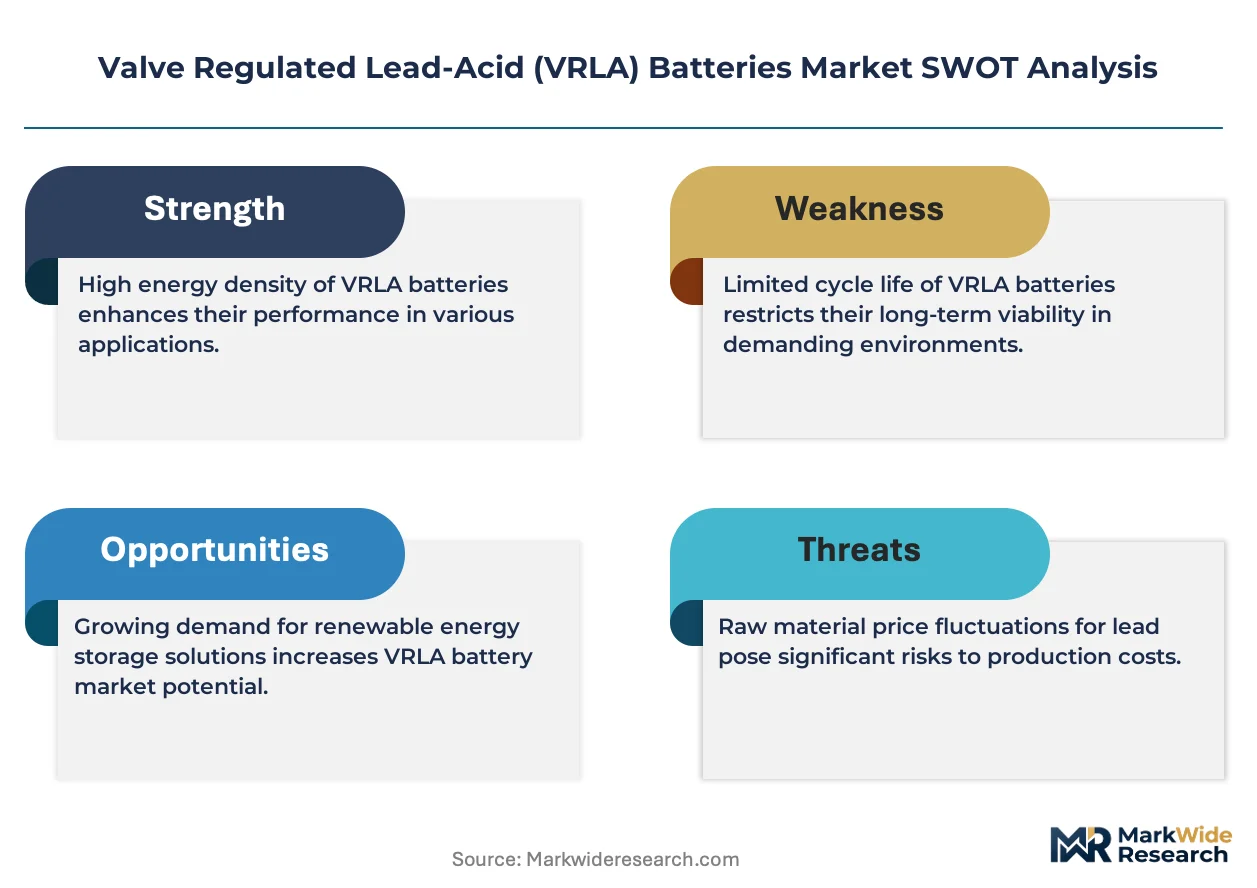
China's dual carbon goals and India's BIS IS 15549 mandates are forcing VRLA manufacturers to decarbonize smelting operations while maintaining cost parity with lithium-ion alternatives in telecom backup applications.
Growth Catalysts
- Grid instability in emerging economies:Telecom tower operators across India and Southeast Asia are expanding VRLA installations as rural electrification gaps persist and diesel generator bans tighten.
- REACH compliance in Europe:Battery recyclers meeting ECHA substance restrictions gain preferential access to OEM supply chains, accelerating circular-economy adoption.
- AGM separator advances:Thinner glass mat designs reduce lead content per kWh while preserving high-rate discharge performance for datacenter UPS systems.
Market Restraints
- Lead price volatility:LME lead futures swings above fifteen percent annually compress cell manufacturer margins and destabilize long-term supply contracts.
- Substitution by lithium iron phosphate:Declining LiFePO4 cell costs displace VRLA in new forklift and residential solar installations below 50 kWh capacity.
- Smelting capacity concentration:Over sixty percent of primary lead refining sits in China, exposing non-Chinese battery assemblers to export quota risks and carbon border adjustment exposure.
Strategic Opportunities
- Second-life automotive lead recovery:Pyrometallurgical refiners in Germany and South Korea are capturing end-of-life EV auxiliary battery streams for VRLA feedstock.
- Remote renewable microgrids:Gel-electrolyte variants penetrate African and Latin American off-grid solar installations where maintenance access is limited and ambient temperatures exceed forty degrees Celsius.
- India's PLI scheme for advanced chemistry cells:VRLA manufacturers supplying telecom infrastructure can access production-linked incentives by meeting domestic value-add thresholds.
Industry Challenges
- Smelter emissions compliance:US EPA RCRA hazardous waste protocols and China's MEE air quality standards require capital-intensive baghouse upgrades and continuous emissions monitoring systems.
- Legacy system integration:Datacenter operators running thirty-year-old UPS architectures face compatibility gaps when retrofitting with higher-efficiency AGM cells requiring altered float voltage profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Regulated Lead-Acid (VRLA) Batteries Market |
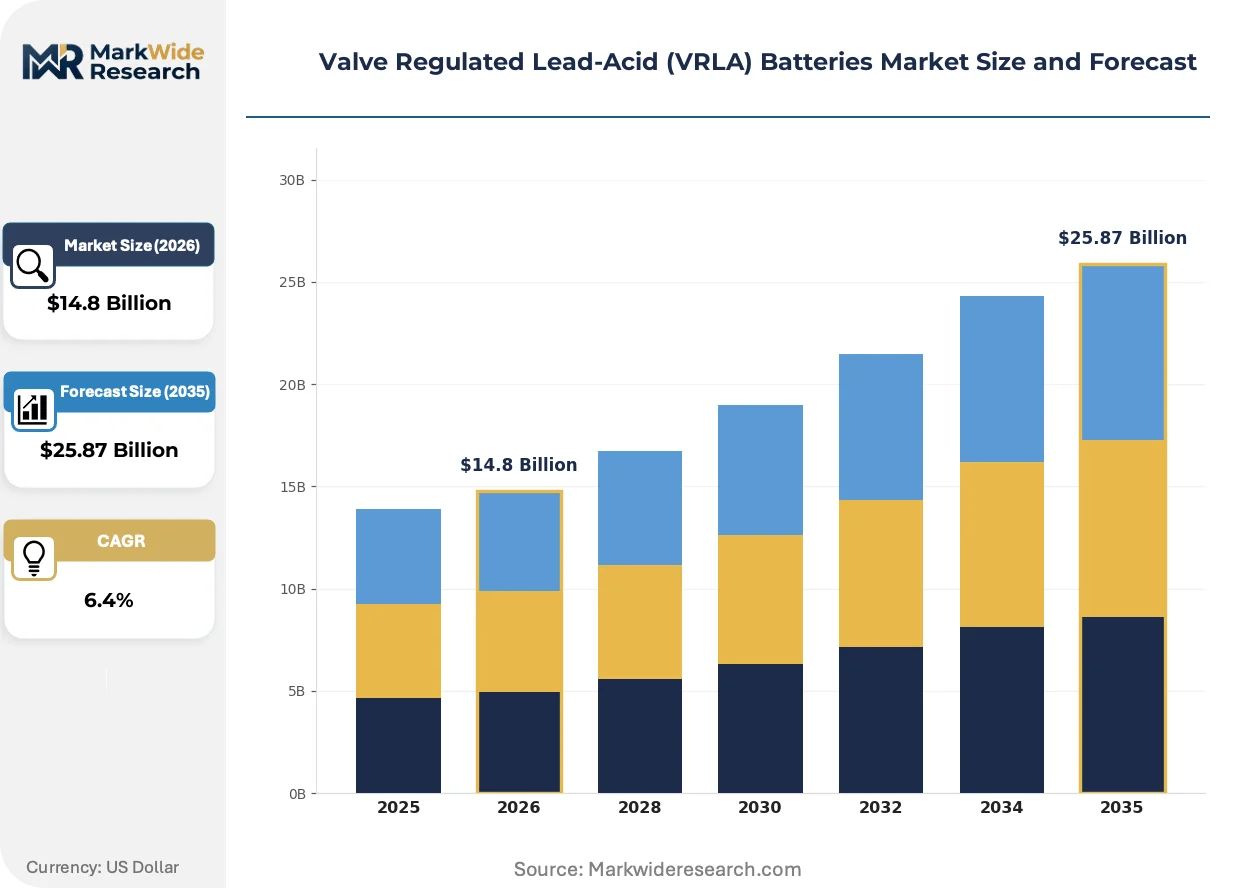
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AGM, Gel, Flooded, Lithium End User: Telecom, UPS, Renewable Energy, Automotive Application: Backup Power, Renewable Energy Storage, Electric Vehicles, Marine Size: Small, Medium, Large, Custom |
| Companies Covered | Clarios, C&D Technologies, EnerSys, Saft Groupe, Leoch International Technology, Exide Technologies, East Penn Manufacturing, Tianneng Holding Group, GS Yuasa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Regulated Lead-Acid (VRLA) Batteries Market Evolving Landscape
Battery-as-a-service models and predictive health monitoring are restructuring how VRLA value migrates from hardware sales to recurring revenue streams tied to uptime guarantees.
Carbon-coated lead-calcium grid alloys are expanding into high-temperature telecom applications previously dominated by pure lead-tin designs. Tower operators in India's Maharashtra and Tamil Nadu corridors are trialing these alloys to combat accelerated corrosion at elevated float temperatures. The technology is expanding into warranty extension programs that differentiate premium cell tiers from commodity replacements.
China's GB/T 19638.2-2018 cycle-life testing mandates now require sixty percent depth-of-discharge validation for stationary cells, forcing domestic manufacturers to reformulate paste recipes and separator compression ratios. Exporters to the Chinese market must retest existing product lines or forfeit SAMR certification eligibility. This regulatory tightening most impacts gel-cell producers serving renewable energy storage segments where deep cycling tolerance determines competitive viability.
Telecom infrastructure buyers are consolidating supplier relationships around integrated recycling contracts that bundle cell procurement with guaranteed buyback of spent units. Tower operators in Indonesia and the Philippines now specify closed-loop lead recovery as a contract prerequisite, displacing spot-market battery transactions. This preference shift is most visible in India's Reliance Jio and Bharti Airtel procurement frameworks, where environmental compliance scoring outweighs unit price in vendor selection algorithms.
Valve Regulated Lead-Acid (VRLA) Batteries Market Segmentation
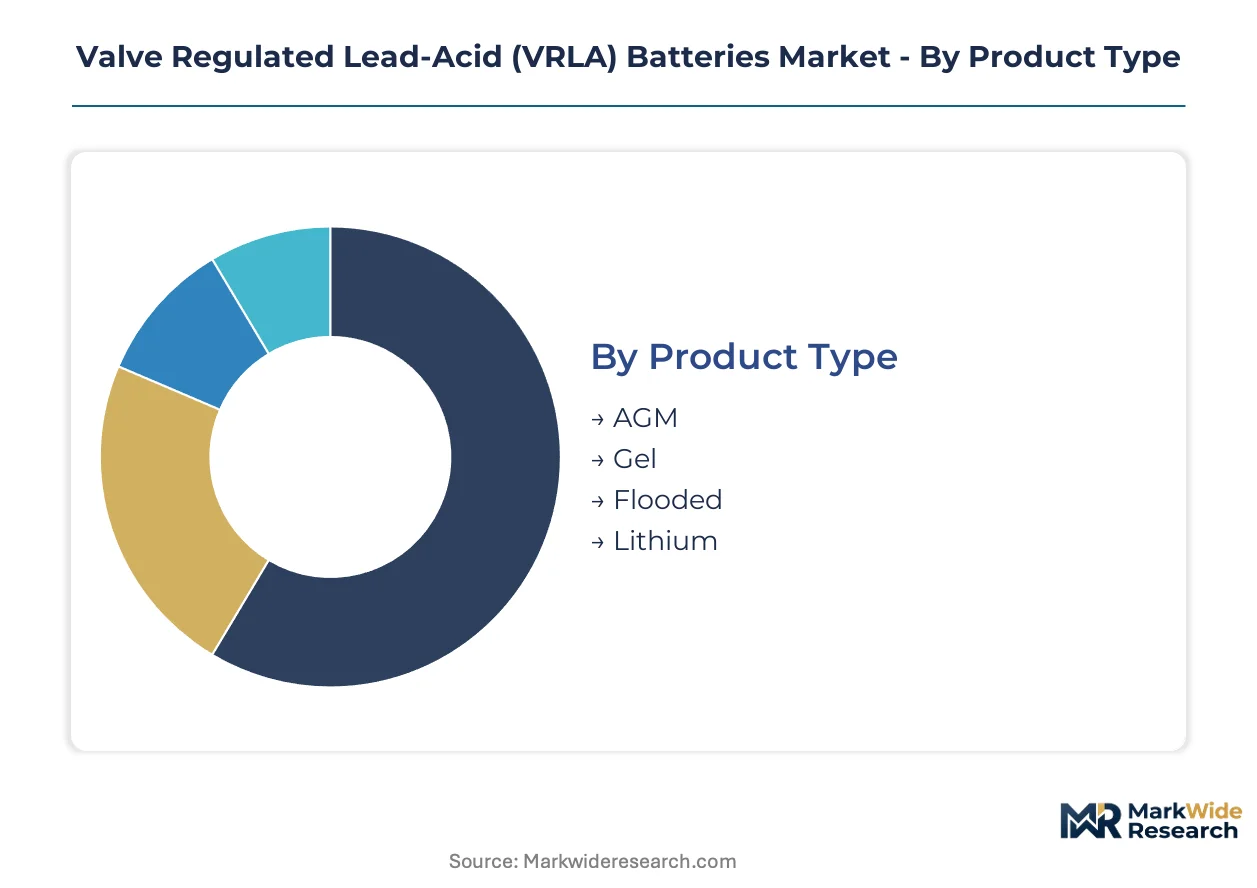
VRLA battery procurement patterns diverge sharply across product architectures and deployment scales. Supply chain configuration and end-use reliability requirements determine which segments command premium pricing versus commodity positioning.
Product Type:
Separator chemistry and electrolyte immobilization methods concentrate manufacturing capability among specialized glass-mat producers and gel-formulation specialists.
- AGM:Absorbed glass mat construction uses microfiber silica separators to wick electrolyte, enabling high-rate discharge with minimal internal resistance. Datacenter UPS installations in Mumbai and Chennai specify AGM for their 15-minute backup windows, though lead price volatility squeezes assembler margins on standard telecom cells.
- Gel:Thixotropic silica additives immobilize sulfuric acid, eliminating stratification and extending cycle life in elevated temperatures. Off-grid solar microgrids across Rajasthan and Tamil Nadu deploy gel variants where maintenance access is limited and ambient temperatures exceed 40°C.
- Flooded:Conventional liquid electrolyte design requires periodic watering and ventilation, constraining deployment to accessible industrial sites with active maintenance protocols.
- Lithium:Iron phosphate chemistry encroaches on sub-50 kWh VRLA applications through superior energy density and cycle tolerance, though thermal runaway risks and BMS complexity limit adoption in legacy telecom infrastructure.
Today's leader: AGM. Tomorrow's challenger: Gel.
End User:
Customer procurement sophistication separates specification-driven buyers from price-sensitive volume purchasers.
- Telecom:Tower operators in India and Indonesia bundle cell procurement with closed-loop recycling contracts, prioritizing environmental compliance scoring over unit cost in vendor algorithms.
- UPS:Datacenter operators running legacy three-phase architectures face float voltage incompatibility when retrofitting with modern AGM cells, creating aftermarket service opportunities for voltage-matched replacement designs.
- Renewable Energy:Deep-cycle duty profiles in solar-wind hybrid installations favor gel-electrolyte tolerance, with Chinese GB/T 19638.2-2018 cycle-life mandates forcing paste recipe reformulation for SAMR certification.
- Automotive:Start-stop auxiliary batteries and EV 12V support systems draw VRLA for cost-sensitive applications, though lithium substitution accelerates in premium vehicle segments.
Telecom towers anchor current volume. Renewable energy storage climbs the fastest.
Application:
Runtime duration and depth-of-discharge requirements segment the market into float-dominant versus cyclic-duty categories.
- Backup Power:Uninterruptible supply for critical infrastructure demands 10-20 year float life with minimal maintenance, favoring AGM in datacenter and healthcare installations.
- Renewable Energy Storage:Daily cycling tolerance determines competitive viability, with gel variants penetrating African and Latin American off-grid markets where ambient degradation stresses standard designs.
- Electric Vehicles:Auxiliary 12V systems and low-speed electric mobility represent residual VRLA strongholds as lithium-ion captures traction battery volumes.
- Marine:Custom large-format configurations with enhanced vibration resistance retain pricing power in commercial shipping and naval applications.
Backup power dominates installed base. Renewable energy storage offers steepest expansion trajectory.
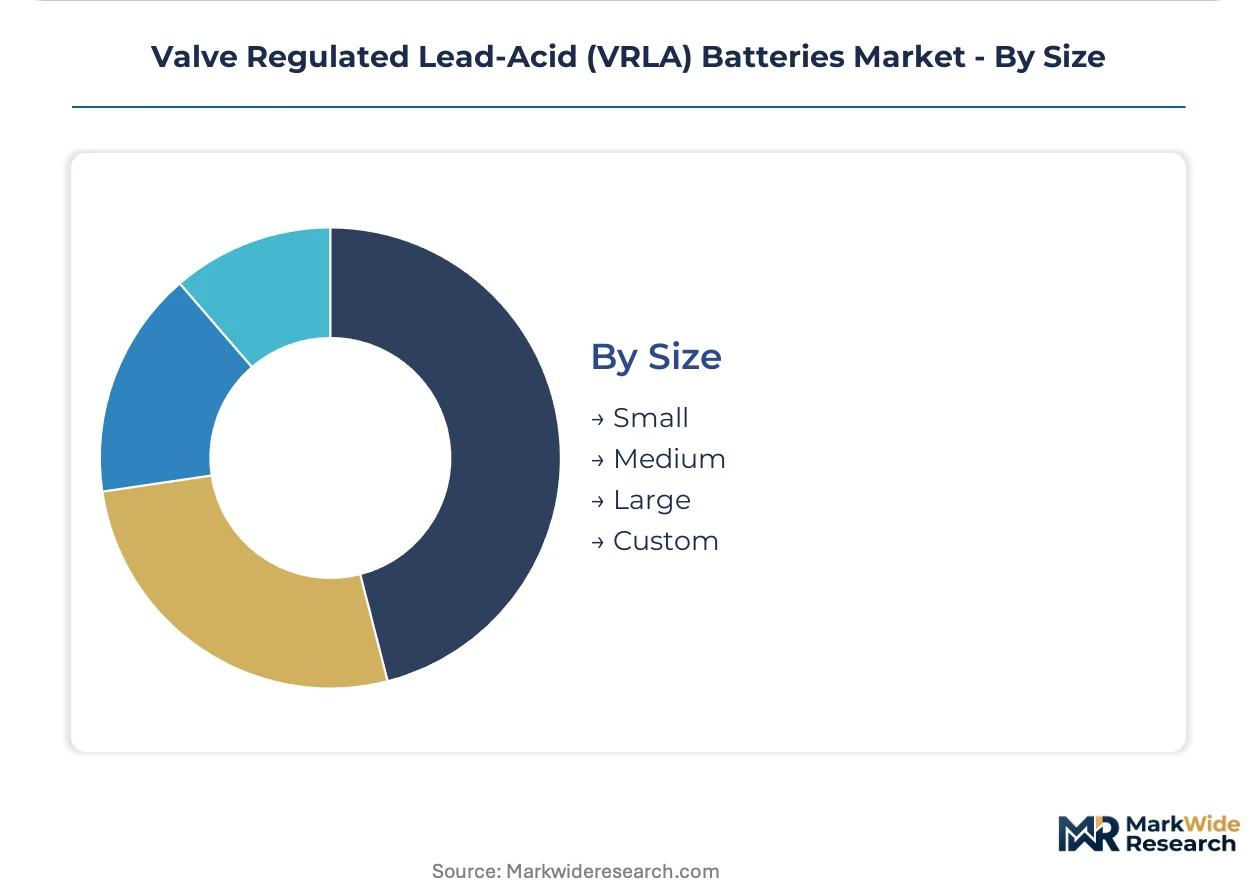
Size:
Manufacturing scale economies and customization intensity inversely correlate across the size spectrum.
- Small:Standardized 6V and 12V monobloc cells face margin compression from lithium-ion substitution in portable and residential applications.
- Medium:Rack-mounted 2V single cells balance volume production with configuration flexibility for telecom and small commercial UPS.
- Large:Industrial 2V cells above 1000 Ah capacity serve utility-scale and marine markets where custom terminal configurations and seismic bracing justify premium pricing.
- Custom:Engineered solutions with modified grid alloys, terminal positions, and case dimensions capture value in retrofit compatibility and extreme environment certification.
Medium formats drive volume economics. Custom configurations defend margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smelting dominance contrasts with India's demand surge as grid instability accelerates VRLA procurement across emerging economies. Regulatory divergence between carbon border regimes and domestic content mandates is fragmenting regional supply strategies. Datacenter clusters in Mumbai and Chennai anchor Asia-Pacific installation volumes.
China
Dual carbon targets and MEE emissions standards are pressuring manufacturers toward cleaner pyrometallurgical processes. SAMR enforces GB/T 19638 national standards that restrict mercury content and mandate cycle-life testing. The Yangtze River Delta concentrates AGM production capacity serving both domestic telecom towers and export markets.
India
Telecom tower operators across Maharashtra and Tamil Nadu are expanding backup installations as diesel generator bans tighten in urban corridors. BIS mandates IS 15549 performance standards for stationary cells used in telecom infrastructure. The PLI scheme for advanced chemistry cells offers production-linked incentives to VRLA suppliers meeting domestic value-add thresholds.
United States
Datacenter operators in Northern Virginia and Phoenix are retrofitting legacy UPS architectures with voltage-matched AGM replacements. EPA RCRA hazardous waste protocols govern lead smelting emissions and spent battery recycling. Clarios leverages its North American service network to bundle predictive analytics with cell replacements.
Germany
Pyrometallurgical refiners are capturing end-of-life EV auxiliary battery streams for VRLA feedstock under REACH compliance frameworks. ECHA substance restrictions grant preferential access to OEM supply chains for certified recyclers. Industrial clusters in North Rhine-Westphalia anchor closed-loop lead recovery operations.
Indonesia
Tower operators are consolidating supplier relationships around integrated recycling contracts that bundle procurement with guaranteed buyback of spent units. The country's national environmental regulator enforces hazardous waste protocols for lead-acid battery handling. Procurement frameworks for major telecom providers now specify closed-loop lead recovery as a contract prerequisite.
Valve Regulated Lead-Acid (VRLA) Batteries Market Competitive Landscape
Top-tier vendors anchor premium service tiers, while mid-scale assemblers compete on volume throughput for standardized telecom cells. The market structure concentrates around three strategic archetypes: integrated recyclers with captive smelting capacity, regional volume producers serving tower operators, and technology licensors monetizing separator formulations. Competitive moves center on backward integration into lead recovery and geographic expansion through local assembly partnerships.
Within the integrated recycler tier, Clarios and EnerSys exemplify archetypes that combine manufacturing with captive recycling infrastructure. Leoch International Technology occupies a position among Asia-Pacific volume specialists. These three anchors represent distinct competitive vectors: service-network bundling, cost control through upstream recovery, and high-volume production for price-sensitive emerging markets.
| Leading Market Players |
|---|
| Clarios |
| C&D Technologies |
| EnerSys |
| Saft Groupe |
| Leoch International Technology |
| Exide Technologies |
| East Penn Manufacturing |
| Tianneng Holding Group |
| GS Yuasa Corporation |
| Others |
Value Network & Pricing Analysis
Captive recycling infrastructure anchors pricing power for integrated VRLA manufacturers, allowing Clarios and EnerSys to offset LME lead volatility through in-house smelting while telecom buyers face compressed margins on spot-market cells.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard AGM cells serving Asian telecom towers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales bundling. Pricing pressure stems from lithium iron phosphate substitution in sub-50 kWh applications, eroding VRLA share in forklift and residential solar. Tower operators in India and Indonesia exhibit highest price sensitivity through consolidated procurement auctions, while datacenter operators in Northern Virginia and Phoenix accept premium tiers for voltage-matched retrofit compatibility.
Supply Chain Analysis
SAMR GB/T 19638 certification gates access to Chinese domestic procurement, forcing exporters to reformulate paste recipes and separator compression ratios. Primary lead refining concentrates in China, South Korea, and Germany, drawing from mined concentrates and end-of-life battery streams. Supply chain risk centers on export quota exposure from Chinese smelting dominance, with non-Chinese assemblers facing carbon border adjustment vulnerability. Distribution runs through regional battery distributors serving telecom infrastructure and datacenter channels, with integrated vendors bypassing wholesale tiers through direct service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in captive recycling economics and premium-tier gel variants for elevated-temperature deployments, as lead input cost control separates integrated incumbents from price-taking assemblers.
For Market Incumbents: To counter lithium iron phosphate displacement in sub-50 kWh applications, deepen backward integration into secondary lead recovery and expand voltage-matched retrofit product lines for legacy UPS architectures. Clarios-style predictive analytics bundling and EnerSys-style captive smelting infrastructure represent defensible moats against commodity margin compression. For New Entrants and Emerging Players: Launch via closed-loop recycling contracts targeting Indonesian and Philippine tower operators where environmental compliance scoring outweighs unit price in vendor selection algorithms. White-space opportunity sits in gel-electrolyte variants for African and Latin American off-grid solar microgrids, with carbon-coated lead-calcium grid alloys enabling warranty extension premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where regional assemblers lack captive recycling infrastructure and face sustained LME lead volatility. Long-term viability favors integrated recyclers with pyrometallurgical capacity in Germany or South Korea, capturing end-of-life EV auxiliary battery streams. Signal to watch: BIS IS 15549 enforcement intensity in India's Maharashtra and Tamil Nadu corridors as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Lead Recovery | Captive smelting insulates margins from LME volatility and Chinese export quota risk. |
| Gel-Electrolyte Capacity Expansion for High-Temperature Markets | Carbon-coated grid alloys extend cycle life in Rajasthan and Tamil Nadu solar deployments. |
| Predictive Health Monitoring Platform Launch | Subscription revenue streams reposition Clarios-style vendors from hardware to uptime guarantees. |
| Closed-Loop Recycling Contract Proliferation | Reliance Jio and Bharti Airtel procurement frameworks now mandate guaranteed buyback terms. |
| Voltage-Matched Retrofit Product Line Development | Legacy UPS compatibility gaps in Northern Virginia datacenters create aftermarket service premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with telecom tower procurement managers, datacenter operations directors, lead smelter technical leads, and AGM separator manufacturing specialists with secondary validation through BIS certification records, SAMR GB/T 19638 filings, EPA RCRA enforcement data, and customs trade statistics for lead concentrate imports. Bottom-up cell shipment estimates by application and top-down smelting capacity analysis triangulated to cross-check volume assumptions.
Segment-weighting approaches distributed value across product architecture, end-user vertical, and regional regulatory cluster dimensions over the projection horizon. CAGRs derived from fitted growth curves incorporating telecom infrastructure buildout rates, datacenter UPS replacement cycles, and renewable energy storage penetration by climate zone. Industry-specific inputs included LME lead futures volatility bands, diesel generator ban enforcement timelines in Indian states, and PLI scheme domestic value-add thresholds.
Several conditions sit outside the modeled scope, including abrupt lithium iron phosphate cost breakthroughs below VRLA parity, unilateral Chinese lead export restrictions, and force majeure disruptions to Yangtze River Delta manufacturing. Forecasts reflect documented assumptions on grid reliability trends and smelter emissions compliance capital requirements. A model refresh is warranted upon material change in India's PLI scheme eligibility criteria or MEE air quality standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Lead-Acid Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Battery Separators Market
Batteries
Alkaline Secondary Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Forklift Battery Rental Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Printable Battery Market
Batteries
Redox Flow Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Drone Power Sources Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
West Africa Battery Market
Batteries
Smart Battery Charger Market