
 Thin Film Battery Market | 2026-2036
Thin Film Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Battery Market Analysis
Multi-source sourcing for solid-state electrolyte materials is pivoting toward vertically integrated supply networks. Blue Spark Technologies leverages captive thin-film deposition capacity to control cost structures. Samsung SDI Co., Ltd. anchors its position through R&D intensity in laser structuring processes. Ilika plc specializes in solid-state cell architectures for medical-grade applications.
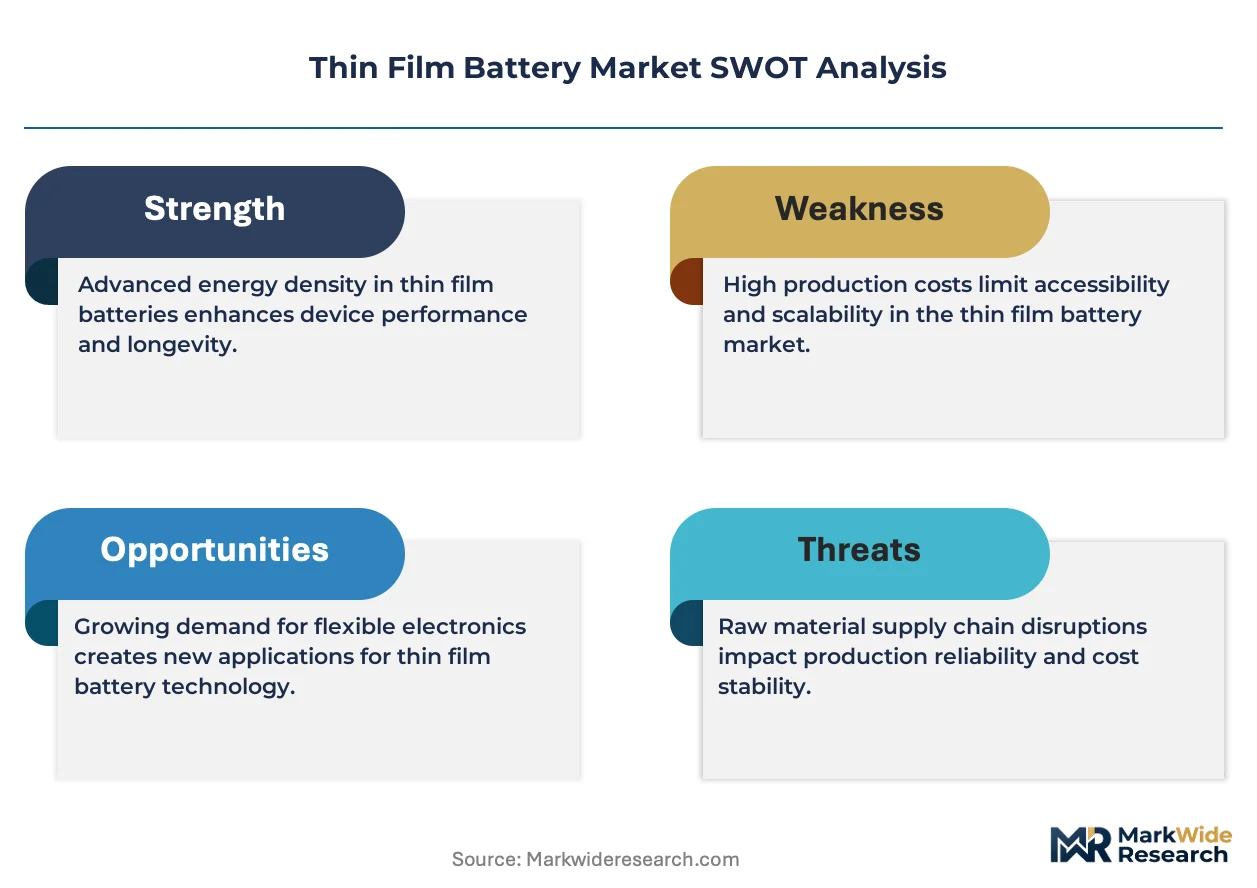
Thin film batteries are electrochemical energy storage devices fabricated through vacuum deposition or printing processes, typically achieving thicknesses below 0.5 millimeters with flexible substrate compatibility. They deliver microwatt-to-milliwatt power for devices where conventional cylindrical or pouch cells prove dimensionally incompatible. Solid-state product types occupy the premium tier due to enhanced safety profiles and wider temperature operating ranges. Wearable technology applications represent the fastest-expanding demand pool, driven by skin-patch monitors and flexible displays requiring conformal power sources. Thin film deposition technology dominates manufacturing investment, though inkjet printing is gaining traction for rapid prototyping and customized form factors.
FDA medical device regulations and EU Battery Directive sustainability mandates shape product certification pathways and material disclosure requirements for thin film battery suppliers. REACH restrictions on hazardous substances constrain electrolyte formulation choices, particularly for European market access. Stakeholders must monitor solid-state manufacturing yield improvements and regulatory harmonization between medical and consumer electronics safety standards to align capacity planning with addressable demand expansion.
Market Dynamics
Solid-state electrolyte manufacturing yield improvements are compressing unit economics while REACH compliance mandates force electrolyte reformulation across European supply chains. Laser structuring investments in South Korea's electronics corridor concentrate high-value production capacity.
Growth Catalysts
- Wearable medical monitors:Skin-patch glucose trackers and cardiac rhythm monitors require conformal power sources that cylindrical cells cannot provide. FDA 510(k) pathways for these devices accelerate supplier qualification timelines.
- REACH substance restrictions:ECHA's evolving candidate list pressures electrolyte suppliers to eliminate restricted solvents. Reformulation investments unlock European market access for compliant architectures.
- Flexible display integration:Foldable smartphone and e-reader manufacturers specify sub-millimeter power cells. South Korean display fabs source locally deposited thin-film stacks to match panel curvature specifications.
Market Restraints
- Lithium metal foil supply:Ultra-thin lithium anode production concentrates among Japanese and South Korean specialty metallurgy houses. Spot price volatility for 20-micron foil disrupts cost modeling for solid-state designs.
- Vacuum deposition capex:Roll-to-roll sputtering and evaporation systems require cleanroom infrastructure exceeding $50 million per line. Equipment lead times from German and Japanese vendors extend 18-24 months.
- Silicon anode competition:Conventional pouch cells with silicon-graphite composite anodes achieve comparable volumetric energy density at lower cost. Consumer electronics OEMs benchmark thin-film premiums against these advancing alternatives.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for wearables and hearables create demand for localized battery assembly. CDSCO medical device registration reforms enable direct market entry for skin-patch therapeutics.
- Solid-state electrolyte-polymer substrate convergence:Printable ceramic-polymer composites enable ambient processing without vacuum infrastructure. This process shift opens contract manufacturing partnerships with flexible PCB fabricators.
- EU Battery Directive sustainability mandates:Digital battery passports and recycled content thresholds favor thin-film architectures with simpler material recovery profiles. European medical OEMs prioritize suppliers with disclosed supply chain carbon footprints.
Industry Challenges
- Cross-trained process engineers:Vacuum deposition expertise overlaps insufficiently with medical device quality systems. Hiring competition from semiconductor and OLED display sectors elevates compensation premiums.
- FDA-EU MDR dual certification:Divergent biocompatibility testing protocols for implantable versus skin-contact applications extend validation timelines. Parallel track submissions require redundant clinical evidence packages.
- Legacy equipment integration:Thin-film cell voltage profiles and termination geometries differ from conventional lithium-ion standards. Wearable OEMs redesign power management ICs and charging subsystems to accommodate these electrical characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Battery Market |
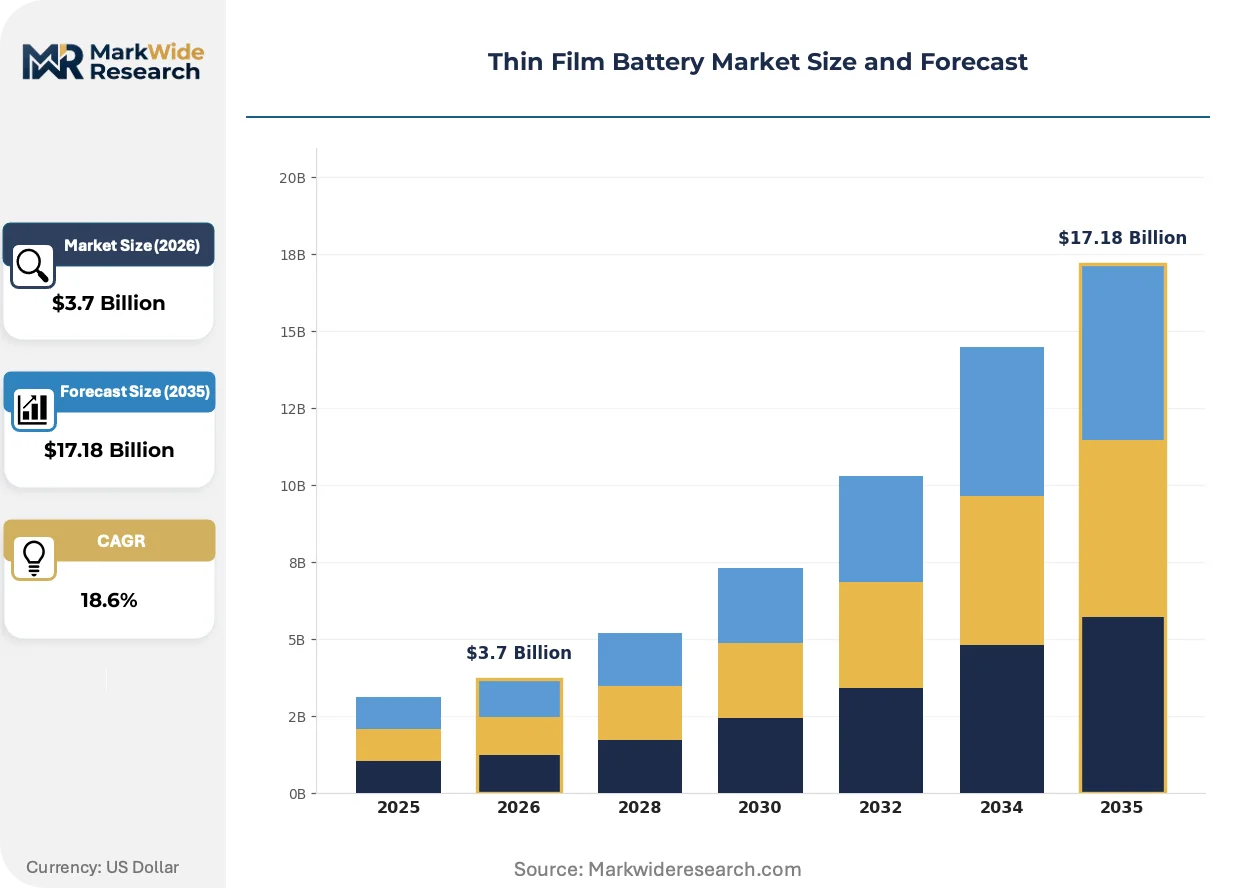
| Market Size in 2026 | $3.7 Billion |
| Market Size in 2035 | $17.18 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Polymer, Solid State, Hybrid, Micro Battery Application: Consumer Electronics, Medical Devices, Wearable Technology, Renewable Energy End User: Manufacturers, OEMs, Research Institutions, Retailers Technology: Thin Film Deposition, Coating Techniques, Laser Structuring, Inkjet Printing |
| Companies Covered | Blue Spark Technologies, Enfucell Oy, STMicroelectronics, LG Chem, Samsung SDI Co., Ltd., Cymbet Corporation, BrightVolt Solid State Batteries, Ilika plc, Jenax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Battery Market Emerging Trajectories
Deposition technology diversification and regulatory material restrictions are forcing parallel innovation across process chemistry and manufacturing equipment. Suppliers compete on thermal budget reduction and substrate flexibility rather than energy density alone.
Sputtered lithium phosphorus oxynitride (LiPON) solid-state electrolytes enable ambient-temperature operation without flammable liquid components. Medical implant manufacturers specify these architectures for neurostimulators and drug delivery pumps where thermal runaway risks are unacceptable. The technology is expanding into consumer hearables as brands differentiate on safety credentials.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) threaten fluorinated electrolyte salts used in high-voltage thin-film designs. Battery suppliers accelerate sulfide-based and oxide-based solid electrolyte development to maintain European market access. Medical-grade product lines face the steepest formulation deadlines due to MDR substance disclosure requirements.
Contract deposition houses in Taiwan and South Korea now offer rapid prototyping services with 48-hour turnaround on custom form factors. Wearable startups bypass captive manufacturing investments by accessing these shared pilot lines. This channel shift concentrates design activity near display and sensor ecosystem clusters while dispersing eventual high-volume production across multiple qualified fabs.
Thin Film Battery Market Segmentation
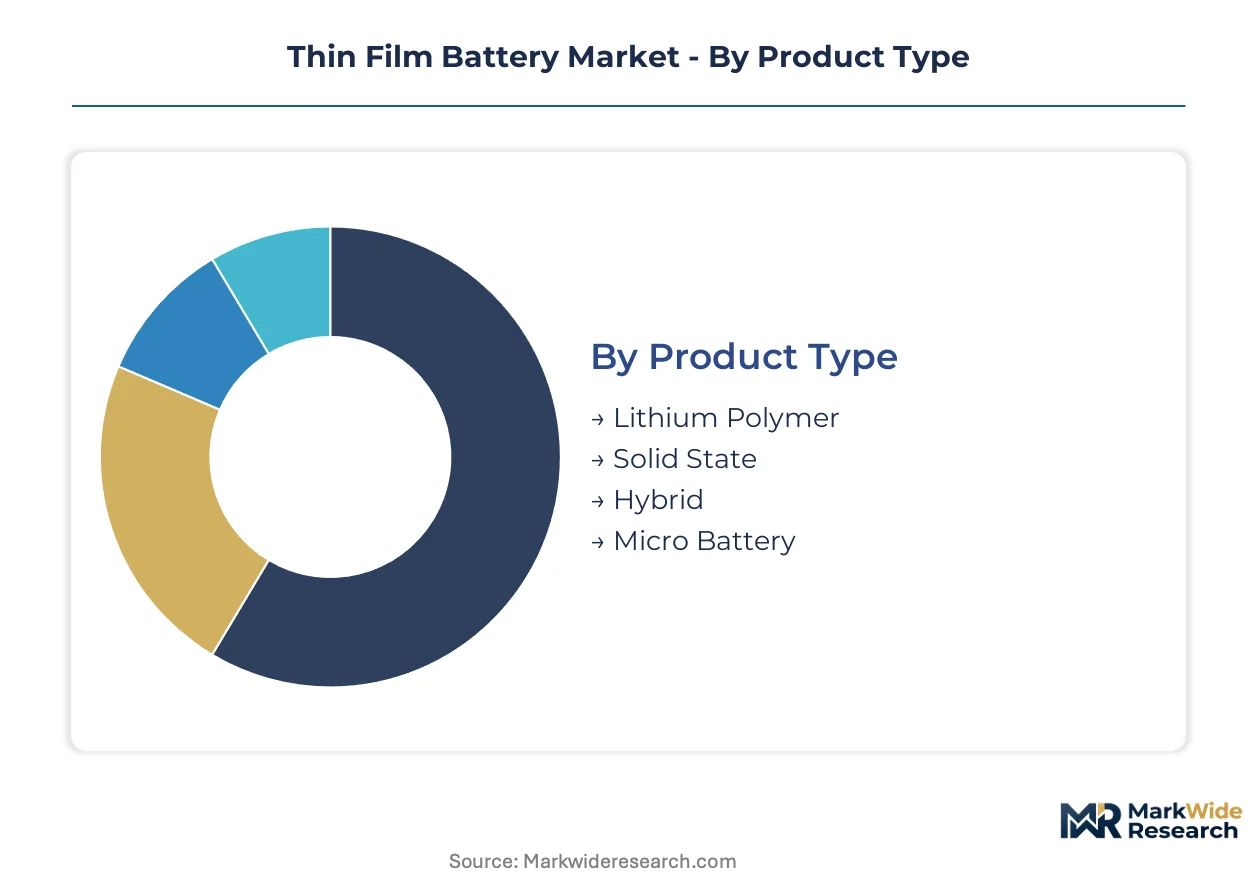
Thin film battery procurement patterns diverge sharply between medical-grade certification requirements and consumer electronics cost optimization. Segmentation reveals where manufacturing complexity translates to pricing power versus commodity competition.
Product Type:
Standardization dominates at the cell chemistry level, yet customization proliferates in electrolyte formulation and substrate selection to match application thermal budgets.
- Solid State:Sputtered lithium phosphorus oxynitride electrolytes eliminate flammable liquid components. Medical implant manufacturers in Switzerland and Germany specify these architectures for neurostimulators where thermal runaway risks are unacceptable. FDA 510(k) pathways for implantable devices accelerate supplier qualification timelines for this chemistry.
- Lithium Polymer:Gel electrolyte systems achieve manufacturing scale through roll-to-roll coating processes. South Korean consumer electronics OEMs source locally deposited stacks for foldable smartphone integration where sub-millimeter thickness proves mandatory.
- Hybrid:Combines solid-state safety with polymer processability for hearable applications.
- Micro Battery:Sub-square-centimeter footprints target sensor nodes and RFID tags.
Most installed capacity flows through Lithium Polymer. Expansion is steepest in Solid State.
Application:
Volume concentration sits with high-unit consumer electronics, yet margin capture favors regulated medical pathways where certification creates supplier stickiness.
- Wearable Technology:Skin-patch glucose trackers and cardiac rhythm monitors require conformal power sources that cylindrical cells cannot provide. South Korean display fabs and Massachusetts-based medical device startups drive specification convergence around sub-0.3mm thickness targets.
- Medical Devices:Implantable neurostimulators and drug delivery pumps demand hermetic sealing and biocompatibility certification. EU MDR substance disclosure requirements and FDA biocompatibility testing protocols extend validation timelines but lock in multi-year supply agreements.
- Consumer Electronics:Foldable smartphones and e-readers specify flexible power cells matched to panel curvature.
- Renewable Energy:Micro-energy harvesting for distributed sensors in solar and wind installations.
Certification intensity peaks in Medical Devices. Commercial volume concentrates in Wearable Technology.
End User:
Procurement sophistication varies from captive manufacturing investments by scale OEMs to outsourced pilot production by venture-backed startups.
- OEMs:Samsung SDI and Blue Spark Technologies maintain captive thin-film deposition capacity to control cost structures and protect formulation intellectual property. Internal quality systems align with FDA and EU MDR requirements for direct device integration.
- Manufacturers:Contract deposition houses in Taiwan and South Korea offer rapid prototyping with 48-hour turnaround on custom form factors. Wearable startups bypass capital investments by accessing shared pilot lines near display ecosystem clusters.
- Research Institutions:University labs and national laboratories advance solid-state electrolyte materials.
- Retailers:Specialized distributors serve hobbyist and prototyping markets with standard form factors.
Technology leadership resides with OEMs. Flexibility is greatest among Manufacturers.
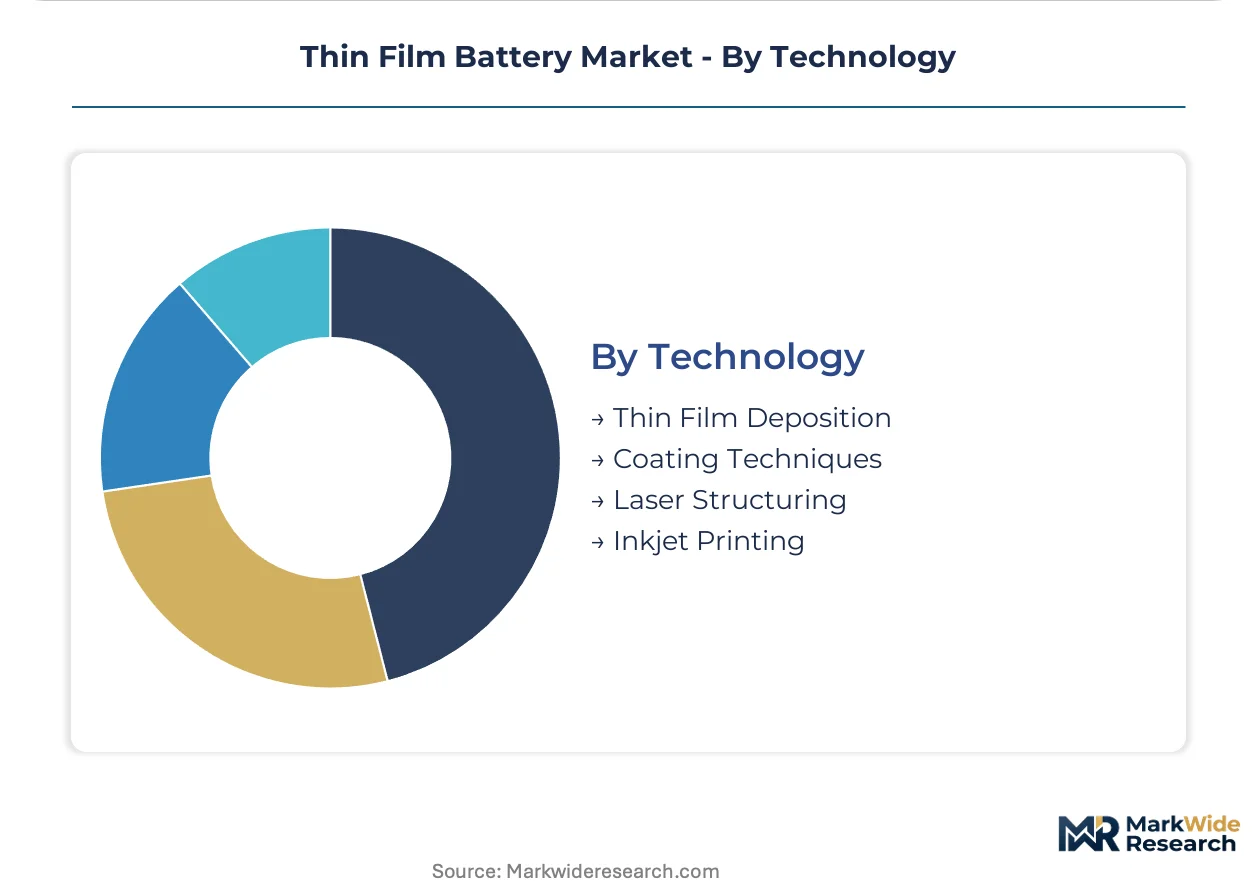
Technology:
Capital intensity separates vacuum-based processes from ambient printing approaches, with equipment selection determining substrate compatibility and throughput economics.
- Thin Film Deposition:Roll-to-roll sputtering and evaporation systems require cleanroom infrastructure exceeding $50 million per line. German and Japanese equipment vendors command 18-24 month lead times. South Korean electronics corridors concentrate this high-value production capacity.
- Laser Structuring:Precision ablation enables three-dimensional cell architectures without photolithography. Samsung SDI anchors competitive positioning through R&D intensity in this process for medical-grade solid-state designs.
- Inkjet Printing:Rapid prototyping and customized form factors gain traction for pilot production.
- Coating Techniques:Slot-die and gravure methods serve polymer electrolyte applications.
Production scale concentrates in Thin Film Deposition. Process innovation is accelerating in Laser Structuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's electronics manufacturing corridor concentrates thin-film battery demand through display and semiconductor integration. FDA and EU MDR certification requirements shape supplier qualification pathways across medical and consumer segments. Regional procurement patterns reflect proximity to flexible electronics fabrication clusters.
South Korea
Samsung SDI anchors domestic demand through captive deposition capacity for foldable smartphone integration. The Ministry of Trade, Industry and Energy (METI-aligned standards via KATS) enforces battery safety certifications for consumer electronics. Gyeonggi-do province hosts concentrated roll-to-roll sputtering infrastructure serving Seoul Capital Area display fabs.
United States
Massachusetts-based medical device startups and California wearables OEMs drive specification convergence around sub-millimeter thickness targets. FDA 510(k) pathways for skin-patch glucose trackers compress supplier qualification timelines. Greater Boston clusters neurostimulator manufacturers sourcing solid-state architectures for implantable applications.
Germany
Siemens Healthineers and regional medtech SMEs specify hermetic solid-state cells for drug delivery pumps. EU MDR substance disclosure requirements and ECHA REACH restrictions force electrolyte reformulation investments. Baden-Württemberg concentrates precision deposition equipment vendors serving Swiss and German implantable device manufacturers.
Japan
Ultra-thin lithium anode production concentrates among specialty metallurgy houses supplying 20-micron foil for solid-state designs. METI's battery technology roadmaps prioritize solid-state yield improvements. Tokyo-Osaka industrial corridor hosts vacuum deposition equipment vendors with 18-24 month order backlogs.
India
PLI scheme incentives for wearables and hearables create procurement pull for localized battery assembly. CDSCO medical device registration reforms enable direct market entry for skin-patch therapeutics. Karnataka and Tamil Nadu electronics manufacturing zones attract contract deposition partnerships with flexible PCB fabricators.
Thin Film Battery Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state specialization and medical-grade certification. The vendor base stratifies across three tiers: integrated electronics conglomerates with captive capacity, independent thin-film specialists, and contract deposition houses serving prototyping demand. Two strategic archetypes dominate—vertically integrated OEMs controlling formulation IP and regional contract manufacturers offering rapid turnaround. Capacity expansion and strategic partnerships constitute the primary competitive moves, with equipment co-development agreements reducing cleanroom infrastructure barriers.
Within the integrated tier, Samsung SDI Co., Ltd. and LG Chem exemplify scale-driven positioning through in-house deposition capacity. Blue Spark Technologies and Ilika plc occupy specialist positions—Blue Spark through captive manufacturing control, Ilika through solid-state architecture focus for regulated medical pathways. These four entities represent distinct competitive vectors: Korean conglomerate scale, American manufacturing control, and British medical-grade specialization.
| Leading Market Players |
|---|
| Blue Spark Technologies |
| Enfucell Oy |
| STMicroelectronics |
| LG Chem |
| Samsung SDI Co., Ltd. |
| Cymbet Corporation |
| BrightVolt Solid State Batteries |
| Ilika plc |
| Jenax Inc. |
| Others |
Supply Flow & Price Mechanics
Ultra-thin lithium metal foil costs cascade from Japanese and South Korean specialty metallurgy houses through three distinct pricing tiers for solid-state designs, with 20-micron spot volatility compressing margins at the premium medical-grade tier while contract offtake agreements stabilize mid-tier consumer electronics procurement.
Pricing Analysis
Input-cost pass-through from lithium foil and vacuum deposition equipment governs thin film battery economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified implantable cells from consumer hearables and commodity sensor tags. Price differentiation hinges on certification grade and volume scale, with REACH-compliant electrolyte reformulation adding cost premiums for European market access. Cost compression in the standard tier is intensifying because silicon-graphite pouch alternatives narrow the energy density gap. Consumer electronics OEMs exhibit highest price sensitivity, while medical device manufacturers accept premiums for hermetic solid-state architectures.
Supply Chain Analysis
Cross-trained process engineers with vacuum deposition expertise are scarce in South Korea's Gyeonggi-do corridor and Taiwan's Hsinchu Science Park, elevating compensation premiums and constraining capacity expansion timelines. Supply concentration rests on South Korea, Japan, and Taiwan for deposition equipment and specialty lithium foil. Raw material dependencies draw from ultra-thin lithium anodes, sputtered LiPON electrolytes, and flexible polymer substrates. Single-source vulnerability concentrates in German and Japanese vacuum equipment vendors with 18-24 month order backlogs. Distribution runs through captive OEM integration for scale demand and contract deposition houses for prototyping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thin film battery market functions as a regulatory compounder where EU Battery Directive sustainability mandates and FDA 510(k) pathway accelerations compound demand for certified solid-state architectures.
For Market Incumbents: Anticipate silicon-graphite pouch cell advances by deepening laser structuring R&D intensity and locking multi-year supply agreements with South Korean display fabs. Anchor competitive positioning through captive electrolyte formulation IP and backward integration into thin-film deposition capacity. Prioritize dual FDA-EU MDR certification investments to defend margin position against emerging solid-state specialists. For New Entrants and Emerging Players: E-commerce-enabled rapid prototyping platforms offer lowest-friction entry into wearable startup procurement workflows. Target India's PLI-subsidized wearables assembly and CDSCO-reformed medical device registration as the most penetrable white-space geography. Pursue contract manufacturing partnerships with flexible PCB fabricators to bypass vacuum infrastructure capex barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where solid-state electrolyte yield improvements compress unit economics below standalone viability thresholds for thin-film specialists. Frame long-term viability around medical-grade certification stickiness and display ecosystem integration depth. Monitor solid-state manufacturing yield inflection as the primary signal for capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Materials | Captive LiPON sputtering capacity insulates Blue Spark Technologies from ECHA reformulation mandates. |
| Laser Structuring R&D Intensity | Samsung SDI anchors competitive positioning through precision ablation for medical-grade solid-state designs. |
| Contract Deposition Partnerships | Taiwanese rapid prototyping houses enable 48-hour turnaround for wearable startups near display clusters. |
| FDA-EU MDR Dual Certification | Hermetic sealing validation unlocks multi-year supply agreements with Swiss neurostimulator manufacturers. |
| India PLI Localization | Karnataka electronics zones attract battery assembly partnerships for hearables and skin-patch therapeutics. |
Methodological Framework
Multiple input streams — deposition equipment vendor order books, medical device 510(k) filing trajectories, and REACH compliance disclosure databases — were reconciled against primary interviews with thin-film process engineers, biomedical device procurement managers, and flexible display supply chain directors. Secondary validation drew from SEC filings of listed battery specialists, Korean Ministry of Trade battery safety certifications, and Swissmedic implantable device registrations. Bottom-up cell shipment estimates and top-down electronics bill-of-materials analysis were triangulated to anchor volume projections.
Historical capacity expansion patterns were cross-referenced against expert panel inputs on solid-state yield improvement timelines across the projection horizon. Segmentation modeling spanned product type chemistry tiers, application certification intensity, end-user captive versus outsourced procurement, and technology capital intensity. CAGRs were derived from installed capacity ramp schedules and substitution elasticity estimates for silicon-graphite alternatives. Industry-specific forecast inputs included laser structuring throughput improvements and EU Battery Directive recycled content threshold phase-ins.
The model assumes a particular technology adoption path; alternative pathways for printable ceramic-polymer composites would alter the outlook if ambient processing displaces vacuum infrastructure investment. Forecasts reflect assumptions on REACH substance restriction implementation timing and FDA review bandwidth for skin-patch device categories. Material deviation in solid-state electrolyte yield trajectories or lithium foil supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market