
 Europe Rechargeable Battery Market | 2026-2036
Europe Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rechargeable Battery Market Intelligence
Electric vehicle manufacturing is consolidating as the dominant demand vertical across European rechargeable battery offtake. Northvolt anchors its position through captive supply of sustainably sourced cathode materials at its Skellefteå and Borlänge sites. LG Energy Solution competes via manufacturing scale at its Wrocław complex, Poland's largest battery plant. Saft Groupe SA specializes in industrial and defense applications, leveraging its Bordeaux-based R&D to sustain technology leadership in nickel-based chemistries.
Europe rechargeable batteries are electrochemical storage devices designed for repeated charge-discharge cycles, typically employing lithium-ion cells with energy densities exceeding 250 Wh/kg for automotive-grade pouch and prismatic formats. Their primary commercial purpose lies in decarbonizing transport and grid infrastructure through reversible energy storage. Lithium-ion chemistry dominates product type segmentation due to superior cycle life and gravimetric performance, while lead acid retains cost advantages in uninterruptible power supply and forklift traction roles. Battery Management Systems technology represents a concentrated margin pool, as semiconductor-intensive monitoring and thermal regulation functions command premium pricing across electric vehicle and energy storage system applications.
The EU Green Deal, F-Gas Regulation, and REACH compliance framework collectively mandate recycled content thresholds and carbon footprint declarations for cells sold in the European Economic Area, reshaping supplier qualification criteria and factory siting decisions. EMA and national regulators in Germany, France, and Italy are converging on standardized safety testing protocols for stationary lithium-ion installations. Stakeholders must monitor how the EU AI Act and proposed Battery Regulation amendments will interact with existing CE marking requirements to determine which manufacturing locations and recycling partnerships qualify for market access.
Market Dynamics
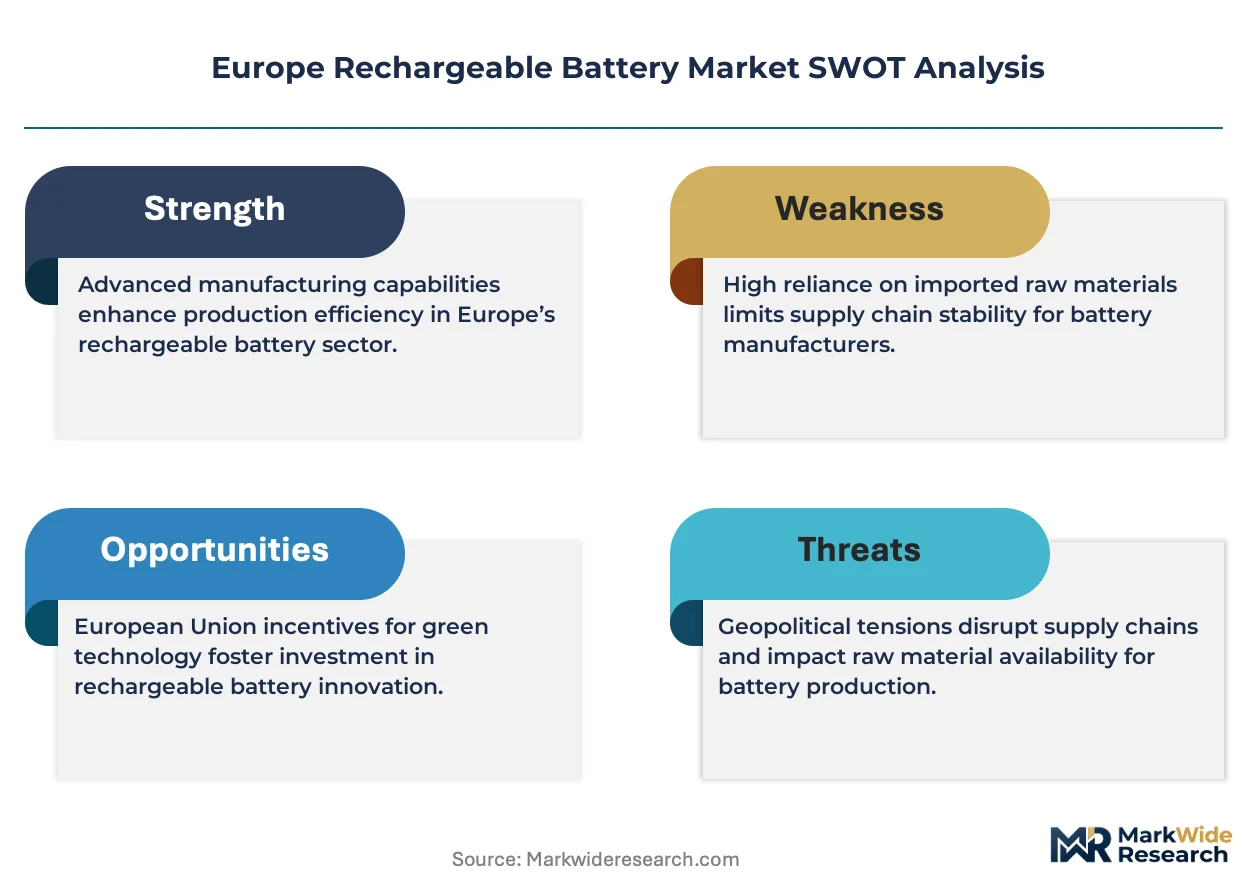
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are forcing cell manufacturers to reconfigure supply chains and factory siting decisions across the European Economic Area.
Growth Catalysts
- EU Green Deal transport electrification targets:Member states must achieve carbon neutrality by 2050, compelling fleet operators in Germany, France, and the Netherlands to accelerate lithium-ion procurement for electric buses and commercial vehicles.
- F-Gas Regulation phase-down:The hydrofluorocarbon reduction schedule is accelerating stationary energy storage deployments as thermal management systems shift toward battery-based cooling alternatives.
- Rhine corridor manufacturing cluster:Cell gigafactories and OEM assembly plants concentrate in Lower Saxony and Baden-Württemberg, creating dense supplier ecosystems that reduce logistics costs and qualification timelines.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs fluctuate with South American brine and Australian spodumene supply disruptions, compressing cathode producer margins and destabilizing long-term contract pricing.
- Single-source cathode precursor dependence:European cell manufacturers rely heavily on Chinese refining capacity for nickel sulfate and cobalt hydroxide, creating geopolitical exposure to export licensing restrictions.
- Energy density ceiling in LFP chemistry:Lithium iron phosphate cells face fundamental electrochemical limits below 200 Wh/kg, constraining their suitability for premium passenger electric vehicles requiring extended range.
Strategic Opportunities
- Polish manufacturing expansion:Lower Saxony-adjacent sites in Silesia and Lower Silesia offer cost-competitive labor pools and EU structural fund access for battery pack assembly operations.
- Second-life stationary storage:Retired electric vehicle battery packs from German automotive OEMs are repurposing into grid-scale energy storage systems, extending value capture across 10-15 year secondary cycles.
- REACH-compliant recycling infrastructure:The EU Battery Regulation's 2031 recycled content thresholds are incentivizing hydrometallurgical recycling investments in Belgium and Finland to recover lithium, nickel, and cobalt from black mass.
Industry Challenges
- Electrochemical engineer scarcity:Cell design and solid-state electrolyte R&D functions face acute talent shortages as universities struggle to scale specialized battery chemistry programs matching industrial demand.
- CE marking timeline compression:The EU AI Act's intersection with Battery Regulation amendments is creating uncertainty in conformity assessment procedures, delaying product launches for intelligent battery management systems.
- Legacy thermal runaway testing protocols:EMA and KBA safety standards for stationary lithium-ion installations remain partially harmonized, forcing manufacturers to run parallel qualification campaigns for German and French markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rechargeable Battery Market |
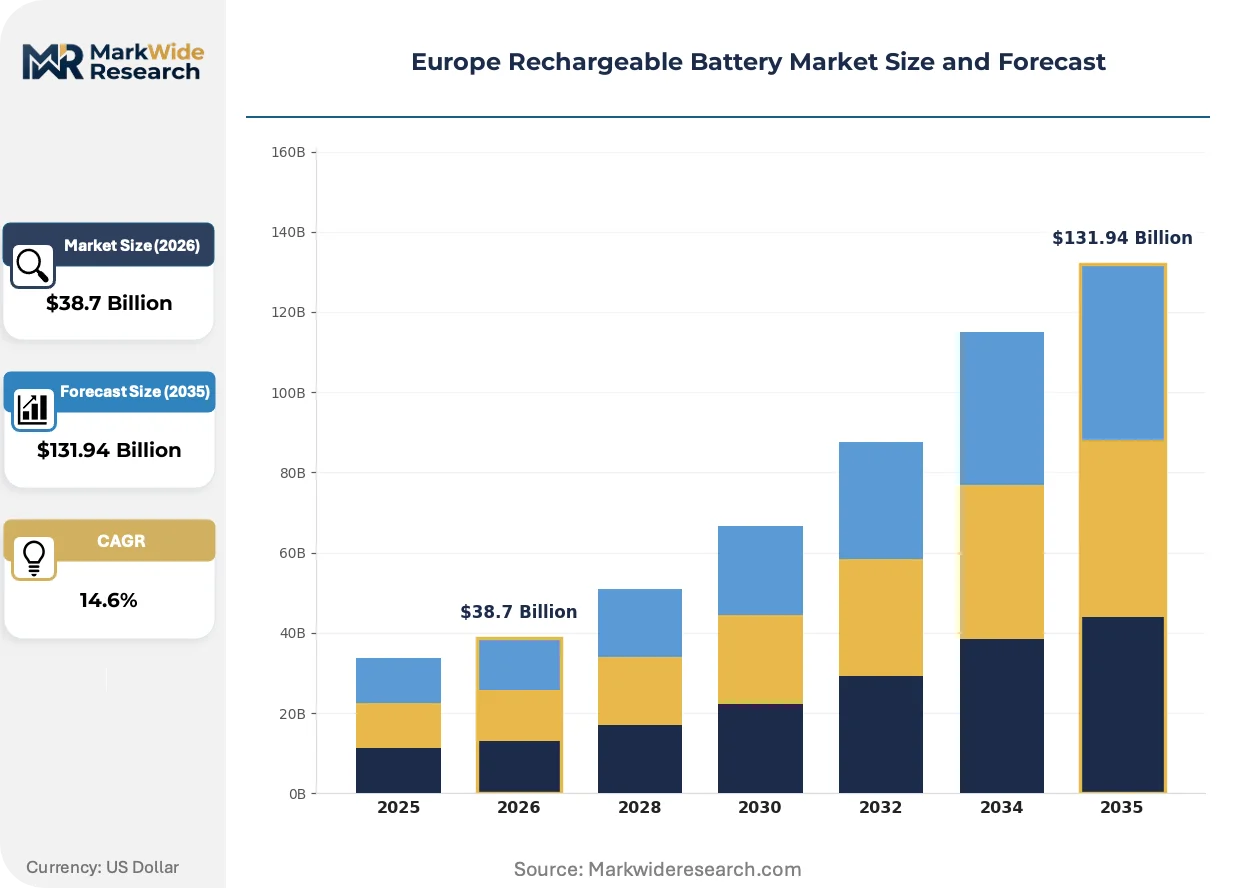
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Energy Storage Systems, Electric Vehicles, Power Tools, Portable Devices Technology: Fast Charging, Energy Density, Battery Management Systems, Recycling Technologies |
| Companies Covered | BYD Co. Ltd., Contemporary Amperex Technology Co. Ltd., Exide Industries, Panasonic Corporation, GS Yuasa Corporation, Northvolt, LG Energy Solution, Saft Groupe SA, Samsung SDI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rechargeable Battery Market Strategic Shifts & Innovations
Solid-state electrolyte development and silicon-anode integration are compressing the performance gap between laboratory prototypes and automotive-grade manufacturing, while regulatory pressure on supply chain transparency accelerates digital traceability adoption.
Silicon-dominant anode formulations are rewriting energy density benchmarks for European passenger electric vehicles. Automotive OEMs in Stuttgart and Munich are qualifying 400 Wh/kg prototype cells for 2027 model year integration. The technology is compressing cobalt dependence in premium vehicle segments while extending single-charge range thresholds.
REACH substance restriction amendments are tightening nickel and cobalt compound reporting obligations for cell importers. The ECHA regulatory expansion is forcing cathode active material suppliers to disclose full supply chain smelter and refiner identities. German battery manufacturers are responding by qualifying Finnish and Swedish mining sources to reduce due diligence burden.
Fleet operators are consolidating procurement through long-term offtake agreements rather than spot market purchases. Direct contracting between European logistics companies and cell manufacturers is displacing traditional distributor networks for heavy-duty electric truck batteries. The shift is most visible in the Netherlands, where Rotterdam port operators negotiate decade-spanning supply contracts indexed to renewable energy certificates.
Europe Rechargeable Battery Market Segmentation
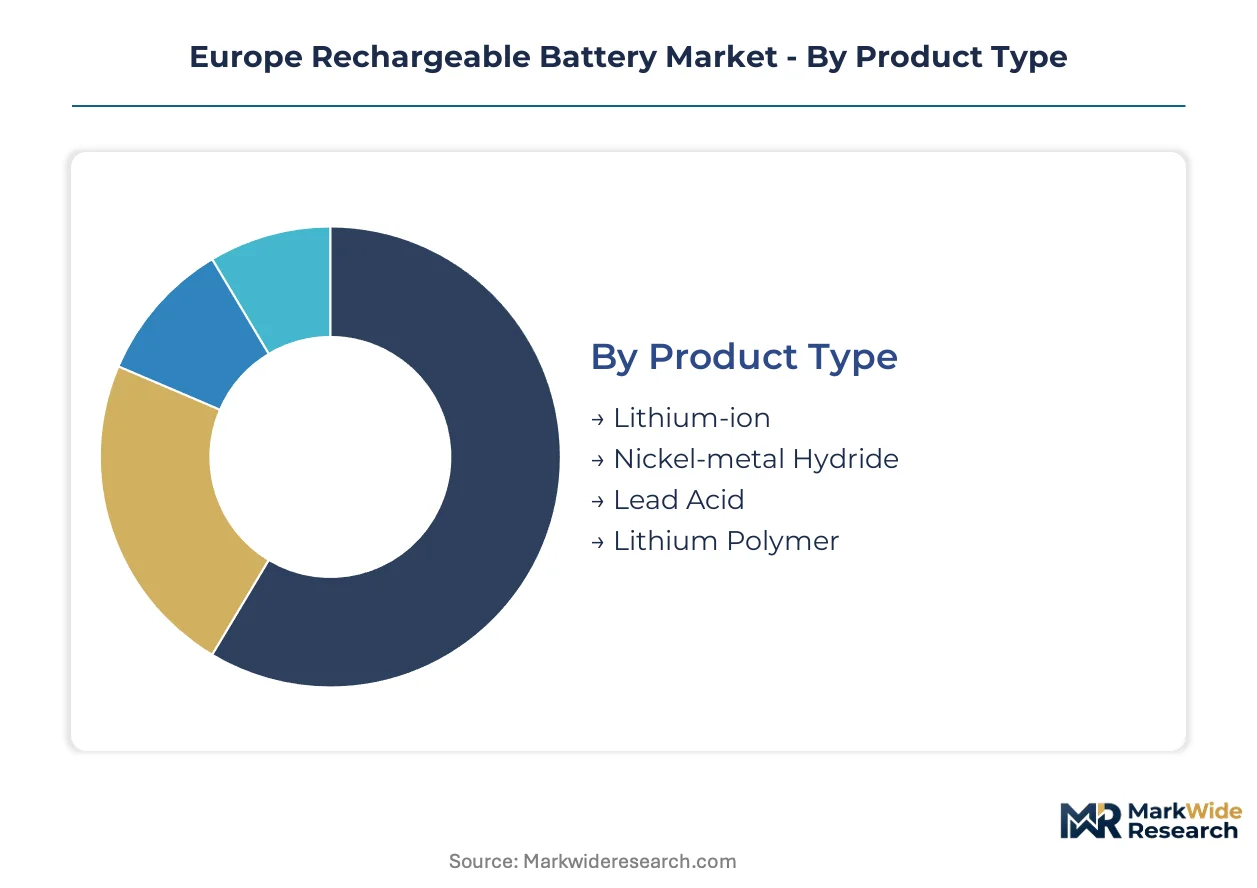
Segmentation in the Europe rechargeable battery market reveals how supply chain configuration and regulatory pressure concentrate value capture in specific chemistries and applications. Understanding these divisions enables manufacturers to align factory investments with the EU Battery Regulation's evolving compliance tiers.
Product Type:
Supply concentration in cathode precursor refining and cell gigafactory placement across Germany and Poland directly shapes competitive dynamics within each chemistry category.
- Lithium-ion:Pouch and prismatic formats employing nickel-manganese-cobalt or lithium iron phosphate cathodes achieve gravimetric energy densities above 250 Wh/kg. German automotive OEMs in Lower Saxony and Baden-Württemberg are scaling procurement for electric vehicle platforms as the EU Green Deal tightens fleet emission standards.
- Nickel-metal Hydride:Rare-earth alloy hydride anodes paired with nickel oxyhydroxide cathodes deliver moderate energy density with superior cycle stability in temperature extremes. Toyota's hybrid manufacturing presence in France and the UK sustains residual demand even as full electrification shifts volume toward lithium-ion alternatives.
- Lead Acid:Mature flooded and valve-regulated designs retain cost advantages in uninterruptible power supply and forklift traction roles across European logistics hubs.
- Lithium Polymer:Flexible pouch configurations with gel electrolytes serve slim-form consumer electronics and medical devices requiring conformal battery shapes.
Today's leader: Lithium-ion. Tomorrow's challenger: Lithium Polymer.
End User:
Cost tier differentiation separates premium automotive-grade cells from standard industrial formats and economy consumer electronics packs.
- Automotive:Cell-to-pack architectures with silicon-anode integration are climbing the fastest as Stuttgart and Munich OEMs qualify 400 Wh/kg prototypes for extended-range passenger vehicles.
- Consumer Electronics:Compact cylindrical and pouch cells power smartphones, laptops, and wearables with declining average selling prices amid Asian manufacturing competition.
- Industrial:Heavy-duty traction batteries for material handling and backup power systems prioritize cycle life over energy density in warehouse automation deployments.
- Renewable Energy:Containerized lithium-ion systems paired with solar and wind installations are expanding most quickly in Germany and the Netherlands as F-Gas Regulation phase-down accelerates battery-based thermal management adoption.
Automotive commands margin premiums. Renewable Energy offers volume acceleration.
Application:
Volume concentration in electric vehicle powertrains versus stationary storage reveals divergent qualification timelines and safety testing protocols.
- Electric Vehicles:Integrated battery packs with liquid thermal management dominate procurement volumes from Rhine corridor manufacturing clusters.
- Energy Storage Systems:Grid-scale and behind-the-meter installations require EMA and KBA harmonized safety certifications currently forcing parallel qualification campaigns.
- Power Tools:High-discharge cylindrical cells serve professional construction and DIY segments with established supply relationships through distributor networks.
- Portable Devices:Low-capacity pouch and cylindrical formats face margin compression from commoditized Asian supply.
Electric Vehicles anchor current investment. Energy Storage Systems promise secondary value capture through retired automotive pack repurposing.
Technology:
Margin concentration in semiconductor-intensive functions separates premium battery management systems from commoditized cell manufacturing.
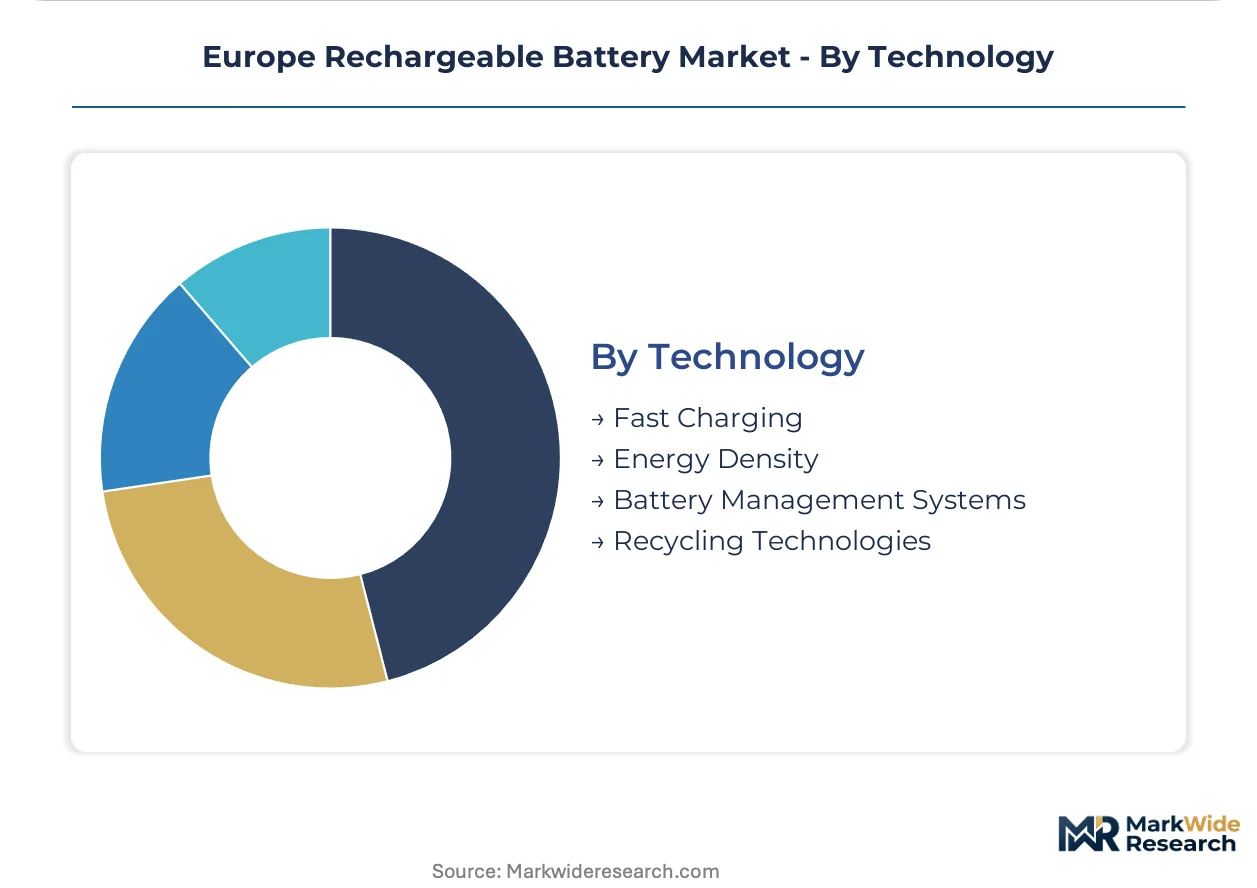
- Battery Management Systems:Integrated circuits for cell balancing, state-of-charge estimation, and thermal regulation command premium pricing across electric vehicle and stationary storage applications as the EU AI Act introduces conformity assessment complexity.
- Fast Charging:Silicon-carbide power electronics and advanced cooling architectures enable 350 kW+ charging rates for highway corridor deployment.
- Energy Density:Silicon-anode and solid-state electrolyte R&D programs at Northvolt and Saft Groupe SA are compressing laboratory-to-manufacturing timelines.
- Recycling Technologies:Hydrometallurgical and direct recycling processes are gaining investment in Belgium and Finland to meet EU Battery Regulation 2031 recycled content thresholds.
Battery Management Systems defend margin pools today. Recycling Technologies will reshape cost structures tomorrow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine corridor manufacturing cluster anchors European rechargeable battery demand through its concentration of cell gigafactories and automotive OEM assembly plants. Lower Saxony and Baden-Württemberg host the densest supplier ecosystems, reducing logistics costs and accelerating qualification timelines for lithium-ion pack procurement.
Germany
Electric vehicle production at Stuttgart and Munich OEMs drives cathode active material demand as the KBA enforces stringent battery safety certifications for automotive applications. The EU Battery Regulation's carbon footprint declarations are reshaping factory siting decisions across Lower Saxony cell plants.
France
Hybrid vehicle manufacturing sustains nickel-metal hydride demand while full electrification shifts volume toward lithium-ion alternatives under the EU Green Deal transport targets. ANSM and national regulators are converging on standardized safety testing protocols for stationary installations in the Bordeaux R&D corridor.
Poland
Lower Silesia and Silesia offer cost-competitive labor pools for battery pack assembly operations adjacent to German demand centers. The Wrocław manufacturing complex represents the country's largest cell production site, serving European OEM procurement through EU structural fund-supported expansion.
Netherlands
Rotterdam port operators negotiate decade-spanning supply contracts for heavy-duty electric truck batteries indexed to renewable energy certificates. F-Gas Regulation phase-down accelerates stationary energy storage deployments as thermal management systems shift toward battery-based cooling alternatives.
Sweden
Skellefteå and Borlänge sites supply sustainably sourced cathode materials to European cell manufacturers facing REACH-compliant recycling obligations. Finnish and Swedish mining sources are qualifying to reduce due diligence burden under ECHA substance restriction amendments for nickel and cobalt compounds.
Europe Rechargeable Battery Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers race to secure positions ahead of EU Battery Regulation recycled content mandates. The vendor base separates into three tiers: integrated cell-to-pack producers with captive cathode supply, scale-focused manufacturers leveraging Polish cost structures, and specialists in industrial and defense applications. Strategic archetypes include sustainability-driven European champions, Asian conglomerates with manufacturing scale, and niche technology leaders in nickel-based chemistries. M&A activity and upstream partnerships represent the dominant competitive moves as firms secure precursor refining capacity outside Chinese supply chains.
Among Asian conglomerates, BYD Co. Ltd. and Contemporary Amperex Technology Co. Ltd. exemplify scale-driven manufacturing archetypes with established European distribution. Panasonic Corporation and Samsung SDI occupy positions within the tier of diversified electronics-to-energy conglomerates leveraging semiconductor and display manufacturing synergies. Northvolt and LG Energy Solution represent contrasting European strategies: the former anchors sustainability credentials through Nordic material sourcing, while the latter exemplifies manufacturing scale at Poland's largest battery complex. Saft Groupe SA sits within the specialist tier, occupying a position defined by industrial and defense application focus rather than automotive volume competition.
| Leading Market Players |
|---|
| BYD Co. Ltd. |
| Contemporary Amperex Technology Co. Ltd. |
| Exide Industries |
| Panasonic Corporation |
| GS Yuasa Corporation |
| Northvolt |
| LG Energy Solution |
| Saft Groupe SA |
| Samsung SDI |
| Others |
Cost & Logistics Intelligence
Electrochemical engineer scarcity in Lower Saxony and Silesia widens labor-cost spreads between automotive-grade cell production and industrial battery assembly, compressing margins in standard-format manufacturing while premium pouch and prismatic cells retain pricing power through silicon-anode qualification timelines.
Pricing Analysis
Input-cost pass-through from lithium carbonate and nickel sulfate volatility is compressing cathode producer margins and destabilizing long-term contract pricing for European cell manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates silicon-anode automotive cells from LFP industrial formats and lead-acid backup systems, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Chinese refining capacity dominance in precursor materials, eroding margin buffers in mid-tier segments. Fleet operators in the Netherlands exhibit highest price sensitivity through decade-spanning offtake negotiations, while defense and aerospace procurement in France shows lowest sensitivity due to performance-locked specifications.
Supply Chain Analysis
Warehouse-distribution layer concentration in Rotterdam and Hamburg port zones feeds hub-and-spoke patterns radiating toward Rhine corridor OEM plants and Polish assembly operations. Geographic supply concentration centers on China for cathode precursor refining, South Korea for separator membranes, and Australia for spodumene concentrate, with European cell manufacturing drawing from these nodes. Raw material dependencies rest on lithium brine, nickel laterite, and cobalt hydroxide flows subject to export licensing restrictions. Single-source vulnerability in Chinese nickel sulfate refining creates structural supply chain risk. Distribution runs through captive logistics networks operated by integrated cell-to-pack producers rather than third-party distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe rechargeable battery market functions as a regulatory compounder where EU Battery Regulation recycled content mandates and carbon footprint declarations are accelerating demand for qualified suppliers ahead of compliance deadlines.
For Market Incumbents: Lock in captive cathode precursor supply through Nordic mining partnerships and hydrometallurgical recycling investments in Belgium and Finland to defend against Chinese refining export restrictions. Accelerate solid-state electrolyte R&D hiring in Bordeaux and Skellefteå to offset electrochemical engineer scarcity threatening cell design timelines. Prioritize CE marking pre-qualification for intelligent battery management systems before EU AI Act conformity assessment complexity hardens. For New Entrants and Emerging Players: Enter via second-life stationary storage repurposing of retired German automotive packs, the most penetrable segment given 10-15 year secondary cycle value capture and lower qualification barriers than virgin cell production. Target Polish pack assembly in Lower Silesia leveraging EU structural fund access and proximity to Lower Saxony demand clusters. Pursue direct contracting with Rotterdam port operators as the dominant go-to-market angle, displacing traditional distributor networks through renewable energy certificate-indexed pricing. For Investors and Strategic Acquirers: European automotive OEMs are the most active acquirer in this space, seeking upstream control over cell capacity ahead of EU Battery Regulation compliance tiers. Long-term viability favors integrated producers with captive material sourcing and recycling infrastructure over pure-play assemblers exposed to precursor price volatility. Monitor hydrometallurgical recycling yield rates as the critical inflection indicator for cost-competitive domestic lithium, nickel, and cobalt recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Nordic mining partnerships reduce REACH compliance burden and Chinese supply chain exposure for European cell manufacturers. |
| Hydrometallurgical Recycling Scale-Up | Belgian and Finnish facilities position suppliers to meet EU Battery Regulation 2031 recycled content thresholds. |
| Solid-State Electrolyte R&D Expansion | Bordeaux and Munich laboratories compress laboratory-to-manufacturing timelines for 400 Wh/kg silicon-anode prototypes. |
| Second-Life Storage System Deployment | German automotive OEM retired packs extend value capture through grid-scale energy storage repurposing. |
| Intelligent BMS CE Pre-Qualification | Early conformity assessment completion avoids EU AI Act intersection delays for automotive qualification. |
Research Approach
Bottom-up automotive and stationary storage modeling reconciled against top-down cathode precursor and cell gigafactory tracking forms the analytical core of this study. Primary interviews with cell manufacturing executives, OEM platform engineers, EPC contractors for grid-scale installations, and recycling plant technical directors were combined with secondary validation from ECHA substance restriction filings, EU Battery Regulation impact assessments, KBA safety certification databases, and customs trade data for lithium carbonate and nickel sulfate flows. Triangulation across these sources ensures supply-side capacity estimates align with demand-side procurement timelines.
Historical trendline analysis of cell production volumes, cathode material shipments, and electric vehicle registration patterns established baseline growth trajectories across the projection horizon. The analytical framework models segmentation dimensions including chemistry type, end-use vertical, application format, and technology tier, with CAGRs derived from regression analysis against EU Green Deal transport electrification targets and F-Gas Regulation phase-down schedules. Forecast inputs incorporate silicon-anode qualification timelines, solid-state electrolyte manufacturing readiness levels, and recycling infrastructure buildout rates.
Inputs from EMA and KBA regulatory filings, Northvolt and LG Energy Solution capacity announcements, and Rotterdam port operator procurement disclosures were available through the study window; gaps in Chinese export licensing decision timelines and South American brine production forecasts introduce uncertainty bands around precursor price assumptions. Forecasts reflect documented assumptions regarding EU Battery Regulation enforcement consistency and REACH amendment adoption schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North Africa Battery Market
Batteries
Yacht Battery Market
Batteries
Japan Battery Market
Batteries
Proton Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Vietnam Battery Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Seawater Battery Market
Batteries
India Battery Cell Market
Batteries
West Africa Battery Market
Batteries
3D-Printed Battery Market