
 Thermoplastic Prepreg Market | 2026-2036
Thermoplastic Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Prepreg Market Intelligence
The automotive sector's share of thermoplastic prepreg consumption is expanding at the expense of traditional industrial applications. This shift prioritizes high-volume, cost-effective material solutions. Toray Industries leverages its deep expertise in carbon fiber to serve demanding aerospace and automotive clients. Solvay specializes in high-performance polymer matrices for complex structural parts, while BASF extends its chemical engineering prowess into advanced composite materials.
Thermoplastic prepregs are intermediate composite materials consisting of reinforcing fibers impregnated with a thermoplastic polymer matrix. These materials, often utilizing PEEK or PAEK resins, offer superior toughness and recyclability compared to thermosets, enabling rapid part fabrication. Carbon fiber-based products command the premium end of the market due to their exceptional strength-to-weight ratio for aerospace applications. In contrast, glass fiber variants represent a cost-effective solution for high-volume automotive and industrial uses.
Material qualification and airworthiness certifications from bodies like the FAA in the United States and compliance with the EU's REACH regulation are critical for market access in aerospace. In the automotive sector, material specifications are often dictated by OEM standards and regional safety mandates. Stakeholder success will depend on navigating the complex trade-offs between material performance, processing speed, and final part cost to secure positions in emerging high-volume applications.
Market Dynamics
The primary structural force is the market's pivot from niche aerospace projects to high-volume automotive production. This transition, driven by electric vehicle lightweighting requirements, is compelling material suppliers to prioritize cost-effective manufacturing processes and supply chain efficiency over ultimate performance alone.
Growth Catalysts
- Automated Manufacturing:Innovations in automated tape laying (ATL) and out-of-autoclave (OOA) processing enable the high-speed, repeatable production necessary to meet the volume demands of the automotive and industrial sectors.
- Electric Vehicle Demand:The push for lighter electric vehicles to extend range and offset battery weight creates significant demand for thermoplastic prepregs in battery enclosures, body panels, and structural reinforcements.
- Regulatory Mandates:Emissions standards in the European Union and fuel economy targets in the United States pressure automotive OEMs to adopt lightweight materials, creating a strong regulatory pull for composite solutions.
Market Restraints
- Material Cost:The high price of performance resins like PEEK and PAEK, along with premium carbon fibers, remains a significant barrier to broader adoption compared to traditional metals and thermoset composites.
- Processing Requirements:Thermoplastic prepregs require higher processing temperatures and pressures than thermosets, necessitating specialized and energy-intensive manufacturing equipment which increases capital expenditure for converters.
- Supply Chain Volatility:The supply of high-grade carbon fiber is concentrated among a few key producers, leading to potential price fluctuations and supply constraints that can impact project costs and timelines.
Strategic Opportunities
- Emerging Mobility:The urban air mobility (UAM) and commercial drone sectors represent a significant future market, requiring lightweight, impact-resistant, and rapidly manufactured structural components.
- Recycled Content:Developing prepregs that incorporate recycled carbon or glass fibers offers a path to lower costs and meet sustainability goals, potentially opening new applications in consumer goods and construction.
- Industrial Applications:Untapped opportunities exist in industrial machinery, robotics, and renewable energy components like wind turbine blades, where high stiffness and fatigue resistance are critical performance attributes.
Industry Challenges
- Specialized Skill Gaps:A shortage of technicians and engineers with expertise in composite design, simulation, and the operation of automated manufacturing systems hinders efficient production scaling.
- Qualification Timelines:Long and costly material qualification programs, especially for aerospace applications governed by bodies like the FAA, slow the introduction of new and innovative material systems.
- Standardization Deficit:A lack of universally accepted standards for material testing and data reporting complicates part design and performance prediction, forcing extensive validation by each OEM.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Prepreg Market |
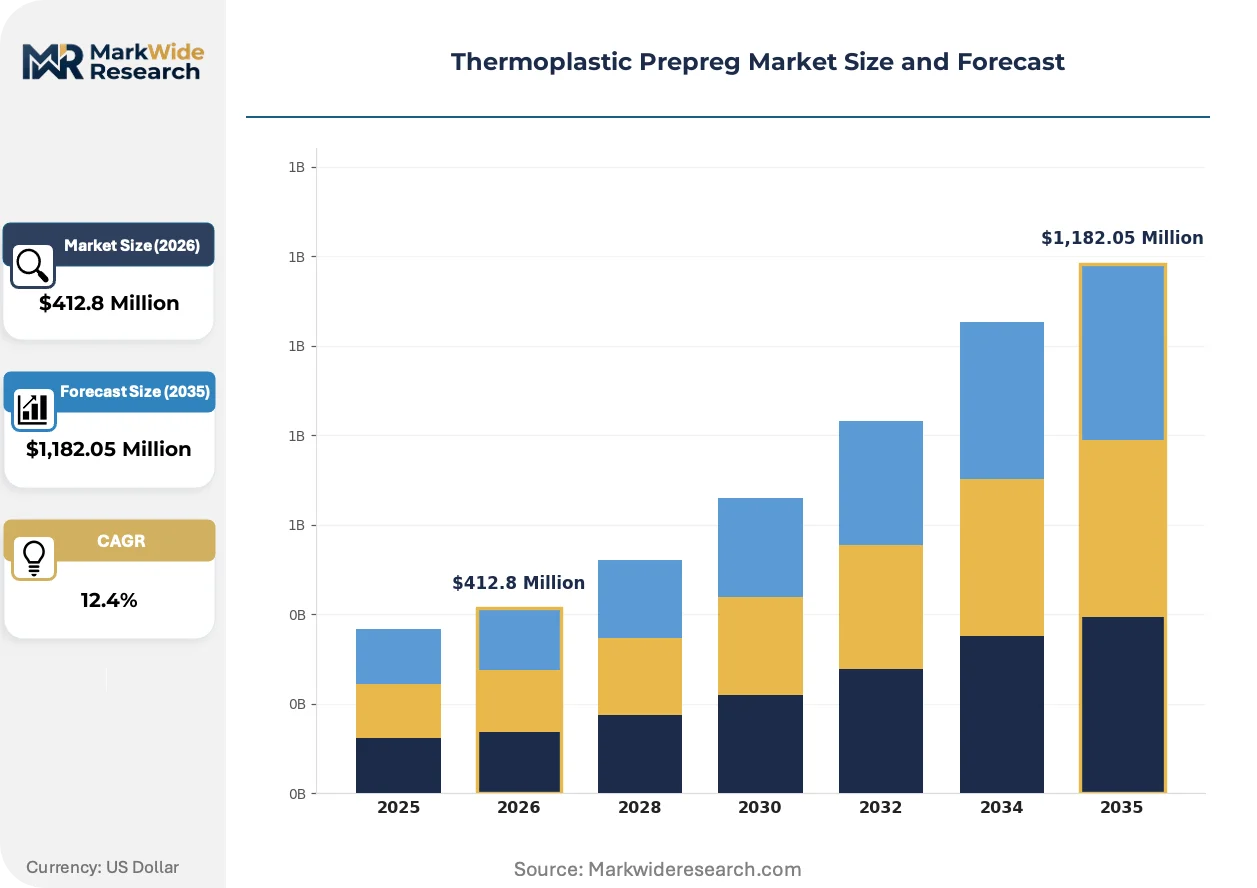
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,182.05 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Natural Fiber, Aramid Fiber Application: Aerospace, Automotive, Sports Equipment, Industrial Form: Sheet, Tape, Roll, Preform End User: OEMs, Tier-1 Suppliers, Service Providers, Automotive Manufacturers |
| Companies Covered | Solvay, SABIC, Toray Industries, BASF, Lanxess, Teijin Limited, Mitsubishi Chemical Corporation, Arkema, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Prepreg Market Strategic Shifts & Innovations
Process industrialization is the central theme, as a market once defined by manual, aerospace-centric methods adapts to the speed and scale of automotive manufacturing. This shift necessitates innovations in material formulation, automation, and regulatory alignment with circular economy principles.
Multi-material prepreg tapes, which strategically combine different fiber or resin types, allow for performance tailoring within a single component. Automotive and sporting goods designers are adopting this to optimize specific zones for stiffness, impact resistance, or cost. This approach is modularizing component design, enabling engineers to create functionally graded parts from one continuous process and reducing assembly complexity.
The EU's REACH regulation and its broader Circular Economy Action Plan are increasing scrutiny on the end-of-life management of composite materials. This regulatory pressure accelerates research into thermoplastic composite recycling, a key advantage over thermosets. Consequently, aerospace and automotive firms are prioritizing these materials to align with sustainability mandates like the Corporate Sustainability Reporting Directive (CSRD).
A clear shift from purchasing raw material spools to procuring pre-consolidated laminates or near-net-shape blanks is evident. This change disrupts traditional distribution channels, placing more value on suppliers with integrated processing capabilities and direct relationships with OEMs. The trend is most advanced within the German automotive industry, where supply chains are optimized for just-in-time delivery to electric vehicle assembly lines.
Thermoplastic Prepreg Market Segmentation
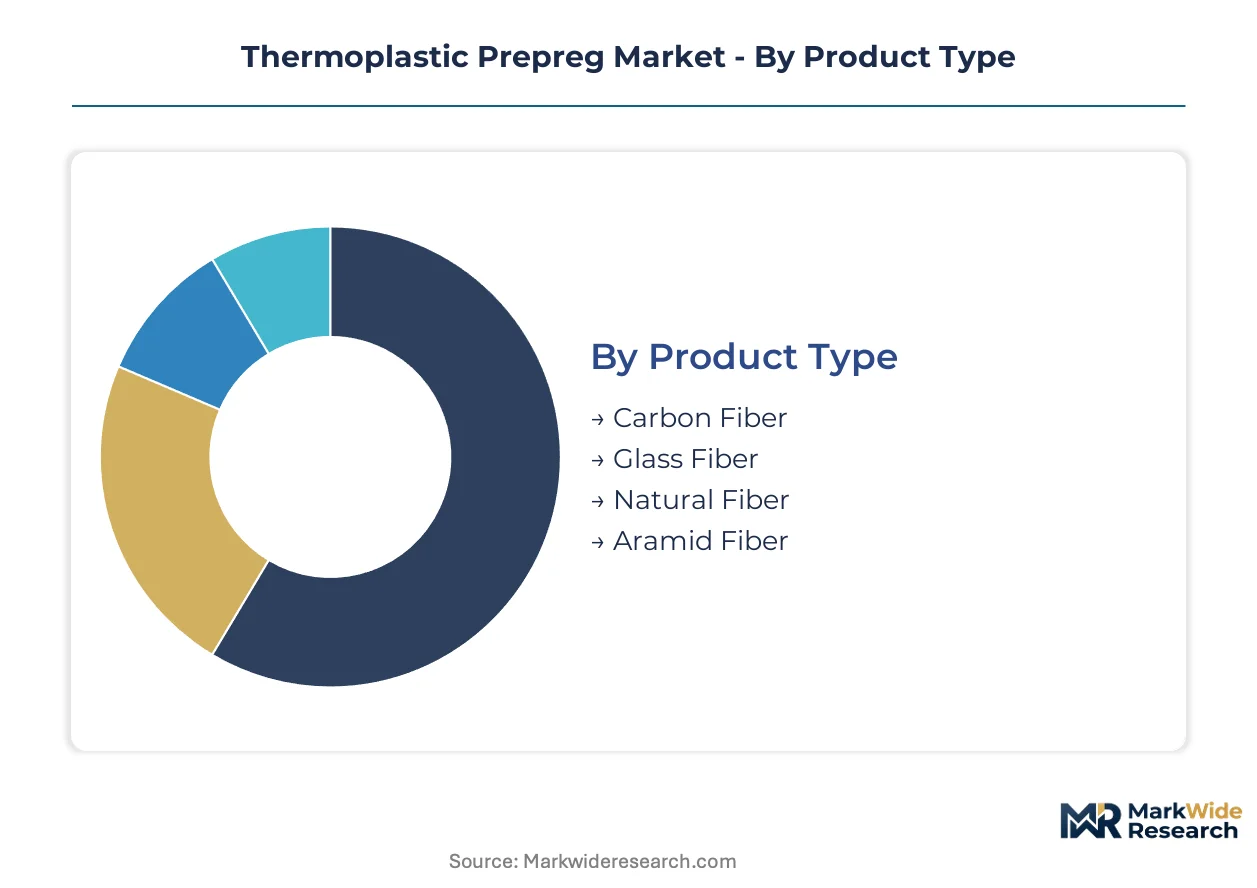
The thermoplastic prepreg market segments reveal distinct material compositions, application priorities, and supply chain dynamics. Understanding these divisions is crucial for manufacturers to tailor product offerings and optimize processing technologies for specific end-use requirements.
Product Type:
The integration depth of thermoplastic prepregs varies significantly across product types, influencing their application from standalone components to embedded structural elements.
- Carbon Fiber:These prepregs utilize carbon filaments for exceptional strength-to-weight ratios, primarily targeting high-performance aerospace structures and premium automotive components. Demand concentrates in Germany and the United States for advanced air mobility and electric vehicle platforms, driven by stringent performance demands.
- Glass Fiber:Comprising glass filaments, these prepregs offer a cost-effective balance of strength and stiffness, making them suitable for high-volume industrial and mainstream automotive applications. European automotive manufacturers prioritize glass fiber variants for battery enclosures and structural reinforcements due to their economic viability and good mechanical properties.
- Natural Fiber:Derived from plant-based sources like flax or hemp, natural fiber prepregs offer a sustainable alternative with good acoustic damping and impact absorption characteristics. These materials find niche applications in interior automotive components and consumer goods, aligning with circular economy initiatives.
- Aramid Fiber:Aramid fiber prepregs provide excellent impact resistance and vibration damping, making them valuable in ballistic protection and specific sporting goods. Their use is limited to applications where energy absorption is a critical design parameter.
Carbon Fiber leads volumes today; Glass Fiber is gaining share fastest.
Application:
The scale and volume requirements dictate material selection across diverse application areas for thermoplastic prepregs.
- Automotive:This segment encompasses structural components, battery housings, and body panels for electric vehicles, prioritizing lightweighting and rapid manufacturing cycles. Demand from German automotive OEMs for range extension and crashworthiness drives significant material consumption.
- Aerospace:High-performance thermoplastic prepregs are critical for aircraft primary and secondary structures, leveraging their superior toughness and fatigue resistance. Material qualification from bodies like the FAA is essential for market entry and sustained presence in this demanding sector.
- Industrial:This category includes applications in machinery, robotics, and renewable energy, where durability, chemical resistance, and high stiffness are valued. Wind turbine blades and robotic arms represent significant growth areas for these robust materials.
- Sports Equipment:Lightweight and high-strength prepregs enhance performance in items like bicycle frames, skis, and rackets. Manufacturers seek materials that offer a balance of stiffness, impact resistance, and aesthetic appeal.
Automotive applications drive the highest material consumption, while aerospace continues its steady, high-performance expansion.
Form:
The form in which thermoplastic prepregs are supplied directly impacts processing efficiency and compatibility with automated manufacturing systems.
- Tape:Unidirectional (UD) tapes are ideal for automated tape laying (ATL) processes, enabling precise fiber placement and rapid production of complex geometries. German automotive production lines increasingly adopt thermoplastic tapes for high-volume structural components.
- Sheet:Prepreg sheets offer versatility for compression molding and diaphragm forming processes, suitable for producing larger, less complex parts. This form is widely used across industrial and automotive applications requiring broad material coverage.
- Roll:Continuous rolls of prepreg material facilitate efficient cutting and handling for various manufacturing techniques. This format supports both automated and semi-automated production lines, providing flexibility for diverse part sizes.
- Preform:Near-net-shape preforms reduce material waste and streamline subsequent consolidation steps. These custom-shaped materials are particularly beneficial for intricate parts in aerospace and high-performance automotive applications.
Tape forms show the most dynamic growth due to automation, with sheet products retaining a substantial, versatile market presence.
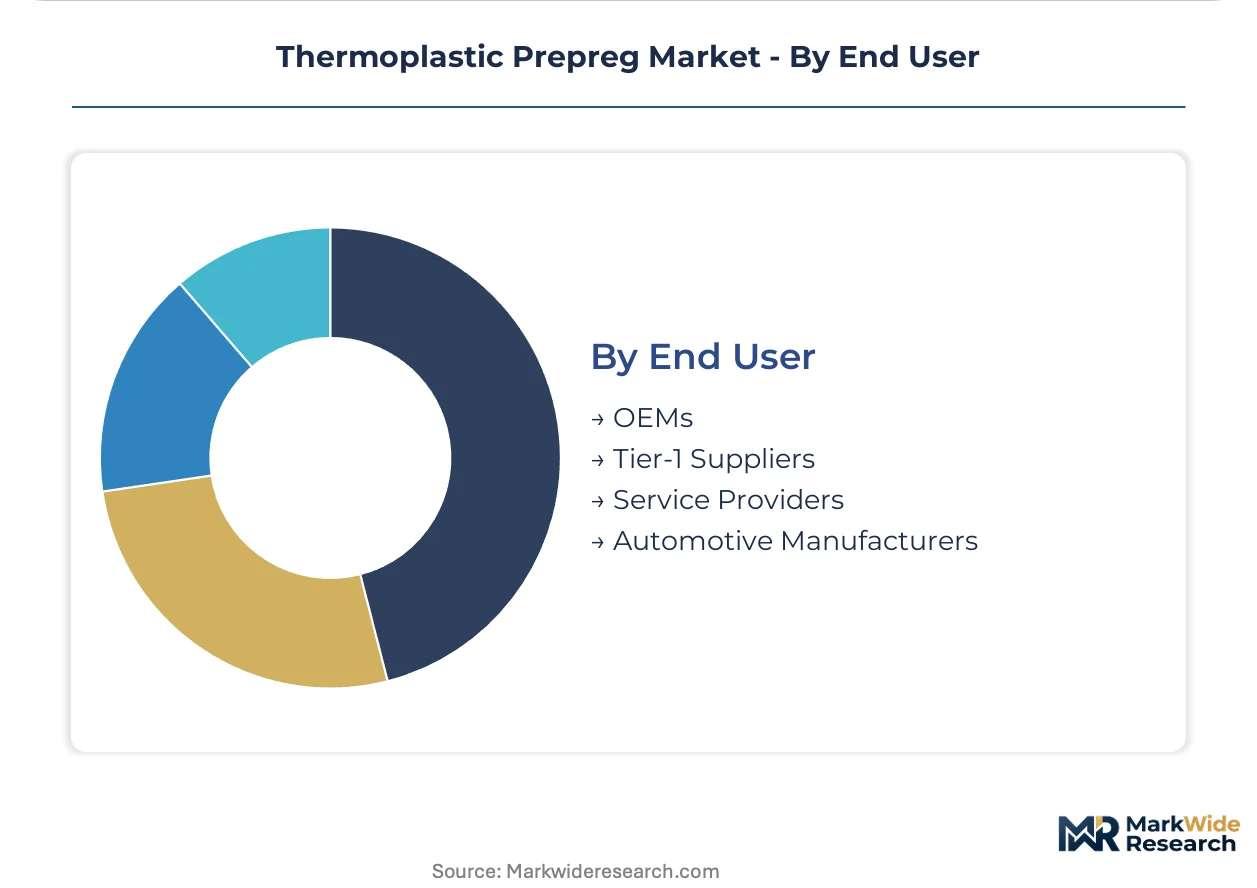
End User:
Procurement patterns for thermoplastic prepregs differentiate end-users based on their position within the manufacturing value chain.
- OEMs:Original Equipment Manufacturers directly procure prepreg materials for in-house component fabrication, maintaining direct control over design and production specifications. Automotive OEMs in Europe are increasingly integrating prepreg processing capabilities.
- Automotive Manufacturers:This segment specifically covers vehicle manufacturers, often a subset of OEMs, emphasizing high-volume procurement and specialized material requirements for vehicle platforms. Their demand focuses on cost-effective, rapidly processable solutions.
- Tier-1 Suppliers:These suppliers manufacture major sub-assemblies for OEMs, requiring prepregs that integrate seamlessly into their established production processes. They often work closely with material producers for tailored solutions.
- Service Providers:This category includes contract manufacturers and specialized fabricators who offer composite part production services to various industries. They require a broad portfolio of prepreg types to meet diverse client needs.
OEMs represent the largest direct purchasing segment, while Automotive Manufacturers exhibit the steepest expansion trajectory for volume procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market dynamic reveals a nuanced regulatory arbitrage, as production and material specification priorities shift between regions based on compliance costs and market access requirements. This strategic maneuvering influences material selection and processing investments across major automotive and aerospace hubs. OEMs evaluate regional mandates alongside material performance attributes.
Germany
Germany's automotive sector drives significant thermoplastic prepreg demand for electric vehicle lightweighting and battery enclosures. The country's commitment to EU emissions standards and the EU Green Deal mandates material innovation. Industrial clusters around Stuttgart and Munich are accelerating the adoption of automated tape laying for high-volume component fabrication.
United States
Demand in the United States stems from advanced air mobility and high-performance aerospace applications requiring robust composite solutions. Fuel economy targets set by the NHTSA encourage automotive OEMs to explore lightweight thermoplastic prepregs. The aerospace manufacturing hub in Seattle focuses on qualifying new composite systems for next-generation aircraft platforms.
China
China's expanding electric vehicle production and ambitious industrial modernization targets are fueling demand for cost-effective thermoplastic prepregs. The dual carbon goals and GB standards for automotive materials influence local material development and procurement strategies. Manufacturing zones in the Yangtze River Delta are establishing large-scale production lines for glass fiber prepreg components.
Japan
Japanese automotive and electronics manufacturers seek thermoplastic prepregs for structural components and consumer goods, emphasizing material strength and recyclability. METI's push for sustainable manufacturing practices encourages the development of advanced composite recycling technologies. The Nagoya region, a major automotive hub, integrates multi-material prepreg tapes into modular component designs.
France
French aerospace and automotive industries prioritize thermoplastic prepregs for their superior toughness and rapid processing capabilities in complex parts. EU's REACH regulation dictates material safety and environmental compliance for new composite formulations entering the market. The Toulouse aerospace cluster is a focal point for qualifying high-performance thermoplastic systems for primary aircraft structures.
Thermoplastic Prepreg Market Key Industry Players
Capacity expansion dominates the current landscape, as major material suppliers invest heavily to meet rising demand from the automotive sector. The market structure exhibits a tiered consolidation, with established chemical giants and specialized composite producers vying for market share. Strategic archetypes include integrated material developers offering end-to-end solutions and niche specialists focusing on high-performance resins or specific fiber types. Geographic expansion into key manufacturing regions is a common competitive move.
Among the integrated material developers, Solvay and Toray Industries exemplify the strategic depth required to serve both demanding aerospace and high-volume automotive clients. Solvay, a multinational chemical company, leverages its expertise in high-performance polymer matrices for complex structural parts, focusing on applications where superior toughness is critical. Toray Industries, a Japanese multinational, utilizes its deep expertise in carbon fiber production to anchor its position in premium applications, particularly for aerospace and advanced automotive platforms. These companies focus on balancing material performance with processing speed and cost-effectiveness for emerging high-volume applications, navigating complex material qualification processes.
| Leading Market Players |
|---|
| Solvay |
| SABIC |
| Toray Industries |
| BASF |
| Lanxess |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Arkema |
| Hexcel Corporation |
Cost & Logistics Intelligence
Ownership by large chemical conglomerates influences both the supply stability and pricing discipline for thermoplastic prepregs. These integrated players can absorb raw material volatility while maintaining long-term supply agreements with key automotive and aerospace OEMs.
Pricing Analysis
Distributor margins for specialized thermoplastic prepregs remain thin due to direct OEM procurement, especially for high-volume automotive programs. The dominant pricing model is contract-based long-term offtake, ensuring supply stability for critical components. Price differentiation stems from material qualification levels, such as FAA certifications, and the volume scale of procurement. Automotive manufacturers exhibit the highest price sensitivity, balancing performance with cost-effectiveness under intensifying cost compression from electric vehicle lightweighting.
Supply Chain Analysis
Workforce availability in Germany and China impacts the specialized manufacturing of thermoplastic prepregs, particularly for advanced processing techniques. The supply chain sources heavily from high-performance carbon fiber and PEEK/PAEK resins, critical for structural integrity. Single-source vulnerability for premium carbon fiber represents a structural risk, potentially affecting project timelines. Downstream distribution primarily operates through direct-to-OEM channels, optimizing just-in-time delivery for large automotive and aerospace programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoplastic prepreg market is a stable compounder, driven by the persistent demand for lightweighting in the automotive and aerospace sectors.
For Market Incumbents: Cement market leadership by investing in advanced automation for out-of-autoclave processing, countering margin pressure from emerging glass fiber alternatives. Expand capacity in German industrial clusters to serve electric vehicle platforms, mitigating the threat of regional supply chain disruptions. Deepen vertical integration into specialized resin production to control input costs.
For New Entrants and Emerging Players: Launch via a direct-to-manufacturer model, targeting niche applications in urban air mobility where qualification timelines are shorter. Focus on developing recycled-content prepregs for industrial applications, leveraging sustainability mandates as a go-to-market angle. The industrial machinery segment represents a penetrable application with less stringent qualification barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized processors with proprietary out-of-autoclave technology, offering leverage in a consolidating market. The long-term viability for thermoplastic prepregs extends beyond a decade, supported by continuous innovation in material science. Acquire firms with established OEM relationships in the German automotive sector. Watch for sustained increases in carbon fiber production capacity as an inflection indicator for broader market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Tape Laying Investment | Accelerates high-volume production for automotive components, reducing manufacturing costs for OEMs. |
| Recycled Fiber Integration | Aligns with EU Circular Economy mandates, opening new cost-sensitive applications in industrial sectors. |
| Advanced Resin R&D | Enhances material performance for demanding aerospace structures, securing premium market share. |
| Geographic Capacity Expansion | Establishes local supply chains in China for electric vehicle battery enclosures, meeting regional demand. |
| OEM Partnership Development | Secures long-term supply contracts with major automotive manufacturers, ensuring stable revenue streams. |
Research Approach
Coverage spans Germany, the United States, and China, with primary inputs from each region. The research combined extensive primary interviews with R&D directors, procurement leads, and OEM engineers. Secondary validation drew from trade association reports, government publications, and company financial filings. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The analysis modeled market dynamics at a granular level across product type, application, form, and end user. An industry-specific dimension, resin type, was also integrated into the framework. Compound annual growth rates were derived from historical data trends and projected adoption rates over the projection horizon. Forecast inputs included electric vehicle production forecasts and aerospace fleet modernization plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Material deviation in global automotive production or aerospace qualification processes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Synthetic Rope Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Composite Drums Market
Composite Materials
Epoxy Composite Market
Composite Materials
High Performance Composites Market
Composite Materials
Global Sports Composites Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Ultra-Lightweight Cement Composites Market