
 Reinforced Carbon-Carbon Composite Market | 2026-2036
Reinforced Carbon-Carbon Composite Market Size, Share, and Industry Trends Forecast 2026-2036
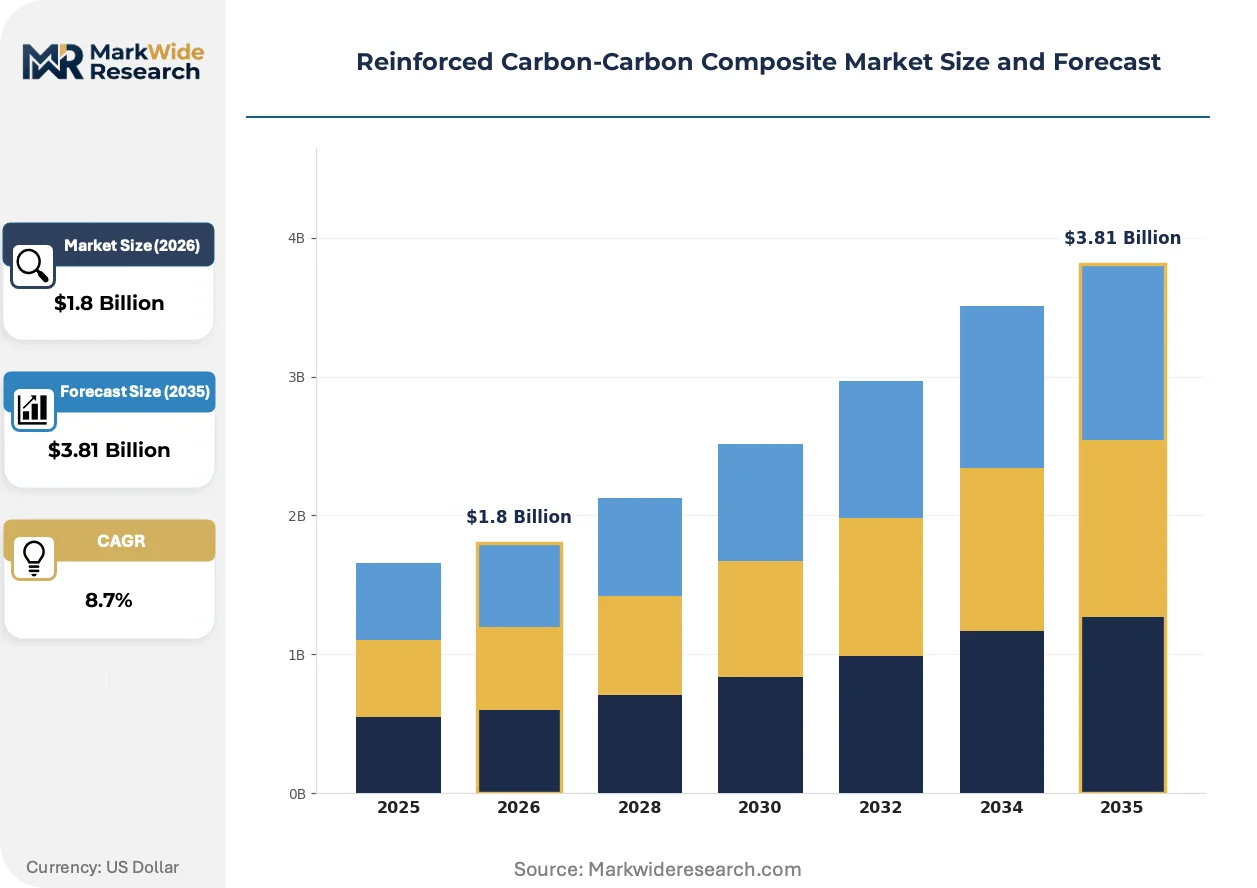
Reinforced Carbon-Carbon Composite Market Analytics
China is fragmenting carbon-carbon composite supply chains through aggressive capacity additions in C/C brake disc and aerospace heat shield production. Toray Industries leverages its PAN precursor verticality to sustain premium filament supply across Asian and North American defense programs. SGL Carbon anchors European aerospace demand through certified supply to Airbus thermal management platforms. Mersen competes in industrial furnace applications with specialized graphitization expertise.
Reinforced carbon-carbon composites consist of carbon fiber preforms densified through chemical vapor infiltration or liquid pitch impregnation, yielding materials that retain structural integrity above 2000°C in oxygen-depleted environments. These composites serve critical functions where metallic alloys fail, including rocket nozzle throats, aircraft brake discs, and fusion reactor plasma-facing components. Thermal protection systems dominate current revenue pools due to sustained Artemis program procurement and commercial space launch cadence. Structural components represent the fastest-expanding segment as hypersonic vehicle programs multiply development contracts across defense agencies. Aerospace applications command margin premiums tied to multi-year qualification protocols and limited approved supplier bases.
FAA certification standards for aircraft brake materials, ESA technical requirements for spacecraft thermal protection, and China's GB standards for carbon fiber reinforced composites collectively shape market access and product qualification timelines. EPA oversight of perchloroethylene in chemical vapor infiltration processes is forcing manufacturing site relocations and solvent recovery investments. Stakeholders must monitor hypersonic defense budget allocations and commercial space re-entry vehicle order books as the primary demand swing factors.
Market Dynamics
Chemical vapor infiltration cycle times and pyrolytic carbon deposition yields remain the binding constraints on thermal protection system output, with furnace capacity scarcity in certified facilities creating order backlogs stretching 18-24 months for aerospace-qualified material.
Growth Catalysts
- Artemis program procurement:NASA's lunar return architecture sustains multi-year thermal protection system contracts for crew capsule heat shields and service module components.
- FAA brake certification standards:Updated aircraft braking material requirements accelerate replacement cycles for carbon-carbon disc stacks in narrow-body and regional jet fleets.
- Hypersonic vehicle development:Defense agency funding for Mach 5+ interceptors and reconnaissance platforms multiplies nosecone and leading-edge development contracts across three continents.
Market Restraints
- PAN precursor cost volatility:Acrylonitrile feedstock price swings transmit directly to carbon fiber tow pricing, compressing margins for C/C brake disc manufacturers serving automotive aftermarket channels.
- Graphitization furnace concentration:Ultra-high temperature processing capability clusters in Germany and Japan, creating single-source vulnerability for aerospace-grade material qualification.
- Ceramic matrix composite substitution:Silicon carbide fiber-reinforced ceramics encroach on intermediate-temperature applications previously served by carbon-carbon in industrial furnace fixtures.
Strategic Opportunities
- Fusion reactor plasma-facing components:ITER and successor tokamak projects specify carbon-carbon divertor targets, opening institutional procurement channels outside traditional aerospace.
- Commercial space re-entry vehicle expansion:Suborbital tourism and point-to-point hypersonic transport prototypes require ablative and reusable thermal protection at production scales beyond current certified capacity.
- EPA solvent recovery mandates:Perchloroethylene emission controls force capital investment in closed-loop CVI systems, advantaging incumbent processors with environmental compliance infrastructure.
Industry Challenges
- Multi-year qualification timelines:Aerospace OEM certification protocols for thermal protection systems extend 36-48 months, freezing supplier rosters and delaying revenue recognition for new entrants.
- Specialized pyrolysis technician scarcity:Chemical vapor infiltration furnace operation and densification monitoring require skills absent from standard materials engineering curricula, constraining production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Carbon-Carbon Composite Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Protection Systems, Structural Components, Heat Shields, Aerospace Applications End User: Aerospace, Defense, Automotive, Energy Manufacturing Stage: Raw Material Processing, Component Fabrication, Assembly, Quality Control Application: Spacecraft Materials, Aircraft Structures, Industrial Furnaces, Rocket Nozzles |
| Companies Covered | Toray Industries, SGL Carbon, Mersen, Teijin, Mitsubishi Chemical Group, Nippon Carbon, Toyo Tanso, Tokai Carbon, Schunk Carbon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Carbon-Carbon Composite Market Evolving Landscape
Processing efficiency breakthroughs and regulatory pressure on traditional densification chemistries are compressing manufacturing timelines while opening qualification pathways for novel reinforcement architectures.
Pre-oxidized PAN fiber stabilization and rapid carbonization protocols are rendering obsolete conventional 40-hour furnace cycles for brake disc preforms. Tier-one automotive suppliers in Germany and Japan have adopted continuous carbonization lines, cutting energy input per kilogram by half and enabling just-in-time delivery to original equipment assembly plants. This acceleration is rendering obsolete the batch-processing economics that historically protected regional captive producers.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants targeting perchloroethylene in chemical vapor infiltration is forcing manufacturing site relocations and solvent recovery capital deployment. Facilities in Alabama and California face compliance deadlines requiring seven-figure abatement investments or process conversion to alternative densification chemistries. Aerospace-qualified suppliers are responding by consolidating production in greenfield sites with integrated emission controls, extending lead times for new capacity by 12-18 months.
Vertical integration into carbon fiber precursor production is reshaping procurement relationships between brake system integrators and material suppliers. Tier-one aircraft brake manufacturers in the United States and France have established captive tow conversion capability, bypassing traditional merchant fiber markets for high-specification aerospace grades. This consolidation is most visible in the southeastern United States, where landing system OEMs have acquired carbonization assets previously operated by independent converters.
Reinforced Carbon-Carbon Composite Market Segmentation
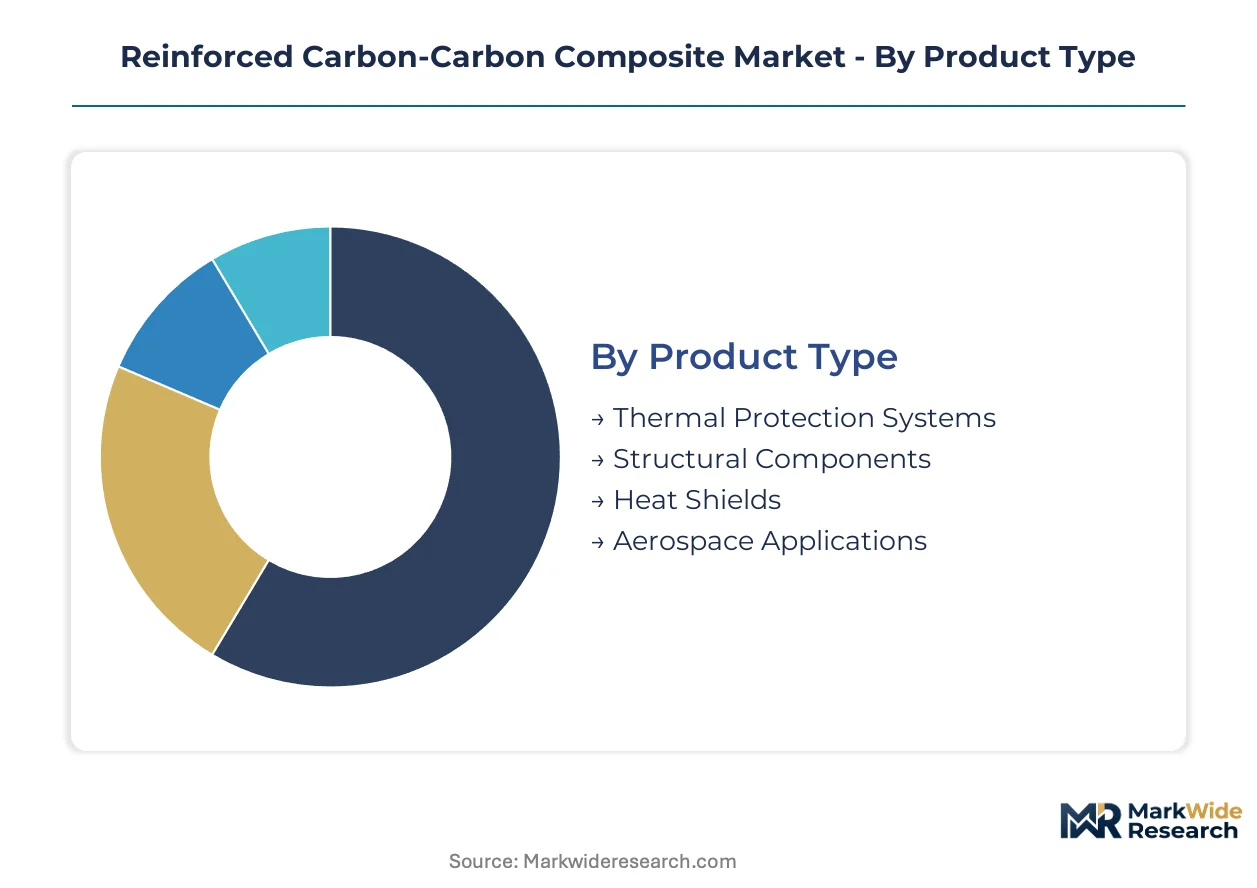
Segmentation in reinforced carbon-carbon composites reveals how qualification barriers and thermal performance requirements partition value capture. Product architecture and end-use certification demands create distinct competitive arenas with divergent margin profiles.
Product Type:
Mature thermal protection platforms coexist with emerging structural applications as qualification timelines stretch supplier capabilities.
- Thermal Protection Systems:Carbon fiber preforms densified through chemical vapor infiltration retain integrity above 2000°C in oxygen-depleted environments. NASA Artemis program procurement concentrates demand in Alabama and California contractor clusters, with 18-24 month order backlogs for aerospace-qualified material.
- Structural Components:Load-bearing architectures for hypersonic vehicle airframes require multi-axis reinforcement and precision-machined interfaces. Defense agency Mach 5+ interceptor programs multiply nosecone and leading-edge development contracts across three continents.
- Heat Shields:Ablative and reusable configurations for re-entry vehicles.
- Aerospace Applications:Certified material for commercial and institutional spacecraft.
Thermal Protection Systems handle the majority of throughput; Structural Components is the fastest mover on share.
End User:
Customer concentration varies sharply by certification burden and procurement channel.
- Aerospace:OEM thermal management platforms command margin premiums tied to multi-year qualification protocols and FAA certification requirements. Airbus and NASA contractor rosters limit approved supplier bases.
- Defense:Hypersonic vehicle development contracts for Mach 5+ interceptors and reconnaissance platforms.
- Automotive:Carbon-carbon brake disc stacks for narrow-body and regional jet fleets face replacement cycle acceleration.
- Energy:ITER and successor tokamak projects specify carbon-carbon divertor targets for plasma-facing components.
Aerospace commands the dominant revenue pool; Defense is climbing the fastest on contract volume.
Manufacturing Stage:
Process control requirements intensify downstream as material qualification stakes rise.
- Raw Material Processing:PAN precursor stabilization and rapid carbonization protocols cut energy input per kilogram by half. Toray Industries leverages vertical filament supply across defense programs.
- Component Fabrication:Chemical vapor infiltration cycle times and pyrolytic carbon deposition yields constrain thermal protection system output.
- Assembly:Integration of densified preforms into finished thermal protection architectures.
- Quality Control:Non-destructive testing and certification documentation for aerospace qualification protocols extending 36-48 months.
Component Fabrication absorbs the most capital intensity; Quality Control is gaining share fastest on certification timeline extension.
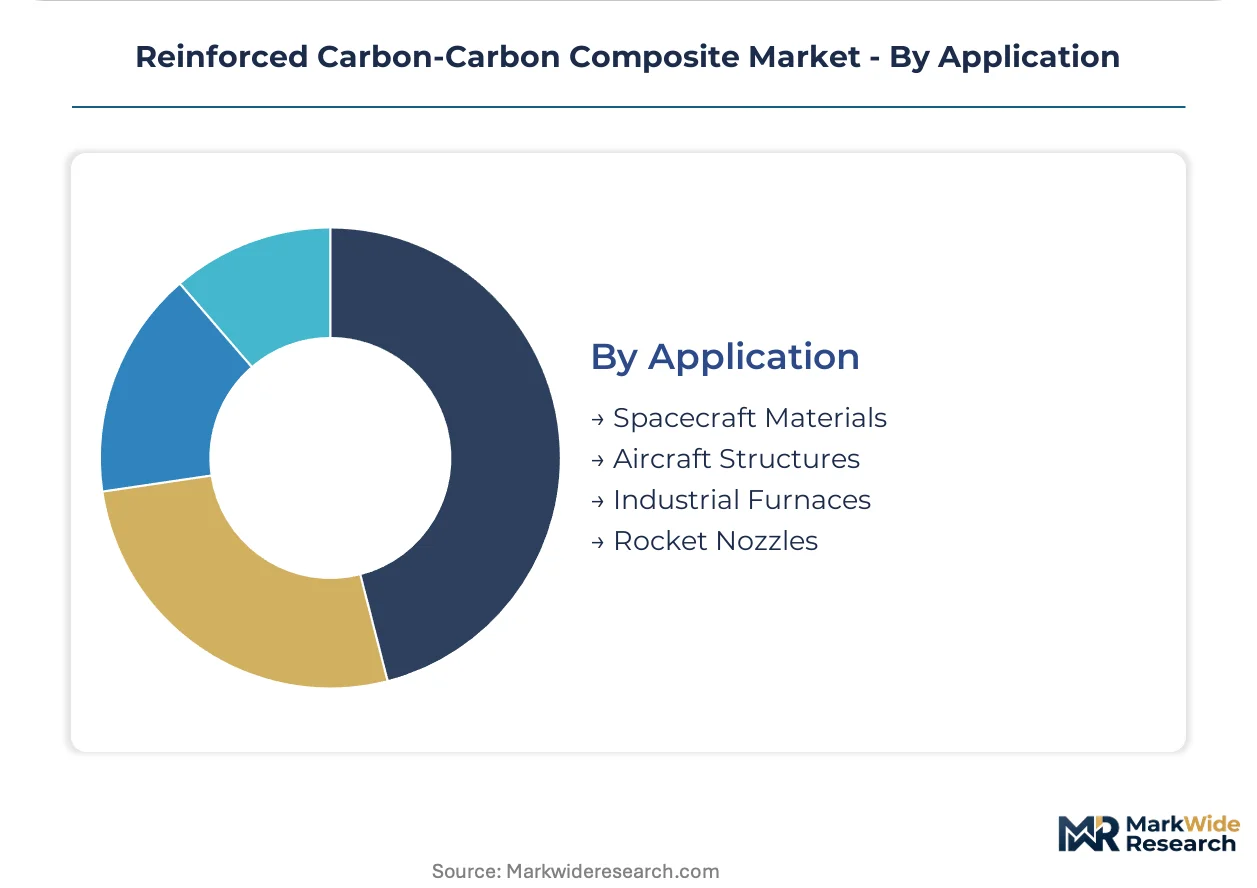
Application:
Operating environment severity dictates reinforcement architecture and densification chemistry selection.
- Spacecraft Materials:Crew capsule heat shields and service module components for lunar return architectures sustain multi-year procurement contracts.
- Aircraft Structures:Brake disc stacks certified to updated FAA braking material requirements.
- Industrial Furnaces:Fixture applications face silicon carbide fiber-reinforced ceramic substitution at intermediate temperatures.
- Rocket Nozzles:Throat components where metallic alloys fail.
Spacecraft Materials dominates current procurement; Rocket Nozzles is expanding most quickly on launch cadence recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphitization furnace capability clusters in Germany and Japan create single-source vulnerability for aerospace-grade material, while chemical vapor infiltration capacity concentrates around NASA contractor sites in the United States. Demand formation follows defense procurement geography and commercial space launch infrastructure.
United States
Artemis program thermal protection system contracts sustain multi-year procurement for crew capsule heat shields and service module components. FAA certification standards for aircraft brake materials accelerate replacement cycles across narrow-body and regional jet fleets. Alabama and California contractor clusters face 18-24 month order backlogs for aerospace-qualified material as furnace capacity scarcity bites.
Germany
Automotive brake disc manufacturers adopt continuous carbonization lines that cut energy input per kilogram by half for just-in-time delivery to original equipment plants. ECHA oversight of chemical vapor infiltration processes shapes manufacturing site compliance requirements. Bavaria-based industrial furnace specialists compete with silicon carbide fiber-reinforced ceramic substitution at intermediate temperatures.
China
GB standards for carbon fiber reinforced composites shape market access and product qualification timelines for domestic and foreign suppliers. MIIT capacity additions in C/C brake disc and aerospace heat shield production fragment global supply chains. Yangtze River Delta fabricators scale output for commercial aviation aftermarket channels.
Japan
PAN precursor verticality sustains premium filament supply across Asian and North American defense programs through backward integration into acrylonitrile feedstock control. METI industrial policy supports ultra-high temperature processing capability retention. Nagoya-area carbonization assets serve hypersonic vehicle development contracts for Mach 5+ interceptor nosecones.
France
Airbus thermal management platforms anchor European aerospace demand through certified supply relationships with limited approved supplier bases. ANSM oversight of perchloroethylene emission controls forces capital investment in closed-loop chemical vapor infiltration systems. Toulouse-area landing system OEMs have acquired carbonization assets from independent converters.
Reinforced Carbon-Carbon Composite Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in preform densification and filament supply. The vendor base separates into three strata: PAN precursor producers with backward integration into acrylonitrile, certified aerospace component fabricators with 36-48 month qualification protocols, and industrial furnace specialists competing on graphitization throughput. Consolidation pressure runs through captive tow conversion capability acquisition and greenfield site development with integrated emission controls.
Among Japanese industrial conglomerates with materials divisions, Toray Industries and Teijin occupy positions spanning PAN precursor through finished composite architectures. SGL Carbon anchors European aerospace demand through German carbonization assets. These three exemplify the vertical control archetype that defines competitive positioning in thermal protection system supply.
| Leading Market Players |
|---|
| Toray Industries |
| SGL Carbon |
| Mersen |
| Teijin |
| Mitsubishi Chemical Group |
| Nippon Carbon |
| Toyo Tanso |
| Tokai Carbon |
| Schunk Carbon Technology |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors linking Japanese PAN precursor facilities to Alabama thermal protection system fabricators impose cost volatility that amplifies price spreads between aerospace-qualified and industrial-grade material. This logistics exposure concentrates pricing power with incumbent suppliers possessing integrated carbonization assets, while forcing aftermarket brake disc manufacturers toward aggressive spot-market fiber sourcing.
Pricing Analysis
FAA certification requirements for aircraft brake materials dictate the pricing tier structure across the reinforced carbon-carbon composite landscape. Three-tier pricing structure across premium, standard, and economy levels separates NASA-qualified thermal protection systems from FAA-certified brake discs and uncertified industrial furnace fixtures. Cost compression in the industrial tier is intensifying because silicon carbide fiber-reinforced ceramics displace carbon-carbon at intermediate temperatures. Automotive aftermarket channels exhibit highest price sensitivity, while defense hypersonic programs demonstrate lowest sensitivity due to performance-non-negotiable procurement protocols.
Supply Chain Analysis
Acrylonitrile feedstock availability in the United States, Japan, and Germany anchors upstream material flows for PAN precursor production. Aerospace-grade carbon-carbon composite manufacturing draws from specialized pitch impregnation resins, ultra-high purity graphite powders, and precision-machined refractory metal fixtures. Single-source vulnerability concentrates in German and Japanese graphitization furnace capacity for aerospace qualification. Distribution runs through certified tier-one brake system integrators and direct NASA contractor relationships for thermal protection platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide fiber-reinforced ceramic substitution threatens carbon-carbon incumbents across industrial furnace and intermediate-temperature aerospace applications, demanding proactive defensive positioning.
For Market Incumbents: Entrench qualification moats by accelerating FAA and ESA certification protocol completion for next-generation thermal protection architectures. Secure captive PAN precursor supply through backward integration into acrylonitrile feedstock control or long-term offtake agreements with Toray Industries and Mitsubishi Chemical Group. Counter ceramic matrix composite displacement by emphasizing carbon-carbon's superior performance above 2000°C in oxygen-depleted environments. For New Entrants and Emerging Players: Pursue fusion reactor plasma-facing component contracts as the most penetrable institutional procurement channel outside traditional aerospace oligopolies. Target ITER and successor tokamak divertor target specifications where silicon carbide ceramics fail and carbon-carbon retains technical superiority. Establish greenfield chemical vapor infiltration capacity in EPA-compliant sites with integrated perchloroethylene recovery systems to bypass incumbent environmental compliance advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with PAN precursor-through-finished-composite control. Long-term viability hinges on defense hypersonic budget durability and commercial space re-entry vehicle order book expansion. Acquisition target archetype: certified aerospace component fabricators with 36-48 month qualification protocols already completed. Signal to watch: NASA Artemis program contract award velocity and Mach 5+ interceptor development contract proliferation across three continents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries and Teijin demonstrate how acrylonitrile feedstock control sustains premium filament supply across defense programs. |
| Greenfield CVI Capacity with EPA Compliance | Closed-loop perchloroethylene recovery systems in Alabama and California extend lead times but lock in aerospace qualification access. |
| Fusion Reactor Component Qualification | ITER divertor target specifications open institutional procurement channels outside traditional aerospace contractor rosters. |
| Hypersonic Vehicle Development Partnership | Mach 5+ interceptor nosecone and leading-edge contracts multiply across defense agencies in the United States, Japan, and France. |
| Continuous Carbonization Line Adoption | German and Japanese automotive suppliers cut energy input per kilogram by half for just-in-time brake disc preform delivery. |
Research Methodology
Initial hypotheses were tested against primary input from chemical vapor infiltration furnace operators, aerospace OEM thermal management procurement leads, defense agency materials engineers, and carbon fiber precursor plant managers and refined through secondary validation against FAA certification databases, EPA National Emission Standards for Hazardous Air Pollutants enforcement records, ESA technical requirements documentation, and customs trade data for carbon-carbon composite imports. Bottom-up capacity utilization assessments at certified Alabama and California facilities were triangulated against top-down NASA Artemis program procurement disclosures.
Demand-supply balance modeling across the analysis window incorporated product type segmentation between thermal protection systems and structural components, end user segmentation across aerospace, defense, automotive, and energy applications, and manufacturing stage segmentation from raw material processing through quality control. CAGRs were derived from production capacity expansion timelines, qualification protocol completion rates, and defense budget appropriation trajectories. Hypersonic vehicle development contract awards and commercial space re-entry vehicle prototype announcements served as forward demand indicators.
Sensitivities concentrate around EPA enforcement intensity for perchloroethylene emission controls, PAN precursor price volatility transmission from acrylonitrile markets, and ceramic matrix composite technical advancement at intermediate temperatures. Cross-checking against NASA procurement forecast revisions and ITER project milestone schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Structural Core Materials Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
FRP Reactor Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Phenolic Panel Market
Composite Materials
Malaysia High Pressure Laminate Market