
 Thermoplastic Polyolefin Membranes Market | 2026-2036
Thermoplastic Polyolefin Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyolefin Membranes Market Outlook
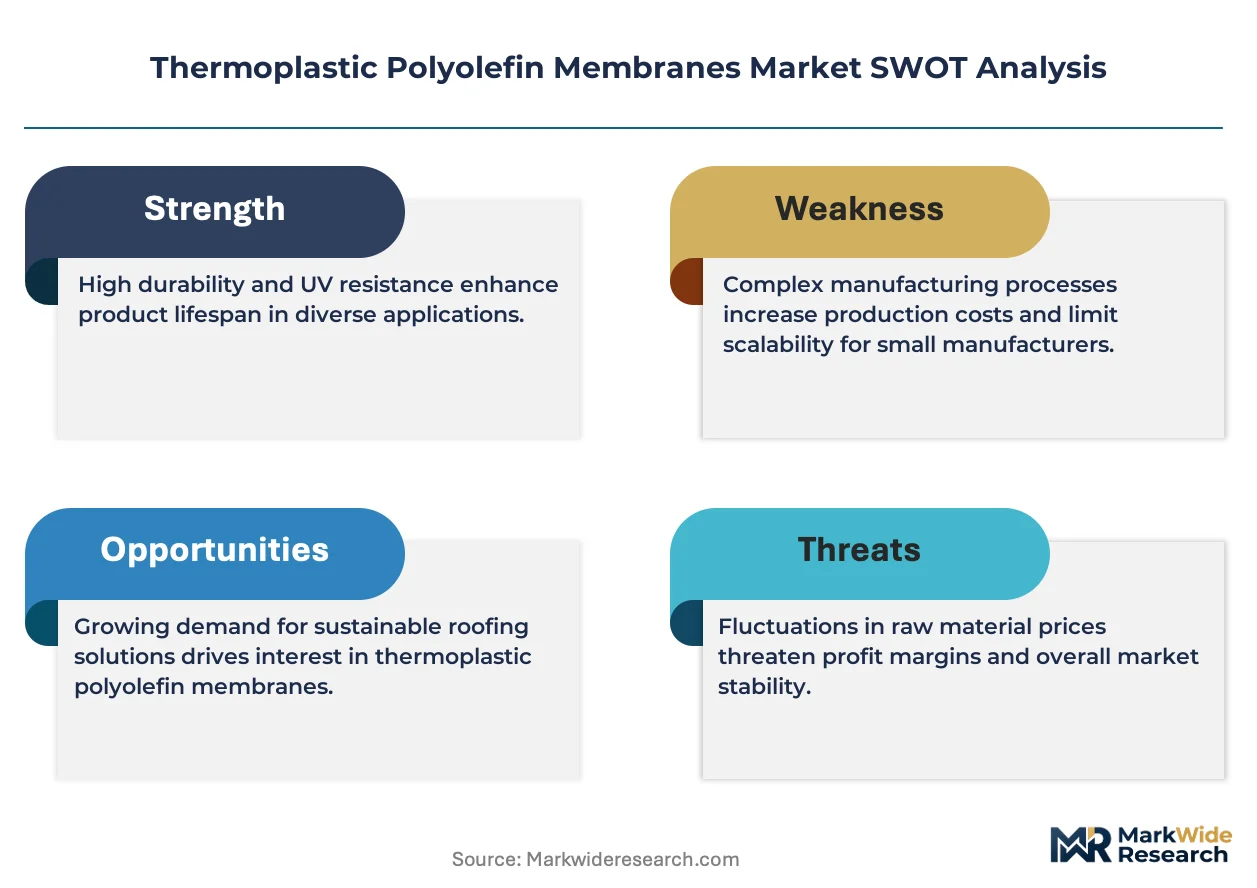
Maintenance and inspection service contracts are shifting how membrane value gets captured in the TPO market. Firestone Building Products leverages its extensive certified contractor network to sustain recurring revenue beyond initial membrane sales. Sika AG competes through integrated waterproofing system packages that combine TPO membranes with adhesives and sealants. Carlisle SynTec Systems anchors its position with in-house production of polymer raw materials and fabrication equipment.
Thermoplastic polyolefin membranes consist of ethylene-propylene rubber combined with polypropylene, manufactured through extrusion calendering into flexible sheets typically 45-80 mils thick, engineered primarily for durable weatherproofing of commercial building envelopes. Single-ply TPO dominates installed volume across North American roofing applications, while reinforced multi-ply configurations command premium positioning in industrial waterproofing where puncture resistance determines specification. Extrusion technology leads manufacturing throughput, though thermoforming processes are gaining traction for pre-fabricated flashing and detail components that reduce field labor.
EPA Energy Star roofing reflectance standards and California Title 24 cool roof requirements shape product formulation toward higher solar reflectance index values. ASTM D6878 standards govern membrane thickness and seam strength, while OSHA fall protection regulations influence installation method selection and contractor training requirements. Stakeholders must monitor evolving state-level building electrification codes that tie envelope performance to broader decarbonization compliance pathways.
Market Dynamics
Cool roof mandates from EPA Energy Star and California Title 24 are compressing specification cycles while forcing reformulation toward higher solar reflectance index values across commercial roofing supply chains.
Growth Catalysts
- California Title 24 cool roof standards:Mandates for minimum solar reflectance in commercial buildings accelerate TPO membrane specification over darker alternatives in the United States.
- Commercial building stock expansion:Warehouse and logistics facility construction across Germany and China drives single-ply membrane volume for large-format flat roofs.
- Extrusion calendering advances:Improved manufacturing throughput reduces unit costs and enables consistent 60-80 mil thickness for reinforced specifications.
Market Restraints
- Propylene feedstock volatility:Ethylene and propylene price swings from petrochemical supply disruptions compress membrane margins unpredictably.
- EPDM substitution persistence:Black EPDM rubber membranes retain cost advantage in non-cool-roof climates and heritage building restorations.
- ASTM D6878 compliance burden:Seam strength and thickness testing requirements extend product development timelines for new formulations.
Strategic Opportunities
- Prefabricated flashing components:Thermoformed detail pieces reduce field labor hours and accelerate installation for commercial contractors.
- Building electrification codes:State-level envelope performance mandates in the United States tie cool roofing to broader decarbonization compliance pathways.
- Industrial waterproofing penetration:Multi-ply reinforced configurations command premium positioning in manufacturing facilities requiring puncture resistance.
Industry Challenges
- Certified installer scarcity:Hot-air welding proficiency and OSHA fall protection training requirements constrain qualified contractor availability.
- Seam integrity field performance:Inconsistent welding quality across installation crews drives warranty claims and reputation risk for membrane suppliers.
- Raw material backward integration:Captive polymer production requires capital intensity that mid-scale manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyolefin Membranes Market |
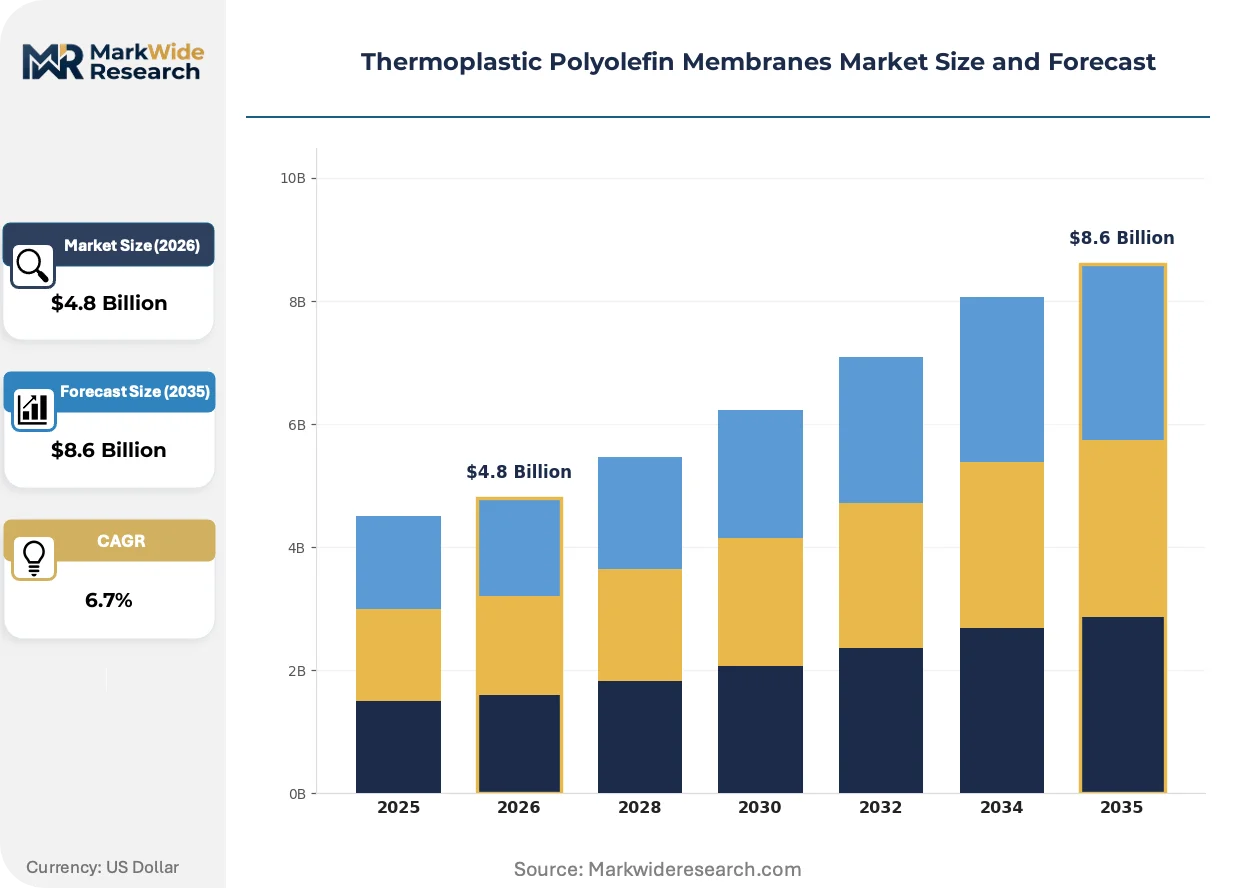
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Ply, Multi-Ply, Reinforced, Non-Reinforced Application: Roofing, Waterproofing, Lining, Flooring End User: Construction, Automotive, Industrial, Agriculture Technology: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | Firestone Building Products, Johns Manville, GAF, Tremco Incorporated, SOPREMA SAS, Sika AG, ARDEX Australia, Genflex, Carlisle SynTec Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyolefin Membranes Market Strategic Shifts
Formulation chemistry and installation methodology are converging to reduce field labor while tightening energy performance compliance across commercial building envelopes.
Self-adhering TPO membrane technology is overtaking traditional mechanically attached systems in low-slope commercial roofing. Building owners in the United States specify these products to eliminate fastener penetrations and reduce thermal bridging. The shift is compressing demand for traditional ballasted systems while elevating specification priority for factory-applied adhesive consistency.
EPA Energy Star roofing reflectance standards are tightening minimum initial SRI thresholds for steep-slope and low-slope categories. Product portfolios now stratify around certified performance tiers rather than nominal thickness grades. Manufacturers serving California and Texas markets prioritize formulation stability against UV degradation to maintain reflectance over service life.
Maintenance service bundling is restructuring how membrane value gets captured in commercial roofing. Contractors in Germany and the United States now lead with multi-year inspection contracts rather than material-only bids. Facility managers in logistics and retail verticals favor this model for predictable envelope lifecycle cost management.
Thermoplastic Polyolefin Membranes Market Segmentation
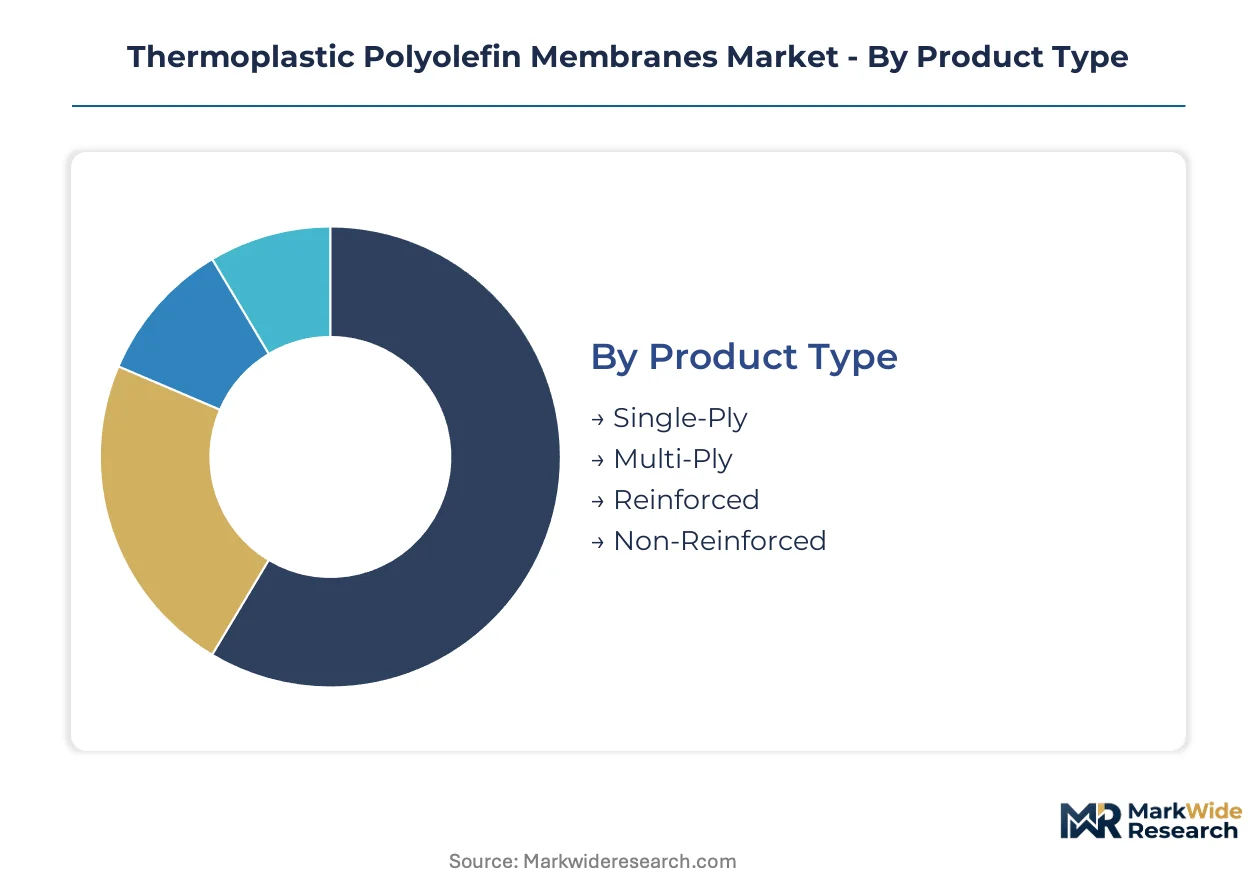
TPO membrane specification diverges sharply across construction verticals, with product thickness and reinforcement levels calibrated to load-bearing requirements and climate exposure. Segmentation discipline separates commodity roofing volume from premium industrial waterproofing applications where puncture resistance commands price premiums.
Product Type:
Manufacturing scale concentrates around extrusion calendering lines capable of producing consistent sheet thickness at high throughput, with reinforced specifications requiring captive polymer compounding capabilities that mid-scale producers struggle to fund.
- Single-Ply:Unreinforced 45-60 mil sheets dominate commercial roofing installations across the United States and Germany, where cool roof mandates from EPA Energy Star and California Title 24 accelerate specification over darker alternatives. Warehouse and logistics facility construction in China absorbs the bulk of global single-ply volume for large-format flat roof applications.
- Reinforced:Polyester or fiberglass scrim sandwiched between TPO layers delivers puncture resistance for industrial waterproofing and exposed roofing in high-traffic maintenance zones. German manufacturing facilities and US data centers specify 60-80 mil reinforced membranes where service life requirements exceed twenty years.
- Multi-Ply:Laminated configurations combining TPO with vapor barriers or insulation facers address complex envelope assemblies in cold climate construction.
- Non-Reinforced:Homogeneous sheets serve flashing details and prefabricated components where flexibility and thermoformability outweigh tensile strength requirements.
Single-Ply absorbs the bulk of installed capacity; Reinforced is expanding most quickly as industrial waterproofing specifications tighten.
Application:
End-use concentration tracks building stock composition and regulatory pressure on thermal performance, with roofing commanding the largest addressable surface area while waterproofing captures premium margin.
- Roofing:Low-slope commercial roofing represents the dominant TPO application, with self-adhering membrane technology displacing mechanically attached systems to eliminate fastener penetrations and reduce thermal bridging. US building owners increasingly specify these products under tightening EPA Energy Star reflectance standards.
- Waterproofing:Below-grade and plaza deck applications demand multi-ply reinforced configurations with factory-applied adhesive consistency. German civil engineering projects and US infrastructure rehabilitation drive specification for tunnels, bridges, and foundation walls where hydrostatic pressure resistance determines material selection.
- Lining:Geomembrane applications in containment and environmental protection utilize thicker TPO sheets with chemical resistance formulations.
- Flooring:Specialized wear-layer applications in healthcare and food processing facilities leverage TPO durability and cleanability.
Roofing maintains volume leadership across all geographies; Waterproofing posts the steepest expansion trajectory as infrastructure rehabilitation accelerates.
End User:
Customer procurement patterns separate project-driven construction demand from recurring industrial maintenance budgets, with automotive and agriculture representing emerging adjacencies.
- Construction:General contractors and roofing specialists specify TPO membranes through competitive bidding processes increasingly bundled with multi-year inspection and maintenance contracts. US commercial building owners and German facility managers favor this outcome-based procurement model for predictable envelope lifecycle cost management.
- Industrial:Manufacturing facility operators prioritize puncture-resistant reinforced membranes for process areas with rooftop equipment traffic and chemical exposure. Chinese industrial park development and US manufacturing reshoring drive specification for large-format installations.
- Automotive:Interior trim and underbody applications exploit TPO lightweighting and recyclability versus traditional PVC.
- Agriculture:Greenhouse cladding and livestock containment represent nascent demand concentrated in controlled-environment agriculture expansion regions.
Construction channels the majority of membrane volume; Industrial end users are gaining share fastest as manufacturing facility investment accelerates.
Technology:
Process selection determines capital intensity and product geometry flexibility, with extrusion dominating flat sheet production while thermoforming captures value-added prefabrication.
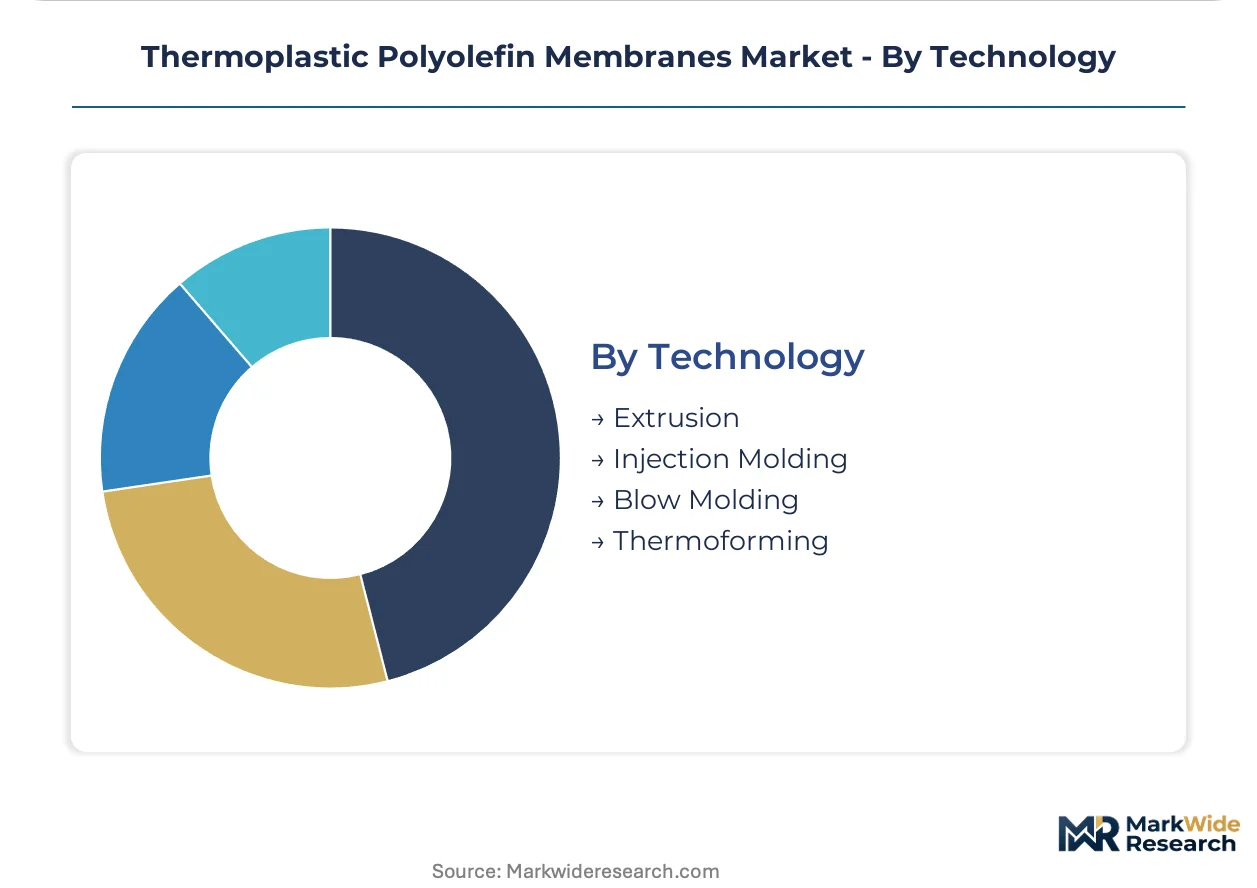
- Extrusion:Calendering and flat-die extrusion lines produce continuous sheet at widths exceeding twelve feet, enabling efficient coverage of large roof areas with minimal seams. Firestone Building Products and Carlisle SynTec Systems operate captive extrusion capacity in the United States with integrated polymer compounding for formulation control.
- Thermoforming:Vacuum and pressure forming processes convert extruded sheet into prefabricated pipe boots, curb flashings, and detail components that reduce field labor hours. German contractors and US commercial roofing specialists increasingly specify thermoformed accessories to accelerate installation and improve seam consistency.
- Injection Molding:Limited TPO penetration in rigid automotive and industrial components where polypropylene homopolymer dominates.
- Blow Molding:Niche hollow-profile applications in fluid handling and containment.
Extrusion commands the overwhelming share of production capacity; Thermoforming climbs the fastest as prefabrication reduces field welding risk and labor cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Germany and the United States while consumption absorbs volumes across warehouse construction clusters in China and commercial roofing retrofits in California. This geographic split shapes trade flows and regional pricing power.
United States
Warehouse and logistics facility construction across Texas and the Southeast drives single-ply membrane absorption for large-format flat roofs. EPA Energy Star certification requirements and California Title 24 building standards enforce minimum solar reflectance index values that accelerate TPO specification over darker alternatives. Dallas-Fort Worth and Atlanta metropolitan areas anchor the fastest-growing installation contractor networks.
Germany
Industrial waterproofing specifications for manufacturing facilities and data centers command premium reinforced membrane positioning. REACH regulations and the EU Green Deal framework tighten embodied carbon disclosure requirements for construction materials. The Rhine-Ruhr and Bavarian industrial corridors concentrate specification activity for multi-ply configurations exceeding twenty-year service life requirements.
China
Industrial park development and logistics hub construction absorb bulk global single-ply volume for standardized warehouse envelopes. GB standards for building energy efficiency and provincial green building mandates in Jiangsu and Zhejiang accelerate cool roofing adoption. The Yangtze River Delta and Pearl River Delta clusters dominate both manufacturing capacity and end-use consumption.
Canada
Cold climate construction demands multi-ply laminated configurations combining TPO with vapor barriers and insulation facers. Health Canada and PMRA oversight of construction material emissions influences formulation chemistry for indoor air quality compliance. Toronto and Vancouver metropolitan areas concentrate commercial roofing retrofit activity tied to municipal green building programs.
United Kingdom
Commercial building stock renovation and heritage structure waterproofing create specification diversity across reinforced and non-reinforced grades. UK Building Regulations Part L thermal efficiency standards and London Plan energy performance requirements shape product selection criteria. The Greater London and Manchester construction markets lead volume absorption for self-adhering membrane technology.
Thermoplastic Polyolefin Membranes Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the TPO membrane value chain. Integrated manufacturers controlling polymer compounding and extrusion capacity face competition from specialists sourcing sheet stock for fabrication and distribution. Three archetypes dominate: vertically integrated compounders with captive raw material production, membrane fabricators purchasing polymer feedstock on contract, and installation-focused contractors bundling materials with service contracts. Consolidation pressure operates through acquisition of regional roofing distributors and backward integration into polymer compounding.
Among North American integrated manufacturers, Firestone Building Products and Carlisle SynTec Systems exemplify the capital-intensive archetype with captive production capabilities. Sika AG represents the European formulation specialist model with integrated waterproofing system packaging. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across the United States, Germany, and Switzerland.
| Leading Market Players |
|---|
| Firestone Building Products |
| Johns Manville |
| GAF |
| Tremco Incorporated |
| SOPREMA SAS |
| Sika AG |
| ARDEX Australia |
| Genflex |
| Carlisle SynTec Systems |
| Others |
Value Chain & Pricing Dynamics
Certified hot-air welding technicians in the Dallas-Fort Worth corridor command wage premiums that compress contractor margins and widen pricing spreads between self-adhering membrane tiers and traditional mechanically attached systems. Labor-cost differentials between unionized installation crews in California and non-union contractors in Texas reinforce three-tier pricing stratification across premium reinforced specifications, standard single-ply grades, and economy non-reinforced alternatives.
Pricing Analysis
Margin tightening in standard-grade single-ply reflects propylene feedstock volatility from Gulf Coast petrochemical disruptions and EPDM substitution persistence in non-cool-roof climates. Three-tier pricing structure across premium reinforced, standard single-ply, and economy flashing-grade levels separates buyers by certification tier—ASTM D6878 compliance and EPA Energy Star SRI thresholds—and volume scale, with logistics facility developers in China exhibiting highest price sensitivity versus data center operators in Germany prioritizing twenty-year service life over unit cost.
Supply Chain Analysis
Direct-to-roofing-contractor channels handle specification-driven demand in the United States and Germany, while distributor-led procurement dominates fragmented construction markets in China and Canada. Manufacturing gravity centers on the United States, Germany, and China for extrusion calendering capacity, with polymer compounding for reinforced grades drawing from ethylene-propylene rubber supply anchored in Texas and Louisiana petrochemical corridors. Raw material dependency on propylene monomer and polyester scrim feeds vulnerability to tariff exposure on Chinese-sourced reinforcement textiles. Distribution runs through Firestone Building Products' certified contractor network and Carlisle SynTec Systems' regional fabricator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TPO membrane market sits in a technology-transition phase as self-adhering membrane systems displace mechanically attached and ballasted legacy installations across commercial roofing specifications.
For Market Incumbents: Deploy captive polymer compounding capabilities to defend margin position against propylene feedstock volatility and mid-scale fabricator price competition. Firestone Building Products and Carlisle SynTec Systems should expand thermoformed prefabrication capacity to capture value from field labor reduction demands, while tightening certified installer networks to mitigate seam integrity warranty exposure from inconsistent hot-air welding quality across contractor crews. For New Entrants and Emerging Players: Industrial waterproofing contractors in Chinese manufacturing parks represent an underserved buyer archetype seeking puncture-resistant reinforced membranes with localized technical support. New entrants should target below-grade plaza deck applications in US infrastructure rehabilitation and German tunnel projects where multi-ply specifications command premium positioning, partnering with regional distributors for adhesive and sealant bundling rather than competing on extrusion scale. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale membrane fabricators possessing backward integration into polymer compounding given building electrification code expansion across US states. Long-term viability over a multi-year window favors targets with captive thermoforming capabilities and maintenance service contract revenue streams. Investors should monitor California Title 24 amendment cycles and EPA Energy Star SRI threshold revisions as inflection indicators for cool roof mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive propylene formulation control insulates margins from Gulf Coast supply disruptions. |
| Thermoformed Prefabrication Capacity Expansion | Factory-formed flashing components reduce field welding hours and accelerate contractor installation timelines. |
| Certified Installer Network Consolidation | Controlled hot-air welding proficiency mitigates seam integrity warranty claims and reputation risk. |
| Maintenance Service Contract Bundling | Multi-year inspection agreements shift revenue from transactional membrane sales to predictable recurring streams. |
| Multi-Ply Reinforced Product Line Extension | Industrial waterproofing specifications in German manufacturing and US data centers command premium positioning. |
Study Parameters
Document review covered ASTM D6878 standards documentation, EPA Energy Star roofing certification databases, and California Title 24 building code amendments, complemented by interviews with commercial roofing contractors, membrane manufacturing plant managers, polymer procurement leads at downstream fabricators, and facility managers at logistics and data center operators. Secondary validation drew from customs and trade flow data, SEC 10-K filings of publicly traded building products companies, and industry association reports from the National Roofing Contractors Association. Bottom-up volume estimates from contractor installation tracking and top-down value assessments from manufacturer revenue analysis were triangulated for consistency.
Historical shipment data cross-referenced against panel input from roofing distributor purchasing managers and polymer compounding executives informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application vertical, end-user procurement pattern, and technology process route. CAGRs were derived from regression analysis of installed square footage growth against commercial construction permit data and cool roof mandate adoption curves. Industry-specific forecast inputs incorporated propylene monomer price elasticity and certified installer workforce expansion rates.
Revisions become necessary when state-level building electrification code adoption accelerates beyond baseline assumptions or when propylene supply disruptions from Gulf Coast weather events materialize. Practitioners should monitor EPA Energy Star SRI threshold amendment proposals and OSHA fall protection regulatory updates for early signals of specification cycle compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market