
 Rubber Carbon Black Market | 2026-2036
Rubber Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Carbon Black Market Outlook
Tire manufacturer procurement consolidation is recalibrating supplier power across the value chain. Cabot Corporation leverages its North American furnace network to sustain long-haul supply commitments. Birla Carbon anchors volume leadership through integrated feedstock positions in India and Egypt. Orion Engineered Carbons GmbH differentiates via specialty-grade capacity for premium tire formulations.
Rubber carbon black constitutes a colloidal carbon additive produced through partial combustion or thermal decomposition of hydrocarbon feedstocks, with particle sizes ranging from 10 to 100 nanometers and surface areas between 20 and 150 m²/g, functioning primarily as a reinforcing filler and pigment in elastomer compounds. The High Abrasion Furnace segment dominates tire tread applications where durability requirements are most severe. Specialty Grade material commands premium positioning in industrial rubber products requiring precise conductivity or UV stability thresholds. Pellet form leads logistics efficiency for bulk tire plant deliveries while powder retains niche coating applications.
EPA emissions standards under the Clean Air Act constrain US furnace black production methods, while REACH registration requirements in Europe govern aromatic oil extractable limits in rubber compounds. India's Central Pollution Control Board enforces stack emission norms on carbon black manufacturing clusters in Gujarat and Maharashtra. Stakeholders must track feedstock volatility, regulatory enforcement intensity in manufacturing clusters, and tire OEM qualification timelines for specialty grades.
Market Dynamics
Tire manufacturer procurement consolidation is compressing supplier margins while furnace emission standards under the EU Green Deal force capital-intensive retrofit cycles across European production assets.
Growth Catalysts
- Automotive tire reinforcement demand:OEM qualification programs for high-durability tread compounds are pulling volume through specialty-grade channels. Passenger vehicle electrification is extending tire replacement cycles, intensifying demand for abrasion-resistant formulations.
- REACH aromatic oil limits:European compounders are reformulating elastomer mixes to meet extractable polycyclic aromatic hydrocarbon thresholds, creating specification premiums for low-PAH carbon black grades in industrial rubber applications.
- India domestic tire capacity expansion:Gujarat and Maharashtra manufacturing clusters are scaling furnace black output to serve localized supply chains for Apollo Tyres, MRF, and JK Tyre.
Market Restraints
- Feedstock cost volatility:Coal tar and petroleum residue prices swing with crude oil benchmarks, compressing margin predictability for non-integrated producers lacking captive refinery relationships.
- Furnace technology lock-in:Thermal black and acetylene black processes face stranded asset risk as EPA and EU Green Deal emission standards tighten, requiring $40-80 million per facility for wet-scrubbing and energy recovery retrofits.
- Silica-silane substitution:Tire makers are partial-replacing carbon black with precipitated silica in low-rolling-resistance green tire formulations, displacing volume in passenger segment tread compounds.
Strategic Opportunities
- Conductive grade expansion:Electric vehicle battery pack seals and charging infrastructure cables require precisely controlled resistivity, opening premium positioning for specialty furnace blacks with surface area above 125 m²/g.
- India PLI scheme alignment:Production-linked incentive structures for advanced chemistry cell manufacturing are cascading demand into EPDM and silicone rubber compounds requiring high-purity carbon black.
- Pellet logistics optimization:Dense-phase pneumatic conveying systems at tire plants are favoring hard-pellet morphology over powder, rewarding producers with dedicated bulk handling infrastructure.
Industry Challenges
- Furnace control engineering talent scarcity:Combustion optimization and emissions monitoring expertise is concentrated among retiring specialists, constraining operational excellence at newer facilities.
- OEM qualification timeline compression:Tire manufacturers are compressing supplier approval cycles from 24 months to 14 months while simultaneously tightening batch-to-batch consistency specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Carbon Black Market |
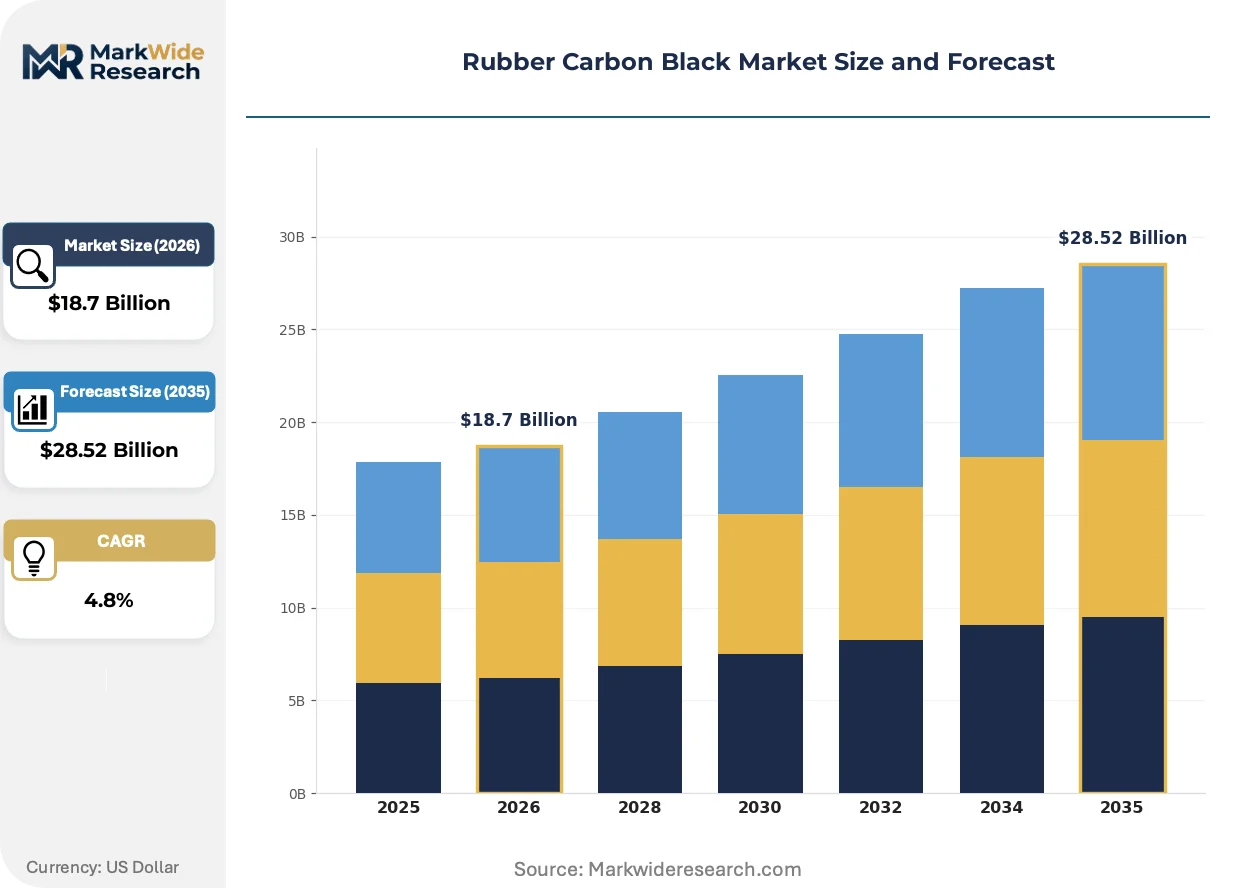
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Abrasion Furnace, Low Abrasion Furnace, Thermal Black, Acetylene Black End Use Industry: Automotive Tires, Industrial Rubber Products, Footwear, Coatings Grade: Standard Grade, Specialty Grade, Super Specialty Grade, Reinforcement Grade Form: Powder, Granular, Pellet, Liquid |
| Companies Covered | Cabot Corporation, Birla Carbon, Orion Engineered Carbons GmbH, Continental Carbon Company, Tokai Carbon Co. Ltd, Jiangxi Black Cat Carbon Black Co. Ltd, OCI Company Ltd, Phillips Carbon Black Limited, OMSK Carbon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Carbon Black Market Strategic Shifts
Digital process control and sustainable feedstock sourcing are converging to redefine production economics, while regulatory chemistry limits and buyer consolidation reshape competitive requirements.
Plasma-carbon black synthesis is converging with renewable methane feedstocks to enable near-zero Scope 1 emission production. Pilot facilities in Scandinavia are validating plasma arc technology at 5,000-tonne annual scale. This pathway is converging with tire OEM science-based targets, compressing the timeline for fossil-derived furnace black displacement in premium supply chains.
The EU Green Deal's industrial emissions directive is mandating continuous emissions monitoring and best available technique upgrades across carbon black manufacturing. German and Dutch facilities face 2027 compliance deadlines for NOx and SOx stack limits. High-abrasion furnace producers serving truck tire OEMs are accelerating wet-scrubbing retrofits to avoid qualification suspension.
Long-term offtake contracting is displacing spot market purchasing among tier-one tire manufacturers. Procurement teams at Continental and Bridgestone are locking 36-48 month supply agreements with volume-floor guarantees. This concentration is most visible in Germany and Japan, where single-source qualification protocols now dominate commercial negotiations.
Rubber Carbon Black Market Segmentation
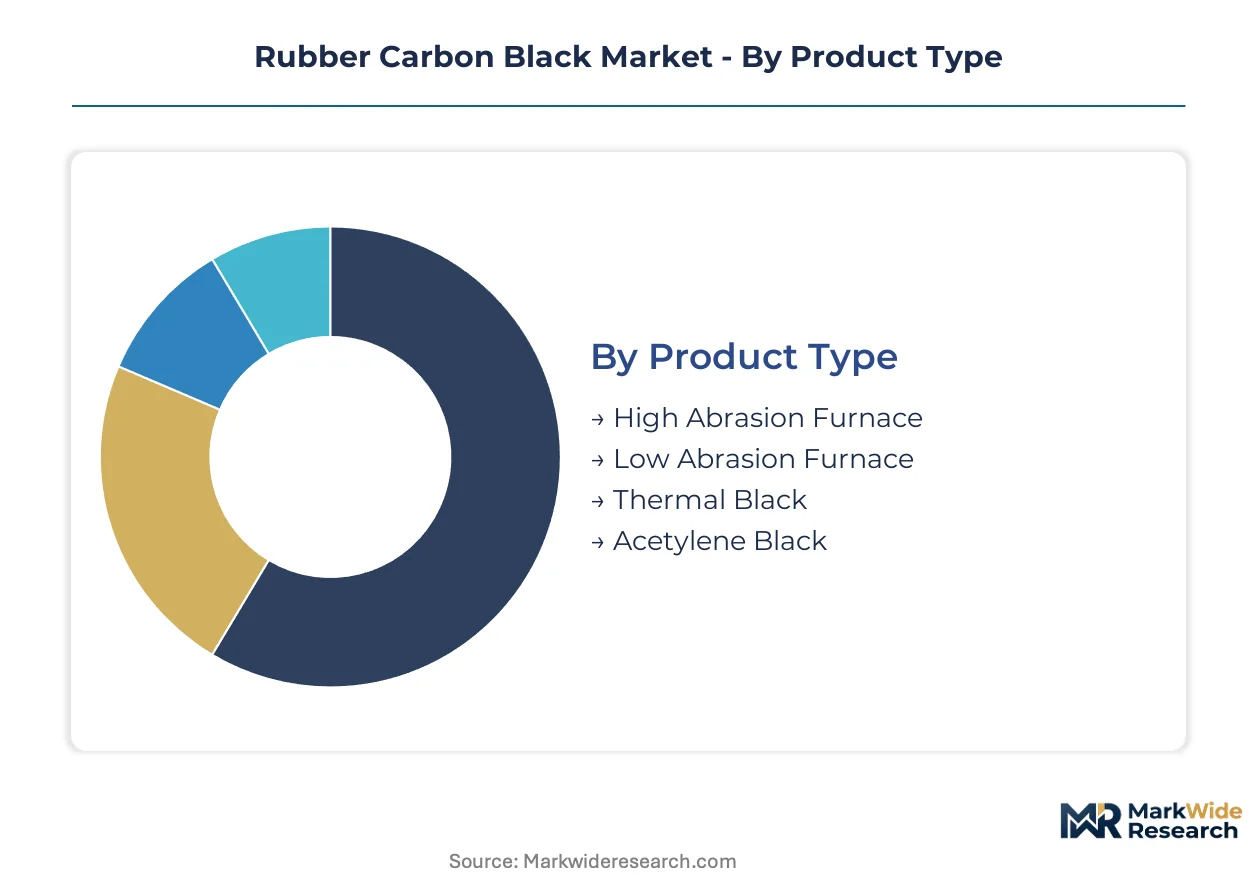
Rubber carbon black segmentation reflects divergent certification burdens across tire OEM qualification protocols and industrial compounder specifications. Each dimension carries distinct margin structures and supply chain requirements that determine competitive positioning.
Product Type:
REACH registration and EPA Clean Air Act compliance create tiered regulatory burdens across furnace technologies, with emission-intensive processes facing steeper capital requirements.
- High Abrasion Furnace:Reinforcing carbon black produced through oil-furnace combustion with surface areas of 70-150 m²/g and particle sizes of 20-40 nanometers. Passenger and truck tire tread formulations in Germany and Japan concentrate demand, driven by extended replacement cycles for electric vehicles requiring superior durability.
- Low Abrasion Furnace:Medium-reinforcement grade with surface areas of 35-65 m²/g, optimized for tire carcass and sidewall compounds. Industrial rubber belt and hose manufacturers in India pull volume through cost-sensitive procurement channels.
- Thermal Black:Produced via natural gas thermal decomposition with larger particle sizes of 120-500 nanometers and lower surface areas of 7-12 m²/g.
- Acetylene Black:High-purity conductive grade derived from acetylene decomposition, serving premium battery seal and cable shielding applications.
High Abrasion Furnace sits at the top of the volume ranking, with Acetylene Black climbing the fastest on electric vehicle conductivity demand.
End Use Industry:
Customer concentration and contract duration vary sharply across end-use segments, with automotive procurement consolidation reshaping supplier relationships.
- Automotive Tires:Accounts for the dominant share of rubber carbon black consumption, spanning passenger, truck, and off-road tire tread, carcass, and sidewall compounds. Long-term offtake agreements with Continental and Bridgestone in Germany and Japan are compressing spot market liquidity.
- Industrial Rubber Products:Conveyor belts, hoses, seals, and gaskets require consistent batch-to-batch properties for dynamic load applications. Indian manufacturing clusters in Gujarat and Maharashtra are scaling domestic furnace capacity to serve localized supply chains.
- Footwear:Soling compounds and rubber boot manufacturing utilize lower-specification grades with less stringent consistency requirements.
- Coatings:Pigment applications in automotive and industrial finishes demand precise dispersion characteristics and UV stability thresholds.
Automotive Tires dominates revenue concentration, though Industrial Rubber Products is expanding most quickly on India domestic capacity buildout.
Grade:
Margin stratification aligns with purity thresholds and OEM qualification intensity, with specialty grades commanding substantial premiums over commodity reinforcement material.
- Standard Grade:General-purpose reinforcing carbon black meeting baseline ASTM specifications for tensile strength and abrasion resistance. Volume tire production in India and Thailand absorbs the majority of output through price-sensitive procurement.
- Specialty Grade:Low-PAH formulations and conductivity-controlled variants serving REACH-compliant European compounders and electric vehicle component manufacturers. Premium positioning reflects extended qualification timelines and batch certification requirements.
- Super Specialty Grade:Ultra-high purity material for medical, food-contact, and aerospace elastomer applications with stringent extractable limits.
- Reinforcement Grade:High-structure variants optimized for heavy-duty truck tire and mining equipment tread compounds requiring maximum durability.
Standard Grade leads absolute volume, while Specialty Grade shows the steepest expansion trajectory on regulatory chemistry limits and EV penetration.
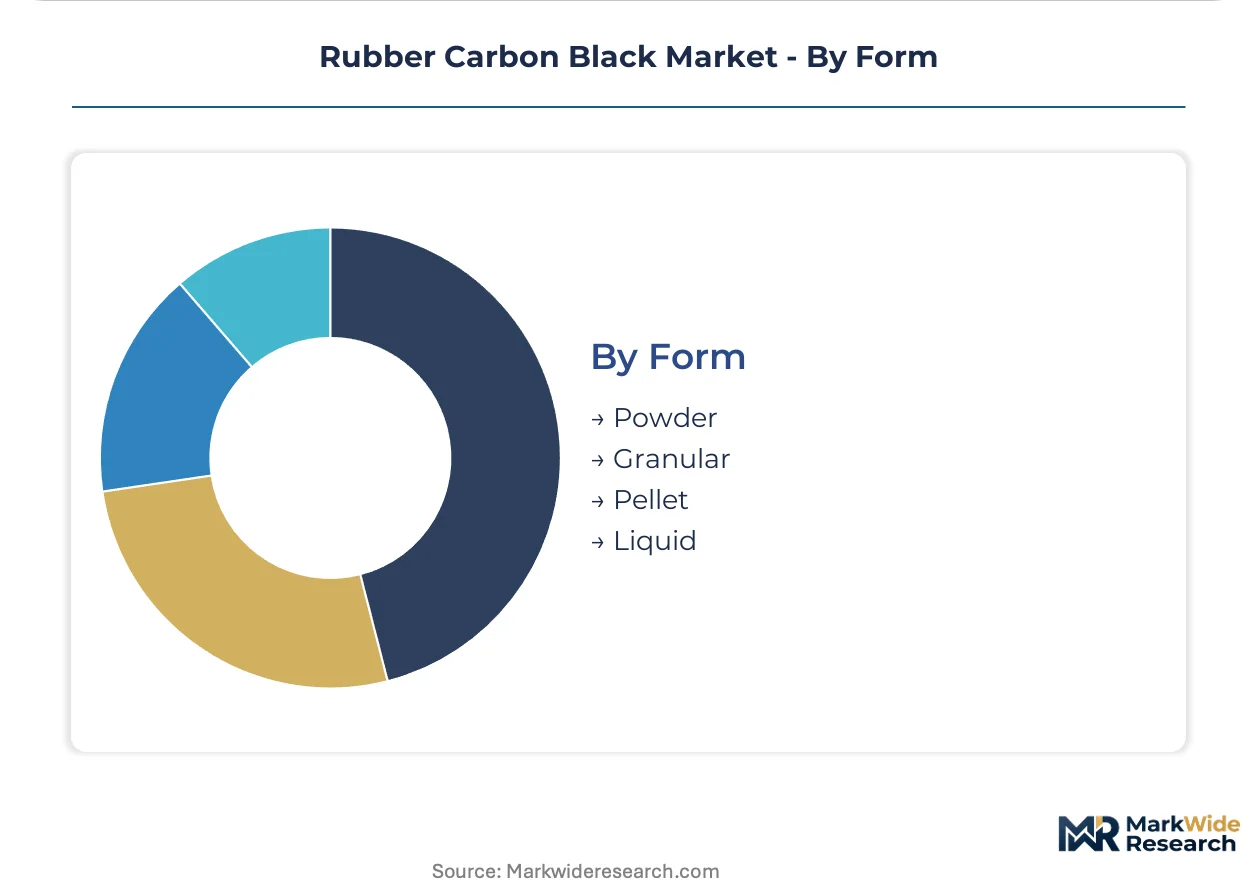
Form:
Logistics infrastructure and handling economics determine form selection, with dense-phase pneumatic conveying systems at tire plants driving format standardization.
- Pellet:Hard-pellet morphology optimized for bulk pneumatic conveying and automated handling at high-volume tire manufacturing facilities. Dense-phase systems at Continental plants in Germany favor this format for dust minimization and flow consistency.
- Powder:Fine particulate form retaining niche applications in coatings and small-batch industrial compounding where dispersion speed outweighs handling costs.
- Granular:Intermediate density format for regional tire plants lacking dedicated pneumatic infrastructure.
- Liquid:Pre-dispersed carbon black concentrates for water-based coating systems and specialty ink formulations.
Pellet form holds the volume advantage, with Liquid gaining share fastest on coatings industry automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Combustion engineering talent clusters in Germany and India anchor furnace black production networks. EPA and EU Green Deal emission mandates reshape capital deployment across manufacturing bases. Tire OEM qualification protocols concentrate procurement relationships in specific industrial corridors.
United States
Gulf Coast petrochemical integration sustains feedstock access for furnace black producers serving domestic tire plants. EPA Clean Air Act enforcement tightens NOx stack limits, forcing wet-scrubbing retrofits at Texas and Louisiana facilities. Houston-area manufacturing clusters absorb reinforcement-grade volume for regional tire compounding operations.
Germany
Automotive OEM science-based targets pull specialty-grade carbon black through extended qualification channels. EU Green Deal industrial emissions directives mandate continuous monitoring upgrades with 2027 compliance deadlines. Cologne-Düsseldorf-Ruhr industrial corridor hosts concentrated furnace capacity serving Continental and Bridgestone supply chains.
India
Domestic tire capacity multiplication at Apollo Tyres, MRF, and JK Tyre drives reinforcement-grade absorption through localized procurement. Central Pollution Control Board stack emission norms govern Gujarat and Maharashtra manufacturing clusters. Mundra and Hazira port-adjacent facilities scale furnace output for export-competitive logistics.
China
Dual carbon goals and MIIT industrial efficiency standards constrain new furnace black capacity approvals. Yangtze River Delta tire manufacturing concentration pulls volume through domestic supply chains. Shandong Province carbon black clusters face emissions intensity reduction mandates under provincial environmental bureaus.
Japan
Premium tire formulation requirements sustain specialty-grade premiums through METI-supported quality certification protocols. Kansai industrial belt hosts integrated rubber compound development facilities. Osaka-based tire OEM technical centers compress supplier approval timelines while tightening batch consistency specifications.
Rubber Carbon Black Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across furnace black production tiers. Market structure concentrates volume leadership among three to four integrated feedstock players while mid-scale specialists occupy specialty-grade niches. Strategic archetypes split between captive refinery-integrated producers, regional furnace network operators, and conductivity-grade specialists. Competitive moves center on furnace emission retrofit cycles and long-term offtake contracting with tire OEM procurement teams.
Within the integrated feedstock tier, Birla Carbon and Cabot Corporation exemplify scale-driven positioning through captive supply relationships. Orion Engineered Carbons GmbH occupies a specialty-grade position serving premium formulation requirements. These three anchors represent divergent strategic postures: volume leadership through upstream integration, geographic network density, and technical specification intensity respectively.
| Leading Market Players |
|---|
| Cabot Corporation |
| Birla Carbon |
| Orion Engineered Carbons GmbH |
| Continental Carbon Company |
| Tokai Carbon Co. Ltd |
| Jiangxi Black Cat Carbon Black Co. Ltd |
| OCI Company Ltd |
| Phillips Carbon Black Limited |
| OMSK Carbon Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting by Continental and Bridgestone procurement teams is compressing spot market liquidity and forcing supply reconfiguration toward volume-floor guarantees, which hardens price floors for integrated producers while squeezing margin predictability for non-captive suppliers.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade material through localized supply chain absorption. Contract-based long-term offtake dominates automotive tire procurement, with price differentiation driven by REACH-compliant low-PAH certification and volume scale commitments. Pricing pressure stems from silica-silane substitution in passenger green tire formulations, with Indian domestic tire manufacturers exhibiting highest price sensitivity and European specialty compounders showing lowest.
Supply Chain Analysis
Carbon black pellet returns and off-spec material flows from tire plant dense-phase conveying systems feed back into furnace feedstock streams for reprocessing. Supply concentrates in India, China, and the United States, with production drawing from coal tar, petroleum residue, and natural gas feedstocks. Single-source vulnerability runs through Gulf Coast petrochemical integration points. Distribution runs through bulk pneumatic terminals at port-adjacent manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electric vehicle battery pack seals and charging infrastructure cables pull demand toward conductivity-controlled specialty grades with surface area thresholds above 125 m²/g.
For Market Incumbents: Deploy wet-scrubbing retrofit cycles ahead of EU Green Deal 2027 compliance deadlines to defend qualification status with German and Dutch tire OEMs. Deepen captive refinery relationships to buffer feedstock volatility, while accelerating plasma-carbon black pilot scale-up to preempt fossil-derived furnace displacement in premium supply chains. For New Entrants and Emerging Players: Mid-scale Indian industrial rubber compounders underserved by integrated majors present the most penetrable entry point. Target Gujarat and Maharashtra manufacturing clusters with hard-pellet logistics optimization and localized technical service capabilities, leveraging PLI scheme alignment for advanced chemistry cell manufacturing demand. For Investors and Strategic Acquirers: Asymmetric upside sits with plasma-arc technology specialists converging with renewable methane feedstock pathways. Five-to-ten-year viability favors acquisition targets with proven pilot-scale validation and tire OEM science-based target alignment. Monitor plasma-carbon black offtake contracting announcements from Scandinavian pilot facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive coal tar and petroleum residue access buffers margin compression from crude oil benchmark swings. |
| Wet-Scrubbing Retrofit Deployment | EPA and EU Green Deal compliance sustains qualification status with Continental and Bridgestone procurement teams. |
| Specialty Grade Capacity Expansion | Surface area above 125 m²/g captures electric vehicle battery seal and charging cable premium positioning. |
| Plasma-Arc Pilot Scale-Up | Renewable methane feedstock convergence enables near-zero Scope 1 emission production for tire OEM targets. |
| Long-Term Offtake Contracting | Volume-floor guarantees with Apollo Tyres and MRF lock Indian domestic capacity absorption. |
Study Parameters
Coverage spans India, Germany, the United States, and China, with primary inputs from each combining interviews with tire procurement directors, carbon black plant managers, furnace control engineers, and rubber compounder technical leads alongside secondary validation from customs trade data, EPA enforcement records, EU ETS emissions disclosures, and tire OEM sustainability reports. Bottom-up volume modeling triangulates with top-down value chain analysis.
Granularity extends to product type, end-use industry, grade tier, and form factor across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic elasticity assumptions. Forecast inputs incorporate REACH aromatic oil limit enforcement intensity, India PLI scheme disbursement trajectories, and silica-silane substitution elasticity in passenger tire tread compounds.
Underlying measurement precision varies by segment; specialty-grade and super-specialty-grade carry tighter precision than standard-grade given extended qualification timeline documentation. Forecasts reflect assumptions on feedstock price correlation, regulatory enforcement schedules, and OEM approval cycle compression. Practitioners should monitor plasma-carbon black offtake announcements, EU Green Deal facility compliance certifications, and India domestic tire capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Polybutadiene Elastomers Market
Rubber
Liquid Polybutadiene Market
Rubber
Rubber Splicing Tape Market
Rubber
Synthetic Rubber Market
Rubber
Polyisoprene Rubber Market
Rubber
Rubber Rollers Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Global Cast Elastomers Market
Rubber
Tire Reinforcement Materials Market
Rubber
Global Automotive Elastomers Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Choppers Market
Rubber
Europe Neoprene Market