
 Scrim Reinforced Films Market | 2026-2036
Scrim Reinforced Films Market Size, Share, and Industry Trends Forecast 2026-2036
Scrim Reinforced Films Market Outlook
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers of scrim reinforced films, forcing reformulation investments that favor larger producers. Berry Global Group, Inc. leverages its integrated resin-to-film manufacturing footprint to absorb these regulatory costs without margin erosion. Saint-Gobain Performance Plastics anchors its position through specialized high-tensile formulations for containment applications. Amcor plc competes by extending its sustainability-certified product lines across multiple regional markets.
Scrim reinforced films are composite materials manufactured by embedding an open-mesh fabric scrim between layers of thermoplastic substrates such as polypropylene or polyethylene, typically achieving tensile strengths exceeding 1000 N/5cm for heavy-duty grades. These structures serve primarily as durable, weather-resistant barriers in construction enclosures, agricultural covers, and industrial packaging systems. Polyethylene formulations dominate volume production due to cost efficiency and chemical resistance, while polypropylene variants capture premium positioning in building wraps where breathability and UV stability determine specification. The thickness dimension stratifies across lightweight agricultural row covers, medium-duty transportation tarpaulins, and heavy-duty containment liners, with margin pools concentrating in ultra-heavy grades for inflatable structures where fabrication complexity limits supplier entry.
The EPA governs volatile organic compound emissions from film manufacturing facilities in the United States, while the EU Green Deal and REACH collectively mandate recyclability thresholds and restricted substance limits across European supply chains. These frameworks elevate compliance costs for commodity producers while creating specification advantages for manufacturers with certified circular material flows. Stakeholders must monitor evolving extended producer responsibility schemes and their impact on regional cost structures.
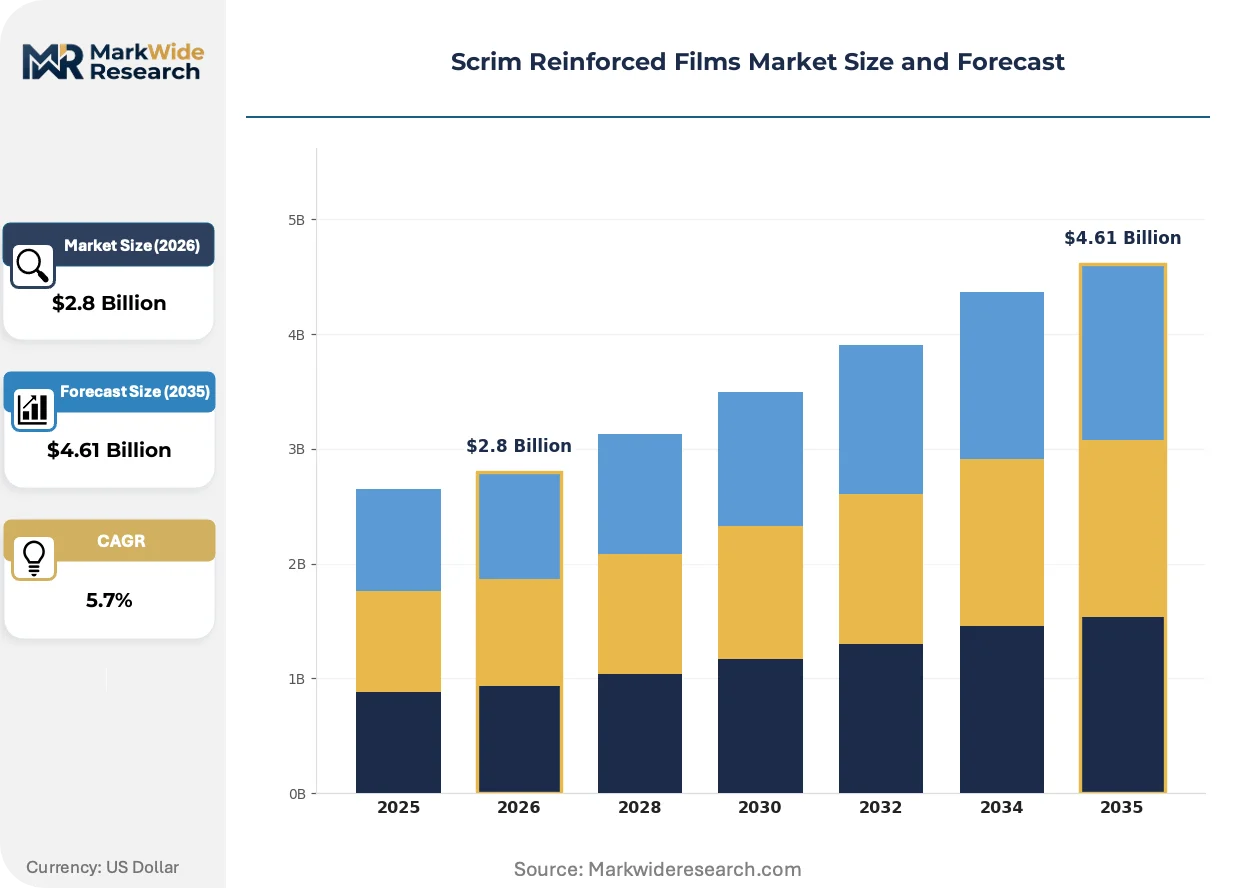
Market Dynamics
The EU Green Deal's recyclability mandates are compressing margins for commodity-grade producers while creating specification premiums for manufacturers with certified circular material flows. Construction sector procurement teams now require documented carbon footprints for building envelope materials.
Growth Catalysts
- REACH compliance thresholds:European manufacturers reformulating polypropylene scrim layers to eliminate restricted phthalates are capturing specification share in building wrap applications.
- Agricultural cover demand:German greenhouse operators are replacing glass with UV-stabilized scrim films to reduce structural load and improve thermal management.
- Industrial packaging:Heavy-duty transportation tarpaulins for chemical logistics are specifying high-tensile polyethylene scrim grades exceeding 1500 N/5cm tear resistance.
Market Restraints
- Resin cost volatility:Polypropylene feedstock prices tied to naphtha cracking economics create margin compression for non-integrated film converters.
- Technical limitation:Current adhesive bonding between scrim mesh and outer film layers degrades below -30°C, excluding Arctic construction applications.
- Substitution threat:Woven polypropylene laminates are displacing scrim films in lower-specification agricultural row cover segments.
Strategic Opportunities
- Underpenetrated geography:Indian cold chain infrastructure expansion is creating first-time demand for insulated scrim-reinforced transport covers.
- Regulatory tailwind:The EU's Construction Products Regulation (CPR) fire-rating requirements are opening premium positioning for halogen-free flame-retardant scrim formulations.
- Technology convergence:RFID-embedded scrim films are integrating track-and-trace capabilities into industrial packaging for pharmaceutical distribution.
Industry Challenges
- Certification timeline:Extended producer responsibility (EPR) scheme registration in France and Germany requires 12-18 month compliance documentation for imported films.
- Skill gap:Multi-layer extrusion operators with scrim tensioning expertise are in short supply across Central European manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scrim Reinforced Films Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, PVC, Nylon End Use Industry: Construction, Packaging, Agriculture, Transportation Thickness: Lightweight, Medium, Heavy-duty, Ultra-heavy Application: Tarpaulins, Containment, Building wraps, Inflatable structures |
| Companies Covered | Berry Global Group, Inc., Amcor plc, Saint-Gobain Performance Plastics, SWM International, Taghleef Industries, Jindal Films Ltd., Raven Industries, Inc., Sealed Air Corporation, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scrim Reinforced Films Market Strategic Shifts
Active reformulation of core materials and embedding of functional layers are transforming scrim film specifications. Manufacturers are racing to align product architectures with tightening regulatory thresholds.
Co-extruded barrier layers with ethylene vinyl alcohol (EVOH) cores are integrating oxygen and moisture resistance into agricultural films without separate lamination steps. Berry Global Group and Saint-Gobain Performance Plastics are qualifying these structures for modified atmosphere packaging in produce logistics. The technology is integrating gas-flush compatibility that extends strawberry shelf life from 7 to 14 days in European retail distribution.
REACH SVHC candidate list expansions are forcing substitution of conventional UV stabilizers with benzotriazole-free alternatives in outdoor-grade scrim films. German building inspectors are now rejecting shipments containing non-compliant additive packages. The construction sector is responding by demanding full material disclosure certificates from film suppliers prior to contract award.
Consolidated buying by European construction consortiums is compressing supplier margins while elevating technical service requirements. Mid-sized distributors are losing specification influence as direct manufacturer-to-contractor relationships replace traditional channel structures. France and the Netherlands show the fastest channel compression, with three major infrastructure projects awarding sole-source scrim film contracts in 2024.
Scrim Reinforced Films Market Segmentation
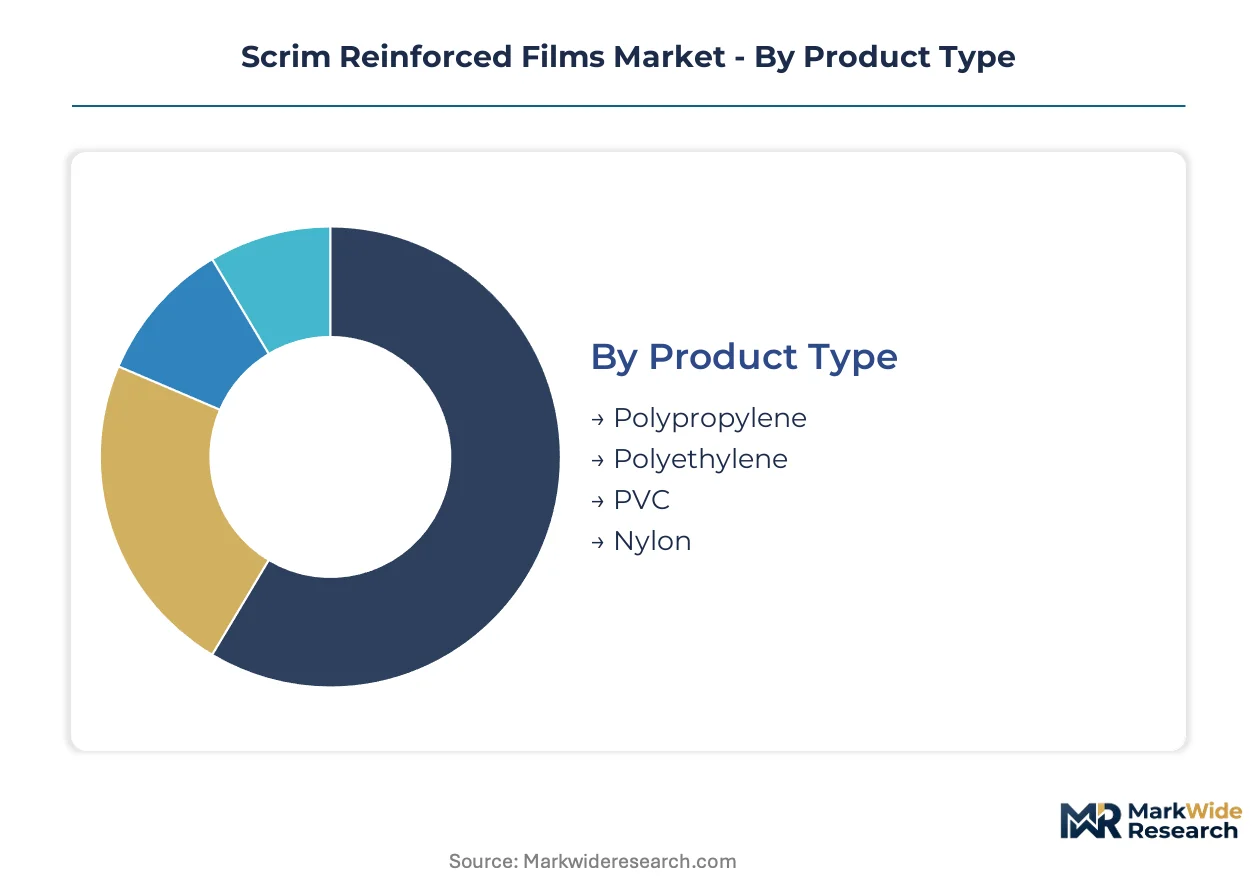
Scrim reinforced films stratify across multiple technical dimensions that determine specification premiums and procurement patterns. Material chemistry, thickness grades, and end-use performance requirements create distinct margin pools that suppliers navigate through differentiated formulation strategies.
Product Type:
Material selection hinges on cost-performance tradeoffs between chemical resistance, UV stability, and recyclability compliance under EU Green Deal mandates.
- Polypropylene:Open-mesh scrim layers embedded in biaxially oriented polypropylene substrates deliver breathability and dimensional stability for building wrap specifications. German construction consortiums now mandate REACH-compliant additive packages, disqualifying conventional phthalate-stabilized grades from public infrastructure tenders.
- Polyethylene:Linear low-density polyethylene formulations dominate volume production through cost efficiency and moisture barrier performance. Demand concentrates in heavy-duty transportation tarpaulins where tear resistance exceeding 1500 N/5cm determines logistics operator procurement decisions.
- PVC:Plasticized vinyl scrim structures offer flame-retardant properties for containment applications in chemical processing facilities.
- Nylon:Polyamide scrim layers provide puncture resistance for inflatable structure specifications where fabrication complexity limits supplier entry.
Volume sits with Polyethylene; growth tilts toward Polypropylene as recyclability certifications gain procurement weight.
End Use Industry:
Application environments dictate performance thresholds ranging from weather resistance to load-bearing capacity.
- Construction:Building envelope specifications require documented carbon footprints and fire-rating compliance under EU Construction Products Regulation. French and Dutch infrastructure projects are consolidating procurement through direct manufacturer-to-contractor relationships that bypass traditional distribution channels.
- Packaging:Modified atmosphere packaging with EVOH barrier layers extends produce shelf life in European retail distribution networks.
- Agriculture:German greenhouse operators are replacing glass with UV-stabilized scrim films to reduce structural load and improve thermal management.
- Transportation:Cold chain logistics in India is creating first-time demand for insulated scrim-reinforced transport covers.
Construction commands the largest revenue pool; Agriculture is expanding most quickly as protected cultivation spreads across Northern Europe.
Thickness:
Fabrication complexity and raw material intensity separate margin tiers across the thickness spectrum.
- Lightweight:Agricultural row covers and temporary weather protection specify thin-gauge films where woven polypropylene laminates increasingly displace scrim constructions on cost.
- Medium:Transportation tarpaulins and general-purpose containment balance durability against handling weight for logistics efficiency.
- Heavy-duty:Extended-service building wraps and industrial curtains require multi-layer co-extrusion with tension-controlled scrim embedding.
- Ultra-heavy:Inflatable structures and architectural membranes command premium positioning where specialized bonding equipment and operator expertise limit competitive entry.
Medium thickness generates the highest unit volumes; Ultra-heavy captures the steepest margin expansion as technical barriers protect pricing power.
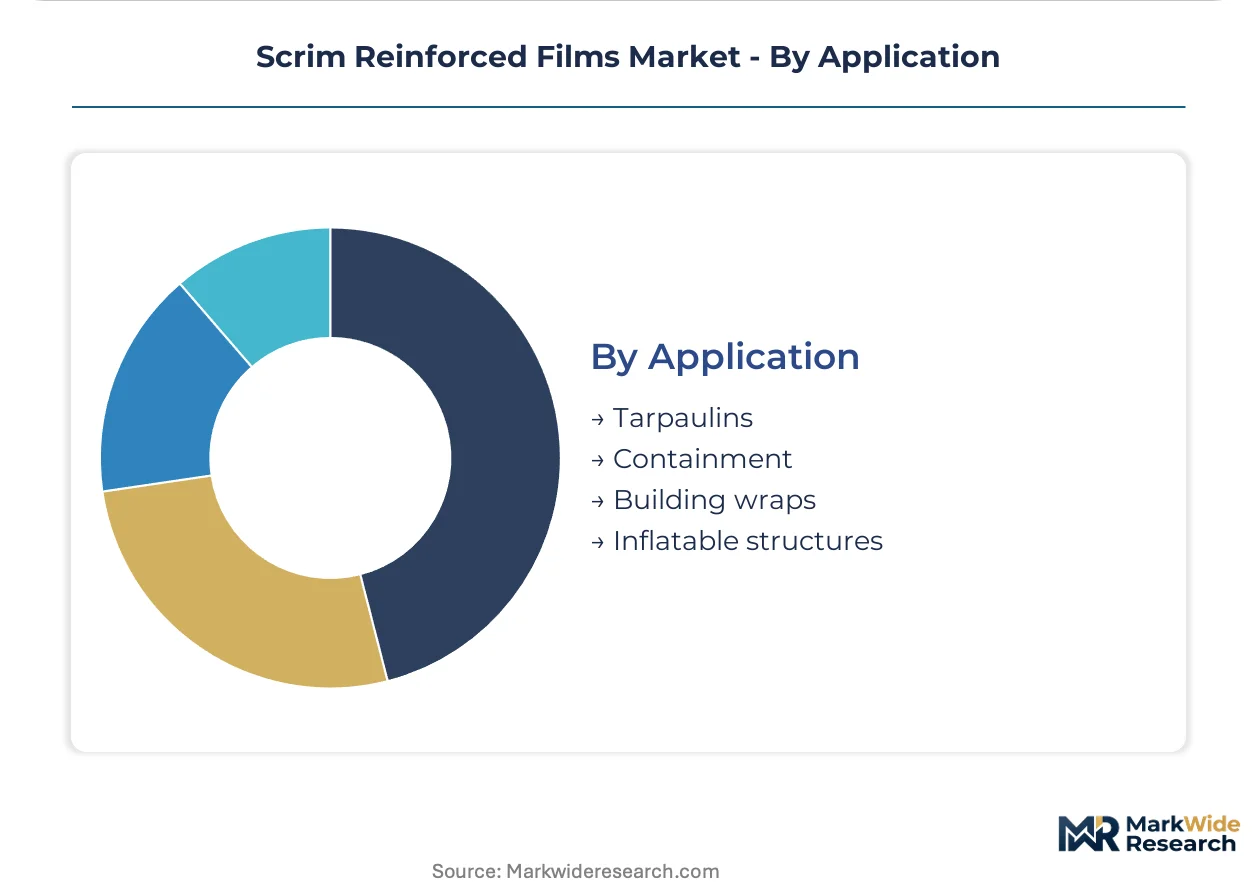
Application:
Functional requirements determine whether specifications prioritize barrier properties, tensile strength, or deployability characteristics.
- Tarpaulins:Transportation and storage covers specify high-tensile polyethylene grades with reinforced eyelets and heat-sealed seams for load-securement compliance.
- Containment:Environmental remediation and chemical processing applications demand halogen-free flame-retardant formulations qualifying under EU fire-rating standards.
- Building wraps:Weather-resistant barriers require vapor permeability control and UV stabilization for multi-year exposure durability.
- Inflatable structures:Architectural and recreational applications specify welded seam integrity and pressure-retention performance where fabrication defect rates determine supplier selection.
Tarpaulins anchor current production volumes; Building wraps are gaining share fastest as energy-efficiency retrofits accelerate across European housing stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free zones in the Pearl River Delta concentrate Chinese scrim film manufacturing capacity for export-oriented production. German chemical parks along the Rhine corridor anchor European formulation expertise. Indian special economic zones in Gujarat and Maharashtra are attracting first-mover investments in cold-chain infrastructure films.
Germany
German greenhouse operators are replacing glass with UV-stabilized scrim films to reduce structural load and improve thermal management. REACH compliance thresholds under ECHA mandates are forcing reformulation of polypropylene scrim layers to eliminate restricted phthalates. The Rhine-Main industrial corridor hosts concentrated film extrusion capacity serving building wrap specifications for public infrastructure tenders.
United States
EPA volatile organic compound emission limits govern film manufacturing facilities across the Gulf Coast petrochemical belt. Construction sector procurement teams in Texas and California now require documented carbon footprints for building envelope materials. The Houston Ship Channel cluster integrates resin production with film extrusion for heavy-duty transportation tarpaulins serving chemical logistics operators.
China
Dual carbon goals under MEE oversight are accelerating domestic demand for recyclable polypropylene formulations in agricultural applications. Yangtze River Delta manufacturing zones export medium-duty scrim films to Southeast Asian construction markets. Zhejiang province hosts the highest concentration of multi-layer co-extrusion lines with tension-controlled scrim embedding capability.
India
Cold chain infrastructure expansion under PLI scheme incentives is creating first-time demand for insulated scrim-reinforced transport covers. BIS certification requirements for flexible packaging materials are elevating compliance costs for imported films. The Sanand-Gujarat industrial belt is emerging as a fabrication hub for medium-gauge agricultural row covers serving domestic protected cultivation.
France
Extended producer responsibility scheme registration under French environmental regulations requires 12-18 month compliance documentation for imported films. EU Construction Products Regulation fire-rating requirements are opening premium positioning for halogen-free flame-retardant scrim formulations. The Hauts-de-France region concentrates building envelope specification influence through consolidated procurement by infrastructure consortiums.
Scrim Reinforced Films Market Competitive Environment
North American producers anchor one tier; European specialists hold formulation-driven positioning in premium building wrap segments. The vendor base separates into integrated resin-to-film manufacturers, specialized high-tensile formulators, and regional converters serving commodity agricultural applications. Three archetypes dominate: vertically integrated petrochemical-film operations, technology-licensed regional fabricators, and niche inflatable structure specialists. Competitive moves concentrate on backward integration into resin production and direct manufacturer-to-contractor relationship building that bypasses traditional distribution.
Within the integrated manufacturing tier, Berry Global Group, Inc. and Saint-Gobain Performance Plastics exemplify divergent strategic positions. Berry Global leverages captive resin supply to absorb regulatory cost pressures without margin erosion across multiple regional markets. Saint-Gobain occupies a specialized position through high-tensile formulation expertise for containment and architectural membrane specifications where fabrication complexity limits competitive entry. Amcor plc represents the sustainability-certified vector, extending circular material flow certifications across European procurement channels where documented recyclability determines contract eligibility.
| Leading Market Players |
|---|
| Berry Global Group, Inc. |
| Amcor plc |
| Saint-Gobain Performance Plastics |
| SWM International |
| Taghleef Industries |
| Jindal Films Ltd. |
| Raven Industries, Inc. |
| Sealed Air Corporation |
| Huhtamaki Group |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement by European construction consortiums has compressed supplier margins while elevating technical service requirements, creating a contract-based pricing structure where multi-year offtake agreements dominate volume allocation. Direct manufacturer-to-contractor relationships in France and the Netherlands now bypass traditional distribution channels entirely.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ultra-heavy gauge inflatable structure films where specialized bonding equipment and operator expertise limit competitive entry. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified polypropylene building wraps from commodity polyethylene tarpaulins and lightweight agricultural row covers. Price differentiation hinges on recyclability certification under EU Green Deal mandates and tensile strength grade, with German public infrastructure tenders disqualifying non-compliant additive packages. Cost compression in medium-duty transportation segments is intensifying because woven polypropylene laminates displace scrim films in lower-specification agricultural applications. Agricultural greenhouse operators show highest price sensitivity due to thin margins in protected cultivation, while containment applications for chemical processing demonstrate lowest sensitivity given specification-critical performance requirements.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and chemical logistics operators mandate multi-supplier qualification for heavy-duty transportation tarpaulins exceeding 1500 N/5cm tear resistance. Manufacturing concentration centers on Germany, China, and the United States, with the Rhine-Main corridor hosting formulation expertise, the Yangtze River Delta anchoring export-oriented co-extrusion capacity, and the Gulf Coast petrochemical belt integrating resin production with film extrusion. Raw material dependencies draw from naphtha-derived polypropylene feedstock, linear low-density polyethylene resin, and benzotriazole-free UV stabilizers substituting conventional additives under REACH SVHC expansions. Single-source vulnerability concentrates in ultra-heavy gauge fabrication equipment where European and Chinese suppliers control tension-controlled scrim embedding technology. Distribution runs through direct manufacturer-to-contractor channels for construction specifications, with traditional distributors retaining influence only in commodity agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in multi-layer co-extrusion capacity with tension-controlled scrim embedding capability are propping pricing power for qualified manufacturers. Extended lead times for specialized bonding equipment limit rapid capacity expansion.
For Market Incumbents: Anchor market position through captive supply of REACH-compliant additive packages and backward integration into resin production that absorbs regulatory cost pressures without margin erosion. Invest in direct relationship building with French and Dutch infrastructure consortiums that have consolidated procurement through sole-source contracts. Defend against woven polypropylene laminate substitution by qualifying co-extruded EVOH barrier layers for modified atmosphere packaging applications in produce logistics. For New Entrants and Emerging Players: The EU Construction Products Regulation fire-rating requirements in France open a window for halogen-free flame-retardant scrim formulations that incumbent commodity producers have been slow to develop. Target Indian cold chain infrastructure expansion under PLI scheme incentives where first-time demand for insulated scrim-reinforced transport covers lacks established supplier relationships. Enter through technology licensing partnerships with Zhejiang province co-extrusion specialists to bypass capital-intensive equipment acquisition barriers. For Investors and Strategic Acquirers: The window for entry favors mid-sized European formulators with certified circular material flows and established ECHA registration documentation. Long-term viability rests on positioning for extended producer responsibility scheme expansion across EU member states where compliance documentation timelines create competitive moats. Acquisition target archetype: German or French specialists with halogen-free flame-retardant certification and direct contractor relationships in infrastructure consortiums. Watch for BIS certification requirement expansion in India as signal for import substitution opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polypropylene supply absorbs REACH reformulation costs without margin erosion for Berry Global-scale operators. |
| Halogen-Free Flame-Retardant Certification | EU CPR compliance opens premium positioning in French containment applications where specification barriers limit entry. |
| Direct Manufacturer-to-Contractor Relationships | Channel compression in Netherlands infrastructure procurement bypasses distributor margin capture entirely. |
| RFID-Embedded Functional Layer Development | Track-and-trace integration addresses pharmaceutical distribution requirements in European cold chain logistics. |
| Indian Cold Chain Market Entry | PLI scheme incentives create first-mover advantage for insulated transport cover specifications in Gujarat and Maharashtra. |
Study Parameters
Multi-period observation of scrim film procurement patterns, regulatory filing timelines, and capacity utilization rates anchored the trend analysis, supplemented by interviews with plant managers at European extrusion facilities, procurement leads at German construction consortiums, distribution channel partners in agricultural supply networks, and technical R&D directors specializing in multi-layer co-extrusion. Secondary validation drew from ECHA REACH registration databases, EU Construction Products Regulation certification records, SEC 10-K filings of integrated resin-to-film manufacturers, and customs trade data tracking polyethylene and polypropylene film exports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for construction spending and agricultural protected cultivation area.
Input-output matrices modeled relationships between resin feedstock pricing, extrusion capacity expansion, and end-use demand across material chemistry, thickness grade, and application specifications over the projection horizon. Segmentation dimensions included product type, end-use industry, thickness tier, and geographic production cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating regulatory compliance cost pass-through assumptions and substitution threat parameters for competing material technologies. Industry-specific forecast inputs encompassed EPR scheme implementation timelines and BIS certification requirement evolution in Indian flexible packaging.
The model assumes a particular technology adoption path for benzotriazole-free UV stabilizer substitution; alternative pathways for conventional additive retention would alter the outlook for incumbent reformulation investments. Deviation in EU Green Deal recyclability mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Composites Cylinder Market
Composite Materials
Marine Composites Market
Composite Materials
Medical Composite Material Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Global Sports Composites Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Structural Composites Market
Composite Materials
Synthetic Rope Market