
 Prepreg Market | 2026-2036
Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Prepreg Market Intelligence
Defense contractors and urban air mobility developers are rotating toward thermoplastic prepregs as primary procurement archetypes. Toray Industries, Inc. dominates carbon fiber supply chains through backward integration into precursor manufacturing. Hexcel Corporation specializes in toughened epoxy formulations qualified for Boeing and Airbus platforms. Gurit Holding AG anchors wind energy demand through vacuum infusion-compatible product lines.
Prepreg denotes fiber reinforcement pre-impregnated with catalyzed resin, typically stored below minus eighteen degrees Celsius to arrest cure kinetics until autoclave or oven processing achieves full polymerization. Carbon fiber prepreg leads composite type value generation due to specific stiffness advantages in primary aircraft structures. Epoxy resin chemistry captures the largest product type position, though cyanate ester grades are gaining fastest in satellite and radar dome applications where dielectric performance governs selection. Thermal curing remains the dominant processing technique, yet out-of-autoclave vacuum infusion methods are displacing legacy protocols in wind blade fabrication.
FAA airworthiness directives and EASA CS-25 certification standards govern material qualification cycles for commercial aerospace prepregs. EPA hazardous air pollutant rules and REACH substance restrictions constrain solvent-based resin formulations, redirecting formulation investment toward waterborne and hot-melt alternatives. Stakeholders must monitor evolving OEM qualification timelines and regulator-driven substance bans to align R&D portfolios with accessible market segments.
Market Dynamics
Prepreg manufacturers confront a structural pivot as out-of-autoclave curing protocols gain aerospace qualification, compressing capital requirements for tier-two suppliers while reshaping resin formulation priorities toward lower-temperature activation chemistries.
Growth Catalysts
- EASA CS-25 certification pathways:Streamlined qualification timelines for thermoplastic prepregs are accelerating OEM adoption in narrow-body programs, reducing material substitution barriers.
- Wind turbine OEM consolidation in China:Domestic blade fabricators are scaling vacuum infusion-compatible prepreg consumption to capture offshore installation contracts.
- PEEK resin advancement:High-temperature thermoplastic matrices are penetrating engine nacelle applications previously reserved for thermoset epoxies.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petroleum feedstock indices, squeezing margin stability for mid-scale prepreg converters.
- Japanese precursor concentration:Three suppliers control over seventy percent of PAN precursor capacity, creating single-source vulnerability for European and North American fiber manufacturers.
- REACH substance restrictions:ECHA candidate list expansions threaten bisphenol-A derived epoxy formulations, forcing reformulation investments without guaranteed qualification continuity.
Strategic Opportunities
- Urban air mobility infrastructure:eVTOL airframe programs in Germany and the United States are specifying thermoplastic prepregs for crashworthiness and recyclability compliance.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive composites are incentivizing localized prepreg manufacturing investments within the European Union.
- Automotive structural battery enclosures:Electric vehicle platforms are adopting compression-molded thermoplastic prepregs for cell-to-pack architectures requiring thermal runaway containment.
Industry Challenges
- Autoclave operator certification scarcity:Qualified technicians for pressure-temperature profile management are concentrated at legacy aerospace tiers, constraining capacity expansion.
- FAA-EASA dual qualification timelines:Parallel certification tracks for new resin systems extend development cycles by eighteen to thirty-six months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepreg Market |
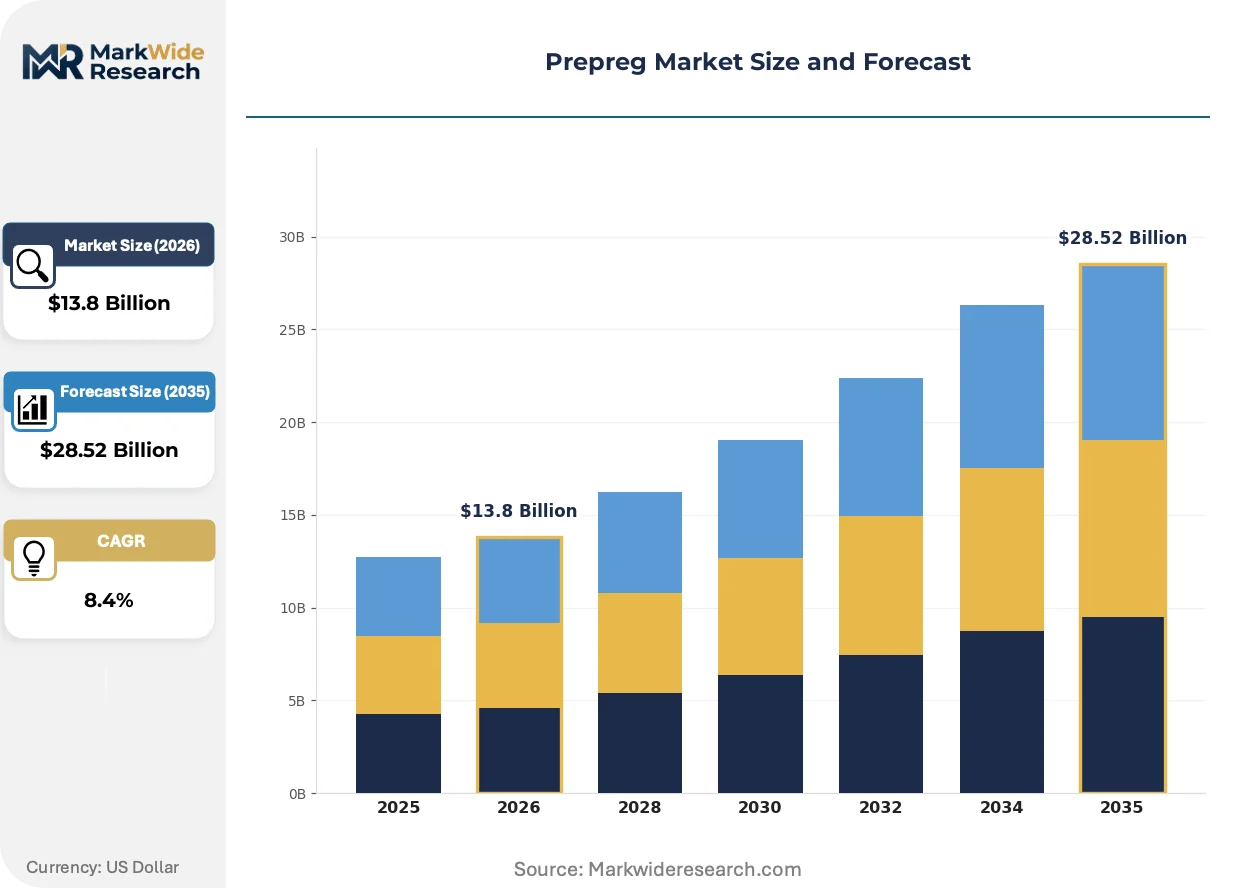
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyester, Cyanate Ester End User: Aerospace, Automotive, Sports, Wind Energy Composite Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber Processing Technique: Thermal Curing, Cold Pressing, Vacuum Infusion, Hand Layup |
| Companies Covered | SGL Carbon SE, Gurit Holding AG, Toray Industries, Inc., Owens Corning, Solvay S.A., Teijin Limited, Mitsubishi Chemical Corporation, Asahi Kasei Corporation, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepreg Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to redefine processing economics and qualification protocols across aerospace, wind, and emerging mobility verticals.
Out-of-autoclave epoxy formulations are displacing traditional autoclave-dependent prepregs in primary structure applications. Bombardier and Gulfstream business jet programs have qualified vacuum-only cure cycles for wing skins and pressure bulkheads. This transition is displacing capital-intensive autoclave infrastructure from tier-one supplier facilities, redistributing competitive advantage toward resin chemistry control.
REACH Annex XIV authorization requirements are forcing systematic substitution of styrene-based vinyl ester chemistries in marine and corrosion applications. ECHA sunset dates for diisocyanates in polyurethane hardeners are compressing formulation windows for wind blade adhesives and gelcoats. Nordic and Baltic manufacturers are responding fastest, piloting bio-based epoxy alternatives with DNV certification support.
Consolidated procurement through OEM direct material agreements is fragmenting distributor influence in aerospace supply chains. Airbus and Boeing are mandating qualified material supplier lists with locked pricing tiers, bypassing traditional composite distributors for carbon fiber and resin purchases. This concentration is most visible in Toulouse and Hamburg manufacturing clusters, where tier-one fabricators now contract resin systems directly with Hexcel and Solvay.
Prepreg Market Segmentation
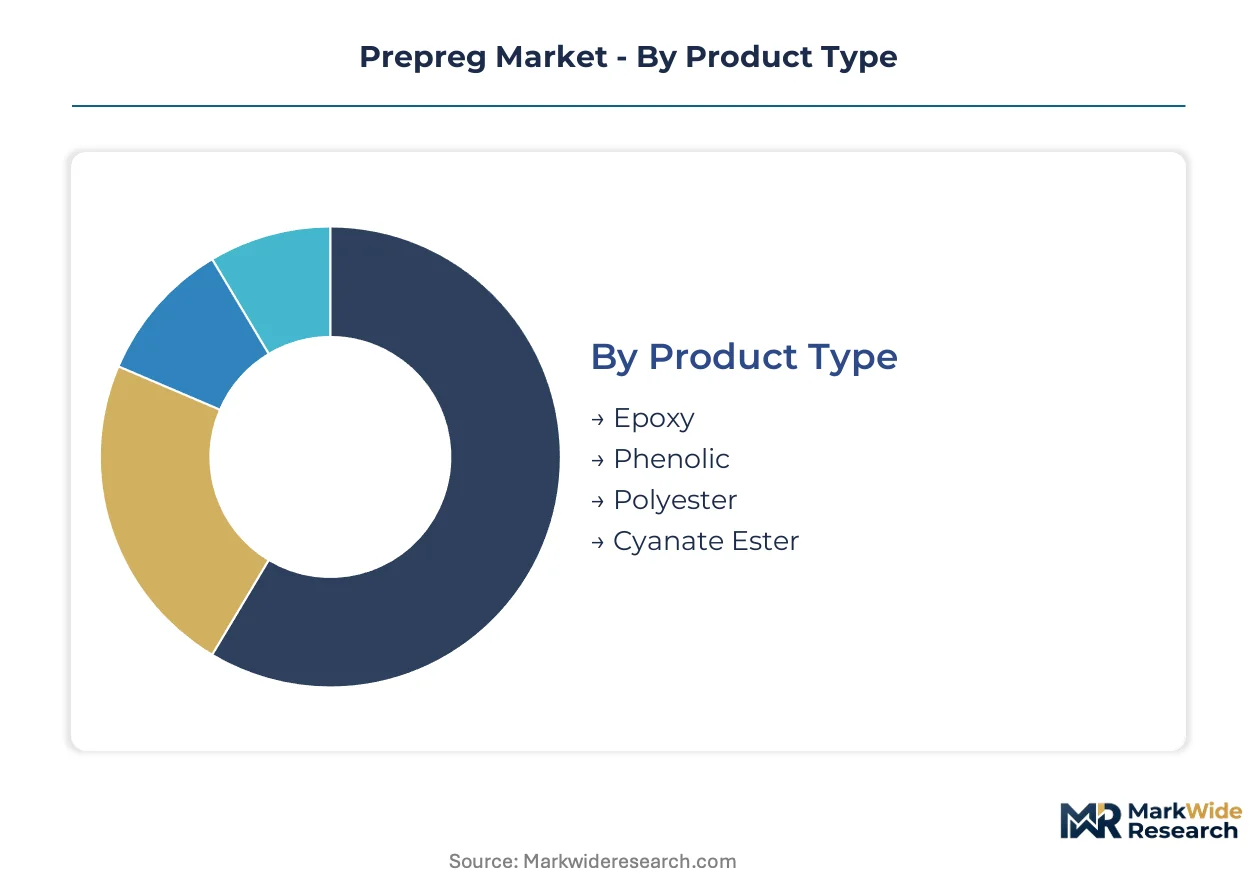
Prepreg procurement patterns diverge sharply across resin chemistry, reinforcement architecture, and curing protocols. Each segmentation axis carries distinct qualification barriers and geographic demand centers that reshape supplier priorities.
Product Type:
Epoxy formulations dominate domestic aerospace programs in France and Germany, while phenolic grades serve export-led marine and rail fire-safety specifications. Polyester and cyanate ester volumes concentrate in specialized satellite and radar applications with cross-border supply chains.
- Epoxy:Toughened formulations qualified for Boeing 787 and Airbus A350 primary structures command premium positioning. Hexcel and Solvay direct agreements with Toulouse and Hamburg manufacturing clusters anchor demand. REACH substance restrictions on bisphenol-A derivatives are forcing systematic reformulation toward waterborne alternatives.
- Cyanate Ester:Low dielectric loss characteristics suit satellite antenna substrates and phased-array radar domes where signal transparency governs selection. Demand concentrates in Bavaria and California defense corridors. ESA and NASA outgassing specifications create narrow qualification windows.
- Phenolic:Fire-smoke-toxicity compliance drives rail interior panel specifications in SNCF and Deutsche Bahn rolling stock programs.
- Polyester:Cost-sensitive marine and corrosion applications in Baltic shipyards favor vinyl ester hybrids with styrene reduction.
Epoxy commands the established base. The steepest expansion runs through cyanate ester grades penetrating low-observable and spaceborne platforms.
End User:
Volume scales separate capital-intensive aerospace qualification cycles from high-throughput automotive compression molding. Customer procurement maturity ranges from locked OEM direct agreements to fragmented distributor channels.
- Aerospace:FAA-EASA dual certification timelines extend eighteen to thirty-six months for new resin systems. Boeing and Airbus qualified material supplier lists bypass traditional distributors, concentrating purchasing power at tier-one fabricators in Everett, Charleston, Toulouse, and Hamburg.
- Wind Energy:Vacuum infusion-compatible prepregs serve blade fabricators scaling for offshore installation contracts. LM Wind Power and Vestas facilities in Denmark and Spain specify DNV-certified laminates with thirty-year fatigue performance guarantees.
- Automotive:Compression-molded thermoplastic prepregs for electric vehicle battery enclosures require thermal runaway containment specifications from NHTSA and UN ECE R100.
- Sports:Bicycle frame and ski manufacturers in Italy and Austria prioritize visual carbon weave aesthetics and rapid takt-time processing.
Aerospace retains margin leadership through qualification barriers. Wind energy delivers volume acceleration as Chinese OEM consolidation drives blade scaling.
Composite Type:
Fiber selection determines stiffness-to-weight ratios and electromagnetic signature management. Precursor supply concentration in Japan creates sourcing vulnerability for European and North American converters.
- Carbon Fiber:PAN-based intermediate modulus grades dominate primary aircraft structures. Toray Industries maintains backward integration into precursor manufacturing, controlling seventy percent of global capacity through Japanese, French, and US production assets.
- Glass Fiber:E-glass and S-glass variants serve wind blade spar caps and automotive underbody shields where cost efficiency outweighs stiffness premiums. Owens Corning and Jushi Group supply chains anchor US and Chinese blade fabrication.
- Aramid Fiber:Ballistic protection and pressure vessel applications specify DuPont Kevlar and Teijin Twaron for energy absorption and fragment containment.
- Natural Fiber:Flax and hemp reinforcements penetrate automotive interior panels and sporting goods with bio-based positioning for EU Green Deal compliance.
Carbon fiber absorbs the dominant value share. Natural fiber alternatives gain regulatory tailwinds from EU carbon border adjustment mechanisms.
Processing Technique:
Capital intensity separates autoclave-dependent aerospace protocols from out-of-autoclave methods displacing legacy infrastructure. Technician certification scarcity constrains capacity expansion at legacy tiers.
- Thermal Curing:Autoclave pressure-temperature profiles remain mandatory for primary structure qualification in FAA airworthiness directives. Bombardier and Gulfstream business jet programs have qualified vacuum-only cycles for wing skins, redistributing competitive advantage toward resin chemistry control.
- Vacuum Infusion:Out-of-autoclave epoxy formulations compress capital requirements for tier-two suppliers. Chinese wind blade fabricators scale vacuum infusion for offshore turbine contracts exceeding twelve megawatts.
- Cold Pressing:Automotive structural components specify rapid cycle times for high-volume electric vehicle platforms.
- Hand Layup:Marine and architectural applications retain manual processing for complex geometries and low-volume custom fabrication.
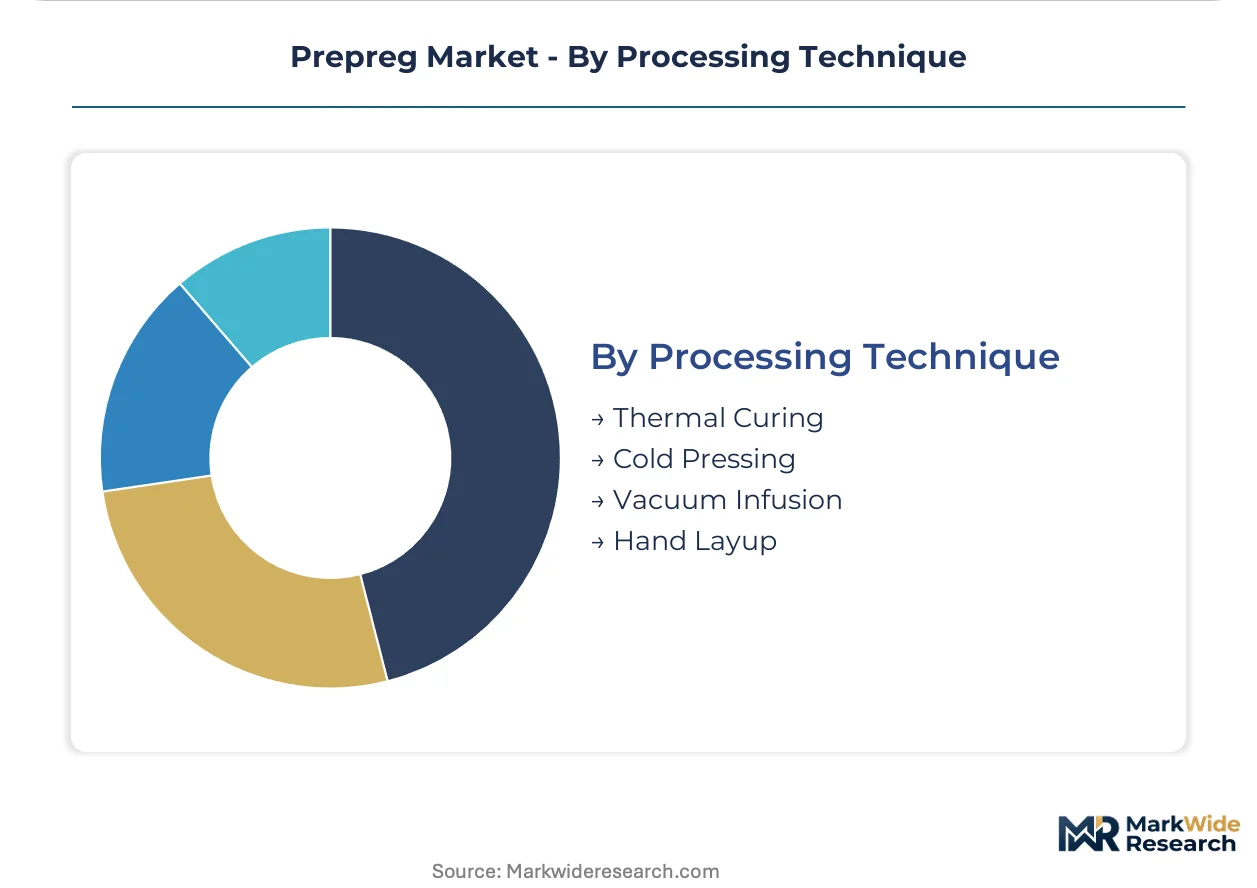
Thermal curing retains qualification dominance. Vacuum infusion captures the steepest capacity expansion as out-of-autoclave protocols achieve aerospace primary structure acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese carbon fiber exports supply aerospace fabricators in France, Germany, and the United States, creating a tripolar trade corridor that shapes regional investment patterns. Chinese wind blade production absorbs growing volumes of vacuum-infusion prepregs for offshore turbine installations. European REACH compliance costs are redirecting formulation R&D toward bio-based resin alternatives.
United States
Boeing 787 and 777X production in Everett and Charleston drives qualified material consumption for primary structures. FAA airworthiness directives govern resin system certification timelines extending eighteen to thirty-six months. The Pacific Northwest cluster around Seattle concentrates tier-one fabricators with locked pricing agreements through direct OEM contracts.
Germany
Airbus Hamburg and Toulouse supply chains anchor epoxy prepreg demand for narrow-body and wide-body programs. EASA CS-25 certification pathways for thermoplastic prepregs are compressing qualification barriers. Bavaria hosts satellite and radar dome specialists specifying cyanate ester grades for dielectric performance.
China
Domestic wind turbine OEMs scaling blade fabrication for offshore contracts exceeding twelve megawatts absorb vacuum-infusion compatible prepregs. MIIT industrial policy supports composite material localization through domestic precursor development. The Yangtze River Delta cluster concentrates LM Wind Power and Vestas supplier facilities.
Japan
Toray Industries maintains backward integration into PAN precursor manufacturing controlling seventy percent of global capacity. METI strategic material designations protect carbon fiber supply chains for defense and aerospace applications. The Chubu region around Nagoya anchors precursor production with French and US downstream assets.
France
Airbus Toulouse manufacturing clusters mandate qualified material supplier lists bypassing traditional distributors. EU Green Deal carbon border adjustments incentivize localized prepreg production within the European Union. The Occitanie region hosts composite research facilities piloting bio-based epoxy alternatives with DNV certification support.
Prepreg Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and qualification timelines. The vendor base concentrates around three Japanese conglomerates controlling precursor supply, European chemical groups with aerospace resin portfolios, and Swiss-German specialists in wind energy systems. Archetypes include backward-integrated fiber producers, formulation-focused resin houses, and application-specific fabricators. Dominant competitive moves span capacity expansion in low-cost manufacturing zones and strategic partnerships with OEMs for locked pricing tiers.
Among Japanese conglomerates, Toray Industries, Inc. exemplifies the backward-integrated archetype through captive precursor production. European resin specialists include Solvay S.A. and Hexcel Corporation, occupying positions within aerospace-qualified formulation tiers. Gurit Holding AG represents the application-specific fabricator model concentrated in wind energy supply chains.
| Leading Market Players |
|---|
| SGL Carbon SE |
| Gurit Holding AG |
| Toray Industries, Inc. |
| Owens Corning |
| Solvay S.A. |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Asahi Kasei Corporation |
| Hexcel Corporation |
| Others |
Cost & Logistics Intelligence
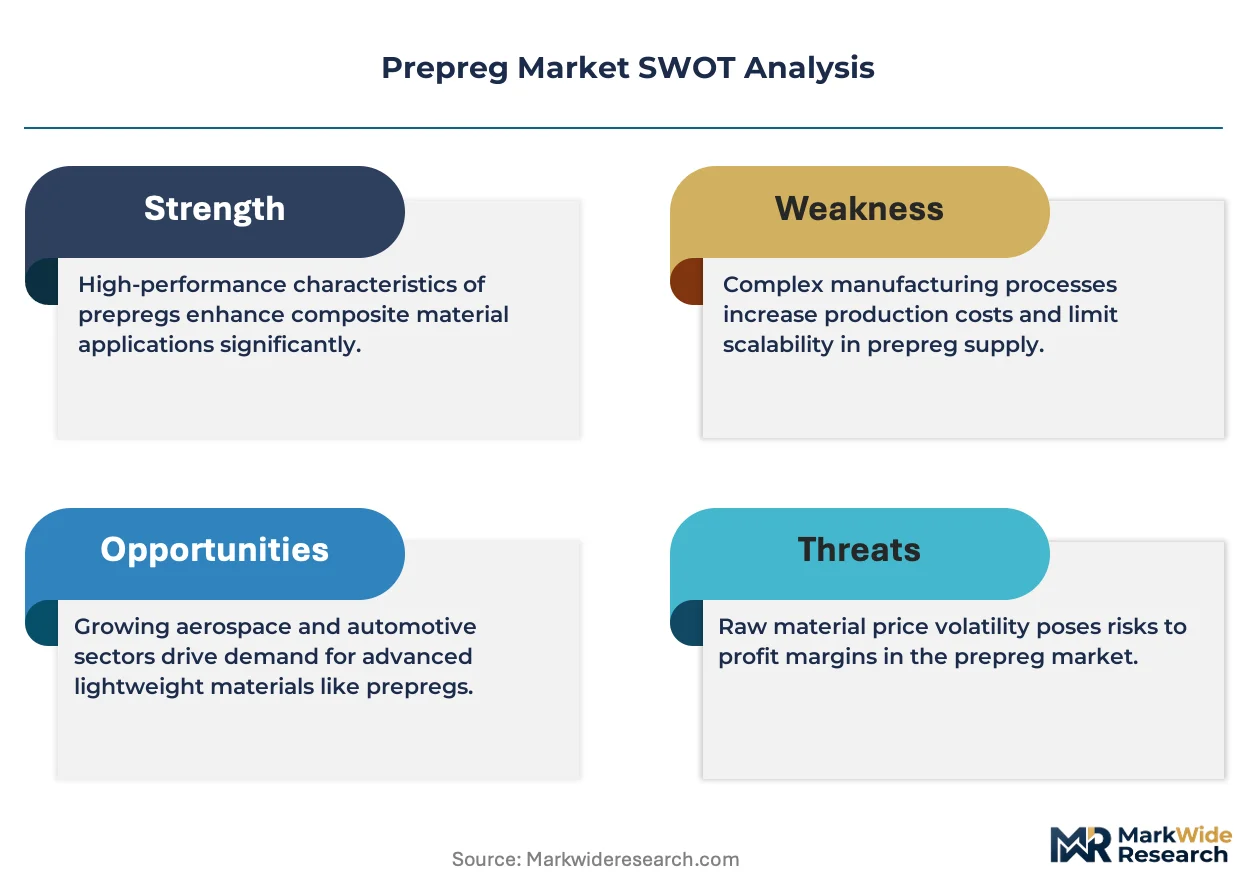
Autoclave capacity utilization rates above eighty percent at tier-one aerospace fabricators create pricing power asymmetries that compress margin recovery for mid-scale converters while reinforcing locked-contract premiums for qualified resin systems.
Pricing Analysis
Autoclave-cured thermoset prepregs command substantial premiums over out-of-autoclave formulations, with vacuum-only cure cycles narrowing the gap as Bombardier and Gulfstream qualifications validate lower-capital processing. Pricing stratifies across aerospace-qualified, industrial-grade, and emerging thermoplastic tiers, with certification level and fiber modulus grade driving differentiation. Cost compression in industrial-grade epoxy runs through acrylonitrile feedstock volatility and Chinese wind blade procurement consolidation. Automotive battery enclosure specifications show highest price sensitivity due to volume-scale mandates, while satellite-grade cyanate ester programs demonstrate lowest sensitivity given dielectric performance requirements.
Supply Chain Analysis
Strait of Malacca transit lanes underpin carbon fiber precursor logistics from Japanese Chubu region production bases to European and North American downstream prepreg converters. Supply concentrates in Japan, the United States, and China, with Toray Industries, Hexcel, and domestic Chinese precursor developers anchoring respective geographies. PAN precursor, epoxy resin, and high-temperature thermoplastic matrices constitute critical input dependencies. Single-source vulnerability pervades Japanese precursor concentration exceeding seventy percent of global capacity. Distribution runs through qualified material supplier lists mandated by Airbus and Boeing, bypassing traditional composite distributors for direct tier-one fabricator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prepreg market tracks aerospace production cycles, with Boeing and Airbus narrow-body ramp rates governing demand recovery velocity through the analysis window.
For Market Incumbents: Secure locked pricing tiers through direct OEM agreements with Toulouse and Hamburg manufacturing clusters before thermoplastic qualification pathways mature. Expand autoclave capacity in low-cost manufacturing zones to offset capital intensity compression from out-of-autoclave adoption. Defend against resin formulation substitution by accelerating EASA CS-25 certification investments for next-generation epoxy systems. For New Entrants and Emerging Players: Differentiate on bio-based epoxy alternatives aligned with EU Green Deal carbon border adjustments and REACH substance restrictions. Target automotive structural battery enclosure specifications where thermoplastic prepreg penetration remains nascent and NHTSA thermal runaway compliance creates qualification windows. Pursue DNV certification partnerships for wind energy vacuum infusion supply to Nordic and Baltic blade fabricators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated fiber producers with captive precursor supply and long-term aerospace contracts. Five-to-ten year viability favors converters with demonstrated FAA-EASA dual qualification track records and thermoplastic R&D pipelines. Monitor ECHA candidate list expansions for bisphenol-A derivative restrictions as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Toray Industries controls seventy percent of global PAN capacity through Japanese, French, and US assets. |
| Out-of-Autoclave Formulation Development | Bombardier and Gulfstream vacuum-only cure qualifications redistribute competitive advantage toward resin chemistry control. |
| Thermoplastic Qualification Pathway Investment | EASA CS-25 streamlined timelines accelerate OEM adoption in narrow-body programs, reducing substitution barriers. |
| EU Green Deal Localized Production | Carbon border adjustments incentivize prepreg manufacturing investments within the European Union. |
| DNV Certification Partnership | LM Wind Power and Vestas facilities specify certified laminates with thirty-year fatigue performance guarantees. |
Research Approach
Desk research of customs trade data, ECHA substance restriction filings, and aerospace OEM procurement disclosures preceded structured interviews with composite plant managers, tier-one fabricator procurement leads, resin system R&D directors, and wind blade technical specialists. Primary fieldwork combined with secondary validation through SEC 10-K filings, DNV certification registries, and FAA airworthiness directive databases. Bottom-up volume estimates triangulated against top-down aerospace production forecasts and wind turbine installation projections.
Variance decomposition across resin chemistry, reinforcement architecture, end-use vertical, and curing protocol dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by value-per-kilogram differentials across carbon fiber, glass fiber, and aramid grades. Forecast inputs incorporated OEM qualification timeline assumptions, REACH substance restriction sunset dates, and precursor capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside EASA-FAA certification harmonization or acrylonitrile price stability assumptions would require recalibration. Practitioners should keep alternative scenarios live as ECHA candidate list expansions and thermoplastic qualification velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market