
 Reinforced Plastic Sheeting Market | 2026-2036
Reinforced Plastic Sheeting Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforced Plastic Sheeting Market Analysis
Polyethylene film reinforced with woven scrim or fiberglass mesh is repositioning traditional canvas and untreated polyethylene in temporary enclosure and weather-protection applications. U.S. Liner Company leverages captive extrusion capacity to dominate North American transportation and construction channels. LAMILUX anchors European supply for translucent reinforced panels serving daylighting applications in industrial roofing. Heinrich Strunz Group differentiates through specialized gel-coat surface treatments that extend product service life in corrosive environments.
Reinforced plastic sheeting consists of thermoplastic substrates laminated or coextruded with woven, nonwoven, or chopped-strand reinforcement layers, typically achieving tensile strengths from 50 to 300 lbf/in and puncture resistance critical for scaffolding enclosures, agricultural tunnel covers, and cargo wrap systems. Its primary purpose is to combine the barrier properties of polymer films with dimensional stability under wind load, UV exposure, and mechanical stress. Polyethylene formulations lead volume due to cost scalability and recycling compatibility, while PVC captures margin pools in flame-retardant construction specifications where building codes demand NFPA 701 compliance. HDPE grades compete in agricultural geomembrane and pond liner segments where puncture resistance and chemical inertness justify premium positioning over standard polyethylene.
The US EPA regulates VOC emissions from construction materials under national ambient air quality standards, while OSHA mandates flame-resistance documentation for temporary enclosure materials used in commercial building sites. REACH compliance in Europe restricts phthalate plasticizers in PVC formulations, redirecting R&D toward bio-based plasticizer alternatives and non-PVC construction sheeting. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and emerging state-level chemical disclosure laws in California and New York that will reshape material qualification requirements and supply chain documentation burdens.
Market Dynamics
Construction contractors are consolidating procurement around polyethylene-based reinforced sheeting as EPA VOC emission standards and state building codes force rapid reformulation of legacy construction materials. This regulatory compression is accelerating supplier qualification cycles and reshaping competitive positioning across North American and European supply bases.
Growth Catalysts
- REACH phthalate restrictions:European PVC formulation bans are redirecting R&D investment toward bio-based plasticizer alternatives and non-PVC construction sheeting, opening substitution windows for polyethylene suppliers.
- Automotive daylighting demand:Industrial roofing applications for translucent reinforced panels are expanding in Germany as manufacturers seek natural light penetration with structural load-bearing capacity.
- Scaffolding enclosure specifications:OSHA flame-resistance documentation mandates for temporary commercial building materials are standardizing reinforced sheeting across US construction sites.
Market Restraints
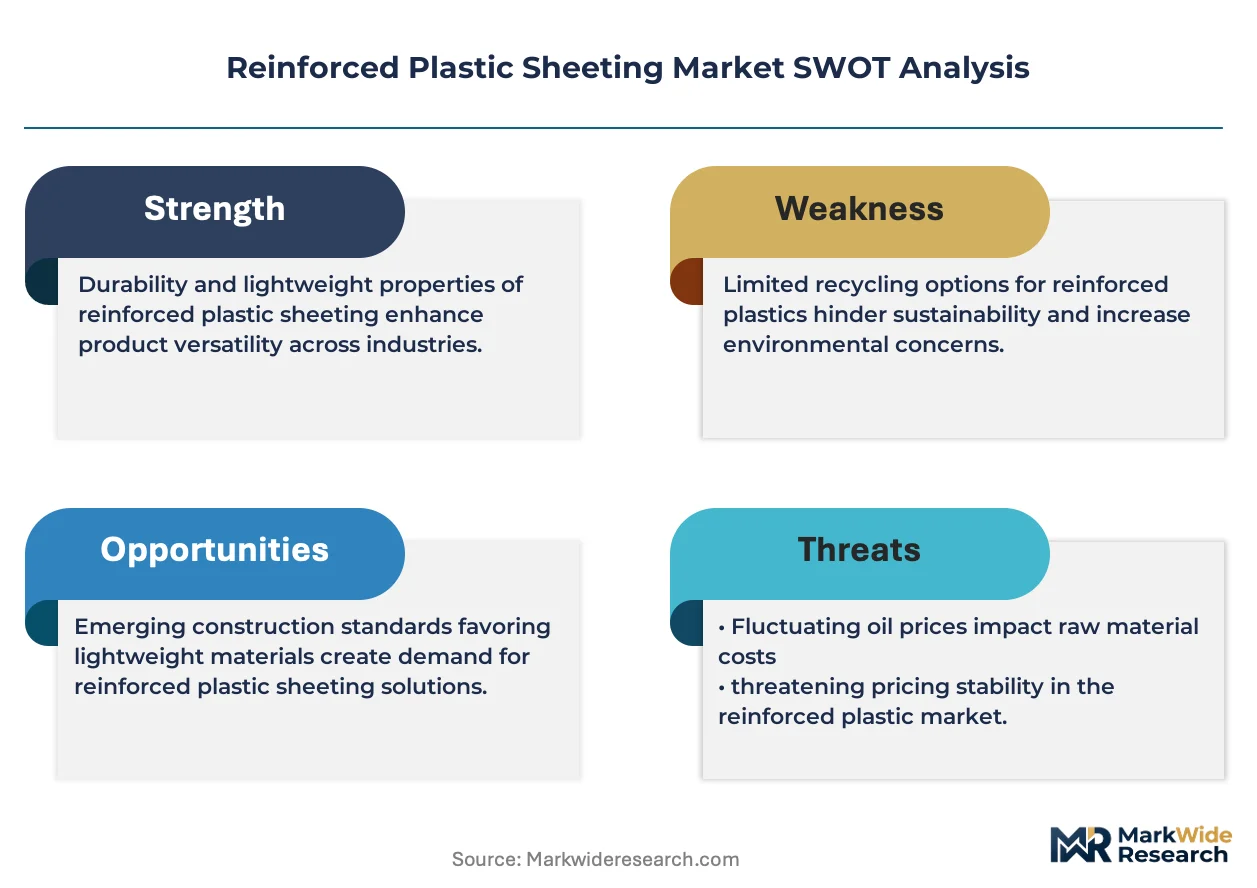
- Ethylene feedstock volatility:Crude oil price swings directly compress polyethylene margin structures and destabilize long-term contract pricing for construction distributors.
- German production cluster concentration:LAMILUX and Heinrich Strunz Group anchor European supply, creating geographic vulnerability for automotive and industrial end users during logistics disruptions.
- Canvas and untreated polyethylene substitution:Traditional materials retain cost advantage in price-sensitive agricultural tunnel cover and short-duration weather protection applications.
Strategic Opportunities
- California chemical disclosure laws:Emerging state-level transparency mandates are creating first-mover advantage for suppliers with pre-qualified low-emission documentation packages.
- Agricultural geomembrane segment:HDPE grades with enhanced puncture resistance are penetrating pond liner and containment applications where chemical inertness commands premium positioning.
- Digital specification platforms:Construction procurement teams are migrating to centralized vendor databases, enabling direct supplier engagement bypassing traditional distributor markup layers.
Industry Challenges
- NFPA 701 certification timelines:Flame-retardant testing protocols for commercial construction applications extend product qualification cycles and delay revenue recognition.
- Coextrusion equipment specialization:Captive woven scrim lamination capacity requires significant capital deployment, favoring incumbents with established extrusion footprints over new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Plastic Sheeting Market |
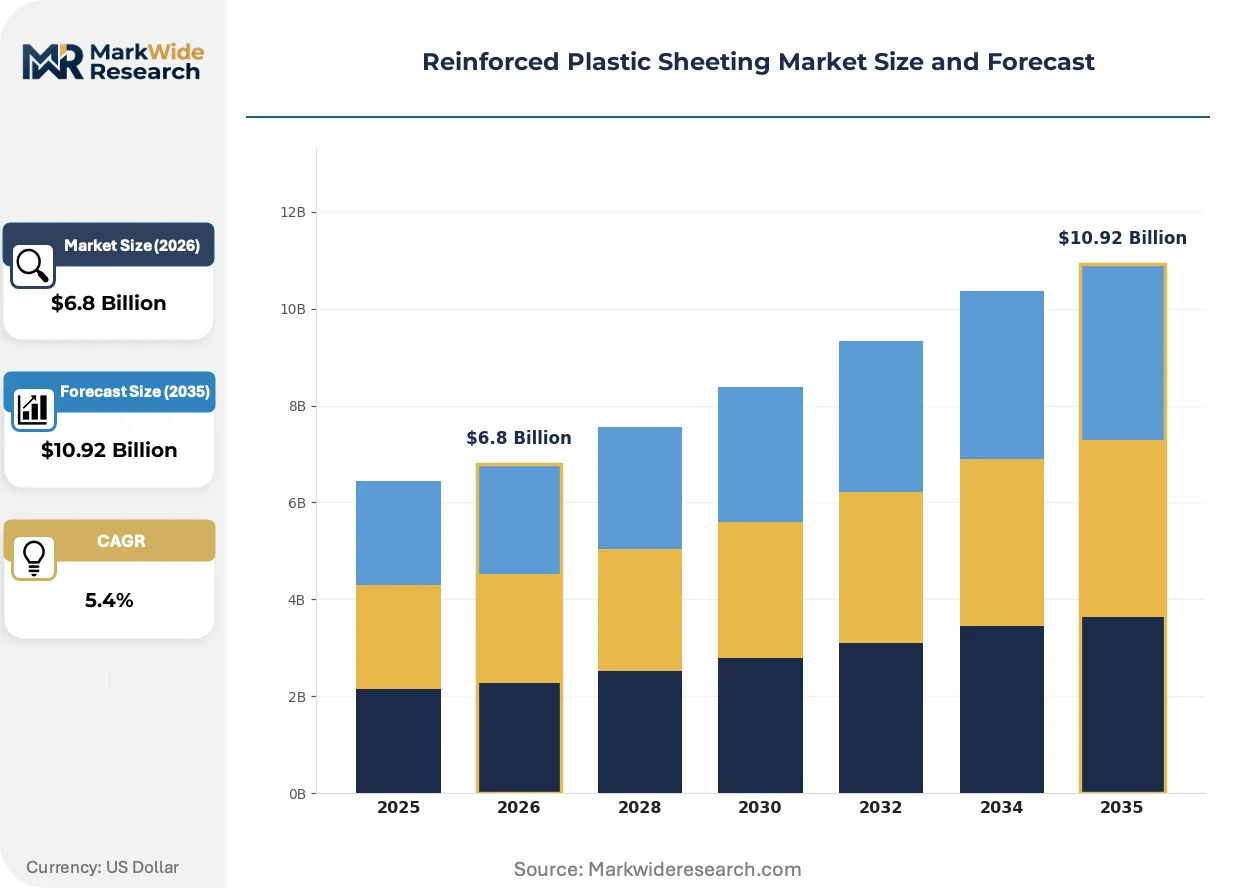
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, HDPE Application: Construction, Agriculture, Packaging, Industrial End User: Contractors, Farmers, Manufacturers, Retailers Thickness: 1mm, 2mm, 4mm, 6mm |
| Companies Covered | Glasteel, U.S. Liner Company, Crane Composites, Optiplan GmbH, Brianza Plastica, LAMILUX, Heinrich Strunz Group, Polser Fiberglass Reinforced Plastics, Panolam Industries International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Plastic Sheeting Market Emerging Trajectories
Reinforced plastic sheeting is undergoing material science convergence as sustainability mandates and performance specifications collide. Formulation chemistry, manufacturing process control, and procurement digitization are the three vectors where competitive differentiation is crystallizing.
Multi-layer coextrusion with embedded fiberglass mesh is decentralizing production economics for high-performance reinforced films. Regional compounders in the US Midwest and Central Europe are adopting modular extrusion lines that slash minimum efficient scale thresholds. Construction distributors now source specification-grade sheeting from mid-cap producers previously excluded by capital barriers.
EPA national ambient air quality standards for construction material VOC emissions are forcing reformulation roadmaps across polyethylene and PVC supply chains. Manufacturers are retiring legacy plasticizer systems and accelerating low-emission adhesive development. California and New York state disclosure frameworks are extending documentation burdens upstream to resin suppliers.
Construction procurement teams are consolidating vendor relationships around suppliers with pre-integrated certification packages. Master distributor networks are losing share to direct mill relationships as buyers prioritize supply chain transparency. This concentration is most visible in North American commercial building projects where general contractors face liquidated damages for material non-compliance.
Reinforced Plastic Sheeting Market Segmentation
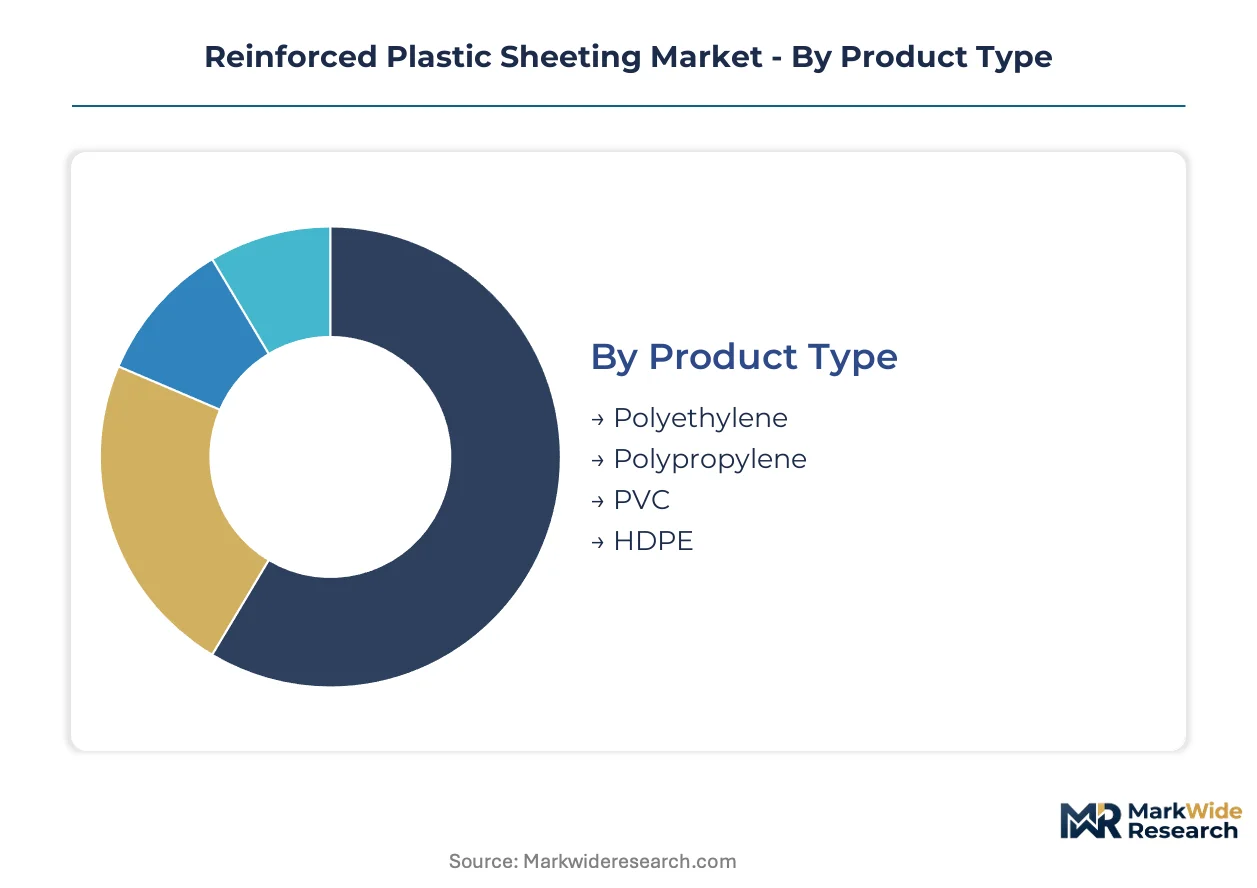
Segmentation in reinforced plastic sheeting separates commodity-grade polyethylene from specification-driven PVC and HDPE tiers, each commanding distinct margin pools and certification requirements. Product chemistry and application severity determine reinforcement density, UV stabilization packages, and flame-retardant compliance documentation.
Product Type:
Standalone sheeting dominates temporary enclosure and weather-protection applications, while embedded reinforcement systems integrate into permanent building envelopes and industrial daylighting assemblies.
- Polyethylene:Low-density and linear low-density formulations laminated with woven scrim achieve cost scalability for construction moisture barriers and agricultural tunnel covers. US contractors consolidate procurement around EPA-compliant low-emission grades as state building codes tighten VOC standards.
- PVC:Gel-coat surface treatments and phthalate-free plasticizer systems serve flame-retardant scaffolding enclosures where OSHA mandates NFPA 701 documentation. REACH restrictions in Europe redirect formulation R&D toward bio-based alternatives, compressing traditional PVC margin structures.
- Polypropylene:Higher melt strength and chemical resistance position this substrate for industrial containment and corrosive environment applications.
- HDPE:Enhanced puncture resistance and chemical inertness penetrate geomembrane segments including pond liners and agricultural containment systems.
Volume placements concentrate in polyethylene; the faster expansion belongs to HDPE as agricultural containment specifications intensify.
Application:
Application segmentation tracks project duration and regulatory exposure, with permanent installations demanding full certification packages versus temporary deployments tolerating reduced documentation.
- Construction:Scaffolding enclosures, temporary weather protection, and moisture barriers under slabs and foundations require wind-load-rated reinforcement and flame-resistance certification. OSHA documentation mandates standardize sheeting specifications across US commercial building sites, consolidating vendor relationships around pre-qualified suppliers.
- Agriculture:Tunnel covers, greenhouse glazing, and pond liners balance UV stabilization against cost per square foot, with HDPE geomembranes gaining share in chemical containment applications.
- Industrial:Daylighting panels and corrosive environment cladding integrate fiberglass-reinforced systems with structural load-bearing capacity.
- Packaging:Cargo wrap and dunnage applications prioritize puncture resistance and tear propagation resistance for transportation damage prevention.
Construction absorbs the largest volume share; agriculture climbs fastest as climate-controlled growing infrastructure expands.
End User:
End-user segmentation distinguishes specification authority from procurement execution, with contractors and manufacturers driving technical requirements while farmers and retailers prioritize unit economics.
- Contractors:General and specialty contractors in commercial construction consolidate procurement around distributors with integrated certification packages, bypassing traditional master distributor networks. Liquidated damages clauses for material non-compliance concentrate buying power with pre-qualified mill-direct relationships.
- Farmers:Agricultural operations balance replacement cycles against seasonal cash flow, favoring polyethylene cost structures over HDPE premiums in short-duration tunnel cover applications.
- Manufacturers:Industrial OEMs and automotive suppliers specify translucent reinforced panels for daylighting integration, with German production clusters serving as primary supply anchors.
- Retailers:Hardware and farm supply channels stock commodity-grade sheeting for consumer weather protection and small-scale agricultural applications.
Contractors command the dominant volume position; manufacturers expand most quickly as industrial daylighting specifications proliferate.
Thickness:
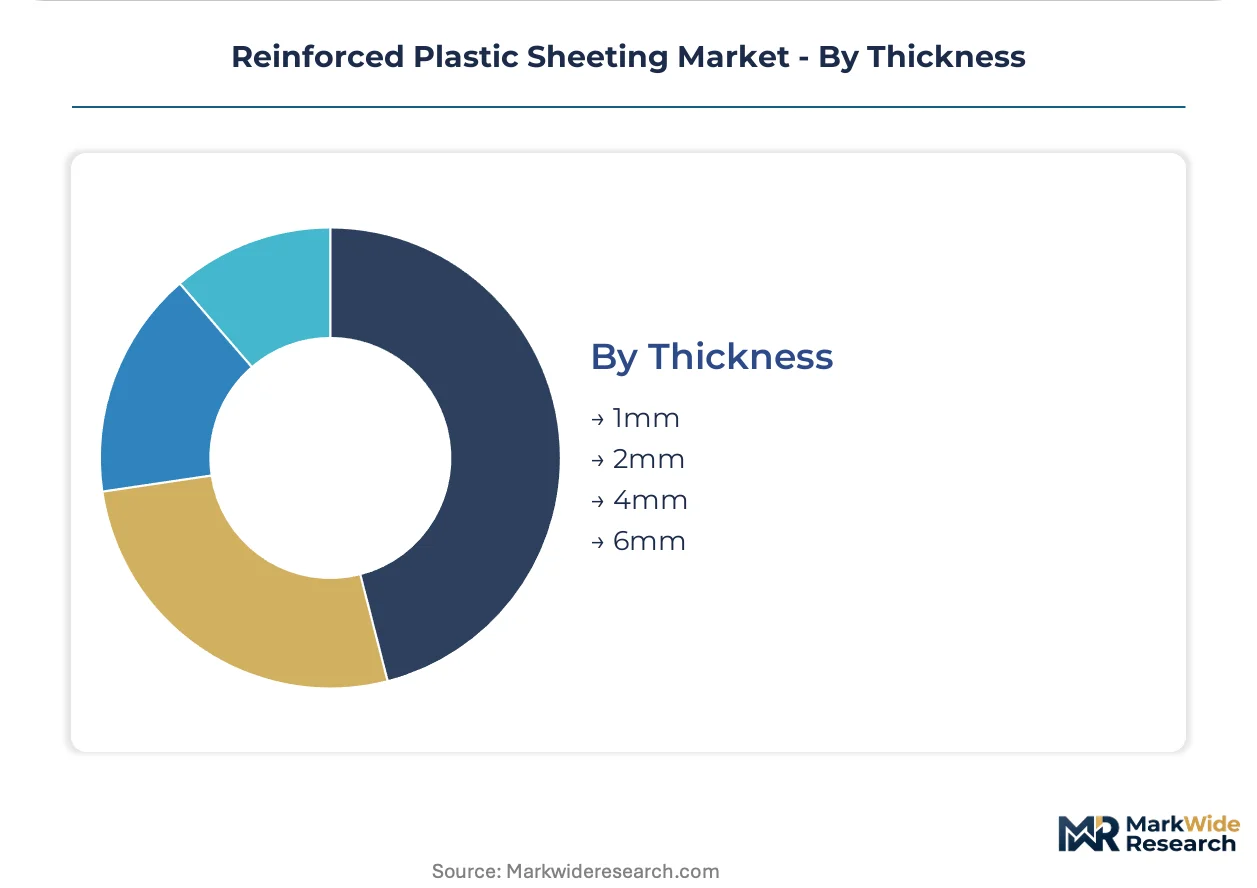
Thickness segmentation aligns mechanical performance with application severity, separating temporary deployment specifications from permanent infrastructure requirements.
- 6mm:Heavy-duty reinforced panels for industrial roofing and permanent daylighting systems achieve structural load-bearing capacity with embedded fiberglass mesh. German automotive and industrial end users anchor demand for this specification tier.
- 4mm:Mid-weight construction enclosures and long-duration agricultural tunnels balance puncture resistance against material cost and handling weight.
- 2mm:Standard construction weather protection and packaging applications optimize for deployment speed and single-season replacement cycles.
- 1mm:Light-duty temporary covers and short-term agricultural protection minimize unit cost for price-sensitive applications.
Volume concentrates in 2mm specifications; 6mm panels gain share fastest as industrial daylighting replaces conventional roofing materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors in the United States drive the largest volume concentration for polyethylene-based reinforced sheeting, with German automotive and industrial clusters anchoring European specification-grade demand for translucent daylighting panels.
United States
Commercial building contractors consolidate procurement around EPA-compliant low-emission polyethylene grades as state building codes in California and New York tighten VOC disclosure requirements. OSHA mandates flame-resistance documentation for scaffolding enclosures, standardizing reinforced sheeting specifications across job sites. The US Liner Company leverages captive extrusion capacity to dominate transportation and construction distribution channels nationwide.
Germany
Automotive OEMs and industrial roofing integrators specify 6mm translucent reinforced panels with embedded fiberglass mesh for structural daylighting applications. REACH phthalate restrictions redirect PVC formulation R&D toward bio-based plasticizer alternatives, compressing traditional margin structures. LAMILUX and Heinrich Strunz Group anchor production clusters in Bavaria and surrounding regions, serving European automotive and corrosive environment cladding demand.
China
Construction activity in Yangtze River Delta and Pearl River Delta metro corridors absorbs commodity-grade polyethylene sheeting for temporary weather protection and moisture barriers. The country's national environmental regulator enforces ambient air quality standards that parallel EPA VOC frameworks, pressuring reformulation of legacy adhesive systems. Regional compounders adopt modular coextrusion lines to serve mid-tier construction distributors previously dependent on imported supply.
India
Agricultural tunnel cover and greenhouse glazing applications expand as climate-controlled growing infrastructure penetrates Maharashtra and Gujarat farming belts. The Bureau of Indian Standards issues construction material specifications that reference international flame-resistance protocols, creating qualification pathways for reinforced sheeting imports. Domestic fabricators in Tamil Nadu and Karnataka develop woven scrim lamination capacity to displace Southeast Asian supply in price-sensitive segments.
Canada
Energy sector containment and mining temporary enclosure specifications drive demand for HDPE geomembrane grades with enhanced puncture resistance. Health Canada and the Pest Management Regulatory Agency coordinate chemical disclosure frameworks that align with emerging US state-level transparency mandates. Ontario-based distributors consolidate procurement around pre-qualified mill-direct relationships to bypass traditional master distributor markups.
Reinforced Plastic Sheeting Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade PVC and HDPE tiers consolidating around formulation-integrated incumbents while commodity polyethylene faces fragmentation from regional compounders. The vendor base organizes into three strategic archetypes: captive extrusion specialists with woven scrim lamination capacity, gel-coat surface treatment differentiators, and modular coextrusion entrants attacking mid-tier construction channels. Dominant competitive moves include backward integration into resin compounding and geographic expansion through distributor bypass strategies.
Among Germany-based fabricators, LAMILUX exemplifies the daylighting-specialist archetype, while Heinrich Strunz Group occupies a position within surface-treatment-differentiated supply. U.S. Liner Company anchors North American volume concentration. These three represent distinct competitive vectors: translucent structural panels, corrosive-environment durability, and transportation-channel scale dominance.
| Leading Market Players |
|---|
| Glasteel |
| U.S. Liner Company |
| Crane Composites |
| Optiplan GmbH |
| Brianza Plastica |
| LAMILUX |
| Heinrich Strunz Group |
| Polser Fiberglass Reinforced Plastics |
| Panolam Industries International |
| Others |
Supply Flow & Price Mechanics
Ethylene feedstock costs transmit directly through polyethylene margin structures, compressing standard-grade pricing while gel-coat surface treatments and NFPA 701 certification packages sustain premium tier positioning for PVC and HDPE specification grades. Construction distributors in the United States and automotive OEMs in Germany face divergent pricing pressure vectors as regional regulatory frameworks reshape material qualification requirements and procurement documentation burdens.
Pricing Analysis
Volume placements concentrate in commodity polyethylene grades where cost-per-square-foot economics dominate contractor procurement decisions, while specification-driven PVC and HDPE tiers command margin premiums through flame-retardant certification and enhanced puncture resistance. Price differentiation hinges on EPA VOC compliance documentation and REACH phthalate-free formulation status, with California chemical disclosure laws intensifying cost compression for legacy plasticizer systems. Margins are tightening in standard polyethylene as modular coextrusion entrants attack mid-tier construction channels. Agricultural tunnel cover buyers exhibit highest price sensitivity, while industrial daylighting integrators prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle specification-grade demand from German automotive and industrial clusters, while construction distributors consolidate procurement around pre-qualified mill-direct relationships to bypass traditional master distributor markups. Geographic supply concentration centers on the United States, Germany, and China, with captive extrusion capacity and woven scrim lamination infrastructure anchoring competitive positioning. Raw material dependencies draw from ethylene feedstocks, fiberglass mesh reinforcement, and UV stabilization additive packages. Single-source vulnerability concentrates in German production clusters serving European automotive daylighting specifications. Distribution runs through regional compounders adopting modular extrusion lines to serve mid-tier construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer coextrusion with embedded fiberglass mesh is displacing legacy canvas and untreated polyethylene in temporary enclosure applications, creating technology-transition windows across specification-grade and commodity tiers.
For Market Incumbents: Extend captive extrusion capacity into low-emission formulation development to defend against REACH-driven PVC substitution and EPA VOC compliance requirements. Anchor supply relationships with resin compounders capable of bio-based plasticizer alternatives. Deepen backward integration into UV stabilization additive sourcing to secure margin control as ethylene feedstock volatility intensifies. For New Entrants and Emerging Players: Modular coextrusion technology-first wedges open mid-tier construction procurement channels previously blocked by capital barriers. Target agricultural geomembrane segments in India and Canada where HDPE specification intensity outpaces incumbent supply response. Deploy digital specification platform integration as primary go-to-market angle to bypass entrenched distributor networks. For Investors and Strategic Acquirers: California chemical disclosure law implementation is the leading indicator that documentation-integrated suppliers will consolidate procurement share from legacy distributors. Long-term viability favors acquisition targets with pre-qualified low-emission certification packages spanning EPA, REACH, and emerging state-level frameworks. Monitor NFPA 701 certification timeline compression as signal for specification-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene formulation control insulates margin structures from feedstock volatility in construction channels. |
| Gel-Coat Surface Treatment Expansion | Heinrich Strunz Group's corrosive-environment specialization commands premium positioning in industrial cladding applications. |
| Modular Coextrusion Capacity Deployment | Regional compounders in US Midwest slash minimum efficient scale thresholds to attack mid-tier construction procurement. |
| Digital Specification Platform Integration | Direct mill relationships bypass master distributor markups as contractors prioritize supply chain transparency. |
| Bio-Based Plasticizer R&D Investment | REACH phthalate restrictions redirect formulation chemistry toward sustainable alternatives in European PVC supply. |
Methodological Framework
Independent corroboration across construction procurement directors, plant managers at extrusion facilities, regulatory affairs leads, and distribution channel partners underwrites the qualitative findings in this analysis. Primary interviews with contractors consolidating vendor relationships around pre-qualified suppliers combined with secondary validation from EPA emission filings, state building code documentation, REACH substance restriction databases, and customs trade data establish material flow and pricing benchmarks. Bottom-up volume aggregation across product type, application, and thickness segments triangulates against top-down macroeconomic indicators for the reinforced plastic sheeting industry.
Comparable-period anchoring to historical construction spending cycles and agricultural infrastructure investment patterns calibrates the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use severity classification, reinforcement density specification, and regional regulatory cluster. CAGRs derive from regression analysis of segment-specific demand drivers against feedstock cost trajectories and certification timeline evolution. Industry-specific forecast inputs incorporate OSHA flame-resistance mandate adoption curves and EU extended producer responsibility framework progression.
Several conditions sit outside the modeled scope, including abrupt crude oil price dislocations, unanticipated regulatory acceleration in additional US states, and breakthrough substitution technologies in biodegradable barrier materials. Forecasts reflect assumptions regarding steady-state construction activity and incremental rather than disruptive agricultural climate-control infrastructure expansion. Periodic stress-testing of base assumptions is recommended against ethylene feedstock volatility indicators and certification timeline compression signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Metal Finishing Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Structural Core Materials Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Graphene Composites Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Global Composite Resin Market
Composite Materials
Case Material Market
Composite Materials
Epoxy Composite Market