
 Global Lightweight Construction Material Market | 2026-2036
Global Lightweight Construction Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lightweight Construction Material Market Foresight
EN 771-4 certification for autoclaved aerated concrete masonry units is unwinding competitive access across European public procurement channels. HeidelbergCement leverages its integrated cement-to-precast network to sustain specification relationships with tier-one contractors in Nordic markets. CRH anchors its position through captive gypsum and aggregates positions that feed lightweight panel lines in the UK and Ireland. Bauroc AS competes on Baltic Sea logistics density, shipping AAC products from Estonian plants to Scandinavian job sites with lower freight penalties than Central European rivals.
Lightweight construction materials are engineered substances with bulk densities below 1,900 kg per cubic meter, produced through processes such as autoclaved gas expansion, polymer matrix infusion, or oriented strand lamination to reduce dead loads while preserving compressive or flexural performance. Their primary purpose is to cut structural steel tonnage, foundation volumes, and transport costs in mid-rise and high-rise construction. Engineered lumber leads value contribution where mass timber codes have matured, while fiber-reinforced polymer captures premium margin pools in facade systems requiring corrosion immunity and thermal break continuity. Aluminum sheet and extrusion forms dominate structural component shipments to aviation-adjacent industrial buildings and sports infrastructure.
The EU Green Deal's embodied carbon benchmarks, enforced through national building codes transposing the Energy Performance of Buildings Directive, are mandating environmental product declarations for structural materials in public tenders. REACH compliance on resin chemistry and flame retardant content is filtering out non-compliant polymer foam suppliers from facade and insulation panel supply chains. China's GB standards on autoclaved aerated concrete block density classes, administered by SAMR, are reshaping export qualification requirements for Asian-origin producers. Stakeholders must monitor whether the EU AI Act's eventual extension to construction workflow software will automate compliance verification and shift specification authority from architects to algorithmic procurement platforms.
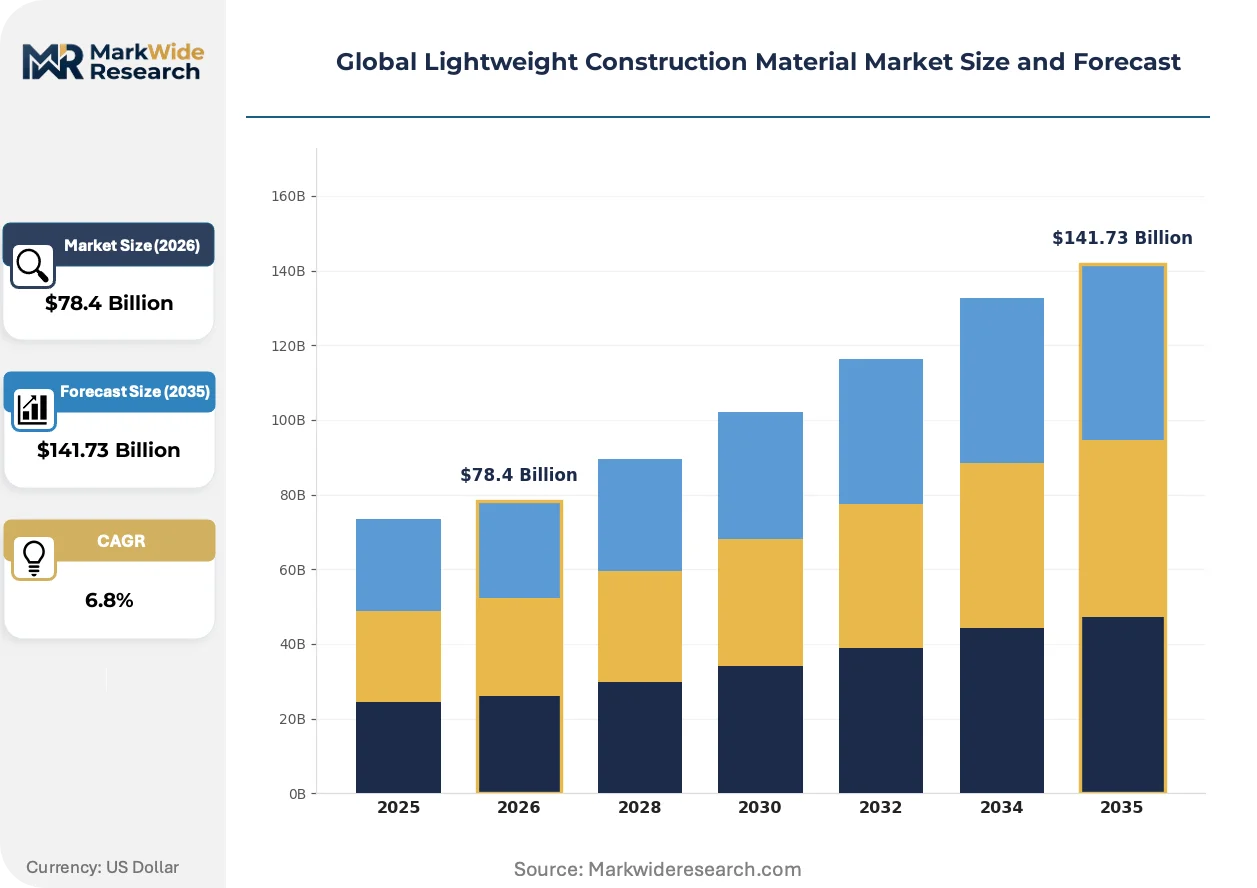
Market Dynamics
EU Green Deal embodied carbon thresholds are compressing specification timelines across European public procurement, forcing architects to substitute conventional concrete and steel with lower-density alternatives before EPD submission deadlines lock material choices.
Growth Catalysts
- EU Green Deal thresholds:National building codes transposing the Energy Performance of Buildings Directive mandate environmental product declarations for structural materials in public tenders across Germany, France, and the Netherlands.
- Passive house retrofit codes:German federal energy efficiency standards are pulling cross-laminated timber and autoclaved aerated concrete volumes into residential renovation pipelines at scale.
- Industrialized prefabrication clusters:Baltic Sea logistics density enables Estonian AAC producers to serve Scandinavian job sites with freight cost advantages over Central European rivals.
Market Restraints
- Resin chemistry compliance costs:REACH registration requirements for flame retardant content in polymer foam insulation are filtering non-compliant suppliers from facade panel supply chains.
- Cement-to-precast network concentration:Integrated building material conglomerates in Nordic markets control specification relationships through captive aggregate and gypsum positions.
- GB standards divergence:China's SAMR-administered autoclaved aerated concrete density classes impose export qualification burdens on Asian-origin producers seeking European market access.
Strategic Opportunities
- Aviation-adjacent industrial buildings:Aluminum sheet and extrusion forms for structural components in sports infrastructure and aerospace manufacturing facilities represent underpenetrated specification channels.
- Mass timber code maturation:Engineered lumber value contribution expands as building codes in Austria, Norway, and Switzerland clarify fire safety performance standards for mid-rise construction.
- Algorithmic procurement platforms:The EU AI Act's eventual extension to construction workflow software may automate compliance verification and shift specification authority from architects to digital platforms.
Industry Challenges
- EPD documentation timelines:Environmental product declaration preparation for novel lightweight materials extends pre-qualification periods beyond traditional concrete and steel certification cycles.
- Cross-material fire testing protocols:Hybrid assemblies combining timber, AAC, and polymer insulation require expensive multi-layer fire resistance testing not covered by single-material standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lightweight Construction Material Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Magnesium, Fiber-Reinforced Polymer, Titanium, Engineered Lumber Application: Structural Components, Facade Systems, Roofing, Flooring, Insulation Panels End Use Industry: Residential Buildings, Commercial Complexes, Institutional Facilities, Infrastructure Projects Form: Sheet, Foam, Panel, Pellet, Composite |
| Companies Covered | AERCON AAC, AeroBlocks, Bauroc AS, SOLBET Sp. z o. o., Ytong, HeidelbergCement, CRH, James Hardie, CEMEX S.A.B. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lightweight Construction Material Market Shifts & Advancements
Material science convergence with digital fabrication is compressing traditional specification hierarchies, as performance-optimized substitutes challenge incumbent structural systems on embodied carbon metrics rather than installed cost alone.
Fiber-reinforced polymer facade systems are displacing aluminum curtain wall assemblies in coastal and chemical exposure environments where corrosion immunity and thermal break continuity justify premium positioning. Specifiers in Dutch and Belgian port redevelopment projects specify FRP cladding at accelerating rates. The displacement is compressing aluminum extrusion demand in maritime-adjacent commercial construction.
REACH compliance on resin chemistry and flame retardant content is filtering non-compliant polymer foam suppliers from European facade and insulation panel supply chains. ECHA substance evaluation protocols now cover halogenated flame retardants previously grandfathered into legacy building products. German and French facade contractors are consolidating supplier bases around pre-certified polymer systems to avoid project delay risk.
Specification authority is migrating toward general contractor procurement teams as design-build delivery models compress traditional architect-led material selection windows. Tier-one contractors in UK and Irish commercial construction now maintain captive lightweight panel technical evaluation capabilities previously housed in architectural practices. The shift concentrates volume commitments with vertically integrated material suppliers capable of warranting performance across structural, thermal, and fire safety domains.
Global Lightweight Construction Material Market Segmentation
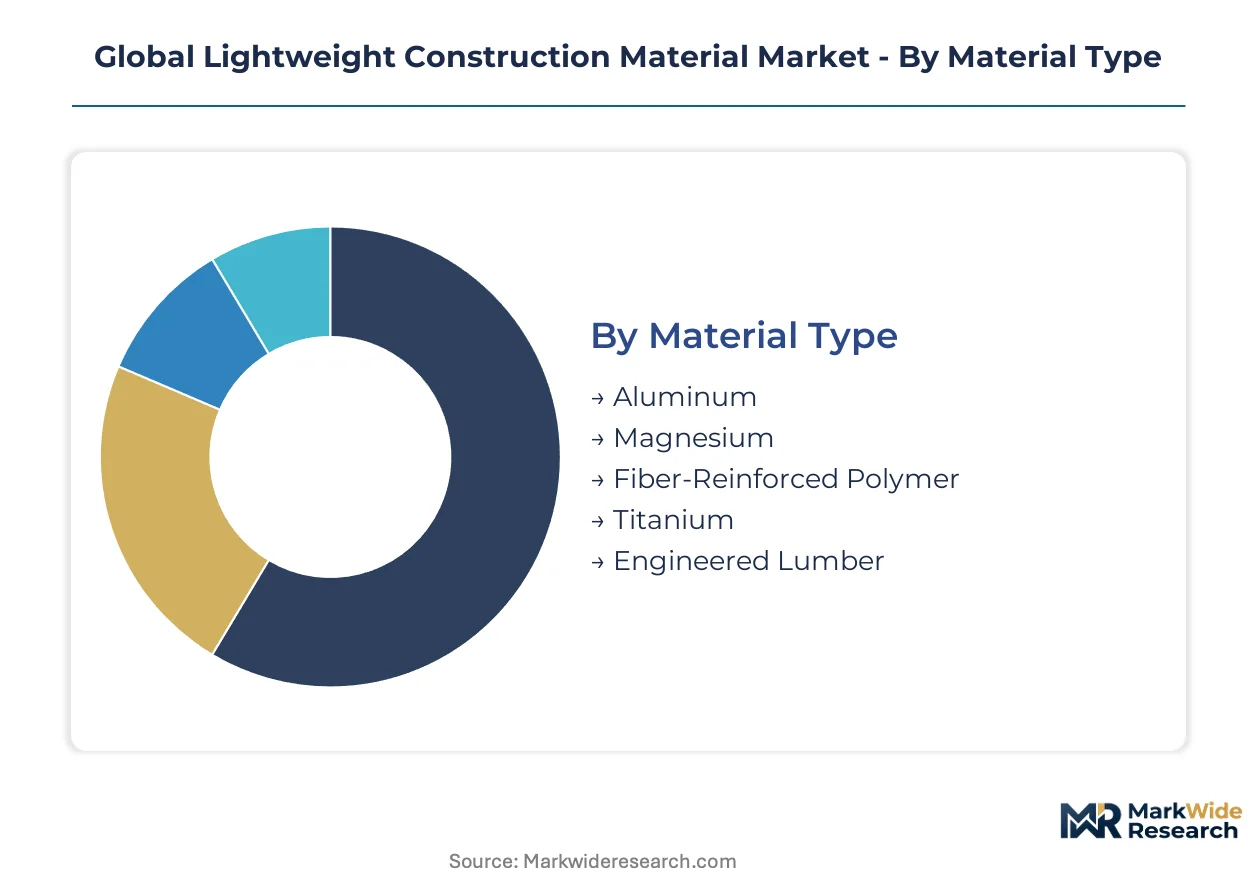
Segmentation in lightweight construction materials reveals how specification authority migrates across value chains. Material chemistry, application performance, and procurement channel access determine margin capture differently in each slice.
Material Type:
Domestic production clusters dominate engineered lumber and autoclaved aerated concrete, while aluminum and titanium rely on export-oriented smelting networks.
- Aluminum:Extruded and sheet forms serve aviation-adjacent industrial buildings and sports infrastructure where corrosion resistance and strength-to-weight ratios justify specification. German and Austrian facade contractors specify aluminum curtain wall systems for mid-rise commercial envelopes.
- Magnesium:Cast and wrought alloys penetrate automotive-adjacent construction equipment and temporary structural systems. Japanese METI-supported R&D clusters advance flame-retardant magnesium sheet for interior partition applications.
- Fiber-Reinforced Polymer:Glass and carbon fiber matrices displace steel reinforcement in coastal infrastructure where chloride exposure degrades conventional rebar. Dutch port redevelopment projects specify FRP cladding at accelerating rates.
- Titanium:Aerospace-grade sponge feeds architectural specialty applications requiring extreme corrosion immunity. Russian and Ukrainian sponge supply disruptions have concentrated procurement attention on Japanese and Chinese sponge alternatives.
- Engineered Lumber:Cross-laminated timber and glulam beams reduce foundation loads in passive house retrofits. Austrian and Norwegian code maturation clarifies fire safety performance standards for mid-rise mass timber construction.
Engineered lumber commands the established base. The steepest expansion runs through fiber-reinforced polymer as coastal infrastructure budgets accelerate.
Application:
Structural components absorb volume at scale, while facade systems capture premium positioning through thermal performance warranties.
- Structural Components:Load-bearing AAC blocks and CLT panels reduce steel tonnage in mid-rise frames. German industrialized prefabrication clusters pull engineered lumber volumes into residential renovation pipelines.
- Facade Systems:FRP and aluminum curtain walls integrate thermal breaks and corrosion immunity. Belgian and Dutch port contractors consolidate supplier bases around pre-certified polymer systems to avoid project delay risk.
- Roofing:Lightweight metal panels and polymer membranes cut dead loads on existing structural frames. Nordic markets favor standing seam aluminum for coastal commercial envelopes.
- Flooring:Engineered timber and magnesium alloy panels serve raised-access applications in data centers and laboratories. UK specification teams evaluate embodied carbon metrics alongside installed cost.
- Insulation Panels:Polymer foam cores with cementitious facing meet EU Green Deal embodied carbon thresholds. REACH compliance on flame retardant content filters non-compliant suppliers from European supply chains.
Structural components anchor volume demand. Facade systems are climbing the fastest as thermal performance warranties extend specification timelines.
End Use Industry:
Residential retrofits concentrate in Northern European markets, while commercial complexes drive specification innovation in the Middle East and Asia-Pacific.
- Residential Buildings:Passive house codes in Germany and Austria mandate low-density envelope materials for energy efficiency compliance. Cross-laminated timber volumes concentrate in multi-family renovation pipelines.
- Commercial Complexes:High-rise envelopes in Dubai and Riyadh specify aerated concrete and fiber-reinforced systems for rapid construction cycles. Freight cost advantages from Baltic Sea logistics enable Estonian AAC producers to serve Scandinavian job sites.
- Institutional Facilities:Schools and hospitals prioritize fire-rated lightweight assemblies. UK design-build contractors maintain captive technical evaluation capabilities for hybrid timber-AEC systems.
- Infrastructure Projects:Bridges and tunnels specify FRP reinforcement where chloride exposure threatens conventional steel. Chinese GB standards on AAC density classes reshape export qualification requirements for Asian-origin producers.
Commercial complexes dominate specification innovation. Residential buildings are expanding most quickly as retrofit codes tighten across Northern Europe.
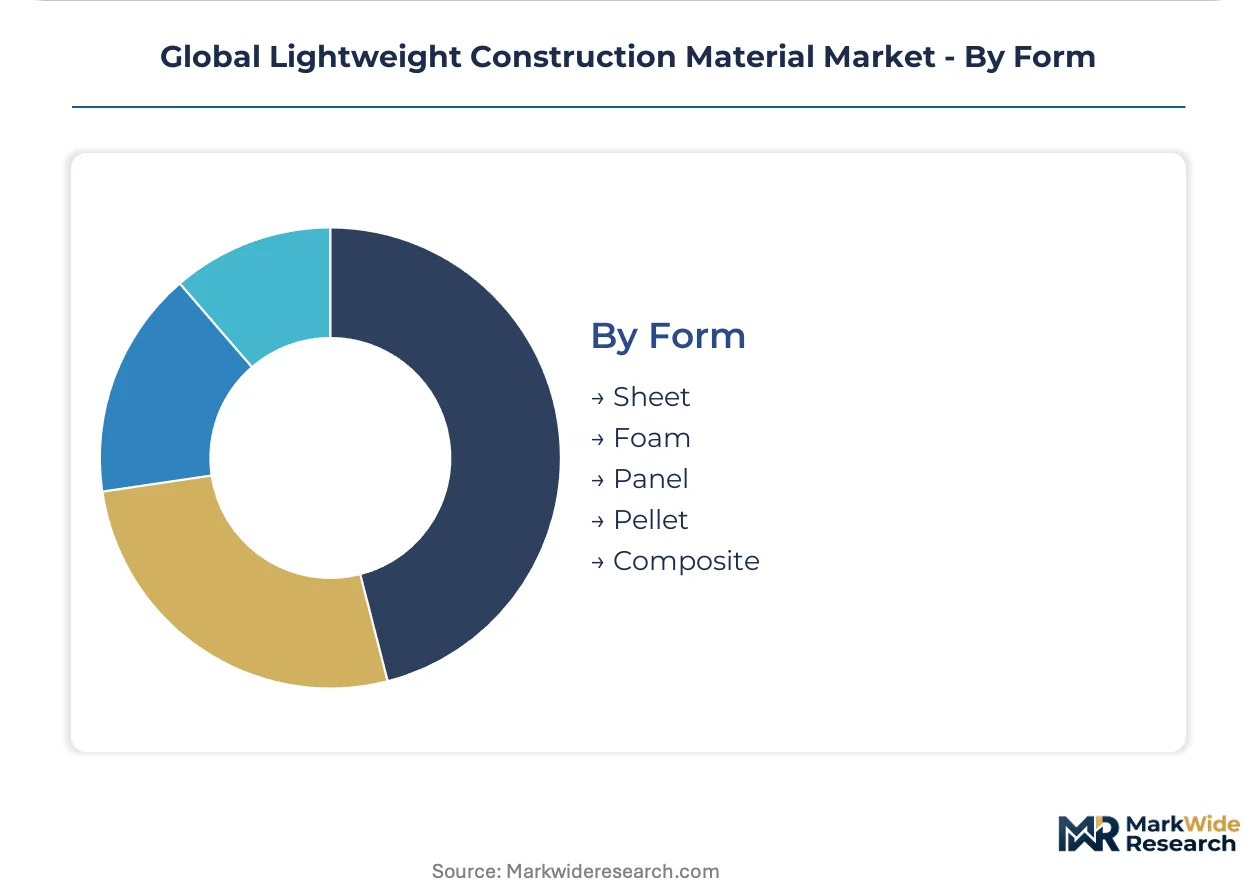
Form:
Panel and sheet forms enable prefabrication economies, while foam and pellet formats serve site-cast and additive manufacturing applications.
- Sheet:Aluminum and magnesium rolled products feed facade and roofing fabrication. German automotive sheet producers leverage rolling mill capacity for construction market diversification.
- Foam:Autoclaved aerated concrete and polymer foams provide thermal insulation with structural backup. SAMR-administered density classes in China impose export qualification burdens on Asian-origin producers.
- Panel:Pre-cured composite and timber panels compress on-site labor requirements. CRH anchors UK and Irish supply through captive gypsum and aggregates positions feeding lightweight panel lines.
- Pellet:Expandable polystyrene and mineral wool feed site-applied insulation systems. REACH registration requirements for flame retardant content consolidate European supplier bases.
- Composite:Multi-layer FRP and aluminum-timber hybrids optimize strength-to-weight ratios. ECHA substance evaluation protocols now cover halogenated flame retardants previously grandfathered into legacy products.
Panel formats hold the volume base. Composite forms are gaining share fastest as hybrid assembly warranties mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embodied carbon mandates are redirecting specification flows across Northern Europe. Germany, France, and the Netherlands now enforce environmental product declarations for structural materials in public tenders. Middle Eastern commercial construction is scaling aerated concrete and fiber-reinforced systems for rapid high-rise delivery cycles.
Germany
Passive house retrofit codes are pulling cross-laminated timber and autoclaved aerated concrete volumes into residential renovation pipelines at industrial scale. The federal Energy Performance of Buildings Directive transposition mandates EPD submission before material choices lock. Industrialized prefabrication clusters in Bavaria and Baden-Württemberg concentrate engineered lumber specification relationships with tier-one contractors.
United Arab Emirates
Commercial complexes in Dubai and Riyadh specify aerated concrete and fiber-reinforced systems for rapid construction cycles in high-rise envelopes. MOHAP building codes emphasize fire-rated lightweight assemblies for institutional facilities. Specification teams in the Emirates consolidate supplier relationships around pre-certified polymer systems to compress procurement timelines.
China
SAMR-administered GB standards on autoclaved aerated concrete density classes are reshaping export qualification requirements for Asian-origin producers. The dual carbon goals framework pressures domestic manufacturers toward lower-density alternatives in public infrastructure tenders. Yangtze River Delta production clusters feed both domestic mid-rise construction and European export channels.
Netherlands
Port redevelopment projects in Rotterdam and Amsterdam specify fiber-reinforced polymer cladding at accelerating rates where corrosion immunity justifies premium positioning. REACH compliance on resin chemistry filters non-compliant polymer foam suppliers from facade panel supply chains. Dutch design-build contractors now maintain captive technical evaluation capabilities previously housed in architectural practices.
United Kingdom
CRH anchors supply through captive gypsum and aggregates positions feeding lightweight panel lines across England and Ireland. UK specification teams evaluate embodied carbon metrics alongside installed cost for raised-access flooring in data centers. London-based contractors consolidate volume commitments with vertically integrated suppliers capable of warranting performance across structural, thermal, and fire safety domains.
Global Lightweight Construction Material Market Competitive Landscape
Player mix skews toward integrated building material conglomerates controlling specification relationships through captive raw material positions. The vendor base concentrates around cement-to-precast networks and captive gypsum-aggregates operations that feed lightweight panel lines. Two strategic archetypes dominate: diversified multinationals leveraging backward integration into raw materials, and regional specialists exploiting logistics density for freight-cost advantages. Competitive moves center on M&A to secure aggregate positions and capacity expansion in industrialized prefabrication clusters.
Among Nordic-Baltic specialists, Bauroc AS exemplifies the logistics-driven archetype, shipping AAC products from Estonian plants to Scandinavian job sites. HeidelbergCement AG and CRH plc represent the integrated multinational tier, anchoring positions through cement-to-precast networks and captive gypsum-aggregates operations. These three occupy positions that illustrate how raw material control and distribution density determine specification access in European public procurement channels.
| Leading Market Players |
|---|
| AERCON AAC |
| AeroBlocks |
| Bauroc AS |
| SOLBET Sp. z o. o. |
| Ytong |
| HeidelbergCement |
| CRH |
| James Hardie |
| CEMEX S.A.B. de C.V. |
| Others |
Supply & Pricing Matrix
Cross-laminated timber substitution for structural steel in German passive house retrofits simultaneously concentrates specification relationships with Bavarian prefabrication clusters and compresses installed cost premiums for engineered lumber assemblies. This displacement dynamic rewards producers with captive forestry positions while penalizing distributors dependent on spot-market fiber sourcing.
Pricing Analysis
Long-term offtake contracts with aluminum indexation dominate structural component procurement for aviation-adjacent industrial buildings, locking in volume commitments before spot volatility. Three-tier pricing structure across premium certified, standard grade, and economy unlabeled tiers reflects EN 771-4 certification status and embodied carbon disclosure depth. Cost compression in economy-tier autoclaved aerated concrete intensifies because Baltic Sea logistics density enables Estonian producers to undercut Central European rivals on delivered cost. Tier-one contractors in UK commercial construction exhibit lowest price sensitivity due to design-build risk transfer, while residential renovation specifiers in Germany remain most cost-constrained.
Supply Chain Analysis
Baltic Sea port congestion through Tallinn and Riga underwrites freight cost advantages for Estonian AAC producers serving Scandinavian job sites. Manufacturing concentrates in Germany, China, and Estonia, with raw material feedstocks drawing from captive gypsum positions in the UK and Ireland, Yangtze River Delta cement clinker, and Nordic timber basins. Single-source vulnerability runs through Russian and Ukrainian titanium sponge disruptions, which have concentrated procurement attention on Japanese and Chinese metallurgical alternatives. Distribution runs through vertically integrated building material conglomerates controlling specification relationships via cement-to-precast networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPD documentation capabilities and multi-layer fire testing infrastructure constitute scarce assets that gate specification access in EU public procurement channels. Firms lacking these competencies face extended pre-qualification timelines that exclude them from tender windows.
For Market Incumbents: Fortify specification relationships by securing captive aggregate positions in Nordic markets and expanding industrialized prefabrication capacity in Bavaria and Baden-Württemberg. HeidelbergCement and CRH demonstrate how backward integration into gypsum and cement clinker insulates margin structures from spot volatility. Invest in automated EPD generation platforms before EU AI Act extensions to construction workflow software shift procurement authority toward algorithmic compliance verification. For New Entrants and Emerging Players: Anchor in Dutch and Belgian port redevelopment projects where fiber-reinforced polymer cladding specification is accelerating fastest due to corrosion immunity requirements. The aviation-adjacent industrial building segment remains underpenetrated relative to commercial construction, offering white-space access with lower incumbent concentration. Pursue certification pre-alignment with REACH resin chemistry standards to avoid supplier base consolidation by tier-one facade contractors. For Investors and Strategic Acquirers: The market sits at a regulatory-implementation phase that favors vertically integrated material conglomerates over pure-play distributors. Long-term viability across the projection horizon hinges on embodied carbon disclosure infrastructure and captive raw material positions. Target acquisition profiles should emphasize firms with EN 771-4 certification scope expansion potential and Baltic Sea logistics density. Monitor ECHA substance evaluation protocol extensions to halogenated flame retardants as an inflection indicator for polymer foam supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Aggregates | CRH and HeidelbergCement leverage gypsum positions to anchor UK and Nordic specification relationships. |
| Industrialized Prefabrication Cluster Expansion | Bavarian engineered lumber concentration pulls cross-laminated timber volumes into German residential renovation pipelines. |
| EPD Automation Platform Development | EU Green Deal submission deadlines compress material choice windows, favoring automated environmental product declaration generation. |
| REACH Pre-Certification Alignment | German and French facade contractors consolidate supplier bases around compliant polymer systems to avoid project delay risk. |
| Baltic Sea Logistics Density Investment | Bauroc AS exploits Estonian plant positioning to serve Scandinavian job sites with lower freight penalties than Central European rivals. |
Research Methodology
Initial hypotheses were tested against primary input from specification architects at tier-one contractors, procurement officers at German and Dutch port redevelopment authorities, plant managers at Estonian AAC facilities, and technical directors at facade engineering consultancies, then refined through secondary validation against customs trade data, SEC 10-K filings of integrated building material conglomerates, EN standard certification registries, and ECHA substance evaluation protocols. Bottom-up volume triangulation across material type, application, and end-use industry segments was cross-checked against top-down macroeconomic construction spend projections.
Variance decomposition across the modeling period isolates volume drivers by segmentation dimension including material chemistry class, structural versus facade application, residential retrofit versus commercial new-build end use, and panel versus foam form factor. CAGRs were derived from regression-based demand elasticity modeling anchored in construction permit flows and embodied carbon regulatory stringency indices. Industry-specific forecast inputs incorporate passive house code adoption trajectories in Germany and Austria, SAMR-administered GB standard enforcement timelines in China, and EU AI Act construction software extension probabilities.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal embodied carbon threshold tightening and stable Baltic Sea freight corridor access; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance evaluation protocols evolve and mass timber fire safety code maturation accelerates across Austria, Norway, and Switzerland.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Laminar Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
Hybrid Composites Market
Composite Materials
Biocomposites Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Green Composites Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Epoxy Composite Market
Composite Materials
Composite Preforms Market
Composite Materials
Lightweight Materials Market
Composite Materials
Global Composites Cylinder Market