
 Copper Clad Laminates Market | 2026-2036
Copper Clad Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Clad Laminates Market Analysis
Substrate thinning for advanced semiconductor packaging is reconfiguring copper clad laminate specifications across the electronics supply chain. Kingboard Laminates Holdings Ltd. leverages vertical integration from copper foil to finished laminate to sustain cost leadership in high-volume FR-4 production. Shengyi Technology Co., Ltd. anchors its position through R&D intensity in halogen-free formulations for server and telecommunications boards. Panasonic Holdings Corporation differentiates via proprietary resin systems that dominate high-frequency applications for 5G base stations.
Copper clad laminates are composite materials formed by bonding copper foil to reinforced resin substrates, typically achieving dielectric constants between 3.5 and 4.5 for standard FR-4 grades and serving as the foundational material for printed circuit board fabrication. The manufacturing process involves impregnating glass fiber weave with epoxy resin, curing under heat and pressure, then laminating rolled copper foil to produce sheets with precise thickness tolerances for subsequent etching and drilling. FR-4 maintains volume leadership across consumer electronics and industrial controls, though high-frequency laminates for millimeter-wave telecommunications represent the fastest-expanding margin pool as substrate loss requirements tighten. Polyimide-based laminates occupy a specialized niche in flexible and rigid-flex circuits for aerospace and medical electronics where thermal stability exceeds standard epoxy capabilities.
China's NMPA and GB standards enforce flame-retardant and halogen-free specifications for electronic substrates used in telecommunications infrastructure, while REACH and RoHS in Europe restrict hazardous substances in laminate resin systems and copper treatment chemistries. The EU's F-Gas Regulation indirectly shapes demand through its impact on thermal management substrates in data center cooling applications. Stakeholders must monitor evolving substrate qualification timelines for advanced packaging nodes and regional divergence in environmental compliance thresholds.
Market Dynamics
Substrate specifications for advanced semiconductor packaging are compressing dielectric constant tolerances and loss tangent thresholds, forcing laminate manufacturers to retool resin formulations and copper foil surface treatments across their production footprints.
Growth Catalysts
- 5G millimeter-wave infrastructure:Telecommunications OEMs in China, South Korea, and Taiwan are qualifying ultra-low-loss laminates for base station antenna arrays and backhaul equipment.
- China's GB standards tightening:NMPA and MIIT mandates for halogen-free substrates in telecommunications infrastructure are accelerating formulation upgrades across domestic supply chains.
- Advanced packaging substrate thinning:Semiconductor foundries are driving demand for ultra-thin core laminates below 30 micrometers for 2.5D and 3D integration schemes.
Market Restraints
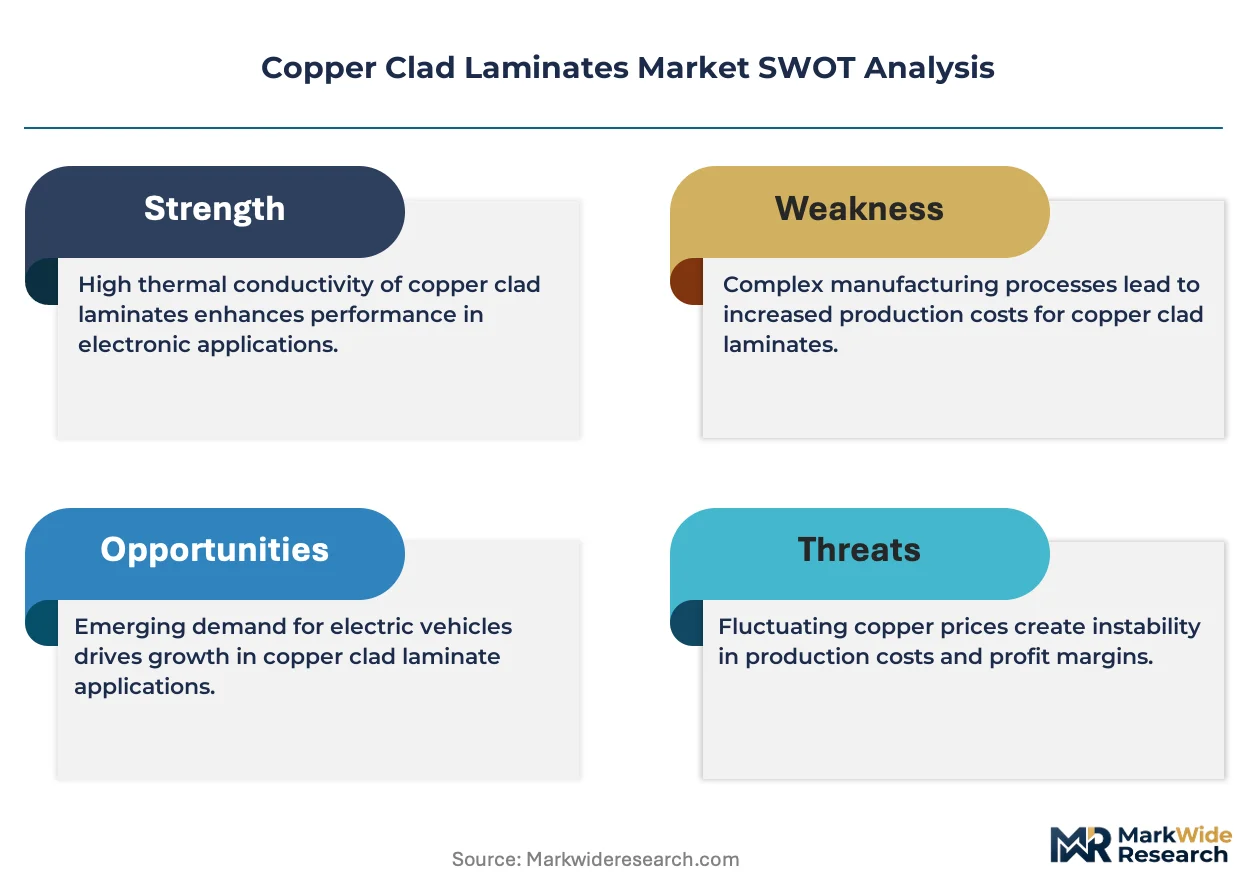
- Copper foil supply concentration:Rolled-annealed and electrodeposited copper foil production clusters in China and Japan create input cost volatility and allocation risk during demand surges.
- REACH and RoHS compliance friction:European restrictions on brominated flame retardants and specific resin hardeners force dual-track inventory management for export-oriented manufacturers.
- Technical limitation in ultra-low Dk materials:PTFE-based laminates for sub-3.5 dielectric constant applications suffer from poor dimensional stability and processing yield rates compared to hydrocarbon-ceramic alternatives.
Strategic Opportunities
- India's electronics manufacturing incentive schemes:PLI scheme allocations for semiconductor packaging and PCBs are attracting laminate qualification programs from East Asian suppliers seeking geographic diversification.
- Thermal management substrate convergence:Metal-backed and thermally conductive laminates for LED and power electronics are merging with traditional CCL fabrication lines.
- Automotive radar substrate qualification:Tier-1 automotive electronics suppliers in Germany and Japan are sourcing high-frequency laminates for 77-81 GHz radar modules at volumes previously reserved for aerospace.
Industry Challenges
- Process engineer scarcity:Lamination press operation and resin rheology expertise are aging out of the workforce faster than vocational training programs in China and Taiwan can replenish.
- Substrate qualification timeline compression:Semiconductor packaging roadmaps now demand 12-18 month qualification cycles versus historical 24-36 month windows, straining R&D-to-production handoffs.
- Copper surface treatment chemistry IP:Proprietary roughening and anti-tarnish formulations from Japanese suppliers create licensing bottlenecks for independent laminate manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Clad Laminates Market |
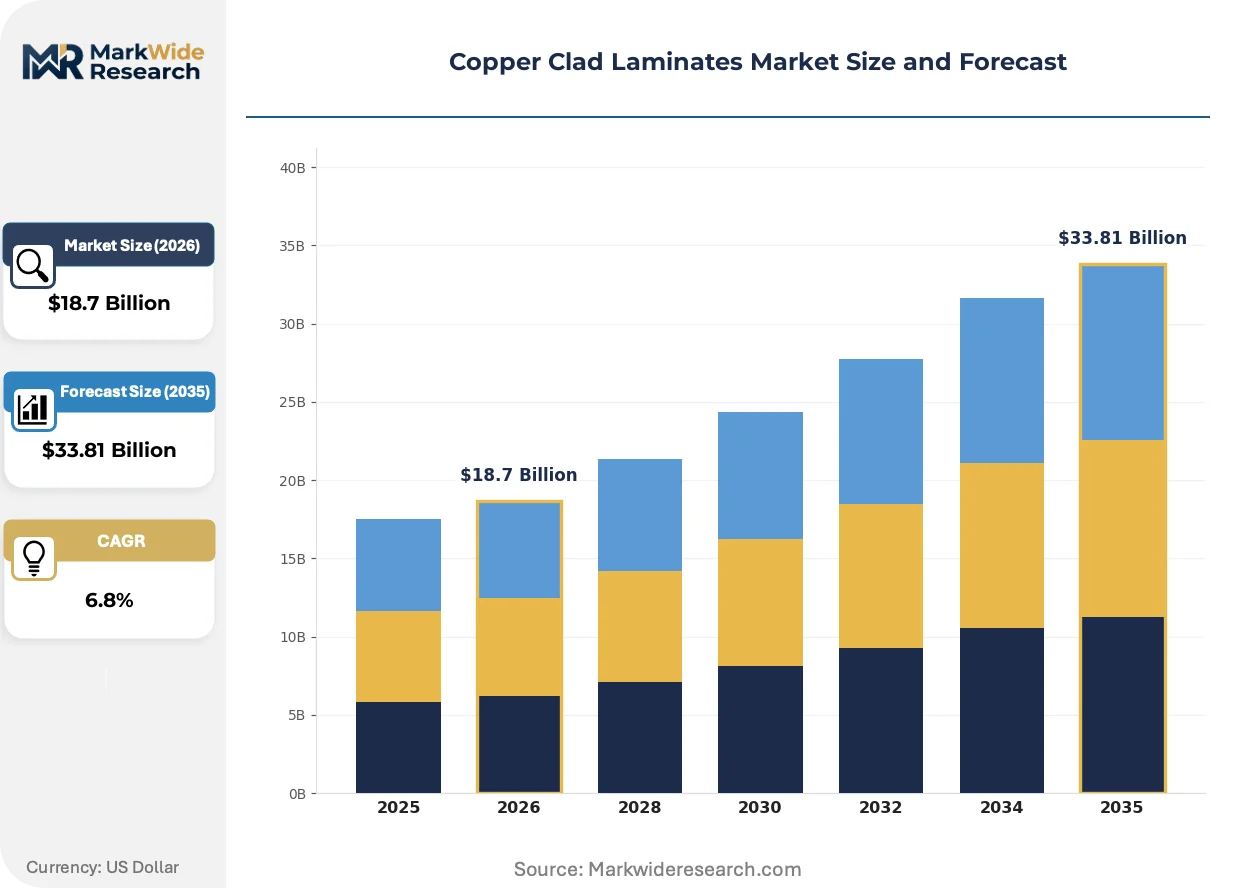
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FR-4, High-Frequency, Polyimide, Metal Core End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Technology: Standard Processing, Advanced Processing, Hybrid Technology, Laser Direct Imaging Application: PCB, RFID, High-Voltage Insulation, Military Electronics |
| Companies Covered | Kingboard Laminates Holdings Ltd., Shengyi Technology Co., Ltd., Nan Ya Plastics Corporation, ITEQ Corporation, Elite Material Co., Ltd., Taiwan Union Technology Corporation, Panasonic Holdings Corporation, Rogers Corporation, Doosan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Clad Laminates Market Emerging Trajectories
Resin chemistry and reinforcement architectures are diverging sharply between commodity FR-4 volume production and specialty formulations for high-frequency and high-thermal applications.
Modified epoxy systems with hydrocarbon and ceramic filler loadings are migrating from aerospace and military applications into commercial 5G infrastructure and automotive radar substrates. Base station OEMs in China and South Korea are accelerating qualification timelines for these materials. This migration is compressing the historical price premium between standard FR-4 and high-frequency laminates by enabling shared production assets.
REACH authorization requirements for brominated flame retardants are forcing European laminate importers to maintain parallel inventory streams of halogen-free and legacy formulations. The industrial consequence is elevated working capital requirements and shortened product lifecycle management for resin systems. Telecommunications infrastructure projects in Germany and France are experiencing 8-12 week procurement delays as suppliers navigate dual-compliance stocking.
Direct procurement relationships between semiconductor packaging houses and laminate manufacturers are displacing traditional PCB fabricator intermediation for advanced substrate development. OSATs in Taiwan and South Korea are establishing dedicated technical service agreements with resin compounders and copper foil mills. This channel restructuring is most visible in the CoWoS and EMIB packaging ecosystems where substrate performance directly determines yield economics.
Copper Clad Laminates Market Segmentation
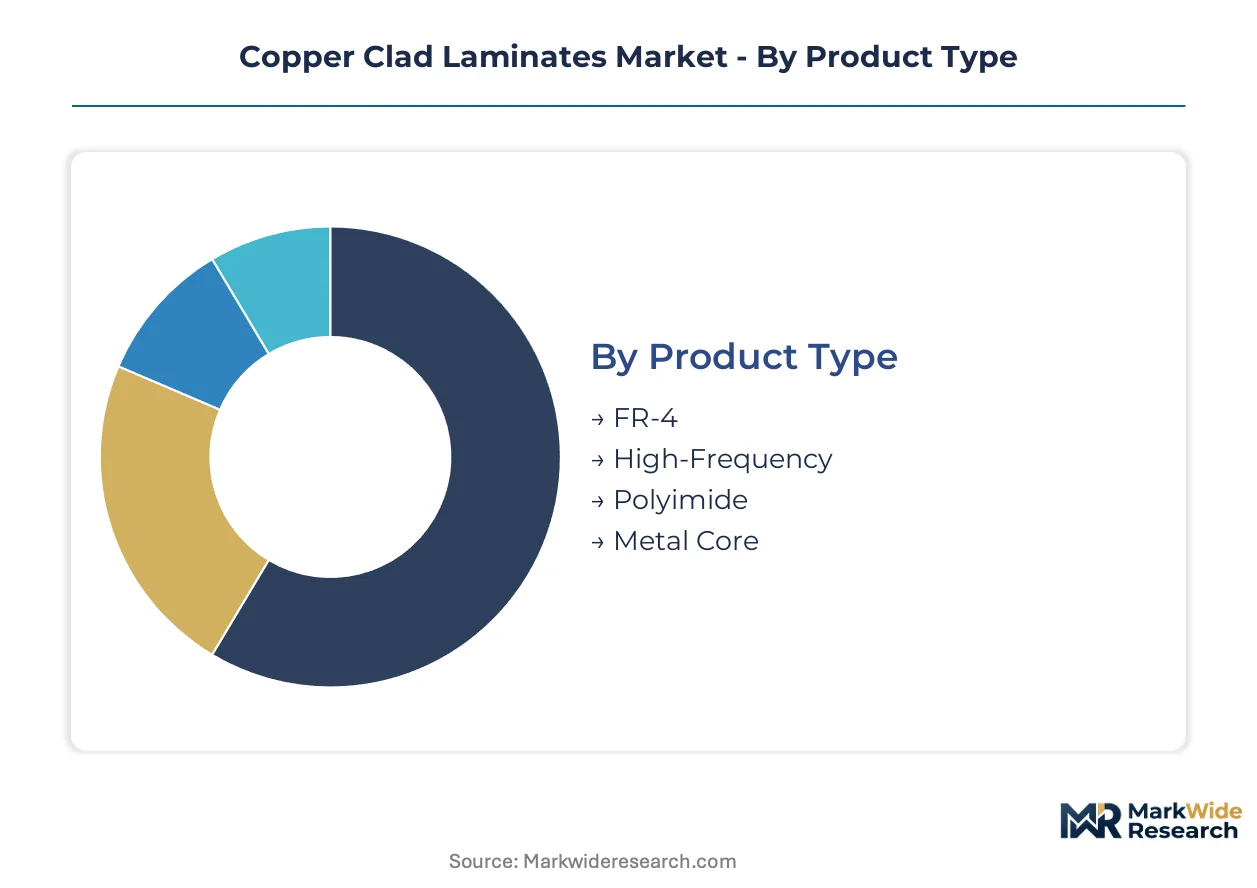
Copper clad laminate specifications diverge sharply across end-use applications, with telecommunications infrastructure demanding ultra-low-loss substrates while consumer electronics optimize for cost-efficient FR-4 volumes. Segmentation dynamics reflect the tension between qualification timelines for advanced packaging and the scale economics of commodity production.
Product Type:
FR-4 laminates turn inventory fastest through standardized PCB fabrication, whereas high-frequency and polyimide grades carry extended qualification cycles and premium pricing structures.
- FR-4:Glass-reinforced epoxy laminates with dielectric constants between 3.5 and 4.5 form the substrate backbone for consumer electronics and industrial controls. Demand clusters in Chinese manufacturing zones serving smartphone and appliance OEMs, where Kingboard Laminates and Shengyi Technology compete on scale and halogen-free formulation compliance.
- High-Frequency:Hydrocarbon-ceramic and PTFE-based laminates achieve sub-3.5 dielectric constants for millimeter-wave signal integrity. 5G base station deployments in South Korea and Taiwan are compressing qualification timelines for these materials as substrate loss specifications tighten.
- Polyimide:Flexible substrates for aerospace and medical electronics where thermal stability exceeds epoxy capabilities.
- Metal Core:Aluminum-backed laminates for LED and power electronics thermal management.
FR-4 dominates installed base. High-frequency laminates are where expansion concentrates.
End User:
Cost tiers separate military-aerospace qualification premiums from automotive radar volume ramps and telecommunications infrastructure deployment cycles.
- Telecommunications:Base station OEMs in China, South Korea, and Taiwan specify ultra-low-loss laminates for antenna arrays and backhaul equipment. NMPA and MIIT halogen-free mandates are accelerating domestic formulation upgrades.
- Consumer Electronics:Smartphone and laptop PCB volumes run through high-velocity FR-4 production lines with compressed margin structures.
- Automotive:Tier-1 suppliers in Germany and Japan are qualifying 77-81 GHz radar substrates at aerospace-grade specifications.
- Aerospace:Polyimide and high-Tg epoxy laminates for avionics and satellite systems with decade-long qualification horizons.
Consumer electronics commands volume share. Automotive radar substrates are climbing the fastest.
Technology:
Volume concentration favors standard processing, while advanced packaging roadmaps are displacing traditional fabrication methods.
- Standard Processing:Conventional lamination and etching workflows for multilayer PCBs in high-volume consumer applications.
- Advanced Processing:Sequential lamination and microvia drilling for HDI substrates in smartphone and server boards.
- Hybrid Technology:Combining rigid and flexible laminate processing for medical and automotive modules.
- Laser Direct Imaging:Maskless exposure systems for fine-line patterning in semiconductor packaging substrates.
Standard processing anchors production throughput. Laser direct imaging is gaining share fastest for advanced node packaging.
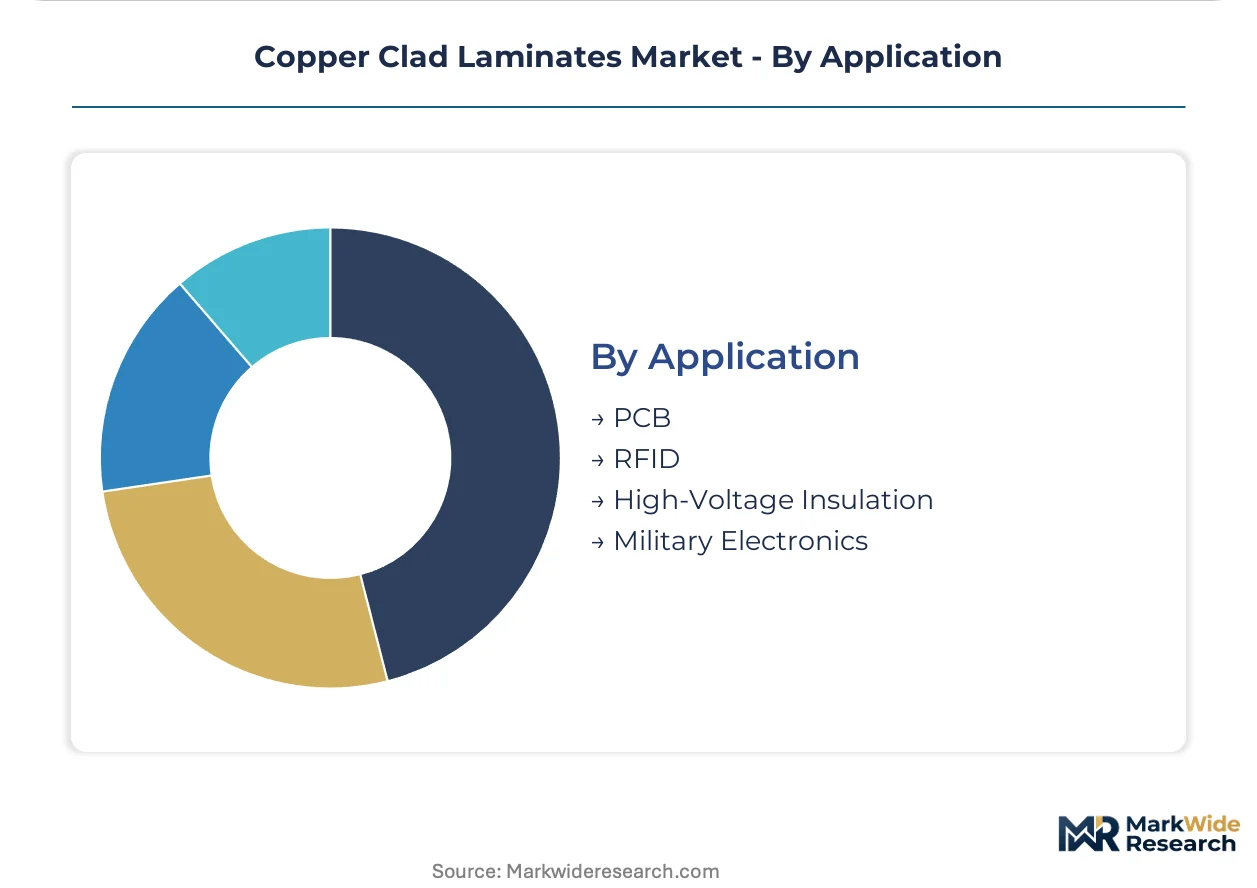
Application:
Maturity gradients separate established PCB volumes from emerging RFID and high-voltage insulation segments with distinct qualification barriers.
- PCB:The foundational application spanning single-layer to multilayer fabrication for all electronic equipment categories.
- RFID:Flexible and rigid-flex laminates for contactless identification tags in logistics and retail.
- High-Voltage Insulation:Thick copper and specialized resin systems for power electronics and electric vehicle inverters.
- Military Electronics:ITAR-controlled substrates with traceability requirements and extended testing protocols.
PCB applications dominate laminate consumption. High-voltage insulation for power electronics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications OEMs and semiconductor packaging houses cluster procurement decisions in East Asian manufacturing corridors, with qualification programs extending into European automotive electronics and Indian electronics manufacturing incentive zones.
China
5G base station deployments and advanced packaging substrate demand drive laminate consumption across the Yangtze River Delta and Pearl River Delta. NMPA and MIIT enforce halogen-free GB standards for telecommunications infrastructure substrates. Shenzhen and Suzhou host concentrated laminate fabrication clusters serving domestic PCB and OSAT ecosystems.
South Korea
Memory semiconductor packaging and automotive radar module production create demand for ultra-thin core and high-frequency laminates. MFDS maintains chemical substance registration requirements for electronic materials imports. Seoul Capital Area and Busan-Ulsan corridor concentrate laminate qualification programs with CoWoS packaging houses.
Taiwan
Advanced semiconductor packaging roadmaps from TSMC and OSAT partners dictate substrate specifications for 2.5D and 3D integration schemes. The national communications regulator enforces electromagnetic compatibility standards for telecommunications laminates. Hsinchu Science Park and Taoyuan Aerotropolis cluster laminate technical service agreements with packaging foundries.
Germany
Tier-1 automotive electronics suppliers qualify 77-81 GHz radar substrates for advanced driver assistance systems. REACH authorization requirements for brominated flame retardants force dual-track inventory management for laminate importers. Bavaria and Baden-Württemberg host automotive electronics development centers sourcing high-frequency materials.
India
PLI scheme allocations for semiconductor packaging and PCB manufacturing attract laminate qualification programs from East Asian suppliers. BIS certification mandates for electronic substrates create compliance entry barriers. Gujarat and Karnataka host emerging electronics manufacturing clusters where laminate distributors establish technical service presence.
Copper Clad Laminates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around scale-driven commodity producers, technology-differentiated specialists, and vertically integrated material suppliers. Three strategic archetypes dominate: FR-4 volume leaders optimizing cost positions, high-frequency formulation specialists capturing telecommunications premiums, and resin-compounder-copper-foil integrators controlling input costs. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing dedicated copper foil supply agreements and establishing technical service agreements with semiconductor packaging houses.
Among East Asian laminate fabricators, Kingboard Laminates Holdings Ltd., Shengyi Technology Co., Ltd., and Panasonic Holdings Corporation occupy distinct archetype positions. Kingboard Laminates Holdings Ltd. exemplifies the scale-driven commodity tier through its vertical integration from copper foil production. Shengyi Technology Co., Ltd. represents the formulation-specialist archetype with concentrated R&D intensity in halogen-free systems. Panasonic Holdings Corporation anchors the technology-differentiated segment through proprietary resin system development for high-frequency applications.
| Leading Market Players |
|---|
| Kingboard Laminates Holdings Ltd. |
| Shengyi Technology Co., Ltd. |
| Nan Ya Plastics Corporation |
| ITEQ Corporation |
| Elite Material Co., Ltd. |
| Taiwan Union Technology Corporation |
| Panasonic Holdings Corporation |
| Rogers Corporation |
| Doosan Corporation |
| Others |
Supply Flow & Price Mechanics
Electrodeposited copper foil production clusters in China and Japan concentrate upstream supply, anchoring margin pools in high-frequency laminate formulations where substrate loss specifications command premium positioning. Rolled-annealed foil allocations from Japanese mills feed directly into telecommunications infrastructure qualification programs, compressing pricing power at the commodity FR-4 tier while amplifying it in millimeter-wave grades.
Pricing Analysis
Cost-plus contracts with copper cathode indexation dominate raw material pass-through structures, insulating laminate fabricators from LME volatility while compressing absolute margin capture. Price differentiation rests on halogen-free certification tiers under NMPA GB standards and volume scale commitments from smartphone PCB aggregators. Pricing pressure stems from FR-4 oversupply in Chinese manufacturing zones, eroding spot market realizations. Consumer electronics OEMs exhibit acute price sensitivity, whereas base station OEMs prioritize dielectric performance over unit economics.
Supply Chain Analysis
Export-control regimes limiting PTFE resin and ceramic filler technologies constrain laminate formulation flows from US and Japanese specialty chemical suppliers. Manufacturing concentrates in China, Taiwan, and South Korea, with resin compounding and copper foil surface treatment chemistry drawing from Japanese and German precursor specialists. Single-source vulnerability sits with proprietary roughening formulations from Nagoya-area chemical suppliers. Distribution runs through PCB fabricator intermediaries for standard grades, while advanced packaging substrates move through direct technical service agreements with OSATs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as organic substrate alternatives and glass-core interposer technologies threaten traditional laminate positioning in advanced packaging nodes.
For Market Incumbents: Harden copper foil supply security through captive electrodeposited capacity or long-term offtake with Japanese mills. Deepen halogen-free formulation IP to preempt REACH-driven specification shifts in European telecommunications infrastructure. Defensive consolidation in resin compounding capabilities counters emerging Chinese specialty chemical entrants. For New Entrants and Emerging Players: India's PLI scheme allocations for semiconductor packaging and PCB manufacturing represent the most penetrable entry point for laminate qualification programs. Automotive radar substrate supply to German Tier-1 suppliers offers secondary white-space, with 77-81 GHz qualification timelines compressing relative to aerospace-grade precedents. Go-to-market execution through technical service partnerships with Gujarat-based OSATs accelerates BIS certification navigation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Japanese resin compounders holding proprietary hydrocarbon-ceramic filler IP. Long-term viability hinges on 5G-Advanced and 6G infrastructure deployment sustaining ultra-low-loss substrate demand. Watch for NMPA halogen-free mandate acceleration as inflection signal for formulation-specialist acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Captive electrodeposited capacity insulates Kingboard Laminates from Japanese mill allocation risk during demand surges. |
| Halogen-Free Formulation R&D | Shengyi Technology's GB standard compliance investments preempt NMPA enforcement tightening in Yangtze River Delta clusters. |
| Direct OSAT Technical Service Agreements | Panasonic Holdings bypasses PCB fabricator intermediation for CoWoS substrate development with TSMC packaging partners. |
| Automotive Radar Qualification Programs | Rogers Corporation leverages aerospace-grade PTFE expertise for 77-81 GHz radar module penetration at German Tier-1s. |
| India PLI Scheme Localization | Taiwan Union Technology establishes Gujarat technical presence to capture semiconductor packaging substrate incentives. |
Methodological Framework
The analysis maps FR-4 commodity production, high-frequency telecommunications laminates, polyimide flexible substrates, and metal-core thermal management grades, each validated through resin compounder technical directors, PCB fabricator procurement leads, OSAT substrate engineers, and copper foil mill sales managers. Primary interview intelligence triangulates against customs trade data, MIIT GB standard filings, NMPA halogen-free certification registries, and SEC 10-K disclosures from listed laminate manufacturers. Bottom-up capacity and utilization estimates reconcile with top-down end-use consumption models across consumer electronics, telecommunications infrastructure, automotive electronics, and semiconductor packaging applications.
Assumption sets held copper cathode pricing and REACH authorization timelines fixed while varying 5G base station deployment cadence and advanced packaging substrate thinning rates across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, processing technology complexity, and regional regulatory cluster. CAGRs derive from rolling average growth rate analysis applied to laminate square-meter consumption by grade, with semiconductor packaging roadmaps and telecommunications infrastructure investment cycles as primary demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese manufacturing PMI, South Korean memory capital expenditure, or European automotive production would shift the trajectory. Forecasts reflect documented assumptions on substrate qualification timeline compression and copper foil supply elasticity. Material shifts in NMPA enforcement intensity or PTFE resin export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Phenolic Panel Market
Composite Materials
Biocomposites Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Structural Core Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Case Material Market
Composite Materials
Hybrid Composites Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Marine Composites Market
Composite Materials
Tow Prepreg Market