
 Ultra-Lightweight Cement Composites Market | 2026-2036
Ultra-Lightweight Cement Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Lightweight Cement Composites Market Analytics
Carbon nanotube reinforcement is tilting fabrication protocols toward thinner, higher-strength sections that slash dead loads without sacrificing compressive performance. CEMEX leverages its transnational ready-mix network to distribute engineered lightweight formulations across diverse climate zones. Sika AG anchors its position through adhesive and additive chemistry that bonds microsphere aggregates into cohesive matrices. Owens Corning specializes in glass fiber compatibility layers that bridge cementitious binders with synthetic reinforcement.
Ultra-lightweight cement composites blend Portland cement, hollow ceramic microspheres, and aerating agents to achieve densities below 1,200 kg per cubic meter while retaining structural load capacity for mid-rise frames. Precast panels dominate current output volumes due to factory-controlled curing and dimensional precision that reduce on-site labor exposure. Structural elements represent the fastest-growing category as seismic retrofit codes in earthquake-prone zones specify reduced mass-to-strength ratios. Carbon nanotube reinforcement commands premium positioning where conductivity and crack resistance justify material cost escalation over conventional mixing.
EPA emissions standards for Portland cement kilns are compressing clinker content allowances and pushing formulators toward supplementary cementitious materials that lighten composite density. REACH registration requirements for nanomaterials in Europe mandate toxicity documentation that filters carbon nanotube suppliers to certified tier-one sources. ISO 21887 performance benchmarks for lightweight aggregate concrete are becoming default procurement specifications in public infrastructure tenders. Stakeholders must monitor evolving embodied carbon accounting rules that will recalibrate material selection criteria across building certification programs.
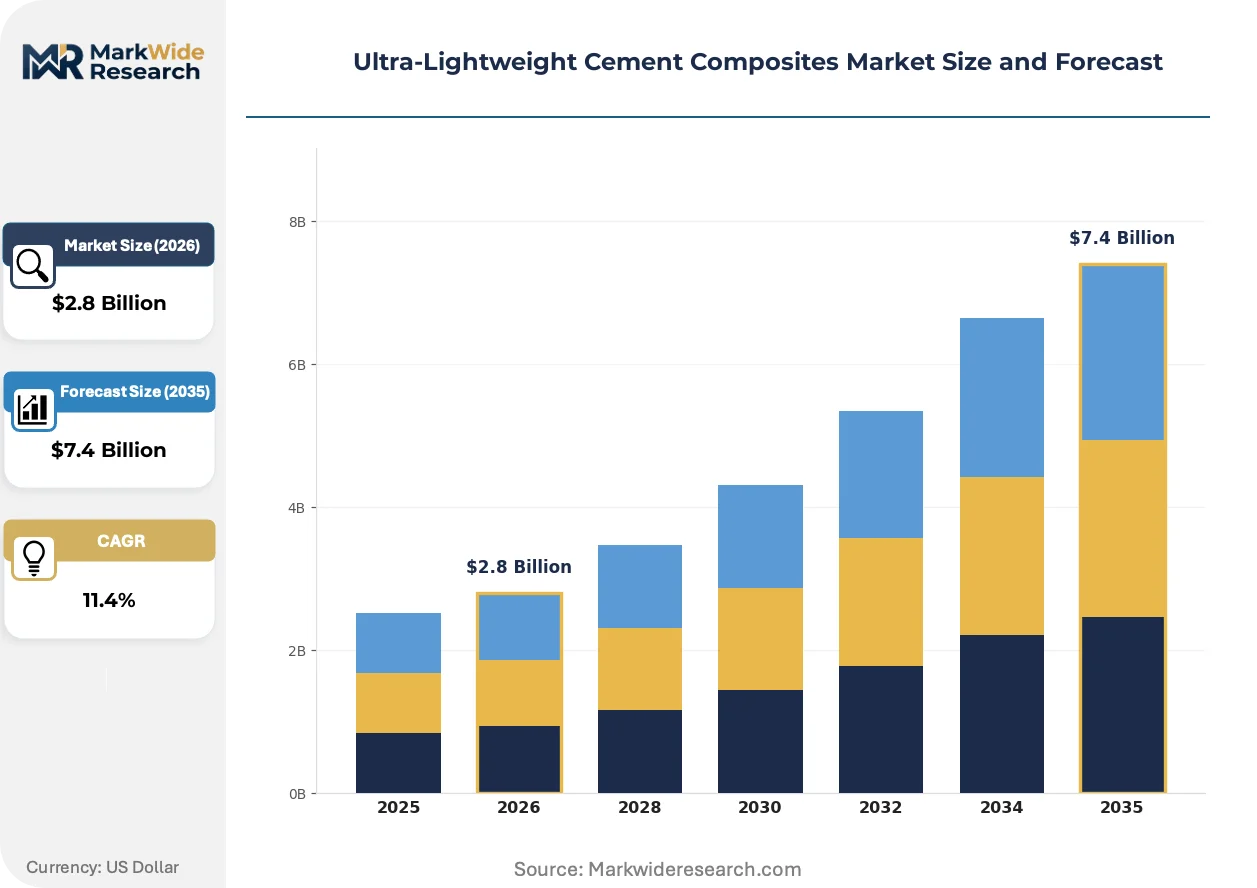
Market Dynamics
Carbon nanotube reinforcement protocols are compressing traditional section thickness requirements while EU Green Deal embodied carbon thresholds force rapid reformulation of binder chemistries across commercial construction supply chains.
Growth Catalysts
- EU Green Deal thresholds:Embodied carbon mandates for construction materials are accelerating specification of ultra-lightweight alternatives in German high-rise envelope systems.
- Seismic retrofit codes:Earthquake-prone zones in Japan and California are mandating reduced mass-to-strength ratios for structural rehabilitation projects.
- Hollow ceramic microsphere advancement:Improved thermal performance characteristics are expanding facade retrofit applications in Nordic commercial buildings.
Market Restraints
- REACH nanomaterial registration:Toxicity documentation requirements for carbon nanotubes restrict supplier pools to certified tier-one sources, elevating input costs.
- Clinker content compression:EPA emissions standards for Portland cement kilns limit traditional binder availability, forcing costly supplementary cementitious material substitution.
- Precast logistics concentration:Factory-controlled curing requirements concentrate production in Rhine-Ruhr and similar industrial clusters, extending delivery radii for remote projects.
Strategic Opportunities
- India's smart city infrastructure:Mass urban renewal programs specify lightweight precast panels for rapid vertical construction in Mumbai and Bangalore metropolitan zones.
- ISO 21887 procurement defaults:Performance benchmarks for lightweight aggregate concrete are becoming mandatory in Australian and Canadian public infrastructure tenders.
- Aerospace-grade facade convergence:Composite manufacturing techniques from aviation supply chains are transferring to commercial building envelope production.
Industry Challenges
- Carbon nanotube handling certification:Specialized safety protocols for nanomaterial fabrication require workforce retraining that extends plant commissioning timelines.
- Multi-material bonding complexity:Glass fiber compatibility layers demand precise chemistry control that legacy quality systems struggle to monitor consistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Lightweight Cement Composites Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast Panels, Structural Elements, Cast-in-Place, Lightweight Blocks End User: Commercial Buildings, Residential Developments, Infrastructure, Industrial Projects Application: Load-Bearing Structures, Non-Load-Bearing Walls, Flooring Solutions, Roofing Systems Technology: 3D Printing, Carbon Nanotube Reinforcement, Eco-Friendly Options, Conventional Mixing |
| Companies Covered | CEMEX, CRH plc, Sika AG, Owens Corning, Saint-Gobain, BASF SE, Heidelberg Materials, Lehigh White Cement, Holcim Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Lightweight Cement Composites Market Evolving Landscape
Material science breakthroughs are compressing density-to-strength ratios while regulatory carbon accounting recalibrates procurement criteria across building certification programs worldwide.
Carbon nanotube reinforcement is collapsing conventional section thickness benchmarks in structural applications. Seismic retrofit contractors in Japan and California are specifying nanotube-doped matrices for mid-rise frames. The technology is collapsing dead load calculations that previously governed foundation engineering decisions.
REACH registration requirements for nanomaterials are filtering carbon nanotube suppliers to certified tier-one documentation holders. Industrial consequence includes supply base consolidation and premium pricing for compliant feedstock. German and French formulators are responding by vertically integrating nanotube sourcing through captive supply arrangements.
Specification-driven procurement now prioritizes embodied carbon metrics over first-cost comparisons in Nordic and Benelux commercial construction. Engineering consultants are displacing traditional quantity surveyors as primary influencers in material selection. This shift is most visible in Netherlands and Denmark high-rise envelope tenders where BREEAM certification thresholds dictate composite specifications.
Ultra-Lightweight Cement Composites Market Segmentation
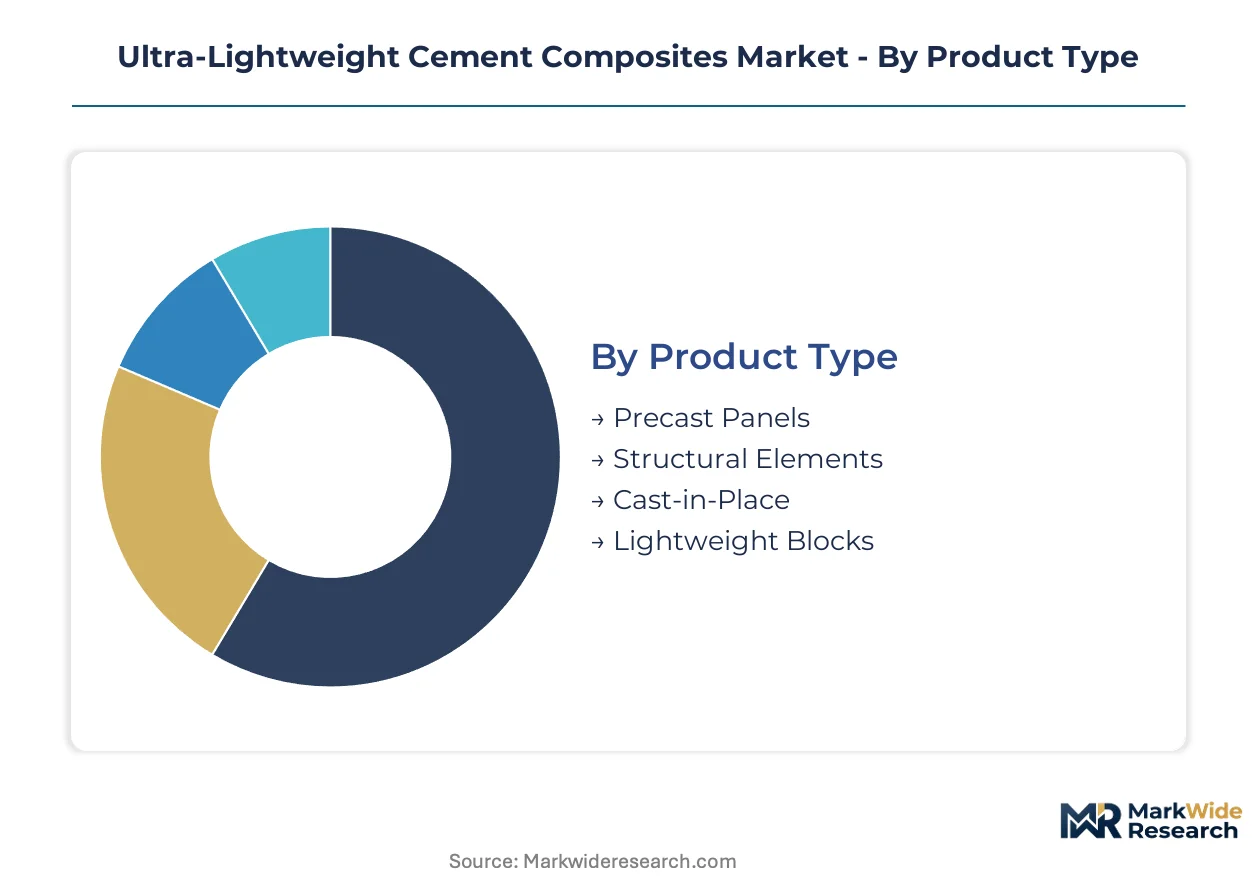
Ultra-lightweight cement composites fragment across four analytical dimensions that determine procurement pathways, fabrication protocols, and margin structures. Product type governs manufacturing location and curing requirements. Technology selection locks in performance premiums and regulatory compliance tiers. End user and application segments channel demand toward distinct specification standards.
Product Type:
Volume concentration and factory proximity dictate competitive positioning across fabrication formats.
- Precast Panels:Factory-controlled curing environments deliver dimensional precision that minimizes on-site labor exposure. Rhine-Ruhr metropolitan cluster concentrates installed capacity for German high-rise envelope systems where EU Green Deal embodied carbon thresholds apply.
- Structural Elements:Seismic retrofit codes in Japan and California mandate reduced mass-to-strength ratios for mid-rise frame rehabilitation. Carbon nanotube doping commands premium positioning where conductivity and crack resistance justify material cost escalation.
- Cast-in-Place:Site-poured applications retain share in remote projects beyond precast logistics radii.
- Lightweight Blocks:Masonry-format products serve residential envelope applications with lower engineering specification thresholds.
Precast Panels hold installed capacity. Structural Elements is rotating up the share rankings.
End User:
Customer type determines specification intensity, certification requirements, and contract value concentration.
- Commercial Buildings:Aerospace-grade facade retrofitting accelerates adoption in Nordic and Benelux markets where BREEAM certification thresholds dictate composite selection. Engineering consultants displace quantity surveyors as primary material influencers.
- Infrastructure:ISO 21887 performance benchmarks are becoming mandatory procurement specifications in Australian and Canadian public tenders. Hollow ceramic microsphere formulations expand thermal performance applications.
- Residential Developments:Cost-sensitive segment favors conventional mixing technologies over nanomaterial reinforcement.
- Industrial Projects:Specialized load requirements and chemical exposure resistance drive custom formulation demand.
Commercial Buildings anchor specification-driven procurement. Infrastructure is climbing the fastest as public tender volumes expand.
Application:
Functional role in building systems determines structural engineering review intensity and liability exposure.
- Load-Bearing Structures:Foundation engineering decisions hinge on dead load calculations that carbon nanotube reinforcement collapses. Seismic zones in Japan specify these matrices for structural rehabilitation where mass reduction governs design.
- Non-Load-Bearing Walls:Facade retrofit applications concentrate in Germany's sustainable high-rise envelope systems. Thermal performance characteristics of hollow ceramic microspheres drive Nordic commercial building adoption.
- Flooring Solutions:Mid-rise frame applications balance span capability against weight reduction targets.
- Roofing Systems:Weather exposure and insulation integration requirements shape formulation selection.
Load-Bearing Structures commands engineering-intensive premiums. Non-Load-Bearing Walls is gaining share fastest through facade retrofit volumes.
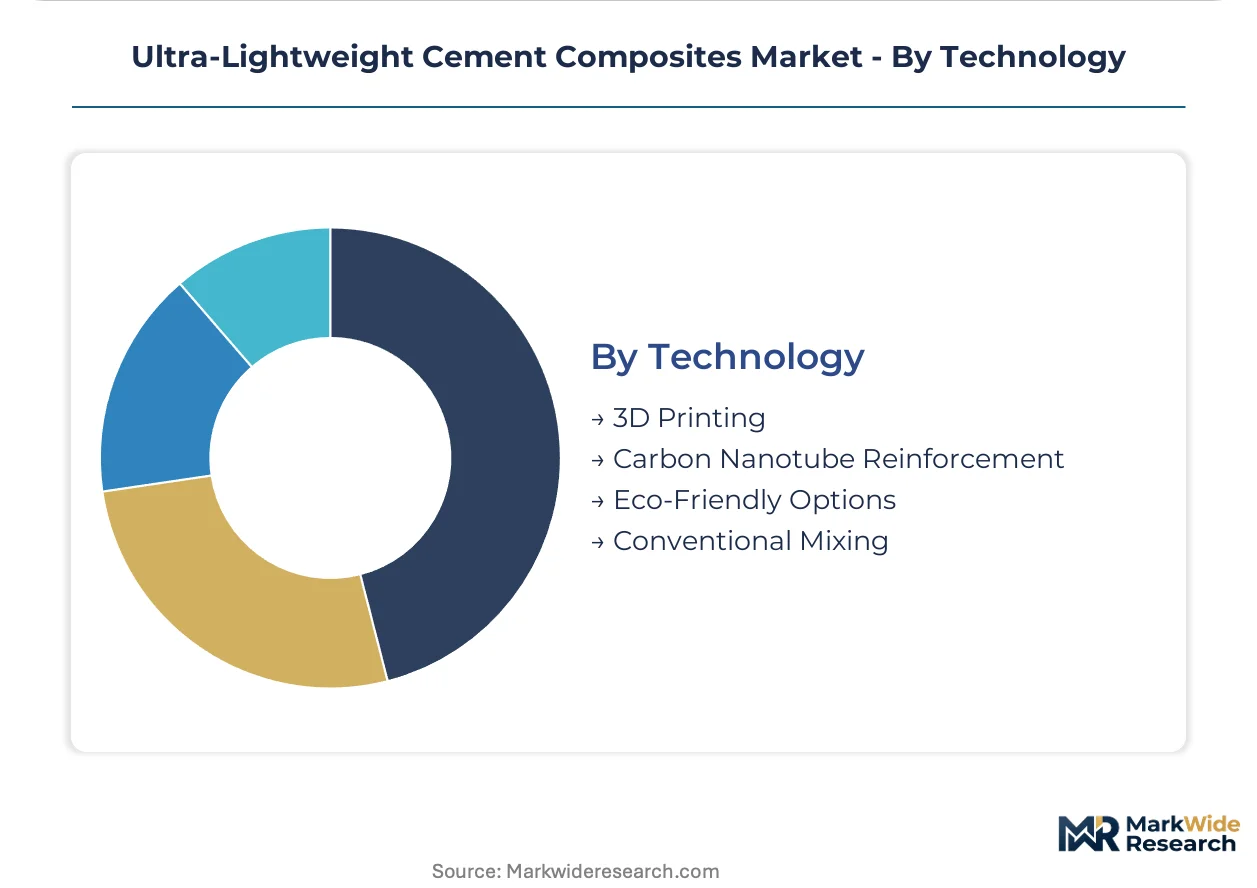
Technology:
Process maturity and regulatory clearance status stratify supplier positioning and pricing power.
- Carbon Nanotube Reinforcement:REACH registration requirements for nanomaterials filter suppliers to certified tier-one documentation holders. Toxicity documentation mandates consolidate supply bases and elevate input costs for German and French formulators.
- 3D Printing:Additive manufacturing protocols from aviation supply chains transfer to commercial building envelope production. Layer-by-layer deposition enables complex geometries impossible in conventional casting.
- Eco-Friendly Options:EPA emissions standards for Portland cement kilns compress clinker content allowances and push formulators toward supplementary cementitious materials.
- Conventional Mixing:Legacy protocols retain cost advantage where performance specifications permit standard lightweight aggregate formulations.
Conventional Mixing holds installed capacity. Carbon Nanotube Reinforcement is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering consultants and facade retrofit contractors concentrate procurement authority across four distinct national markets where embodied carbon regulations and seismic codes reshape material specifications.
Germany
The Rhine-Ruhr metropolitan cluster anchors European production capacity for precast panel fabrication serving high-rise envelope systems. EU Green Deal embodied carbon thresholds tighten compliance requirements for commercial construction tenders. Bavaria's engineering consultancies displace traditional quantity surveyors as primary material influencers in BREEAM-certified projects.
United States
Seismic retrofit contractors in California specify reduced mass-to-strength ratios for structural rehabilitation of mid-rise frames. EPA emissions standards for Portland cement kilns compress clinker content allowances and push formulators toward supplementary cementitious materials. The Pacific Northwest concentrates demand for hollow ceramic microsphere formulations in thermal performance applications.
Japan
Seismic retrofit codes mandate carbon nanotube-doped matrices for structural elements in earthquake-prone urban zones. METI building standards accelerate specification of lightweight precast systems for vertical construction. The Kanto region around Tokyo concentrates installed fabrication capacity for aerospace-grade facade convergence projects.
India
Smart city infrastructure programs in Mumbai and Bangalore metropolitan zones specify lightweight precast panels for rapid vertical construction. BIS performance standards for lightweight aggregate concrete guide procurement in public infrastructure tenders. Gujarat's industrial corridor attracts capacity expansion for factory-controlled curing operations.
Australia
ISO 21887 performance benchmarks become mandatory procurement specifications in federal and state infrastructure tenders. Hollow ceramic microsphere formulations expand into commercial facade retrofit applications in Sydney and Melbourne. New South Wales engineering consultancies prioritize embodied carbon metrics over first-cost comparisons in certification-driven projects.
Ultra-Lightweight Cement Composites Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where transnational ready-mix networks face off against adhesive chemistry specialists and glass fiber compatibility layer providers. Three archetypes dominate: integrated building materials conglomerates with distribution scale, specialty chemical formulators with additive expertise, and composite reinforcement specialists bridging cementitious binders with synthetic matrices. Competitive moves concentrate on backward integration into nanomaterial sourcing and strategic partnerships for aviation-to-construction technology transfer.
Among integrated building materials conglomerates, CEMEX S.A.B. de C.V. and CRH plc exemplify the channel-control archetype through transnational distribution networks. Sika AG occupies a position within the specialty chemical tier, representing formulators who anchor market presence through adhesive and bonding chemistry expertise. These three entities collectively illustrate the competitive tension between scale-driven logistics players and technology-driven formulation specialists.
| Leading Market Players |
|---|
| CEMEX |
| CRH plc |
| Sika AG |
| Owens Corning |
| Saint-Gobain |
| BASF SE |
| Heidelberg Materials |
| Lehigh White Cement |
| Holcim Ltd |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr logistics corridor links hollow ceramic microsphere suppliers to German precast fabricators, with freight cost volatility compressing margins for remote project deliveries while enabling sharp price differentiation between captive-supply Rhine-Ruhr producers and dependent buyers in Nordic markets.
Pricing Analysis
Cost-plus contracts with clinker price indexation dominate procurement between precast panel fabricators and ready-mix suppliers. Price differentiation rests on REACH nanomaterial certification tier and volume scale, with carbon nanotube-doped formulations commanding substantial premiums over conventional mixing. Pricing pressure stems from EPA emissions standards compressing Portland cement availability and elevating supplementary cementitious material substitution costs. Infrastructure buyers exhibit highest price sensitivity, while commercial building developers prioritize embodied carbon metrics over first-cost comparisons.
Supply Chain Analysis
Supplier-financing facilities from Sika AG and Heidelberg Materials extend 90-day payment terms to precast panel distributors, easing working capital constraints for mid-tier contractors. Supply concentrates in Germany, Japan, and India, with hollow ceramic microspheres, carbon nanotubes, and aerating agents anchoring raw material dependencies. Single-source vulnerability around REACH-certified nanotube suppliers elevates disruption risk. Distribution runs through transnational ready-mix networks and project-direct precast logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-lightweight cement composites constitute a high-growth materials disruption as EU Green Deal embodied carbon thresholds recalibrate procurement criteria across commercial construction. Carbon nanotube reinforcement protocols and seismic retrofit code convergence create sustained specification momentum.
For Market Incumbents: Insulate core margin positions by securing captive carbon nanotube supply through backward integration into REACH-certified feedstock partnerships. Expand precast curing capacity in Gujarat's industrial corridor to capture India's smart city infrastructure volumes. Lock in long-term offtake agreements with German engineering consultancies who now dictate material selection for BREEAM-certified high-rise envelopes.
For New Entrants and Emerging Players: Build out specialized formulation capabilities in hollow ceramic microsphere thermal performance systems for Nordic commercial facade retrofit applications. Target Australia's infrastructure segment where ISO 21887 benchmarks are becoming mandatory procurement defaults. Lead with eco-friendly supplementary cementitious material blends that satisfy EPA clinker compression requirements while undercutting nanotube-reinforced pricing tiers.
For Investors and Strategic Acquirers: Adhesive chemistry specialists with nanomaterial bonding expertise represent priority acquisition archetypes, as multi-material compatibility layers become critical differentiators. Monitor REACH registration completion timelines for tier-two carbon nanotube suppliers as inflection signals for supply base consolidation and premium pricing normalization. Long-term viability hinges on positioning ahead of embodied carbon accounting rule expansion across building certification programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanomaterial Supply | REACH certification requirements filter carbon nanotube suppliers to tier-one documentation holders, consolidating supply bases. |
| Capacity Expansion in Gujarat Industrial Corridor | India's smart city programs specify lightweight precast panels for rapid vertical construction in Mumbai and Bangalore zones. |
| Long-term Supply Agreement with Engineering Consultancies | Bavaria and Netherlands consultancies displace quantity surveyors as primary influencers in BREEAM-certified commercial tenders. |
| Green Manufacturing Transition to Supplementary Cementitious Materials | EPA emissions standards compress Portland cement kiln clinker content allowances, forcing binder chemistry reformulation. |
| Joint Venture for Aerospace-Grade Facade Technology Transfer | Aviation composite manufacturing techniques transfer to commercial building envelope production in Kanto region convergence projects. |
Research Methodology
A standing panel of precast plant managers, facade retrofit contractors, engineering consultancy specification leads, and hollow ceramic microsphere procurement directors provided ongoing calibration across the primary research phase. Secondary validation drew from EU Green Deal regulatory filings, EPA emissions compliance disclosures, ISO 21887 technical committee documentation, and REACH nanomaterial registration databases. Bottom-up volume triangulation from fabrication capacity audits cross-checked against top-down demand modeling from construction permit flows and tender award tracking.
Scenario-bracketing around EU embodied carbon threshold enforcement timelines, seismic code adoption rates in earthquake-prone zones, and carbon nanotube supply base consolidation outcomes framed the analytical envelope. Segmentation modeling spanned product type, end user category, application function, and technology maturity tier across the projection horizon. CAGRs derived from elasticity-adjusted volume projections reflecting clinker substitution cost curves and nanomaterial premium decay assumptions.
Stress conditions across Portland cement price volatility, REACH registration denial rates, and German high-rise construction permit issuance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost curves. Macroeconomic contraction, accelerated EU carbon border adjustments, or breakthroughs in alternative lightweight aggregate formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Phenolic Panel Market
Composite Materials
High Performance Composites Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Composite Rollers Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
CFRTP Market