
 Composite Material for Passenger Car Market | 2026-2036
Composite Material for Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Material for Passenger Car Market Insights
Carbon fiber layup technician availability is rotating from aerospace saturation toward automotive programs, unlocking capacity for passenger car series production. Toray Industries leverages its precursor supply chain to anchor Japanese OEM relationships. Hexcel Corporation competes through R&D intensity in thermoplastic unidirectional tapes. SGL Carbon specializes in automotive-specific braided preforms that reduce cycle times for German vehicle assemblers.
Composite material for passenger car denotes engineered combinations of reinforcement fibers and polymer matrices, typically achieving specific tensile strength above 300 MPa with density below 1.6 g/cm³, designed to replace stamped steel and aluminum in body-in-white and closure panels. Carbon fiber commands the highest value pool among product types but glass fiber dominates unit volume due to cost accessibility for exterior parts. Compression molding leads manufacturing stage adoption among Tier-1 suppliers seeking sub-three-minute cycle times at scale. Prepreg retains preference for low-volume performance variants where surface finish quality justifies higher material cost.
EPA tailpipe rules and the EU Green Deal carbon border adjustments are forcing OEMs to document lifecycle emissions from raw fiber production through vehicle end-of-life. NHTSA fuel economy standards and REACH chemical compliance create dual compliance burdens for suppliers serving multiple production geographies. Stakeholders must monitor how the EU AI Act and emerging digital product passport requirements reshape material traceability obligations before committing to long-term capacity investments.
Market Dynamics
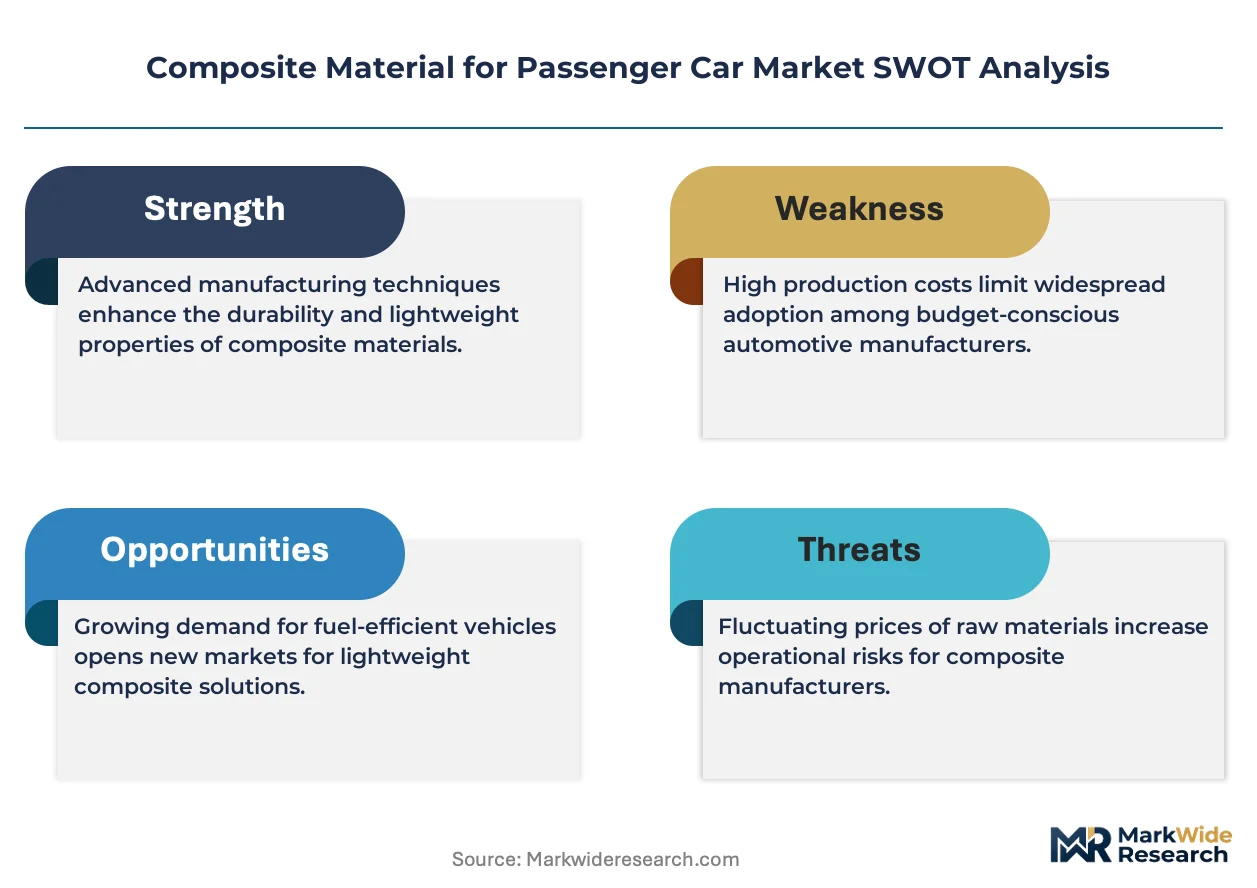
Automotive OEMs face mounting pressure to reduce vehicle mass as EPA tailpipe rules and EU Green Deal carbon border adjustments tighten simultaneously, forcing material substitution decisions that cascade through tiered supply networks.
Growth Catalysts
- EPA and NHTSA fuel economy mandates:US manufacturers must achieve fleet-wide efficiency gains that stamped steel cannot deliver, accelerating thermoplastic composite adoption in closure panels and floor pans.
- Carbon fiber precursor capacity expansion:Aerospace-saturated supply chains are releasing qualified technicians and autoclave capacity toward automotive qualification programs.
- China's dual carbon goals:MIIT production quotas for new energy vehicles favor lightweight platforms that glass fiber and carbon fiber composites enable.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber production depends on petroleum-derived precursor chemicals exposed to energy market fluctuations.
- Autoclave capacity concentration:Aerospace-dominated curing infrastructure in Germany and Japan limits automotive-scale throughput expansion.
- End-of-life recycling complexity:REACH chemical compliance and EU Green Deal circularity requirements impose unresolved technical barriers for thermoset matrix recovery.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic EV platform development creates first-mover advantage for localized preform manufacturing.
- Thermoplastic-thermoset hybrid processing:Compression molding of organosheets enables sub-two-minute cycle times previously unattainable with prepreg autoclave methods.
- Digital product passport mandates:EU AI Act traceability requirements favor suppliers with blockchain-enabled fiber-to-vehicle documentation systems.
Industry Challenges
- Carbon fiber layup technician scarcity:Aerospace wage premiums drain qualified labor pools just as automotive programs require scale-up.
- Multi-jurisdiction certification timelines:Simultaneous EPA, ECHA, and MIIT homologation processes extend program development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Material for Passenger Car Market |
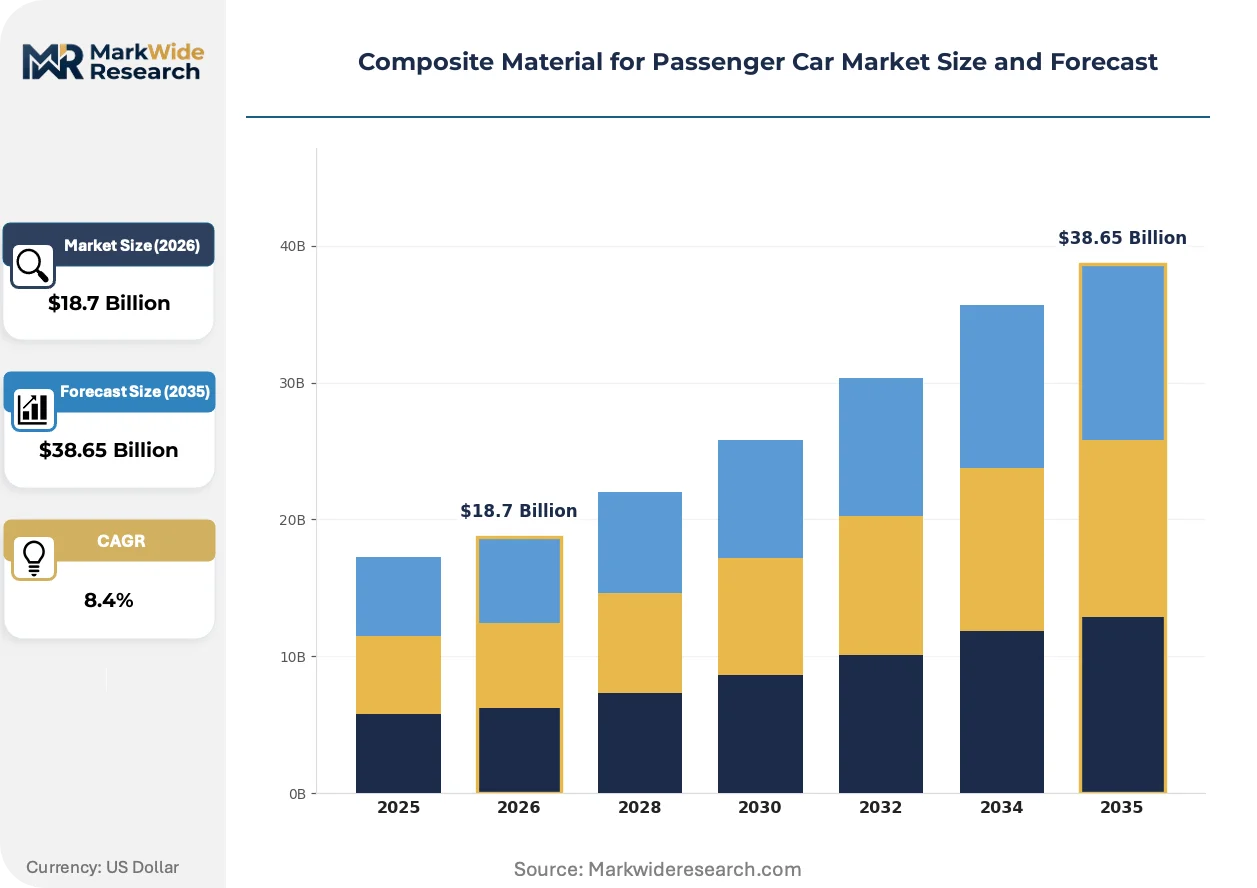
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber Application: Interior Parts, Exterior Parts, Structural Components, Under-the-Hood Parts End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Prepreg, Infusion, Compression Molding, Thermoforming |
| Companies Covered | Toray Industries, Teijin Limited, SGL Carbon, Hexcel Corporation, Mitsubishi Chemical Group Corporation, Solvay, Owens Corning, IDI Composites International, Gurit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Material for Passenger Car Market Trends and Innovations
Material processing pathways are diverging as speed-to-volume and surface-finish requirements split automotive composite strategies into parallel technical tracks.
Thermoplastic unidirectional tapes are fragmenting the traditional prepreg dominance in structural automotive applications. Tier-1 suppliers at BMW and Mercedes-Benz platforms are qualifying these materials for A-pillar and roof bow reinforcement. The shift is fragmenting equipment supplier relationships as press manufacturers displace autoclave vendors in new capacity planning.
EU Green Deal carbon border adjustments are forcing lifecycle emissions documentation from raw fiber production through vehicle end-of-life. OEMs must now verify precursor energy sources and matrix chemistry against ECHA REACH substance restrictions. German vehicle assemblers are responding by qualifying recycled carbon fiber grades that reduce Scope 3 emissions in corporate sustainability reporting.
Direct long-fiber thermoplastic purchasing is compressing traditional distribution hierarchies as compounders establish mill-direct relationships with seating and interior Tier-1s. Material specification authority is migrating from distributor technical sales teams to OEM platform engineering groups. This pattern is most visible in United States pickup truck programs where interior trim weight reduction targets exceed previous generation benchmarks.
Composite Material for Passenger Car Market Segmentation
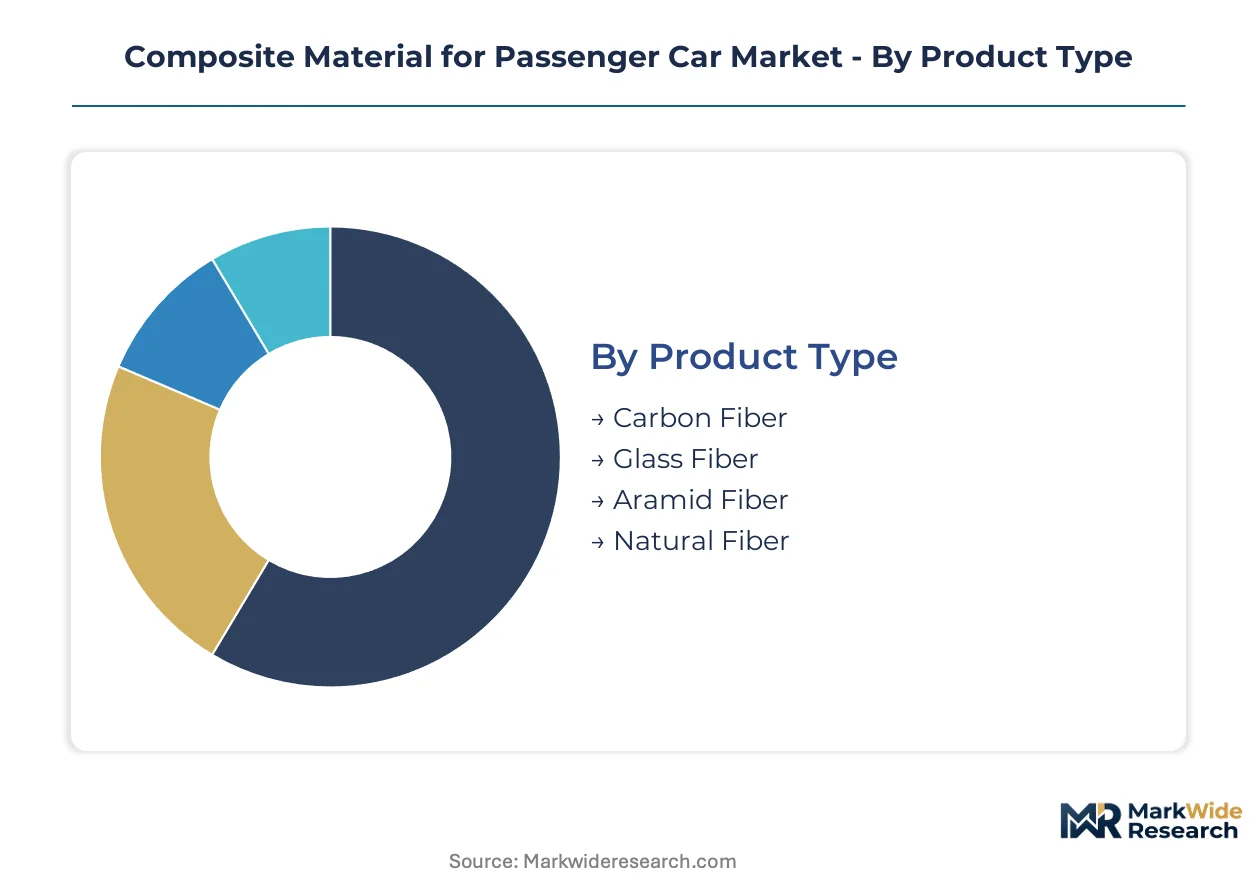
Composite material specification in passenger cars fragments across fiber chemistry, structural function, and manufacturing velocity. Regulatory pressure on lifecycle emissions and crashworthiness forces distinct technical choices within each segment category.
Product Type:
REACH substance restrictions and EPA fuel economy mandates differentiate fiber selection by emissions intensity and recyclability pathway.
- Carbon Fiber:PAN-based precursors achieve tensile strength above 3,000 MPa with density near 1.6 g/cm³. Demand concentrates in German OEM structural programs where KBA crashworthiness standards favor specific energy absorption metrics that carbon fiber delivers. EU Green Deal carbon border adjustments penalize virgin precursor energy intensity, accelerating recycled fiber qualification.
- Glass Fiber:E-glass and S-glass variants dominate unit volume through cost accessibility below carbon fiber by an order of magnitude. Chinese MIIT new energy vehicle quotas drive glass fiber consumption in battery enclosure and exterior panel applications across domestic EV platforms.
- Aramid Fiber:Kevlar and Twaron grades provide ballistic-grade impact resistance for motorsport-derived road car variants. Tier-1 suppliers serving limited-production performance models specify aramid for door intrusion beams.
- Natural Fiber:Flax and hemp fiber composites reduce petrochemical dependency for interior trim applications. BMW and Mercedes-Benz qualify these materials for dashboard and door panel substrates under corporate sustainability targets.
Established volume favors glass fiber; emerging adoption favors carbon fiber.
Application:
Cost tier stratification separates commodity exterior parts from engineered structural substitution.
- Interior Parts:Door panels, seat shells, and dashboard carriers utilize glass fiber thermoplastics for mass reduction without surface finish requirements. United States pickup truck programs specify long-fiber polypropylene for center console and trim weight targets.
- Exterior Parts:Fenders, hoods, and liftgates require Class A surface quality that compression-molded SMC and carbon fiber prepregs achieve. German vehicle assemblers lead exterior carbon fiber adoption for hood and roof applications on performance variants.
- Structural Components:Floor pans, A-pillars, and roof bows demand specific stiffness metrics that carbon fiber unidirectional tapes satisfy. BMW i-series platforms and Mercedes-Benz EQ architectures qualify thermoplastic organosheets for structural reinforcement.
- Under-the-Hood Parts:Engine covers, battery housings, and thermal shields require heat resistance above 150°C that glass fiber phenolic and PPS composites provide. Chinese EV battery enclosure specifications drive glass fiber SMC consumption.
Interior applications anchor current volume; structural components are climbing the fastest.
End User:
Procurement authority migration reshapes specification control across tier levels.
- OEMs:Platform engineering groups at Volkswagen, Toyota, and GM now dictate material specifications directly, bypassing traditional distributor hierarchies for long-fiber thermoplastic compounds.
- Aftermarket Suppliers:Carbon fiber aesthetic components for vehicle customization operate outside homologation pathways, serving enthusiast markets with lower regulatory burden.
- Tier-1 Suppliers:Magna, Faurecia, and Plastic Omnium operate compression molding lines at sub-three-minute cycle times for closure panel series production.
- Vehicle Assemblers:Final assembly plants integrate bonded composite components into mixed-material body-in-white structures, requiring adhesive process control for aluminum-composite joints.
Tier-1 suppliers capture manufacturing value-add; OEMs retain specification authority.
Manufacturing Stage:
Cycle time economics separate aerospace-derived processes from automotive-scale methods.
- Prepreg:Epoxy-impregnated carbon fiber fabrics cure in autoclaves at 180°C for 90-180 minutes. Low-volume performance variants at Porsche and McLaren retain prepreg for surface finish quality.
- Infusion:Resin transfer molding saturates dry fiber preforms with catalyzed resin under vacuum. Wind turbine blade manufacturing expertise transfers to automotive structural prototyping.
- Compression Molding:Organosheets and SMC charge into heated dies for sub-two-minute cycle times. BMW Leipzig and Mercedes-Benz Bremen plants qualify this method for A-pillar and roof bow production.
- Thermoforming:Heated thermoplastic composite blanks stretch-form over single-sided tools for interior trim and non-structural panels. Seating suppliers favor this method for backrest and pan components.
Compression molding commands capacity investment; thermoforming expands most quickly in interior applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs specify carbon fiber for structural crashworthiness while Chinese manufacturers prioritize glass fiber for battery enclosures, revealing a geographic split in material-performance trade-offs. United States pickup programs drive long-fiber thermoplastic consumption for interior mass reduction. Japanese suppliers anchor precursor supply chains for regional OEM relationships.
Germany
BMW and Mercedes-Benz platforms qualify thermoplastic organosheets for A-pillar and roof bow reinforcement. KBA crashworthiness standards favor specific energy absorption metrics that carbon fiber unidirectional tapes deliver. Stuttgart and Munich host the densest concentrations of automotive composite R&D facilities in Europe.
China
MIIT new energy vehicle production quotas accelerate glass fiber SMC consumption for battery enclosure applications. Dual carbon goals pressure OEMs to document lifecycle emissions from raw fiber through vehicle end-of-life. Shanghai and Shenzhen anchor domestic EV platform development with integrated composite manufacturing infrastructure.
United States
EPA tailpipe rules and NHTSA fuel economy mandates force fleet-wide efficiency gains that stamped steel cannot achieve. Long-fiber polypropylene specifications migrate from Tier-1 distributors directly to OEM platform engineering groups. Detroit and Tennessee Valley assembly plants integrate bonded composite components into mixed-material body structures.
Japan
Toray Industries leverages captive precursor supply chains to secure relationships with domestic OEMs. METI industrial policy supports carbon fiber capacity expansion for automotive qualification programs. Nagoya and Osaka metropolitan areas concentrate autoclave infrastructure transitioning from aerospace toward passenger car series production.
India
PLI scheme incentives for automotive manufacturing attract localized preform investment for domestic EV platform development. BIS standards for composite material characterization remain under development, creating qualification timeline uncertainty. Tamil Nadu and Gujarat host emerging clusters of compression molding capacity for closure panel production.
Composite Material for Passenger Car Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with precursor-to-fabrication control separating the upper cohort from component-focused competitors. The upper tier commands specification authority at OEM platform engineering groups, while specialists compete on cycle-time reduction for Tier-1 series production. Three archetypes dominate: integrated fiber producers, automotive-dedicated compounders, and aerospace-transitioning processors. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure qualified technician pools and autoclave throughput.
Among integrated fiber producers, Toray Industries and Mitsubishi Chemical Group Corporation occupy positions defined by captive precursor supply chains. Hexcel Corporation exemplifies the aerospace-transitioning archetype, with R&D intensity in thermoplastic unidirectional tapes representing a strategic pivot toward automotive qualification timelines. SGL Carbon anchors the automotive-dedicated tier through specialization in braided preforms that serve German vehicle assemblers.
| Leading Market Players |
|---|
| Toray Industries |
| Teijin Limited |
| SGL Carbon |
| Hexcel Corporation |
| Mitsubishi Chemical Group Corporation |
| Solvay |
| Owens Corning |
| IDI Composites International |
| Gurit |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH substance restrictions gate both supplier qualification timelines and price differentiation between certified and uncertified fiber grades simultaneously. OEM platform engineering groups now demand full material pedigree documentation, forcing Tier-1 suppliers to absorb certification costs or forfeit specification authority.
Pricing Analysis
Long-term offtake contracts dominate carbon fiber precursor procurement, locking in volume commitments across multi-year automotive platform cycles. Price differentiation rests on fiber grade certification and autoclave processing availability, with aerospace-qualified suppliers commanding premiums over emerging automotive-dedicated processors. Cost compression in glass fiber thermoplastics is intensifying because Chinese compounders are expanding mill-direct relationships with seating suppliers. Aftermarket distributors exhibit highest price sensitivity, while German OEM structural programs remain least sensitive due to crashworthiness compliance requirements.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for PAN precursor shipments from Japan and South Korea to German autoclave facilities. Supply concentrates in Japan, Germany, and China, with Toray Industries and Mitsubishi Chemical anchoring precursor production. Raw material dependencies include acrylonitrile, epoxy resins, and polypropylene feedstock. Single-source vulnerability characterizes aerospace-qualified autoclave capacity in Stuttgart and Nagoya. Distribution runs through Tier-1 compounders establishing direct OEM platform relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite material for passenger cars operates as a substitution defense against aluminum-intensive body-in-white architectures and ultra-high-strength steel advances. Incumbents must demonstrate lifecycle emissions superiority to defend specification share.
For Market Incumbents: Secure captive precursor supply through backward integration into acrylonitrile production or joint ventures with petrochemical processors. Anchor qualification capacity in Germany and China to satisfy simultaneous KBA and MIIT homologation timelines. Defend against emerging thermoplastic tape specialists by accelerating compression molding cycle time reduction below two-minute thresholds.
For New Entrants and Emerging Players: Anchor in India's PLI scheme incentives for localized preform manufacturing serving domestic EV platform development. Target glass fiber SMC supply for Chinese battery enclosure specifications, where MIIT quotas drive volume without aerospace-grade certification barriers. Establish mill-direct relationships with seating Tier-1s to bypass entrenched distribution hierarchies in United States pickup programs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with aerospace-transitioning processors holding stranded autoclave capacity and qualified technician pools. Five-to-ten year viability hinges on successful automotive qualification timelines and thermoplastic process migration. Monitor EU AI Act digital product passport implementation as inflection indicator for traceability-enabled supplier premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries leverages captive acrylonitrile production to secure Japanese OEM relationships against price volatility. |
| Thermoplastic Organosheet Qualification | BMW and Mercedes-Benz platforms adopt compression-molded unidirectional tapes for sub-two-minute A-pillar cycle times. |
| Digital Product Passport Implementation | EU AI Act traceability mandates favor suppliers with blockchain-enabled fiber-to-vehicle documentation systems. |
| Localized Preform Manufacturing | India's PLI scheme attracts compression molding investment for domestic EV closure panel production. |
| Recycled Carbon Fiber Grade Development | German vehicle assemblers qualify reclaimed fiber to reduce Scope 3 emissions under EU Green Deal carbon border adjustments. |
Research Methodology
Desk research of customs trade data, SEC filings from composite material producers, and vehicle production databases preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, and autoclave facility operations managers. Primary fieldwork captured qualification timeline data, cycle time benchmarks, and specification authority migration patterns. Secondary validation drew from IHS Markit registration data, ECHA REACH substance notifications, and MIIT new energy vehicle production disclosures. Bottom-up volume modeling triangulated against top-down OEM platform content assumptions.
Variance decomposition across fiber chemistry, structural application, and manufacturing velocity segments shaped the analytical framework over the projection horizon. Modeled dimensions included vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from segment-level volume trajectories weighted by value-per-kilogram differentials between carbon fiber and glass fiber grades. Forecast inputs incorporated EPA tailpipe rule stringency scenarios and EU Green Deal carbon border adjustment implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and NHTSA fuel economy mandate tightening, continued MIIT new energy vehicle quota enforcement, and stable acrylonitrile supply from petrochemical feedstock channels; material deviation would warrant model refresh. Specific risks include aerospace labor pool competition for carbon fiber layup technicians and unresolved thermoset matrix recycling pathways under REACH circularity requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Carbon Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
FRP Grating Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
FRP Tanks Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Composite Adhesives Market