
 Global Carbon Fiber Composite Heating Elements Market | 2026-2036
Global Carbon Fiber Composite Heating Elements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Fiber Composite Heating Elements Market Intelligence
Predictive maintenance software integration is repositioning carbon fiber composite heating elements from simple components to intelligent thermal systems. SGL Carbon SE leverages its expertise in high-purity carbon fiber production to supply materials for these advanced systems. Methode Electronics specializes in integrating these heaters into complex automotive cabin heating assemblies. Toray Industries Inc. dominates with its large-scale manufacturing capabilities for composite materials.
Carbon fiber composite heating elements are advanced materials that generate heat via electrical resistance through a matrix of carbon fibers embedded in a polymer. They offer rapid thermal response, uniform heat distribution, and high power density, making them ideal for precision heating applications. Flexible heating films represent the fastest-growing product type due to their adaptability in complex geometries. Demand from de-icing systems in aerospace and automotive cabin heating applications constitutes the largest share of the market.
Product development is shaped by stringent safety and performance standards, including FAA regulations for aerospace de-icing systems in the United States. In Europe, compliance with RoHS directives on hazardous substances and CE marking for electronic components governs market access. Component manufacturers must now decide whether to compete on material performance alone or invest in integrated smart heating solutions.
Market Dynamics
The central force shaping the market is the transformation of heating elements from passive components into intelligent thermal systems. This evolution, driven by the integration of sensors and predictive maintenance software, is creating new value propositions centered on system reliability and efficiency, compelling manufacturers to build capabilities beyond pure material science.
Growth Catalysts
- Electric Vehicle Mandates:European Union CO2 emission performance standards for new passenger cars compel automakers to maximize battery range, driving adoption of lightweight carbon fiber heaters for efficient cabin climate control.
- Aerospace Electrification:The transition toward more-electric aircraft architectures necessitates replacing heavy, bleed-air-based de-icing systems with lighter, more efficient electrical solutions like carbon fiber composite heaters.
- Flexible Form Factors:The development of highly conformable heating films enables integration into complex geometries, expanding applications beyond flat panels to curved automotive interiors and intricate medical devices.
Market Restraints
- High Precursor Cost:The elevated cost of aerospace-grade polyacrylonitrile (PAN), the primary precursor for high-performance carbon fibers, creates a significant cost barrier compared to conventional heating technologies.
- Concentrated Fiber Supply:The global supply of high-purity, high-strength carbon fiber is heavily concentrated in a few producers, primarily in Japan, creating potential bottlenecks and price volatility for element manufacturers.
- Substitution by PTC Heaters:In many automotive and consumer applications, lower-cost positive temperature coefficient (PTC) heaters provide a viable alternative, limiting the market to high-performance niches.
Strategic Opportunities
- Medical Device Integration:A significant opportunity exists in developing biocompatible heating elements for wearable therapeutic devices, patient warming systems, and diagnostic equipment requiring precise thermal management.
- Smart Textile Development:Converging carbon fiber heating technology with IoT sensors and flexible electronics opens new markets in intelligent apparel, providing active heating for outdoor, military, and industrial workwear.
- Industrial Process Heating:Penetrating industrial applications, such as composite curing ovens and semiconductor manufacturing, offers a new revenue stream where uniform heat distribution provides a distinct advantage.
Industry Challenges
- Aerospace Certification Timelines:Achieving compliance with stringent FAA and EASA regulations for de-icing systems involves lengthy and capital-intensive testing and validation cycles, delaying market entry for new product designs.
- System Integration Expertise:A skills gap exists in combining materials science with the electronics and software engineering required to develop integrated smart heating systems, hindering the transition from component supplier to solutions provider.
- Lack of Standardization:The absence of industry-wide standards for connectors, communication protocols, and performance testing creates integration friction for OEMs and complicates component sourcing and interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Fiber Composite Heating Elements Market |
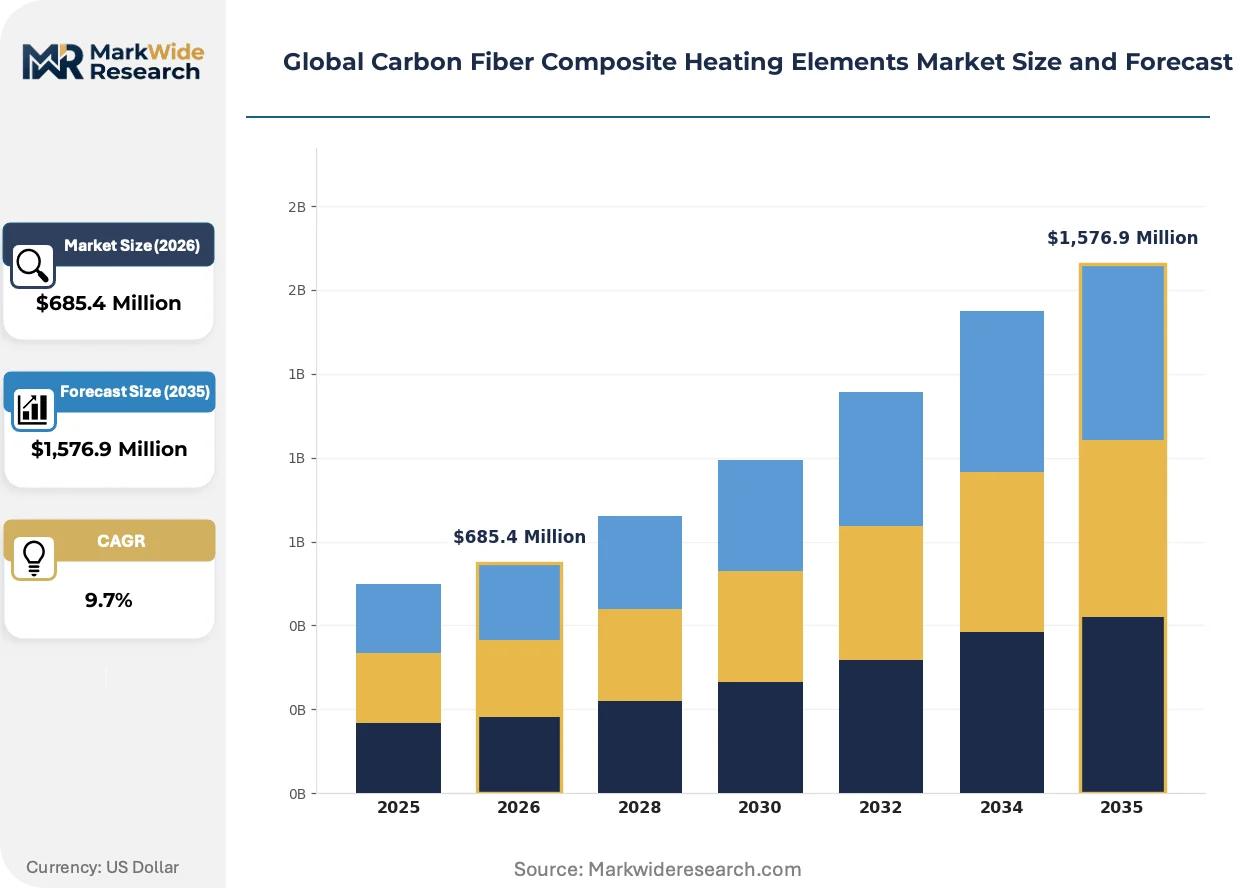
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Heating Films, Rigid Plates, Tubular Elements, Molded Components Application: De-icing Systems, Space Heating, Industrial Process Heating, Automotive Cabin Heating, Electronics Temperature Control Installation Type: Surface Mount, Embedded, Portable Units, Standalone Systems End User Industry: Aerospace Manufacturers, Marine Equipment Suppliers, HVAC Contractors, Electronics Manufacturers |
| Companies Covered | Morgan Advanced Materials, SGL Carbon SE, Methode Electronics, Flexel, CFC Carbon Co., Ltd, Solvay, Schunk Group, GKN Plc, Toray Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Fiber Composite Heating Elements Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of material science with digital intelligence. This shift creates systems that not only generate heat but also sense and adapt, fundamentally altering product capabilities and competitive dynamics.
Predictive maintenance software, integrated with embedded sensors, monitors the health of heating elements to forecast potential failures. Aerospace and premium EV producers are rapidly adopting this for critical systems like wing de-icing and battery thermal management. This integration is consolidating the basis of competition around intelligent system reliability, moving beyond raw material performance.
European Union's Restriction of Hazardous Substances (RoHS) directive governs materials used in electronic equipment sold within the market. The regulation forces manufacturers to eliminate specified hazardous materials, impacting some traditional heater designs. Inherently compliant carbon fiber composite elements thus gain a competitive advantage in segments like automotive electronics and consumer goods destined for Europe.
A clear demand-side shift shows OEMs moving from purchasing discrete heating elements to sourcing fully integrated thermal modules. This change pressures material-centric suppliers while benefiting vendors who can deliver plug-and-play assemblies with wiring and controllers. The shift is most visible within the electric vehicle sector in Germany and China, where simplified assembly is a priority.
Global Carbon Fiber Composite Heating Elements Market Segmentation
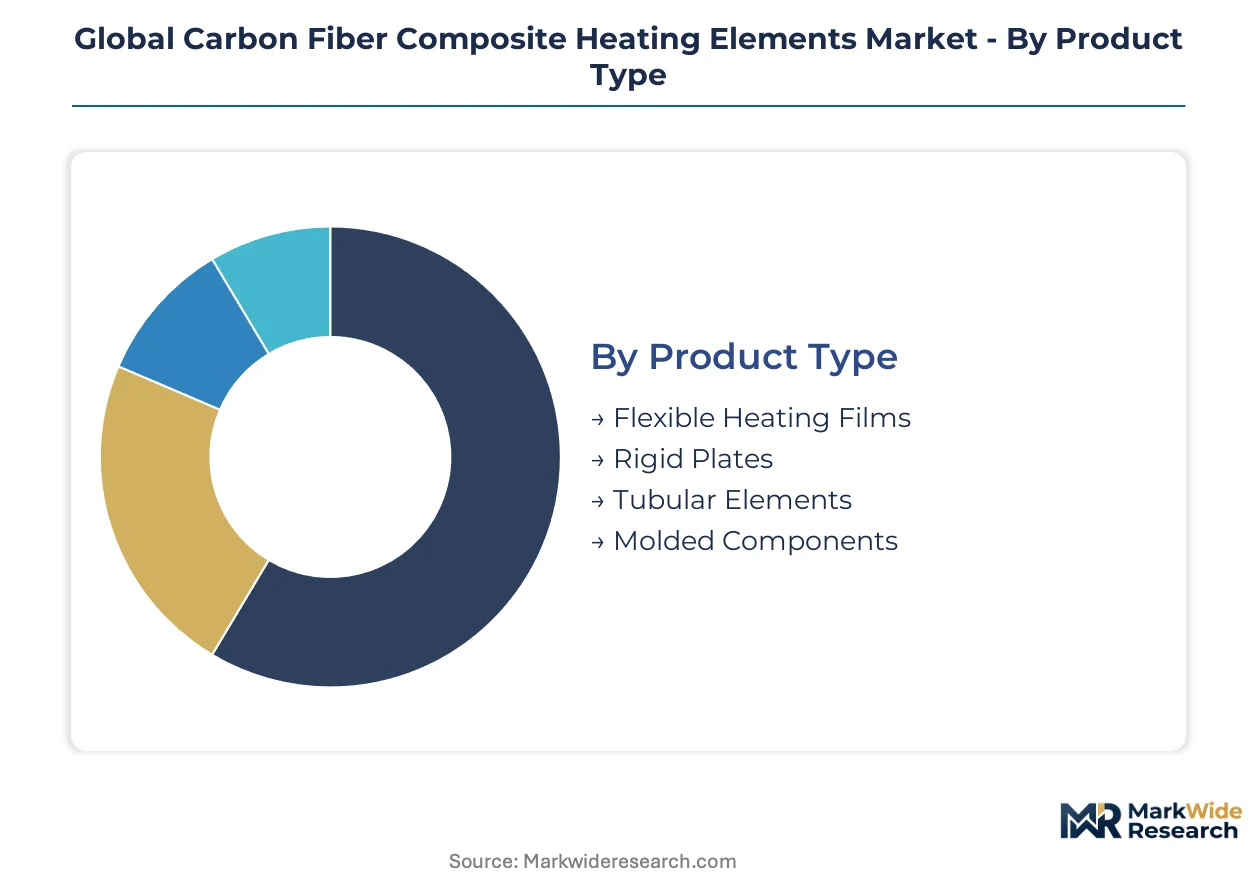
The carbon fiber composite heating elements market segments across diverse product forms, applications, installation methods, and end-user industries. Understanding these distinctions clarifies where material science innovation meets specific thermal management requirements. This granular view reveals distinct value propositions for integrated thermal solutions versus standalone components.
Product Type:
Product types delineate the physical manifestation and integration potential of carbon fiber heating elements, ranging from standalone components to those deeply embedded within systems.
- Flexible Heating Films:These ultra-thin, conformable elements consist of carbon fibers embedded in a flexible polymer matrix, allowing integration into complex, curved geometries. Demand is expanding most quickly in automotive cabin heating for EVs due to their lightweight properties and uniform heat distribution.
- Rigid Plates:Constructed with carbon fibers within a stiff composite structure, these elements provide robust, high-power density heating for flat surfaces. Aerospace manufacturers utilize rigid plates extensively for de-icing systems on wings and other critical surfaces, driven by stringent FAA performance standards.
- Tubular Elements:These components encase carbon fiber heating elements within a tube, protecting them from environmental factors. Industrial process heating applications employ tubular elements for precise temperature control in harsh environments.
- Molded Components:Carbon fiber heating elements are directly integrated during the molding process of a larger part, enabling seamless, custom-shaped thermal solutions. Medical device integration represents a strategic opportunity for molded components requiring biocompatibility.
Rigid Plates leads volumes today; Flexible Heating Films is gaining share fastest.
Application:
Applications for carbon fiber composite heating elements are defined by the specific thermal challenges they address, from safety-critical functions to comfort and process optimization.
- De-icing Systems:These applications prevent ice formation on critical surfaces, primarily in aerospace and wind energy, where system reliability and rapid thermal response are paramount. The transition to more-electric aircraft architectures necessitates replacing heavy bleed-air systems with these lighter electrical solutions.
- Automotive Cabin Heating:Carbon fiber elements provide efficient and rapid heating for vehicle interiors, crucial for passenger comfort and battery range optimization in electric vehicles. Demand is particularly strong in Germany and China due to stringent CO2 emission performance standards for new passenger cars.
- Space Heating:Carbon fiber elements offer energy-efficient and uniform heating for residential and commercial spaces, providing an alternative to traditional convection heaters. HVAC contractors are exploring these solutions for smart building climate control.
- Industrial Process Heating:These elements deliver precise and uniform heat for manufacturing processes, including composite curing and semiconductor production. Uniform heat distribution provides a distinct advantage in these industrial settings.
- Electronics Temperature Control:Carbon fiber heaters manage thermal conditions for sensitive electronic components, preventing overheating or ensuring optimal operating temperatures. Electronics manufacturers integrate these for high-performance computing and communication infrastructure.
The aerospace electrification trend and electric vehicle mandates are the primary forces driving demand across these applications.
Installation Type:
Installation types categorize how carbon fiber heating elements are physically integrated, reflecting their adaptability across various product designs and operational environments.
- Embedded:These elements are integrated directly within the material or structure of the host product, offering seamless heating and protection from external factors. This approach is prevalent in aerospace de-icing systems and advanced automotive components, enhancing system reliability and aesthetics.
- Surface Mount:Carbon fiber heating elements are applied to the exterior surface of a component or assembly, providing direct and efficient heat transfer. This method finds widespread use in industrial process heating and certain medical devices requiring localized thermal management.
- Portable Units:These are self-contained heating solutions that can be easily moved and deployed, often incorporating their own power source and controls. Smart textile development for intelligent apparel and military workwear utilizes portable units.
- Standalone Systems:These heating elements operate as independent units, often with their own housing and control interface, providing heat to a specific area. HVAC contractors deploy standalone systems for targeted zone heating in commercial buildings.
The growing demand for highly conformable and invisible heating solutions will continue to expand the embedded installation type.
End User Industry:
End-user industries define the primary sectors leveraging carbon fiber composite heating elements, each driven by unique performance demands and regulatory landscapes.
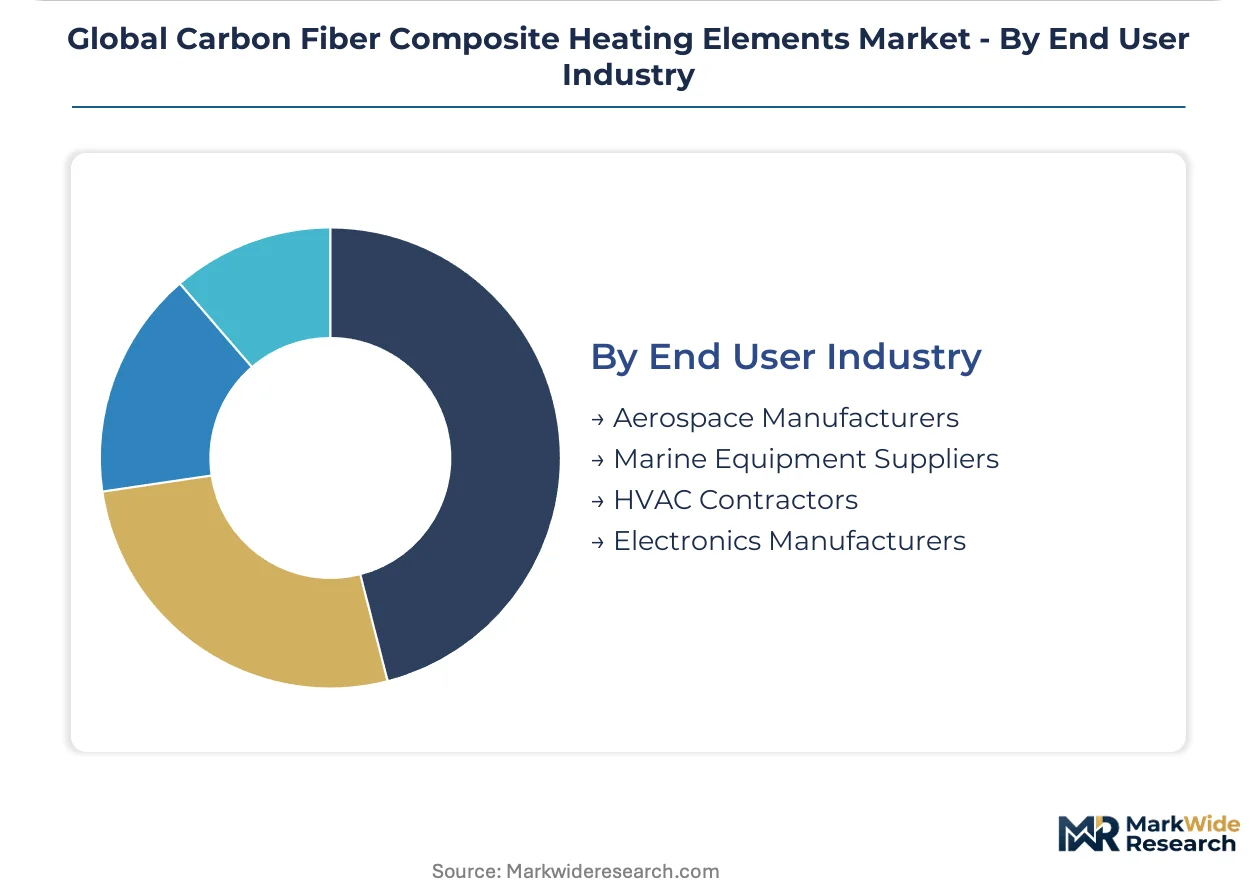
- Aerospace Manufacturers:This segment utilizes carbon fiber heaters for critical de-icing systems on aircraft wings, nacelles, and other surfaces, requiring compliance with stringent FAA and EASA regulations. The industry's focus on lightweighting and electrification strongly influences demand for these advanced components.
- Electronics Manufacturers:These companies integrate carbon fiber elements for precise temperature control in sensitive electronic devices, ensuring optimal performance and preventing thermal damage. Compliance with RoHS directives in Europe is a key driver for material selection in this sector.
- Marine Equipment Suppliers:This industry employs carbon fiber heating elements for de-icing marine vessels, preventing ice buildup on critical components and ensuring safe operation in cold environments. Durability and corrosion resistance are primary considerations for marine applications.
- HVAC Contractors:These professionals install carbon fiber heating elements in residential and commercial buildings for space heating and climate control, seeking energy efficiency and uniform heat distribution. Building efficiency standards influence product selection for HVAC contractors.
Aerospace Manufacturers currently represent the most mature segment, while Electronics Manufacturers show significant potential for future growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs and market access requirements influence manufacturing locations, leading to a differential in production strategies across regions. Manufacturers often seek to balance proximity to key end-user industries with favorable operational environments. This dynamic shapes investment flows and supply chain configurations for carbon fiber composite heating elements globally.
United States
Aerospace manufacturers drive demand for carbon fiber composite heating elements, particularly for advanced de-icing systems. Federal Aviation Administration (FAA) regulations mandate rigorous safety and performance standards for aircraft components. Seattle's aerospace cluster, alongside Wichita, actively integrates these lightweight electrical solutions into new aircraft designs and upgrades.
Germany
Automotive cabin heating solutions see strong demand in Germany, propelled by European Union CO2 emission performance standards for electric vehicles. Compliance with CE marking for electronic components and RoHS directives on hazardous substances is critical for market entry. The automotive manufacturing hubs in Bavaria and Baden-Württemberg are key centers for integrating these efficient heating systems.
China
Electric vehicle mandates and the push for efficient cabin climate control accelerate the adoption of carbon fiber heaters in China's automotive sector. The country's industrial centers demonstrate a robust demand for advanced thermal management solutions. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta regions are rapidly developing and deploying these technologies.
Japan
Japan's market is significantly influenced by its concentrated supply of high-purity carbon fiber, with companies like Toray Industries Inc. dominating production. Electronics manufacturers in Japan integrate carbon fiber elements for precise temperature control in sensitive devices. The industrial heartlands around Tokyo and Osaka continue to innovate in advanced material applications.
Global Carbon Fiber Composite Heating Elements Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied strategic priorities within the carbon fiber composite heating elements market. The landscape features both material science innovators and integrated solution providers. Companies often pursue strategic partnerships to combine material expertise with system integration capabilities. Portfolio diversification into adjacent thermal management technologies also represents a common competitive move.
SGL Carbon SE exemplifies a material-centric producer, leveraging its expertise in high-purity carbon fiber production to supply foundational materials for advanced systems. Methode Electronics, conversely, occupies a position as an integrator, specializing in complex automotive cabin heating assemblies. Toray Industries Inc., a Japanese conglomerate, anchors the market with its large-scale manufacturing capabilities for composite materials, serving a broad range of applications.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| SGL Carbon SE |
| Methode Electronics |
| Flexel |
| CFC Carbon Co., Ltd |
| Solvay |
| Schunk Group |
| GKN Plc |
| Toray Industries Inc |
| Others |
Cost & Logistics Intelligence
Japanese conglomerate-backed producers like Toray Industries Inc. influence carbon fiber composite heating element pricing by controlling high-purity carbon fiber supply. Their production discipline impacts market access and cost structures for downstream integrators.
Pricing Analysis
Capacity additions in Japan are reshaping price floors for high-purity carbon fiber, influencing composite heating element costs. The dominant pricing model remains contract-based long-term offtake for aerospace and automotive OEMs, with value-based pricing for specialized medical devices. Price differentiation stems from strict FAA certification levels and customization for complex geometries. Pricing softness stems from competition with lower-cost PTC heaters in consumer and non-premium automotive applications. Aerospace manufacturers are least price-sensitive, while consumer electronics buyers are most sensitive.
Supply Chain Analysis
Dual-sourcing requirements from aerospace OEMs drive diversification efforts within the carbon fiber composite heating elements supply chain. Geographic supply concentration remains high in Japan and Germany for core materials. The supply chain draws from aerospace-grade polyacrylonitrile and specialized polymer matrix materials. A structural risk is single-source vulnerability for high-purity carbon fiber. Distribution runs through direct channels to OEMs for embedded components and specialized industrial distributors for standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon fiber composite heating elements market presents a clear margin-expansion story, driven by the premium-tier shift towards integrated smart heating solutions. This evolution allows for higher value capture beyond raw material performance.
For Market Incumbents: Hedge against substitution by lower-cost PTC heaters by investing heavily in integrated smart heating system R&D. Consolidate market share through strategic partnerships with software providers to deliver full thermal management solutions. Pursue rigorous FAA and CE certification for new product designs to reinforce performance advantages. This strategy mitigates the threat from emerging entrants offering simpler components.
For New Entrants and Emerging Players: Enter via specialized niches like biocompatible heating elements for medical devices or smart textiles for intelligent apparel. Target underpenetrated segments requiring precise thermal management and flexible form factors. Focus on a go-to-market strategy emphasizing rapid prototyping and customization for specific OEM requirements. This approach avoids direct competition with established aerospace and automotive suppliers.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers lacking integration capabilities. Long-term viability remains strong over the next decade, fueled by aerospace electrification and EV mandates. Identify acquisition targets that possess unique material science IP or proven system integration expertise in automotive and aerospace. The signal to watch is the accelerating OEM demand for fully integrated thermal modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Integrated Thermal Modules) | OEMs prioritize plug-and-play assemblies for simplified manufacturing processes. |
| Strategic Partnership (Software Integration) | Combines material expertise with digital intelligence for intelligent thermal systems. |
| Capacity Expansion (High-Purity Carbon Fiber) | Addresses supply bottlenecks and price volatility for critical precursor materials. |
| Certification Investment (FAA and CE Marking) | Ensures market access and compliance for safety-critical aerospace and European applications. |
| Geographic Expansion (Emerging EV Markets) | Captures demand from rapidly growing electric vehicle production in China. |
Research Approach
Bottom-up aerospace de-icing system modeling reconciled against top-down carbon fiber supply-side tracking forms the analytical core for this study. Primary interviews with aerospace engineers, automotive thermal management leads, and carbon fiber producers provided qualitative insights. Secondary validation included FAA regulations, EU RoHS directives, company SEC filings, and specialized industry reports on electric vehicle production. This approach ensured robust data triangulation.
An input-output matrix framed the forecast, integrating market drivers and restraints across the analysis window. Segmentation dimensions modeled included product type, application, installation type, and end-user industry. Compound annual growth rates were derived from projected shifts in technology adoption and regulatory impacts. Key forecast inputs included global electric vehicle production forecasts and aerospace build rates.
Inputs from major carbon fiber producers and aerospace OEMs were available through the study window; gaps in proprietary OEM demand forecasts introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Deviation in aerospace certification timelines or precursor cost volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Graphene Composites Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
FRP Grating Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Composite Cans Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Composite Rollers Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Structural Core Materials Market
Composite Materials
Reinforced Carbon-Carbon Composite Market