
 Global Sports Composites Market | 2026-2036
Global Sports Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Composites Market Foresight
Buyer concentration among professional cycling teams and elite rowing programs is rebalancing as amateur endurance sports fragment demand across triathlon clubs and regional ski collectives. TORAY INDUSTRIES, INC leverages its carbon fiber precursor dominance to supply high-modulus tow for bicycle frames. Hexcel Corporation anchors North American demand through aerospace-grade material transfer into hockey stick and lacrosse shaft production. SGL Carbon specializes in automotive-derived carbon solutions that it extends into competitive archery bow limb manufacturing.
Sports composites are fiber-reinforced polymer systems combining carbon, glass, or aramid fibers with thermoset or thermoplastic matrices, engineered to achieve strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter for dynamic load-bearing equipment. Carbon fiber commands the premium product tier due to its unmatched stiffness and fatigue resistance in competitive cycling and motorsport protective applications. Glass fiber occupies volume-driven segments such as recreational ski poles and mass-market protective padding where cost sensitivity outweighs performance thresholds. Resin transfer molding leads manufacturing process adoption for complex geometries in helmet shells, while compression molding dominates high-throughput footwear plate production.
REACH compliance in Europe restricts certain epoxy hardeners and solvents, redirecting formulation investment toward bio-based resin platforms. The EU F-Gas Regulation and EPA toxic substance controls in the United States tighten volatile organic compound thresholds in manufacturing facilities, elevating capital requirements for smaller processors. ISO 4210 bicycle safety standards and JIS standards in Japan govern impact resistance and fatigue life, creating certification barriers that favor established suppliers with in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and assess captive recycling capabilities before committing to capacity expansion.
Market Dynamics
Professional cycling teams now mandate ISO 4210-certified carbon fiber frames, compressing supplier qualification timelines while fragmenting procurement across amateur endurance clubs and regional ski collectives.
Growth Catalysts
- EU F-Gas Regulation:This policy pressures manufacturers toward lower-emission resin systems, accelerating bio-based epoxy formulation development.
- Badminton racket production clusters:Concentrated manufacturing in China's Guangdong province creates scale economies that diffuse into adjacent racket sports equipment.
- Resin transfer molding:This process enables complex helmet shell geometries that satisfy escalating safety performance thresholds without weight penalties.
Market Restraints
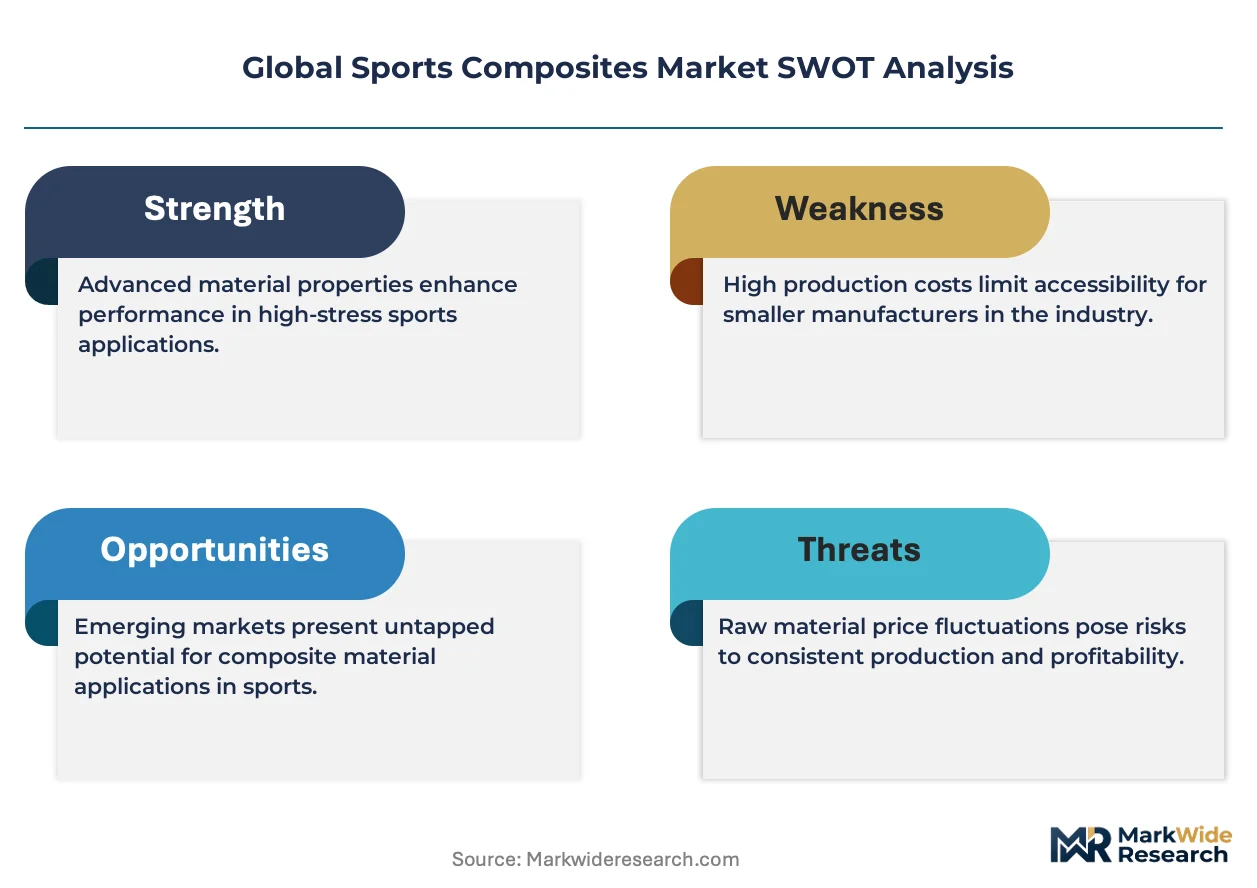
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, compressing margins for mid-tier tow suppliers.
- Guangdong supply concentration:Overreliance on Shenzhen and Dongguan manufacturing clusters exposes buyers to single-region logistics disruptions.
- Thermoset recycling limitations:Cross-linked polymer matrices resist mechanical reprocessing, constraining circular economy compliance.
Strategic Opportunities
- Indian amateur endurance segment:Triathlon club formation in Bangalore and Mumbai outpaces domestic composite supply infrastructure.
- Automotive-to-sports material transfer:Surplus aerospace-grade carbon fiber from defense contractors is absorbing into competitive archery bow limb production.
- Japan's JIS certification reciprocity:Mutual recognition agreements with ASEAN regulators reduce re-testing burdens for exporters.
Industry Challenges
- REACH compliance timelines:European epoxy hardener reformulation requires 18-24 month re-certification cycles that stall product launches.
- Autoclave operator scarcity:Specialized technicians for aerospace-grade composite curing command wage premiums that smaller processors cannot match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Composites Market |
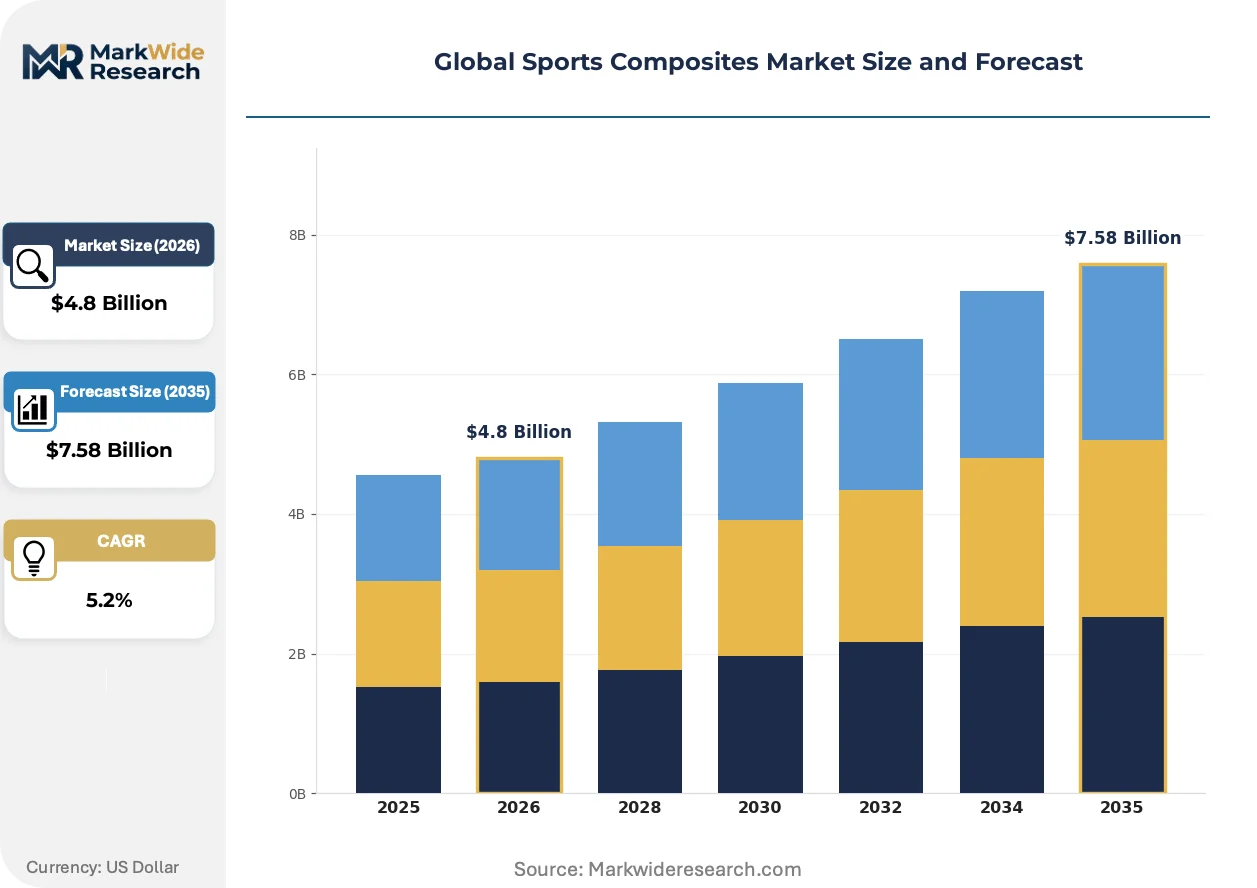
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber Reinforced, Hybrid Composites End User: Professional Athletes, Sports Equipment Manufacturers, Fitness Centers, Adventure Sports, Sports Academies Application: Protective Gear, Sporting Goods, Footwear Components, Sports Infrastructure, Training Equipment Manufacturing Process: Compression Molding, Pultrusion, Resin Transfer Molding, Hand Lay-Up, Filament Winding |
| Companies Covered | TORAY INDUSTRIES, INC, Mitsubishi Chemical Group Corp., SGL Carbon, TEIJIN LIMITED., Hexcel Corporation, Arvind Composite, Advanced Composites, Inc., Fischer Sports GmbH, Callaway Golf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Composites Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape how fiber-reinforced polymers enter sports equipment supply chains.
Recycled carbon fiber reclaimed from aerospace scrap is absorbing into protective motorsport gear manufacturing. Racing suit suppliers in Italy and Germany now specify this feedstock for impact panels. The cost compression is absorbing into mid-market motorcycle protective equipment, displacing virgin glass fiber in knee and elbow armor.
REACH restrictions on specific epoxy hardeners and solvents are redirecting European formulation investment toward bio-based resin platforms. Manufacturers must reformulate without aromatic amines while maintaining ISO 4210 fatigue life standards. German bicycle frame producers are responding by consolidating testing partnerships with in-house laboratories.
Amateur endurance clubs now source direct from composite processors rather than through traditional sporting goods distributors. Triathlon collectives in Australia and Canada negotiate frame batches through digital procurement platforms. This channel disintermediation is most visible in custom time-trial bike builds where geometry specifications vary by individual athlete biomechanics.
Global Sports Composites Market Segmentation
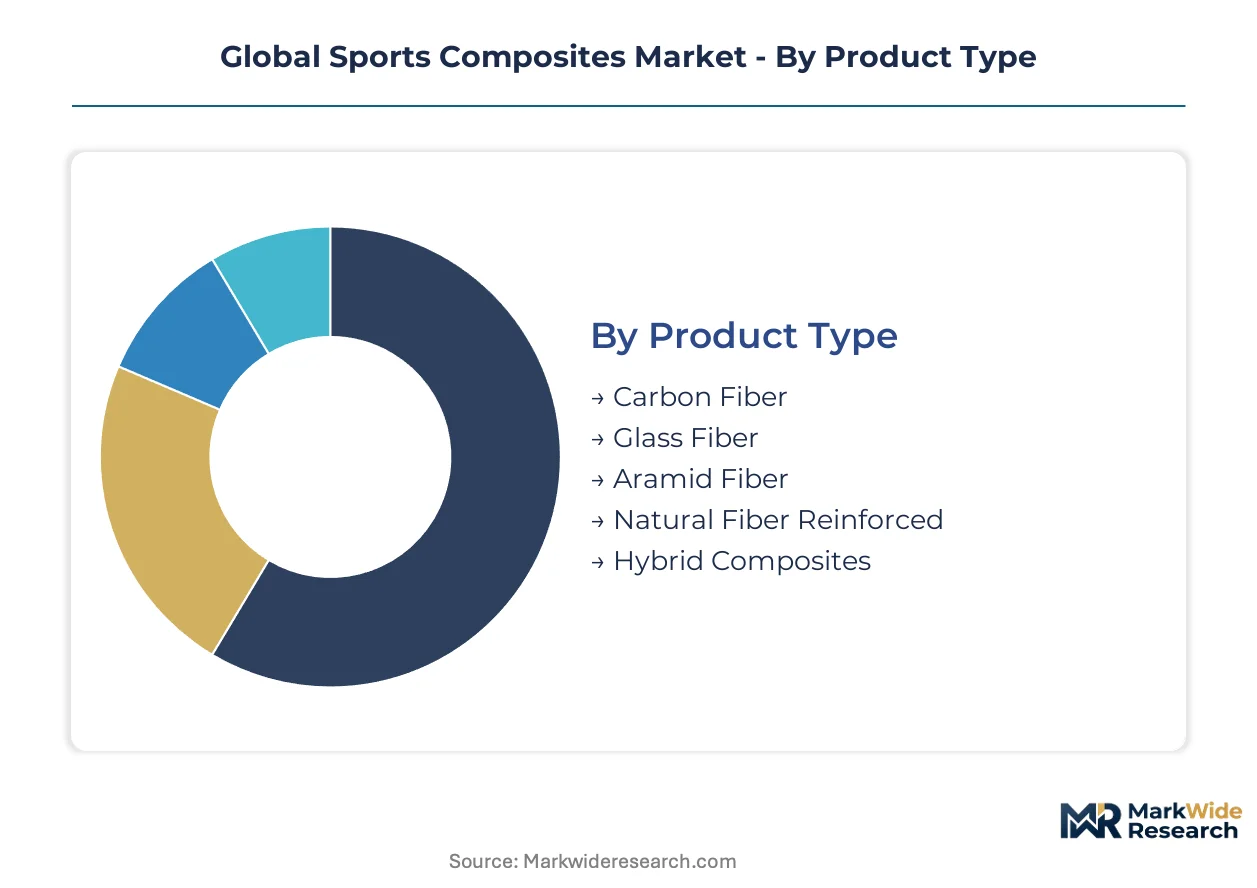
Sports composites demand fragments across fiber grades, end-user tiers, and manufacturing methods that each carry distinct certification burdens and margin profiles. Understanding these splits reveals where supply concentration creates pricing power versus where process innovation unlocks volume.
Product Type:
Carbon fiber precursor supply concentrates among Japanese and German chemical conglomerates, creating tiered access based on tow modulus ratings and long-term offtake contracts.
- Carbon Fiber:High-modulus PAN-based tows deliver stiffness-to-weight ratios exceeding 200 GPa per g/cm³ for competitive cycling frames. Demand clusters in Italian and Taiwanese frame builders serving UCI WorldTour teams under ISO 4210 fatigue protocols.
- Glass Fiber:E-glass and S-glass rovings dominate recreational ski poles and mass-market protective padding where cost thresholds override performance premiums. Guangdong racket manufacturers absorb volume through automated prepeg cutting lines serving badminton and tennis equipment.
- Aramid Fiber:Para-aramid filaments from Teijin and DuPont supply impact-resistant layers in motorsport helmets and ballistic-rated protective gear.
- Natural Fiber Reinforced:Flax and hemp fiber prepregs emerge in eco-positioned surfboard cores and ski sidewalls targeting REACH-compliant European brands.
- Hybrid Composites:Carbon-glass interlayers optimize cost-performance in amateur rowing shell construction and regional triathlon bike forks.
Today's leader: Carbon Fiber. Tomorrow's challenger: Natural Fiber Reinforced.
End User:
Procurement patterns diverge sharply between specification-driven professional tiers and price-sensitive institutional buyers with elongated decision cycles.
- Professional Athletes:Individual competitors and national federations specify custom layup schedules with 12K tow unidirectional prepregs. German track cyclists and Norwegian cross-country ski programs mandate batch traceability from precursor to finished frame.
- Sports Equipment Manufacturers:Integrated brands like those dominating Guangdong badminton production operate captive compression molding cells with 48-hour cycle times for racket frame output.
- Fitness Centers:Commercial gym chains source standardized composite rowing machine frames through distributor networks with limited customization.
- Adventure Sports:Rock climbing equipment producers and paragliding wing manufacturers specify aramid-reinforced harness structures with redundant load paths.
- Sports Academies:Institutional buyers in India's emerging triathlon clubs negotiate volume discounts on entry-level carbon fiber time-trial frames.
Professional Athletes command specification premiums; Sports Equipment Manufacturers capture scale economies.
Application:
Performance thresholds and regulatory exposure vary dramatically across protective, recreational, and infrastructure end-uses.
- Protective Gear:Motorsport helmets and motorcycle armor integrate recycled aerospace carbon fiber scrap from Italian and German suppliers. ECE 22.06 and Snell certification requirements drive resin system selection toward low-void autoclave curing.
- Sporting Goods:Hockey sticks and lacrosse shafts transfer aerospace-grade toughened epoxy formulations from North American defense contractor surplus. Filament winding dominates hollow shaft production with automated fiber placement.
- Footwear Components:Compression molding enables high-throughput carbon fiber plate production for marathon racing flats with sub-40 gram weights.
- Sports Infrastructure:Ski jump inrun tracks and velodrome surfaces deploy glass fiber reinforced panels with UV-stable gel coats.
- Training Equipment:Composite oar shafts and ergometer frames serve rowing clubs with standardized modulus specifications.
Protective Gear absorbs premium fiber grades; Footwear Components scale fastest through automation.
Manufacturing Process:
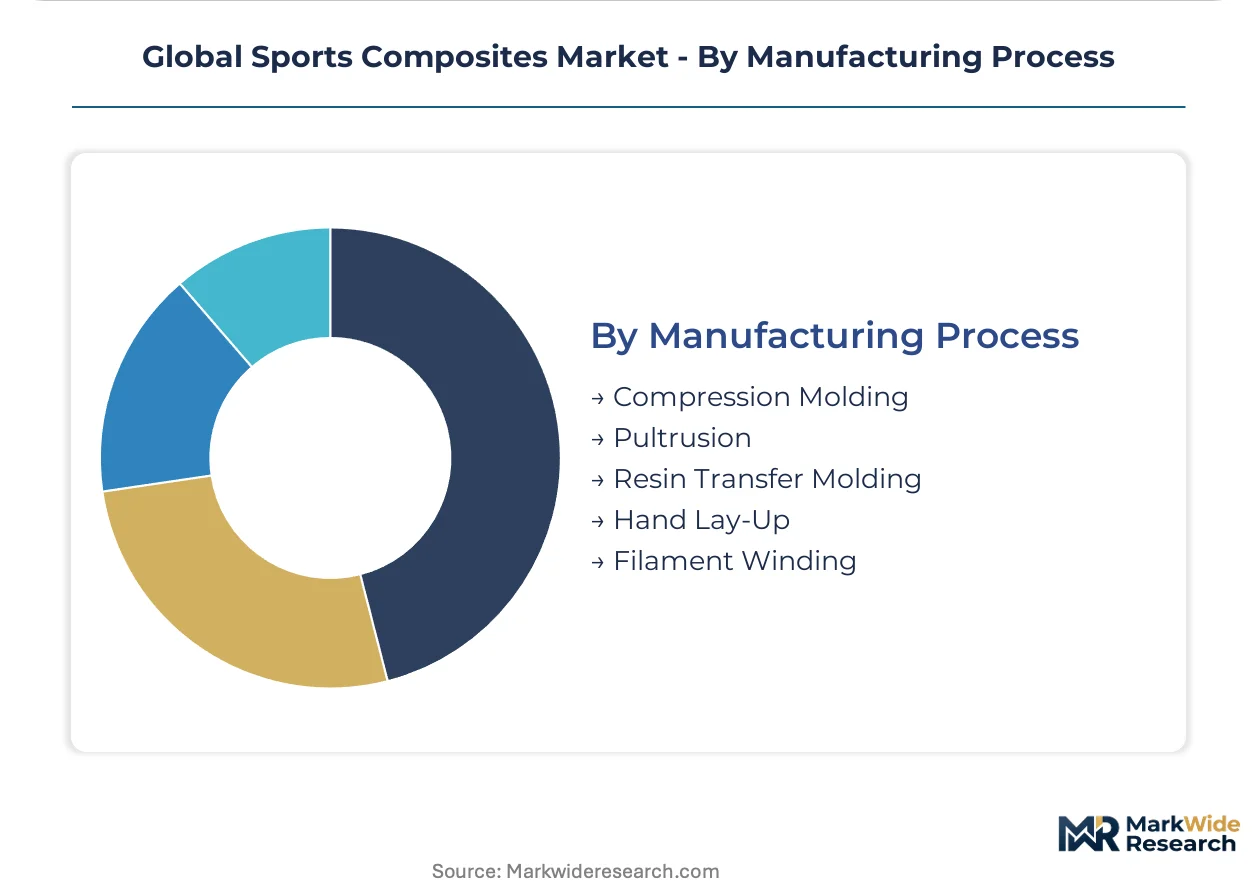
Capital intensity and operator skill requirements create distinct competitive moats across process categories.
- Resin Transfer Molding:Closed-mold infusion enables complex helmet shell geometries with integrated ventilation channels. Italian racing suit suppliers specify RTM for impact panel consolidation without secondary bonding.
- Compression Molding:Matched metal dies deliver sub-3-minute cycle times for footwear plates and racket frames in Guangdong facilities.
- Pultrusion:Continuous profile production serves ski pole and tent pole manufacturers with consistent cross-sectional properties.
- Hand Lay-Up:Custom surfboard and sailboard builders in Australia and Hawaii retain manual prepeg placement for complex double-curvature shapes.
- Filament Winding:Automated tow placement produces hollow lacrosse and hockey shafts with optimized fiber angles for torsional stiffness.
Resin Transfer Molding leads safety-critical applications; Compression Molding dominates unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates badminton racket production while Germany anchors high-modulus carbon fiber demand for competitive cycling, revealing divergent regional specializations across the value chain.
China
Guangdong province hosts dense clusters of racket sports manufacturing in Shenzhen and Dongguan, absorbing E-glass and carbon fiber prepreg through automated cutting lines. The MIIT dual carbon goals pressure processors toward energy-efficient curing ovens. Shenzhen facilities export 70% of global badminton racket frames through Yantian port consolidation.
Germany
Track cycling programs and automotive-derived archery bow producers sustain demand for aerospace-grade tow. REACH compliance timelines of 18-24 months for epoxy hardener reformulation stall product launches. Bavarian frame builders consolidate testing partnerships with in-house laboratories to maintain ISO 4210 certification.
United States
Defense contractor surplus carbon fiber absorbs into hockey stick and lacrosse shaft production through North American filament winding operations. EPA toxic substance controls elevate capital requirements for smaller processors. Utah and Colorado house emerging triathlon club procurement through direct-to-collective digital platforms.
Japan
PAN-based precursor supply concentrates among chemical conglomerates serving domestic bicycle frame builders. METI oversees JIS standard reciprocity agreements with ASEAN regulators that reduce re-testing burdens. Nagoya and Osaka anchor high-modulus tow distribution networks across Pacific Rim markets.
India
Bangalore and Mumbai triathlon club formation outpaces domestic composite supply infrastructure, creating import dependence for entry-level time-trial frames. BIS certification requirements lag behind international standards, slowing local manufacturing scale-up. Maharashtra-based distributors negotiate volume discounts for institutional sports academy procurement.
Global Sports Composites Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across precursor supply, intermediate processing, and finished equipment tiers. Japanese and German chemical conglomerates dominate carbon fiber precursor through long-term offtake contracts and captive PAN production. Mid-tier fabricators cluster around regional manufacturing hubs in Guangdong and the American Midwest. Consolidation pressure concentrates among resin formulators facing REACH and EPA compliance deadlines. Strategic partnerships between precursor suppliers and bicycle frame builders accelerate qualification timelines.
Within the diversified chemical conglomerate tier, TORAY INDUSTRIES, INC and Mitsubishi Chemical Group Corp. represent integrated players with backward control over acrylonitrile supply chains. Hexcel Corporation occupies a position among North American aerospace-grade material suppliers transferring surplus inventory into sporting applications. SGL Carbon exemplifies automotive-derived specialists extending carbon solutions into competitive archery equipment. TEIJIN LIMITED anchors para-aramid supply for impact-resistant protective gear across motorsport and adventure sports segments.
| Leading Market Players |
|---|
| TORAY INDUSTRIES, INC |
| Mitsubishi Chemical Group Corp. |
| SGL Carbon |
| TEIJIN LIMITED. |
| Hexcel Corporation |
| Arvind Composite |
| Advanced Composites, Inc. |
| Fischer Sports GmbH |
| Callaway Golf |
| Others |
Supply & Pricing Matrix
Backward integration into acrylonitrile supply anchors pricing power for Japanese precursor producers while compressing margins for mid-tier tow fabricators dependent on spot market feedstock. This structural asymmetry between captive and outsourced supply positions shapes competitive dynamics across carbon fiber grades serving professional cycling and amateur endurance segments.
Pricing Analysis
Capacity additions in China's Guangdong province are reshaping price floors for E-glass and standard-modulus carbon fiber tows. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade certified tow from industrial-grade filament and recreational-grade glass fiber. Pricing pressure stems from acrylonitrile cost volatility transmitted through non-integrated processors. Amateur triathlon clubs exhibit highest price sensitivity through digital procurement platforms, while UCI WorldTour teams absorb specification premiums for batch-traceable high-modulus tow.
Supply Chain Analysis
ISO 4210 and JIS certification reciprocity agreements gate supplier qualification timelines, favoring incumbent frame builders with in-house testing laboratories. Precursor supply concentrates in Japan, Germany, and the United States; intermediate processing clusters in China's Guangdong province and Italy's Veneto region. Raw material dependencies draw from petrochemical acrylonitrile, aerospace-grade epoxy resin systems, and aramid filament from Teijin and DuPont. Single-region logistics vulnerability in Shenzhen-Dongguan corridor exposes buyers to port congestion and energy rationing under MIIT dual carbon enforcement. Distribution runs through direct-to-collective digital platforms for custom builds and traditional sporting goods distributors for standardized equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specification thresholds are hardening across amateur endurance segments as triathlon clubs and regional ski collectives adopt professional-grade ISO 4210 fatigue protocols previously restricted to UCI WorldTour procurement.
For Market Incumbents: Deepen captive recycling capabilities for thermoset aerospace scrap before extended producer responsibility frameworks tighten in the European Union. Consolidate testing partnerships with Bavarian and Taiwanese laboratories to compress ISO 4210 re-certification cycles. Defend against emerging bio-based resin platforms by locking long-term offtake contracts with PAN precursor suppliers. For New Entrants and Emerging Players: India's amateur endurance clubs in Bangalore and Mumbai represent an underserved buyer archetype with import-dependent supply infrastructure and lagging BIS certification requirements. Target entry-level carbon fiber time-trial frames through volume discount negotiations with Maharashtra-based distributors. Establish digital procurement platform partnerships to bypass traditional sporting goods distribution markups. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier composite processors because REACH and EPA compliance deadlines are forcing consolidation among resin formulators without captive laboratory infrastructure. Five-to-ten year viability hinges on automotive-to-sports material transfer pipelines absorbing defense contractor surplus. Watch for JIS-ASEAN reciprocity expansion as signal for reduced re-testing burden and accelerated ASEAN market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | TORAY INDUSTRIES and Mitsubishi Chemical Group control acrylonitrile feedstock, insulating margins from petrochemical volatility. |
| Captive Recycling Capability Buildout | Italian and German racing suit suppliers specify reclaimed aerospace carbon fiber for motorsport impact panels under ECE 22.06. |
| Direct-to-Collective Digital Platform Launch | Australian and Canadian triathlon clubs negotiate custom geometry batches, disintermediating traditional sporting goods distributors. |
| Bio-Based Epoxy Formulation Investment | German frame builders reformulate without aromatic amines to satisfy REACH restrictions while maintaining ISO 4210 fatigue standards. |
| JIS Certification Reciprocity Expansion | METI mutual recognition agreements with ASEAN regulators reduce re-testing burdens for Japanese precursor exporters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with carbon fiber precursor suppliers, bicycle frame builders, composite processors in Guangdong, and regulatory affairs specialists at METI and ECHA with secondary validation. SEC 10-K filings from Hexcel Corporation and Teijin Limited, customs trade data for acrylonitrile and PAN-based tow, ISO 4210 certification registries, and MIIT dual carbon policy disclosures provided foundational inputs. Bottom-up segment sizing and top-down macro constraint checks ensured cross-verification.
Segment-weighting across fiber type, end-user tier, manufacturing process, and application governed volume and value outputs over the projection horizon. Carbon fiber, glass fiber, aramid, natural fiber reinforced, and hybrid composites each carried distinct margin profiles and certification burdens. Professional athlete, equipment manufacturer, fitness center, adventure sports, and sports academy demand splits were modeled separately. CAGRs derived from elasticity-adjusted trend extrapolation against regulatory inflection points and material science substitution curves.
Inputs from precursor suppliers, frame builders, and regulatory specialists were available through the study window; gaps in real-time acrylonitrile spot pricing and proprietary tow modulus specifications introduce uncertainty bands around mid-tier supplier margin projections. Forecasts reflect documented assumptions regarding JIS-ASEAN reciprocity timeline and REACH epoxy hardener reformulation completion. A model refresh is warranted upon material change in EU extended producer responsibility implementation or MIIT dual carbon enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Acrylic Laminates Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Global Composite Materials Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
FRP Reactor Market
Composite Materials
Core Material for Composites Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Polypropylene and Polypropylene Composites Market