
 Non-Honeycomb Sandwich Panel Core Materials Market | 2026-2036
Non-Honeycomb Sandwich Panel Core Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Honeycomb Sandwich Panel Core Materials Market Analytics
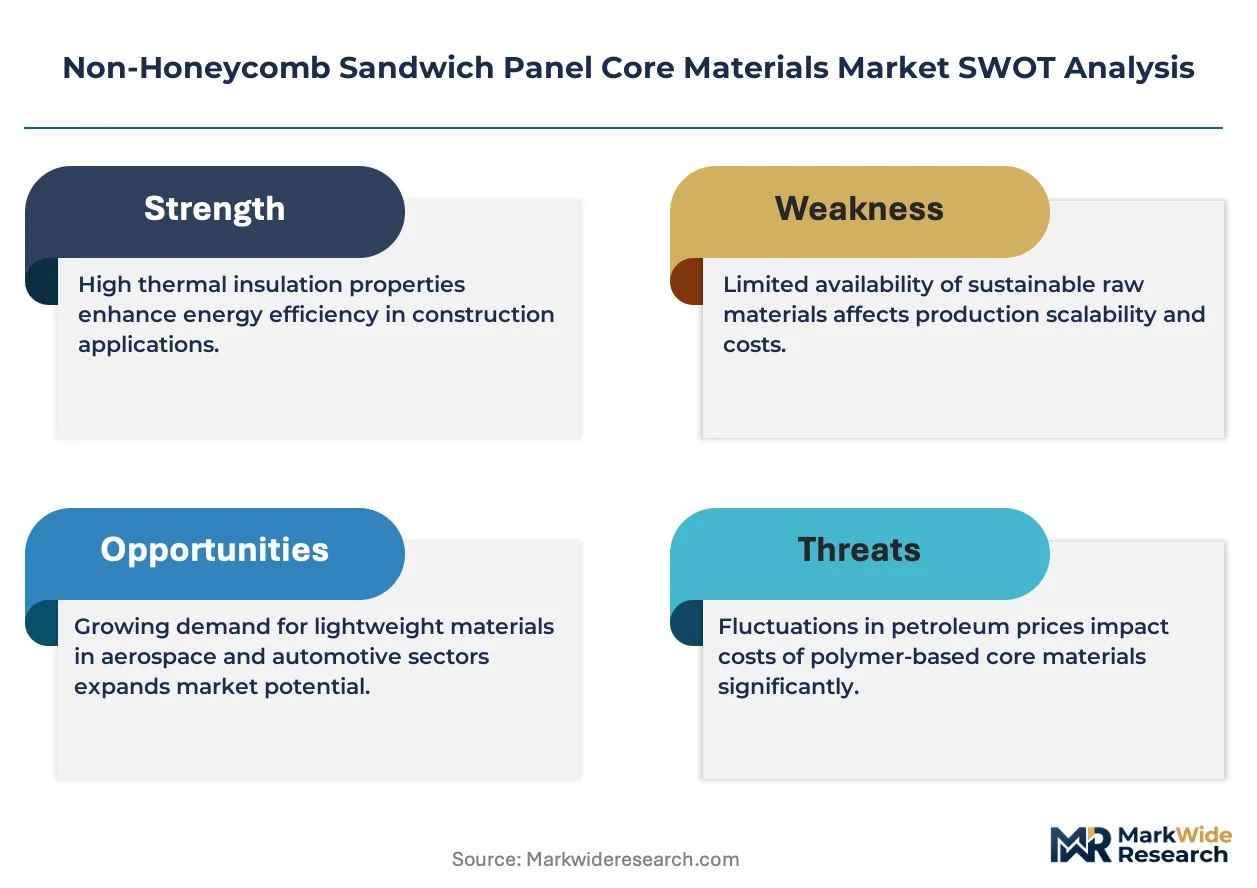
Polyurethane foam is decoupling from traditional balsa wood in wind turbine blade applications, improving moisture resistance and reducing lifecycle maintenance costs. Diab Group leverages its Scandinavian manufacturing heritage to dominate high-performance marine core supply. Gurit sustains technology leadership through advanced resin formulation capabilities. Evonik Industries AG anchors its position with specialized polymethacrylimide foam chemistry for aerospace thermal management.
Non-honeycomb sandwich panel core materials are engineered cellular or fibrous substrates bonded between face sheets to create stiff, lightweight structures with shear resistance typically exceeding 0.5 MPa in structural grades. These composites primarily serve industries requiring high strength-to-weight ratios, including aircraft interiors, boat hulls, building facades, and electric vehicle battery enclosures. Plywood cores retain cost leadership in construction applications where fire-rated assemblies dominate specification sheets. Polystyrene foam occupies the fastest-expanding niche in cold-chain logistics panels driven by refrigeration energy standards. Balsa wood maintains premium positioning in wind energy despite supply volatility from Ecuadorian plantation constraints.
The EU Green Deal and REACH chemical restrictions are tightening allowable emissions from foam core production, redirecting R&D toward bio-based polyols. FAA airworthiness standards for flammability and smoke toxicity govern aerospace material qualification timelines. Stakeholders must monitor evolving building code harmonization between EU member states and North American jurisdictions to anticipate specification divergence that could fragment supply chain configurations.
Market Dynamics
Lightweighting mandates in aerospace and marine sectors are compressing qualification timelines for advanced foam cores, forcing material suppliers to accelerate certification workflows while maintaining shear performance thresholds above 0.5 MPa.
Growth Catalysts
- FAA Flammability Standards:Airworthiness requirements for smoke toxicity and fire resistance are pulling thermoplastic foam cores into aircraft interior panels, displacing legacy phenolic systems in cabin sidewalls and overhead bins.
- Wind Energy Blade OEMs:Rotor diameters exceeding 120 meters demand core materials with improved moisture resistance, driving specification shifts toward closed-cell polyurethane systems in leading-edge and shear-web applications.
- Ecuadorian Plantation Constraints:Supply volatility in certified balsa wood is concentrating procurement attention on German and Scandinavian engineered foam manufacturers with captive raw material streams.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane foam production remains exposed to isocyanate and polyol price swings, compressing margin buffers for mid-tier core fabricators without backward integration into chemical precursors.
- REACH Chemical Restrictions:ECHA's evolving substance restrictions on halogenated flame retardants are forcing reformulation cycles that extend qualification timelines by 18-24 months for European aerospace suppliers.
- Fire-Rated Plywood Substitution:Construction applications in North American jurisdictions retain cost-efficient plywood cores for wall assemblies, limiting addressable market expansion in mid-rise commercial building facades.
Strategic Opportunities
- Electric Vehicle Battery Enclosures:Thermal runaway protection requirements are opening specification pathways for polymethacrylimide foam cores in pack structural trays, with German automotive OEMs leading validation programs.
- Cold-Chain Logistics Panels:Refrigeration energy standards in EU member states are accelerating polystyrene foam core adoption in insulated transport containers and warehouse partition systems.
- EU Green Deal Bio-Polyol Mandates:Embodied carbon accounting for construction materials is redirecting R&D investment toward castor-oil and soy-based polyurethane formulations with verified lifecycle emissions reductions.
Industry Challenges
- Multi-Jurisdictional Certification Overhead:Core material suppliers must maintain parallel qualification dossiers for FAA, EASA, and CAAC airworthiness standards, duplicating testing expenditure without harmonized mutual recognition protocols.
- Specialized Bonding Technician Scarcity:Vacuum-assisted resin transfer molding of large marine hull sections requires skilled laminators familiar with foam core scarfing and adhesive film application, with training pipelines concentrated in Nordic shipbuilding regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Honeycomb Sandwich Panel Core Materials Market |
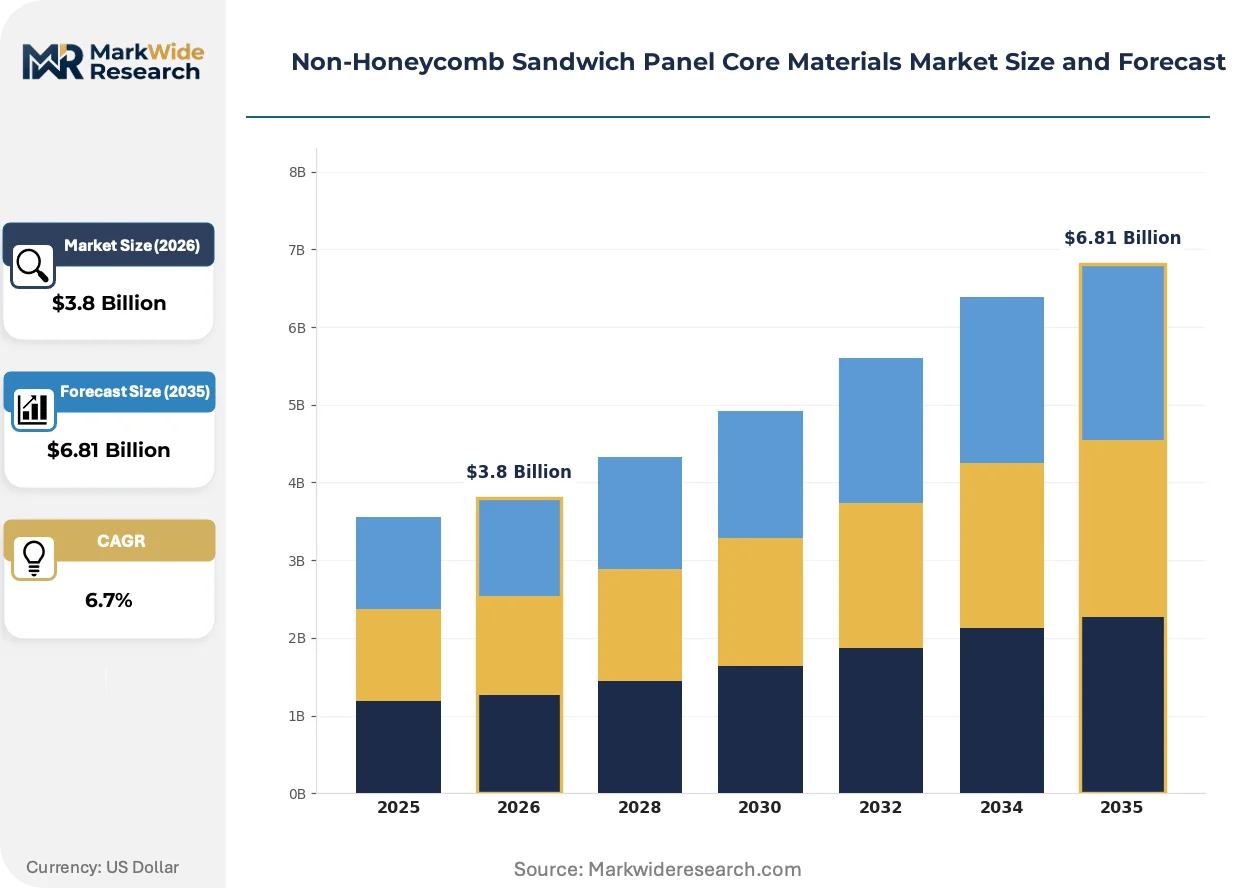
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Core Material Type: Plywood, Polyurethane Foam, Polystyrene Foam, Balsa Wood Industry Application: Aerospace, Marine, Construction, Automotive Manufacturing Technique: Vacuum Infusion, Hand Layup, Compression Molding, Resin Transfer Molding Thermal Conductivity: Low, Medium, High, Ultra-Low |
| Companies Covered | 3A Composites Mobility, Armacell, Diab Group, Gurit, Evonik Industries AG, ACP Composites, CoreLite, Fiber-Tech Industries, Plascore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Honeycomb Sandwich Panel Core Materials Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape core formulation strategies, with sustainability credentials now embedded in procurement scoring rubrics alongside mechanical performance metrics.
Polymethacrylimide foam chemistry is consolidating aerospace thermal management applications through its unique combination of low density, high service temperature, and compatibility with autoclave processing cycles. Tier-one aircraft seat manufacturers in Germany and France are specifying these cores for premium cabin monuments where heat dissipation and weight reduction must coexist. The technology is consolidating supplier relationships around specialized chemical producers with captive polymerization capabilities, compressing the viable vendor base for high-performance grades.
REACH chemical restrictions on persistent organic pollutants are forcing systematic elimination of legacy halogenated flame retardants from polyurethane foam formulations. ECHA's substance evaluation workflows are extending notification requirements to imported core materials, compelling non-EU manufacturers to establish EU-based testing partnerships. Marine and rail interior segments in Northern Europe are experiencing the most acute compliance pressure, with specification sheets now requiring third-party verification of flame-retardant chemistry.
Buyer consolidation among wind turbine OEMs is compressing core material procurement into multi-year framework agreements with volume guarantees. Vestas and Siemens Gamesa are consolidating supplier panels to three qualified foam core sources per blade platform, displacing spot-market purchasing for structural shear webs. This concentration is most visible in Denmark and Spain, where blade manufacturing clusters have co-located with certified core fabrication facilities to minimize logistics cost and quality variance.
Non-Honeycomb Sandwich Panel Core Materials Market Segmentation
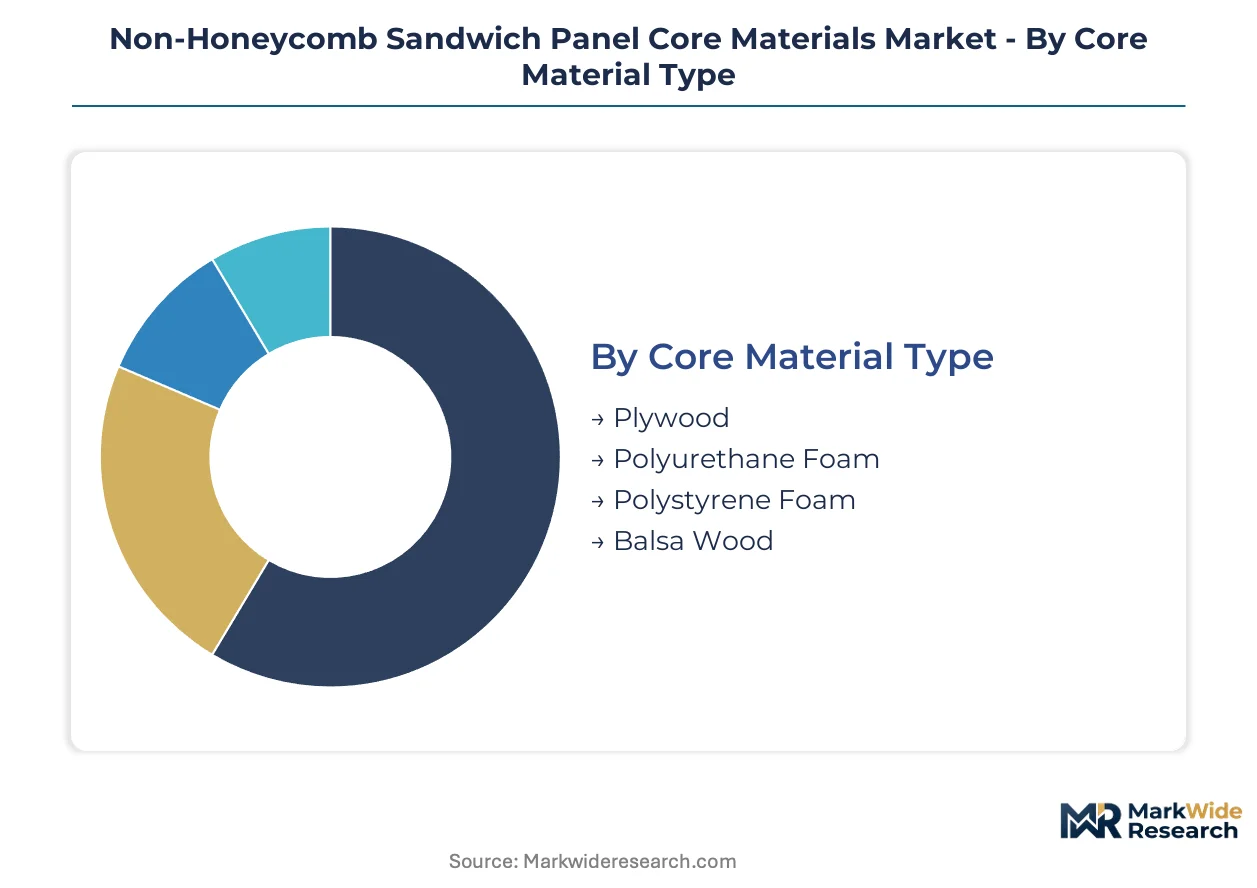
Core material selection in sandwich panel systems hinges on the integration depth between structural performance and end-use environmental exposure. Segmentation reveals which substrates function as standalone solutions versus embedded multi-material assemblies across aerospace, marine, and construction applications.
Core Material Type:
Integration depth varies sharply by substrate chemistry, with engineered foams embedding into complex laminates while plywood and balsa often serve as standalone structural layers.
- Plywood:Cross-laminated timber veneers bonded with phenolic or melamine resins deliver cost-efficient shear resistance for construction wall assemblies and marine interior fitments. Fire-rated plywood cores dominate North American mid-rise commercial facades where building codes mandate ASTM E84 Class A surface burning characteristics. Plywood leads volumes today; polyurethane foam is gaining share fastest.
- Polyurethane Foam:Closed-cell thermoset polymer systems achieve density gradients from 30 to 200 kg/m³ through controlled blowing agent chemistry, enabling tailored stiffness-to-weight ratios. Wind turbine blade OEMs in Denmark and Germany specify polyurethane for leading-edge sections where moisture ingress resistance outperforms balsa alternatives. Polymethacrylimide variants from German chemical specialists anchor aerospace thermal management applications.
- Polystyrene Foam:Expanded and extruded polystyrene beads deliver ultra-low thermal conductivity for cold-chain logistics panels and refrigerated transport containers.
- Balsa Wood:Ecuadorian plantation-sourced end-grain balsa retains premium positioning in wind energy despite supply volatility from certified forestry constraints.
Cost tier stratification separates commodity foams from certified aerospace grades commanding substantial specification premiums.
Industry Application:
Application-driven segmentation reflects divergent qualification burdens, with aerospace and marine demanding multi-jurisdictional certification while construction tolerates regional performance benchmarks.
- Aerospace:Aircraft interior panels and structural subassemblies require FAA/EASA flammability compliance under 14 CFR 25.853 and CS-25 Appendix F standards. German and French seat manufacturers specify polymethacrylimide cores for premium cabin monuments where heat dissipation and weight reduction coexist. Aerospace leads volumes today; automotive is gaining share fastest.
- Marine:Boat hulls and superstructures utilize vacuum-infused foam cores with shear resistance exceeding 0.5 MPa, with Nordic shipbuilding regions concentrating skilled laminator talent for large-section scarfing operations. Diab Group's Scandinavian manufacturing heritage dominates high-performance marine core supply.
- Construction:Building facades and wall assemblies specify plywood or polystyrene cores based on fire-rating requirements and thermal envelope performance targets.
- Automotive:Electric vehicle battery enclosures represent an emerging specification pathway for thermal runaway protection, with German OEMs leading validation programs for structural pack trays.
Customer type bifurcation splits the market between OEM direct procurement with multi-year framework agreements and distributor-mediated spot purchasing for maintenance and retrofit applications.
Manufacturing Technique:
Volume and margin profiles diverge by process automation level, with hand layup retaining relevance for custom marine builds while compression molding scales automotive and aerospace production.
- Vacuum Infusion:Resin distribution under engineered vacuum pressure achieves consistent fiber-to-resin ratios in large marine hull sections, with process control critical for void-free core-to-skin bonding. Denmark and Spain host co-located blade manufacturing clusters with certified core fabrication facilities.
- Hand Layup:Manual resin and reinforcement placement persists in custom yacht construction and prototype aerospace panels where geometric complexity exceeds automated tooling reach. Vacuum-assisted resin transfer molding of large marine hull sections requires skilled laminators familiar with foam core scarfing and adhesive film application.
- Compression Molding:Matched-die forming under heat and pressure enables high-throughput production of automotive battery enclosure components with tight dimensional tolerances.
- Resin Transfer Molding:Closed-mold injection processes deliver aerospace-grade surface finish and repeatability for autoclave-cured structural assemblies.
Maturity gradients position vacuum infusion as the established marine standard while compression molding scales fastest in automotive electrification applications.
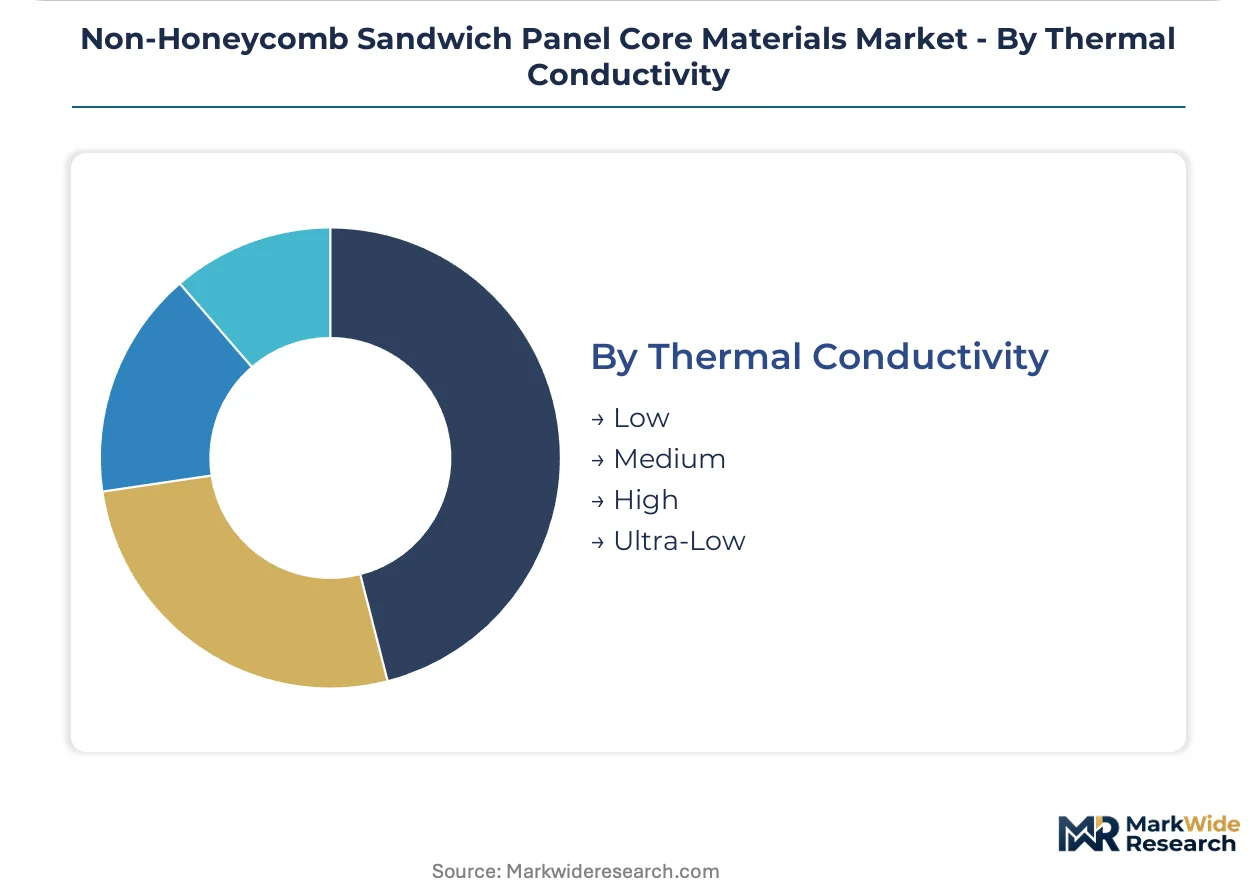
Thermal Conductivity:
Supply concentration for ultra-low conductivity grades centers on specialized chemical producers with captive polymerization capabilities, compressing the viable vendor base for aerospace-qualified materials.
- Low:Expanded polystyrene and standard polyurethane formulations serve construction insulation and general industrial panels where moderate thermal resistance satisfies energy code minima.
- Medium:Modified polyurethane systems with hydrocarbon blowing agents balance processability and R-value performance for commercial refrigeration and transport containers. EU refrigeration energy standards are accelerating polystyrene foam core adoption in insulated transport containers and warehouse partition systems.
- High:Structural cores prioritize mechanical performance over thermal properties, with balsa and plywood dominating load-bearing applications where conductivity is secondary to shear stiffness.
- Ultra-Low:Vacuum-insulated panel cores and advanced polymethacrylimide formulations achieve thermal resistance critical for cryogenic and aerospace thermal management systems. Evonik Industries AG anchors its position with specialized polymethacrylimide foam chemistry for aerospace thermal management.
Geography concentrates ultra-low conductivity production in German and Scandinavian chemical manufacturing corridors with integrated polymerization and testing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced composites manufacturing corridor concentrates aerospace and automotive demand for high-performance foam cores, with regulatory pressure from Brussels reshaping material specifications across adjacent markets.
Germany
Aircraft seat manufacturers in Hamburg and Bavaria specify polymethacrylimide cores for premium cabin monuments requiring heat dissipation. The EU Green Deal's embodied carbon accounting redirects R&D investment toward bio-based polyol formulations. The Stuttgart-Munich corridor hosts co-located testing facilities serving both automotive battery enclosure and aerospace thermal management programs.
United States
FAA flammability standards under 14 CFR 25.853 pull thermoplastic foam cores into aircraft interior panels, displacing legacy phenolic systems. Building codes in California and New York mandate ASTM E84 Class A surface burning characteristics for mid-rise commercial facades. The Pacific Northwest and Southeast regions concentrate marine hull fabrication requiring vacuum-assisted resin transfer molding expertise.
Denmark
Wind turbine blade OEMs specify polyurethane foam for leading-edge sections where moisture resistance outperforms balsa alternatives. REACH chemical restrictions on halogenated flame retardants extend qualification timelines for core material imports. The Esbjerg region hosts blade manufacturing clusters co-located with certified core fabrication facilities to minimize logistics cost.
China
Domestic wind energy expansion drives specification shifts toward closed-cell polyurethane systems in rotor blades exceeding 120 meters in diameter. The national dual carbon goals tighten allowable emissions from foam core production, redirecting investment toward captive raw material streams. The Yangtze River Delta concentrates manufacturing infrastructure for both aerospace-qualified and construction-grade sandwich panel cores.
France
Aircraft interior panel fabricators in Toulouse and Paris leverage autoclave processing capabilities for polymethacrylimide-based structural subassemblies. EASA flammability compliance under CS-25 Appendix F standards governs material qualification timelines for European aerospace suppliers. The Île-de-France region anchors supply relationships with specialized chemical producers holding captive polymerization capabilities.
Non-Honeycomb Sandwich Panel Core Materials Market Competitive Landscape
Global majors compete with regional champions across certification depth and raw material integration, producing a tiered structure where aerospace-qualified suppliers command specification premiums over construction-grade fabricators. Chemical producers with in-house polymerization capabilities occupy the premium tier, while timber and commodity foam processors serve cost-sensitive construction segments. Two dominant competitive moves define positioning: backward integration into chemical precursors to buffer margin compression, and geographic co-location with blade manufacturing clusters to capture wind energy procurement consolidation.
Within the chemical-specialist tier, Evonik Industries AG and Diab Group exemplify positioning anchored in proprietary foam chemistry and Scandinavian manufacturing heritage respectively. Gurit sustains technology leadership through advanced resin formulation capabilities. These three entities represent the viable vendor base for aerospace-qualified materials where thermal conductivity and autoclave compatibility requirements compress supplier options.
| Leading Market Players |
|---|
| 3A Composites Mobility |
| Armacell |
| Diab Group |
| Gurit |
| Evonik Industries AG |
| ACP Composites |
| CoreLite |
| Fiber-Tech Industries |
| Plascore |
| Others |
Value Network & Pricing Analysis
Wind turbine blade OEM procurement consolidation into multi-year framework agreements is compressing spot-market premiums and forcing core fabricators toward volume-scaled contract structures that sacrifice margin for capacity utilization guarantees.
Pricing Analysis
Isocyanate and polyol cost pass-through dominates polyurethane foam pricing, with petrochemical feedstock volatility compressing margins for non-integrated fabricators. Three-tier pricing structure across aerospace-qualified, industrial-grade, and construction-commodity levels separates certified polymethacrylimide cores from standard polystyrene. Cost compression in mid-tier polyurethane runs through balsa substitution pressure from German and Scandinavian engineered foam suppliers. Construction plywood cores exhibit highest price sensitivity, while aerospace thermal management grades sustain specification premiums.
Supply Chain Analysis
Regional distribution centers in Hamburg, Esbjerg, and the US Pacific Northwest anchor hub-and-spoke patterns for marine and wind energy core delivery. Manufacturing concentrates in Germany, Denmark, and China, with Ecuadorian balsa plantations feeding wind blade shear-web production. Supply chains draw from petrochemical precursors, certified timber plantations, and specialized polymerization equipment. Single-source vulnerability concentrates in aerospace-qualified polymethacrylimide chemistry held by German chemical specialists. Distribution runs through co-located blade fabrication facilities and Tier 1 laminator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as lightweighting mandates across aerospace, automotive, and wind energy create durable specification pull for engineered foam substrates.
For Market Incumbents: Lock in multi-year framework agreements with Vestas and Siemens Gamesa before procurement consolidation closes supplier panels. Secure captive polyol streams through backward integration or long-term offtake contracts to buffer isocyanate price volatility. Invest in FAA-EASA dual certification infrastructure to defend aerospace premium positioning against emerging Asian competitors. For New Entrants and Emerging Players: The price-point gap between aerospace-qualified polymethacrylimide and construction-grade polystyrene offers entry space for mid-tier polyurethane specialists. Target cold-chain logistics panels in EU member states where refrigeration energy standards accelerate insulated container demand. Pursue co-location with automotive battery enclosure manufacturers in Germany's Stuttgart-Munich corridor for thermal runaway protection validation programs. For Investors and Strategic Acquirers: Asymmetric upside sits with chemical producers holding captive polymerization capabilities and existing aerospace certification dossiers. Long-term viability hinges on bio-polyol transition readiness under EU Green Deal embodied carbon accounting. Watch ECHA substance restriction timelines as inflection indicators for reformulation-driven vendor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Buffers margin compression from petrochemical feedstock volatility for mid-tier fabricators. |
| Dual FAA-EASA Certification Investment | Unlocks premium aerospace pricing tiers for polymethacrylimide core manufacturers. |
| Co-location with Blade Manufacturing Clusters | Captures wind energy procurement consolidation in Denmark and Spain logistics corridors. |
| Bio-based Polyol Formulation Development | Aligns polyurethane chemistry with EU Green Deal embodied carbon requirements. |
| Automotive Battery Enclosure Validation | Opens specification pathways for thermal runaway protection in German OEM programs. |
Research Methodology
Coverage spans Germany, Denmark, the United States, China, and France, with primary inputs from each market cluster combining interviews with foam core plant managers, wind blade procurement leads, aerospace laminators, and chemical R&D directors. Secondary validation draws from FAA airworthiness filings, ECHA substance restriction notifications, EU customs trade data, and wind turbine OEM annual disclosures. Bottom-up volume modeling triangulates against top-down aerospace and automotive production forecasts.
Granularity-level modeling disaggregates core material type, industry application, and thermal conductivity tier across the analysis window. Segmentation dimensions include density grade, manufacturing technique, and regional regulatory cluster. CAGRs derive from regression against historical aerospace production, wind energy capacity additions, and electric vehicle platform ramp schedules. Industry-specific inputs incorporate REACH chemical restriction timelines and FAA certification backlog data.
Caveats apply where ECHA substance evaluation outcomes or FAA rulemaking revisions could materially shift qualification timelines and vendor viability. Forecasts reflect stated assumptions about petrochemical feedstock stability and wind turbine OEM procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
China Marine Composites Market
Composite Materials
Composite Market
Composite Materials
Epoxy Composite Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Thermoset Composites Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Reinforced Plastics Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Composite Coatings Market
Composite Materials
United States Marine Composites Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Transportation Composites Market