
 Synthetic Rope Market | 2026-2036
Synthetic Rope Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Rope Market Intelligence
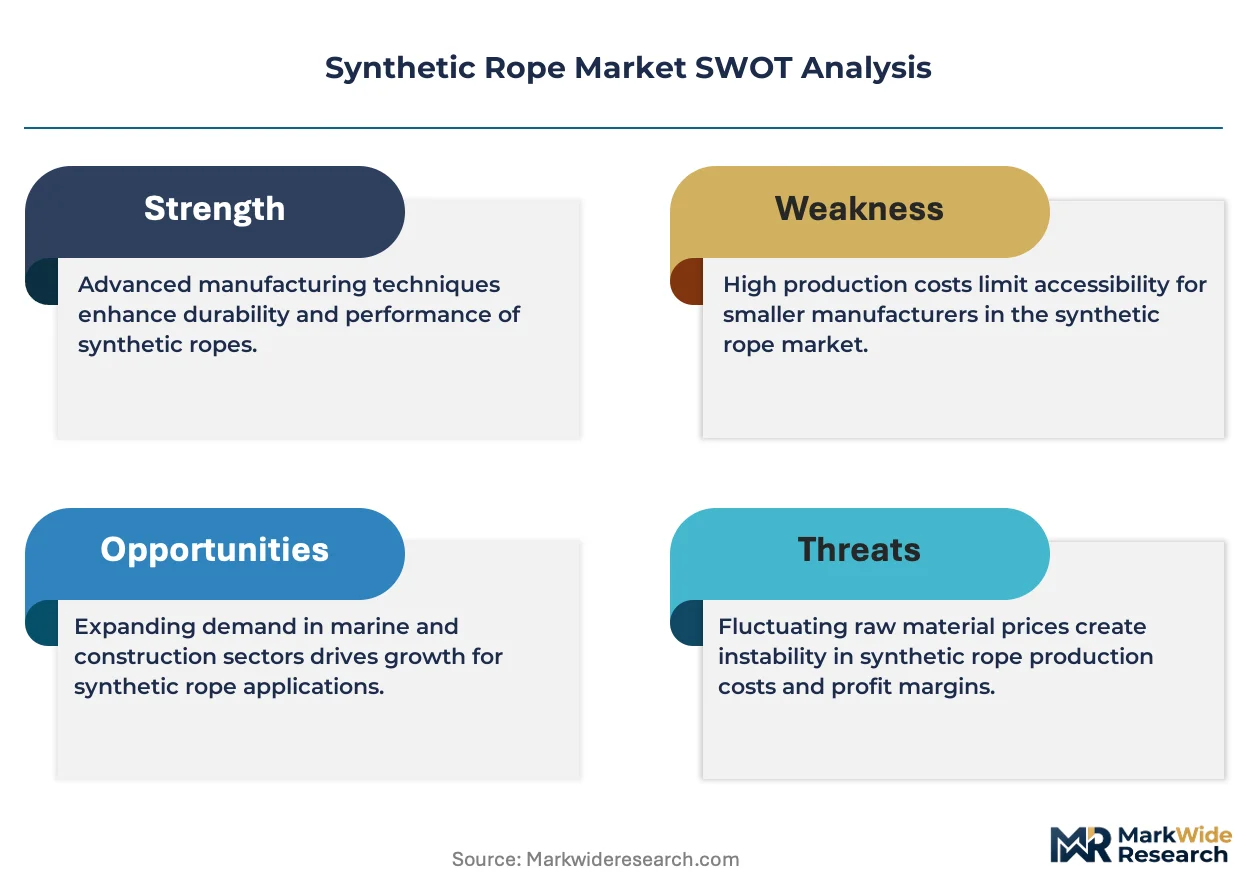
China's polyester and HMPE capacity build-out is fragmenting the traditional supply hierarchy that once favored European and North American producers. Samson Rope Technologies anchors its position through deep specialization in marine-grade HMPE solutions for offshore energy. Cortland Limited leverages integrated fiber-to-rope manufacturing to sustain margin control across demanding industrial applications. Teufelberger Holding AG competes through Austrian-engineered high-performance braiding technology that commands premium positioning in rescue and arborist segments.
Synthetic rope consists of extruded polymer fibers—polypropylene, nylon, polyester, or ultra-high molecular weight polyethylene—twisted or braided into load-bearing strands with tensile strengths exceeding steel wire at one-eighth the weight, engineered primarily for lifting, mooring, towing, and fall-protection applications. HMPE rope leads value generation due to its strength-to-weight superiority in offshore and heavy-lift settings, while polypropylene rope dominates volume through cost-driven marine and agricultural demand. The application split reveals marine as the established revenue core, with construction emerging as the fastest-expanding channel as crane operators replace wire rope to reduce handling injuries and downtime.
ISO 2307 and EN 1891 set baseline testing protocols for breaking strength and elongation that govern product qualification across EU and Asian export markets, while OSHA fall-protection standards in the United States mandate synthetic rope inspection cycles that sustain replacement demand in utility and construction sectors. China's GB standards for fiber ropes, administered by SAMR, are converging with international norms to facilitate domestic manufacturer export competitiveness. Stakeholders must monitor regulatory divergence between EU chemical restriction pathways and U.S. performance-based standards when configuring regional product portfolios and certification investments.
Market Dynamics
Offshore wind farm expansion is compressing procurement cycles for high-modulus polyethylene mooring systems, forcing rope manufacturers to recalibrate capacity planning around turbine installation schedules rather than traditional maritime replacement demand.
Growth Catalysts
- REACH chemical disclosure mandates:European coating reformulation requirements are accelerating HMPE rope qualification timelines as manufacturers pre-certify products for EU offshore energy tenders.
- China shipbuilding procurement:Domestic vessel outfitting demand is absorbing excess polyester and HMPE fiber capacity from new Chinese polymer plants.
- OSHA fall-protection inspection cycles:Mandated synthetic rope replacement intervals in US utility and construction sectors sustain predictable aftermarket volume.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester rope margins compress when propylene and PTA spot prices spike, exposing volume producers to input cost squeezes.
- HMPE fiber supply concentration:Ultra-high molecular weight polyethylene fiber production clusters among three specialized chemical manufacturers, creating single-source vulnerability for premium rope grades.
- Steel wire rope substitution defense:Crane operators in cost-sensitive emerging markets retain wire rope for static lifting where handling weight is not operationally critical.
Strategic Opportunities
- Floating offshore wind mooring:Deeper-water turbine platforms require longer, lighter mooring lines than fixed-bottom installations, expanding addressable HMPE demand per project.
- Arborist and rescue segment premiumization:Austrian-engineered braiding technology commands pricing power in professional rope access where failure tolerance approaches zero.
- Integrated fiber-to-rope manufacturing:Captive polymer extrusion and rope construction under one roof insulates margin control against fiber merchant market swings.
Industry Challenges
- ISO 2307 and EN 1891 testing backlog:Certification queue delays at accredited laboratories extend product launch timelines for new rope constructions targeting EU export markets.
- HMPE splicing technician scarcity:Proper termination of high-modulus ropes requires specialized training that outpaces vocational program output in offshore energy hiring regions.
- Legacy wire rope infrastructure incompatibility:Crane drum designs optimized for steel wire abrasion patterns accelerate HMPE rope wear when operators substitute without hardware modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Rope Market |
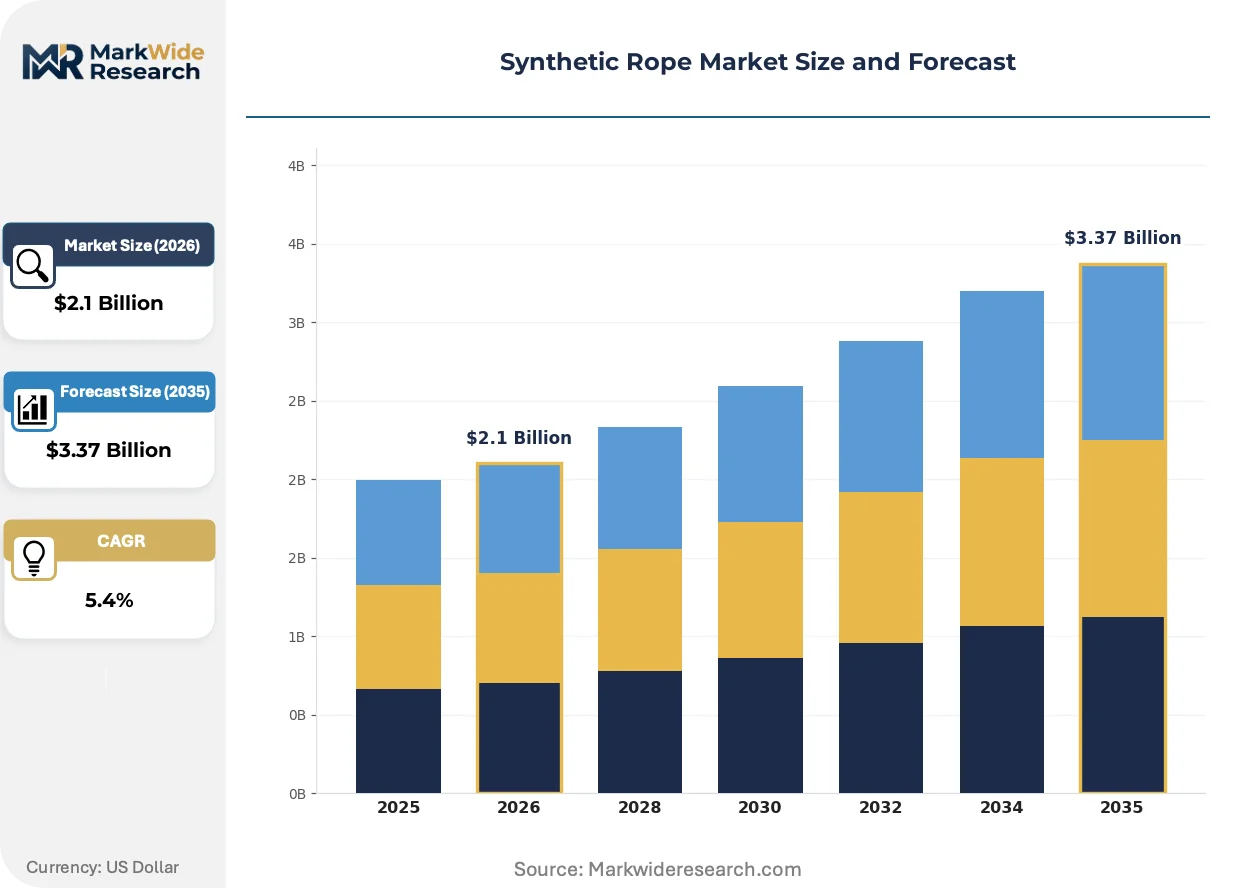
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene Rope, Nylon Rope, Polyester Rope, HMPE Rope Application: Marine, Construction, Sports, Agriculture End User: Industrial Manufacturers, Recreational Users, Shipping Companies, Utility Providers Diameter: 1/4 Inch, 1/2 Inch, 3/4 Inch, 1 Inch |
| Companies Covered | Marlow Ropes, English Braids Ltd., Cortland Limited, Southern Ropes, Teufelberger Holding AG, WireCo WorldGroup, Yale Cordage, Bridon-Bekaert, Samson Rope Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Rope Market Strategic Shifts & Innovations
Digital twin technology is virtualizing rope condition monitoring, compressing the feedback loop between field degradation data and replacement scheduling decisions across marine and heavy-lift operations.
Embedded fiber-optic strain sensing is virtualizing traditional visual and tactile inspection protocols for critical mooring and lifting applications. Offshore wind operators in the North Sea are piloting continuous load monitoring systems that transmit real-time tension data to shore-based maintenance teams. This virtualization of inspection labor is enabling predictive replacement models that optimize rope life extraction while eliminating emergency downtime.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing coating reformulation across European-sourced synthetic ropes. Manufacturers serving EU offshore energy projects must qualify alternative fiber finishes that maintain abrasion resistance without fluorinated chemistry. The regulatory pressure is concentrating procurement among rope suppliers with in-house polymer chemistry capabilities rather than contract finishers.
Buyer consolidation among offshore wind developers is compressing supplier qualification timelines and favoring rope manufacturers with documented installation track records. Procurement teams at major European energy utilities now mandate reference projects as a gating criterion for mooring system tenders, displacing smaller rope producers without offshore wind project history. This credential concentration is most visible in Danish and German North Sea lease rounds where developer procurement standards have effectively narrowed the qualified supplier base.
Synthetic Rope Market Segmentation
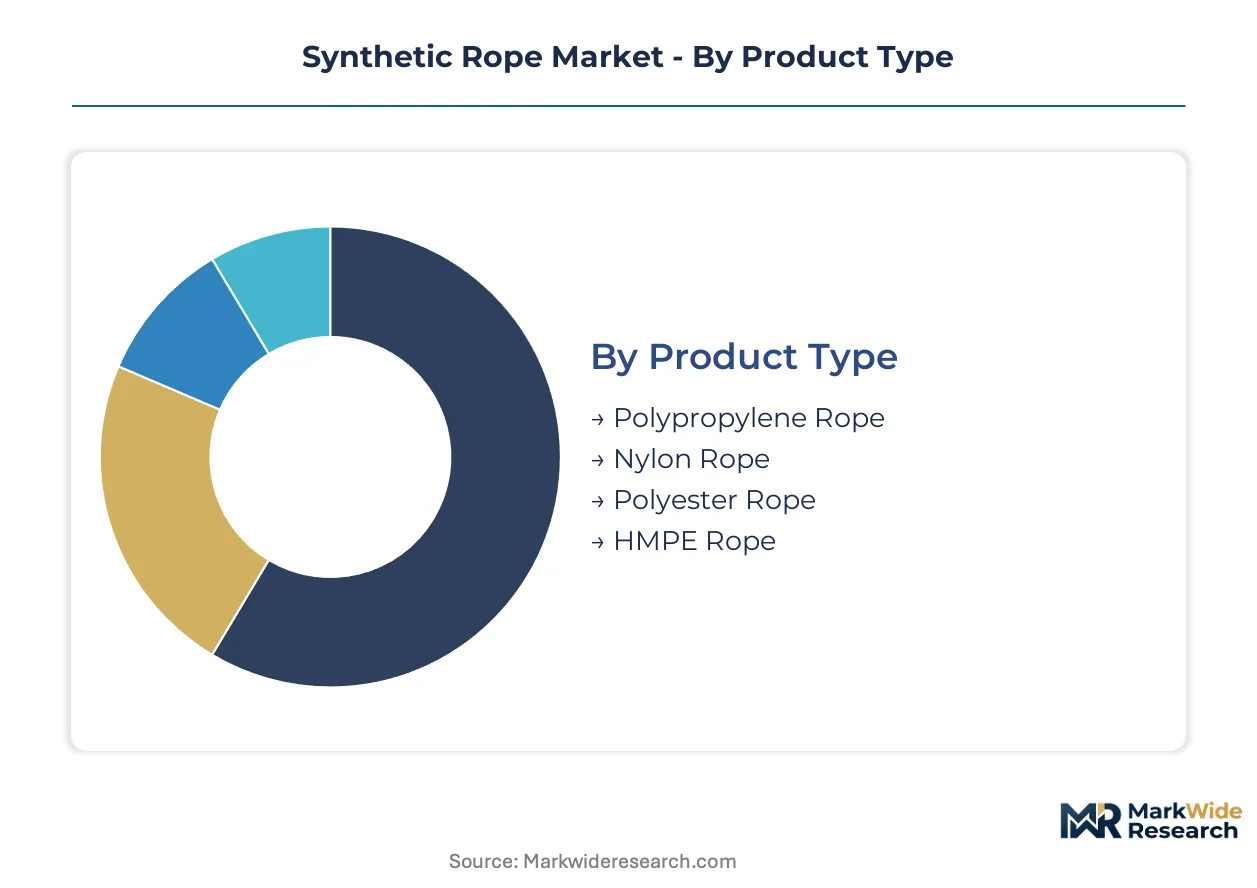
Synthetic rope segmentation reveals how material science, application engineering, and procurement scale intersect to create distinct competitive arenas. Understanding these divisions exposes where margin concentrates versus where volume flows.
Product Type:
Mature commodity grades dominate tonnage while emerging high-performance polymers capture value expansion in critical-load environments.
- Polypropylene Rope:Extruded monofilament and multifilament construction delivers buoyant, moisture-resistant performance at the lowest fiber cost point. Agricultural bundling and fishing net applications in China absorb the majority of global polypropylene rope output from domestic extrusion plants.
- Nylon Rope:Polyamide 6 and 6,6 fibers provide exceptional energy absorption and abrasion resistance through dynamic loading cycles. US utility providers specify nylon for lineman safety lanyards under OSHA 1926.95 fall-arrest mandates, sustaining replacement demand through mandated inspection intervals.
- Polyester Rope:PET fiber construction offers dimensional stability and UV resistance superior to polypropylene in marine environments. Coastal fishing fleets in Vietnam and Indonesia favor polyester for longline and trawl applications where sunlight degradation accelerates.
- HMPE Rope:Ultra-high molecular weight polyethylene achieves strength-to-weight ratios exceeding steel wire rope by factors of seven to ten. Floating offshore wind mooring projects in the North Sea specify HMPE for water-depth installations exceeding sixty meters where steel catenary weight becomes prohibitive.
Polypropylene rope retains volume leadership; HMPE rope holds the steepest expansion curve.
Application:
Cost sensitivity varies dramatically across end-uses, with safety-critical applications tolerating premium pricing while commodity marine usage drives hard negotiation on per-meter rates.
- Marine:Mooring, towing, and fishing operations constitute the historical revenue foundation. Danish offshore wind developers specify HMPE mooring lines for turbine platforms, displacing traditional chain-and-wire configurations.
- Construction:Crane lifting and personnel fall-protection represent the fastest-growing application channel. German construction firms accelerate synthetic rope substitution for wire rope on mobile cranes to reduce handling injuries and drum changeover downtime.
- Sports:Climbing, sailing, and equestrian applications demand certified low-elongation performance. Austrian braiding technology commands premium positioning in UIAA-certified climbing ropes where failure tolerance approaches zero.
- Agriculture:Baling twine, greenhouse trellising, and livestock fencing consume high volumes at minimal specification. Brazilian soybean producers drive polypropylene baler twine demand during harvest compression windows.
Marine anchors established revenue; construction delivers the most rapid share gain.
End User:
Procurement sophistication diverges sharply between specification-driven industrial buyers and price-sensitive recreational purchasers.
- Industrial Manufacturers:OEM integration of synthetic rope into lifting equipment, conveyor systems, and safety hardware requires batch certification and traceability. German crane manufacturers source HMPE rope assemblies with embedded RFID tags for warranty compliance tracking.
- Shipping Companies:Fleet-wide rope standardization programs negotiate multi-year supply agreements with volume-tier pricing. Greek tanker operators consolidate mooring line procurement across vessel classes to leverage scale against European rope distributors.
- Utility Providers:Electric transmission and telecommunications infrastructure maintenance mandates synthetic rope replacement cycles under OSHA and utility-specific safety protocols. US rural electric cooperatives sustain predictable aftermarket demand through scheduled bucket truck line refurbishment.
- Recreational Users:Individual consumers purchase through retail and e-commerce channels with minimal technical specification. Australian recreational boaters drive seasonal demand spikes for polyester dock lines through marine chandleries.
Industrial manufacturers concentrate value capture; recreational users expand the addressable base most broadly.
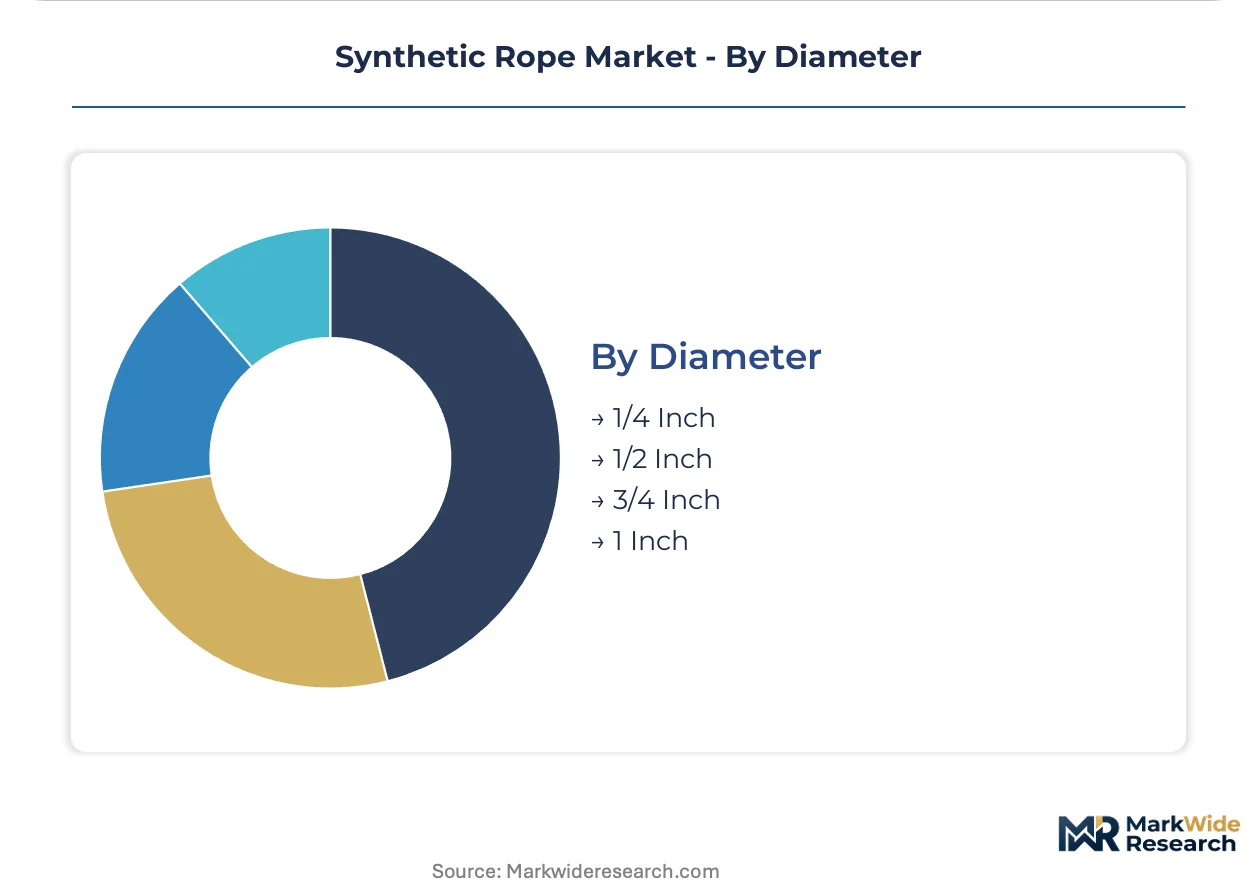
Diameter:
Scale economics favor high-volume mid-range diameters while specialized small and large formats command manufacturing premiums.
- 1/4 Inch:Precision braiding for arborist climbing lines, rescue cordage, and small-craft rigging. French tree care professionals specify 6mm HMPE for mechanical advantage systems in technical aerial rescue.
- 1/2 Inch:General-purpose industrial and marine workhorse diameter balancing handling ergonomics with load capacity. US commercial fishing fleets deploy 12mm polyester for trawl warps and net tending.
- 3/4 Inch:Heavy-lift crane applications and medium-vessel mooring where single-line strength requirements exceed ten metric tons. Korean shipyards specify 19mm HMPE for offshore support vessel towing bridles.
- 1 Inch:Maximum-diameter constructions for deep-water mooring and ultra-heavy lift where splicing complexity limits supplier qualification. Scottish floating wind projects require 25mm HMPE with specialized tapered termination for platform station-keeping.
Half-inch diameter retains shipment leadership; one-inch formats scale fastest in offshore energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes synthetic rope primarily for vessel outfitting and agricultural bundling, while European procurement concentrates on high-modulus polyethylene systems for offshore energy mooring. This consumption-mix differential fragments manufacturing strategies across geographies.
United States
OSHA fall-protection mandates drive replacement demand across utility and construction sectors. Federal safety protocols enforce synthetic rope inspection cycles that sustain aftermarket volume. Gulf Coast offshore service vessel operators source HMPE mooring lines through Houston-based distributors.
Germany
Construction crane operators accelerate wire-to-synthetic substitution to reduce handling injuries and drum changeover downtime. REACH chemical disclosure requirements tighten coating reformulation timelines for EU export qualification. North Sea wind lease rounds concentrate procurement among qualified suppliers in Hamburg and Bremen.
China
Domestic shipbuilding expansion absorbs polyester and HMPE fiber output from new polymer plants. SAMR-administered GB standards converge with international norms to facilitate manufacturer export competitiveness. Yangtze River Delta rope fabricators supply coastal fishing fleets and container vessel outfitters.
Denmark
Offshore wind developers specify HMPE mooring systems for floating turbine platforms in deep-water lease areas. ECHA restrictions on fluorinated coatings force fiber finish qualification for North Sea project eligibility. Copenhagen-area procurement teams mandate reference project documentation as tender gating criteria.
Brazil
Soybean producers drive seasonal polypropylene baler twine demand during harvest compression windows. Agricultural applications dominate volume consumption at minimal specification tiers. São Paulo-state distributors supply coastal fishing operations with polyester longline and trawl configurations.
Synthetic Rope Market Key Industry Players
Capability concentration sits with specialized fiber-to-rope integrators; scale advantage sits with diversified industrial cordage houses. The vendor base separates into three functional tiers: integrated polymer producers controlling upstream fiber supply, specialized marine-grade engineers commanding offshore energy premiums, and commodity converters competing on per-meter pricing. Dominant competitive moves include captive polymer extrusion investments and strategic qualification tracking for EU offshore wind tenders.
Specialists in high-modulus polyethylene marine systems include Samson Rope Technologies and Cortland Limited, which occupy positions within the integrated-manufacturing archetype. Teufelberger Holding AG represents the precision-braiding tier serving rescue and arborist segments where Austrian-engineered construction commands pricing power. WireCo WorldGroup anchors the diversified industrial cordage category with broad portfolio coverage across lifting and mooring applications.
| Leading Market Players |
|---|
| Marlow Ropes |
| English Braids Ltd. |
| Cortland Limited |
| Southern Ropes |
| Teufelberger Holding AG |
| WireCo WorldGroup |
| Yale Cordage |
| Bridon-Bekaert |
| Samson Rope Technologies |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape across synthetic rope manufacturing, compressing margins on polypropylene and polyester grades when propylene and PTA spot prices spike while insulating integrated fiber-to-rope producers from merchant market swings.
Pricing Analysis
Chinese-origin polypropylene rope trades at substantial discounts to European-manufactured HMPE equivalents, reflecting fiber cost differentials and certification overhead. Pricing stratifies across premium, standard, and economy tiers based on tensile certification grade and volume procurement scale. Cost compression in commodity marine grades is intensifying as Yangtze River Delta extrusion capacity expands. Agricultural buyers in Brazil exhibit highest price sensitivity, while North Sea offshore wind developers tolerate substantial premiums for documented installation track records.
Supply Chain Analysis
Export-control restrictions on ultra-high molecular weight polyethylene fiber production equipment limit technology transfer to Chinese manufacturers, concentrating premium HMPE supply among Dutch, Japanese, and American chemical producers. Raw material flows draw from propylene crackers in the US Gulf Coast, PTA refineries in South Korea, and caprolactam plants in Germany. Single-source vulnerability pervades high-modulus fiber supply, with three specialized chemical manufacturers controlling merchant HMPE output. Distribution runs through marine equipment distributors in Hamburg, Houston, and Singapore, with direct OEM supply agreements gaining share in offshore energy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic rope market fragmentation creates specialized niche opportunities as offshore wind procurement consolidation displaces generalist suppliers without project documentation history.
For Market Incumbents: Entrench position through captive polymer extrusion investments that insulate margin control against fiber merchant volatility. Accelerate REACH-compliant coating qualification to pre-empt EU tender exclusion. Prioritize reference project documentation in Danish and German North Sea lease rounds where developer procurement standards have narrowed qualified supplier bases. For New Entrants and Emerging Players: Establish a beachhead in Brazilian agricultural baler twine where specification minima and seasonal demand patterns deter integrated marine specialists. Target Vietnamese and Indonesian coastal fishing fleets with UV-stabilized polyester longline configurations. Pursue private-label supply agreements with Yangtze River Delta distributors to bypass brand development overhead. For Investors and Strategic Acquirers: REACH Annex XVII fluorinated substance restrictions reshape the acquisition landscape toward rope manufacturers with in-house polymer chemistry capabilities rather than contract finishers. Five-to-ten-year viability favors integrated fiber-to-rope specialists with offshore wind installation track records. Monitor ECHA coating reformulation enforcement intensity as inflection indicator for European procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HMPE Fiber Production | Captive supply of ultra-high molecular weight polyethylene insulates margin control against three-supplier concentration risk. |
| REACH-Compliant Coating Qualification | Pre-certified fiber finishes unlock EU offshore energy tender eligibility as ECHA restrictions tighten. |
| Embedded Fiber-Optic Strain Sensing Development | Real-time load monitoring virtualization commands premium positioning in North Sea floating wind mooring contracts. |
| HMPE Splicing Technician Training Programs | Vocational pipeline expansion addresses scarcity constraining premium rope termination quality in offshore hiring regions. |
| Reference Project Documentation Investment | Documented installation track records satisfy procurement gating criteria at Danish and German utility developers. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with rope manufacturing plant managers, offshore wind procurement leads at European utilities, marine equipment distributors, and technical R&D directors; and secondary validation through customs trade databases, SEC filings of diversified cordage houses, ISO certification registries, and ECHA substance restriction notifications. Bottom-up fiber consumption estimates and top-down end-use demand aggregation were triangulated against capacity announcements from Chinese polymer producers.
Forecast inputs considered material-grade segmentation, application-channel splits, diameter-format distributions, and regional procurement patterns across the analysis window. CAGRs were derived from installed base modeling of marine fleet renewal cycles, offshore wind turbine deployment schedules, and construction crane fleet synthetic substitution rates. Petrochemical feedstock price scenarios and REACH enforcement timelines served as sensitivity inputs.
Stress conditions across propylene spot volatility bands, HMPE fiber supply disruption scenarios, and EU coating reformulation compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on shipbuilding output trajectories and offshore wind lease round schedules. Material shifts in ECHA fluorinated substance restriction implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Graphene Composites Market
Composite Materials
Pultrusion Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Plastic Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Europe Composites Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Long-Fiber Thermoset Composites Market