
 High Performance Composites Market | 2026-2036
High Performance Composites Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Composites Market Analysis
Modular preform kits and standardized layup bundles is hardening as the dominant procurement format for aerospace tier-one suppliers. Teijin Limited leverages its integrated carbon fiber-to-prepreg chain to capture value from this bundling shift. Hexcel Corporation anchors North American supply through dedicated autoclave capacity and qualification depth with prime contractors. SGL Carbon specializes in automotive-grade chopped fiber formats that compete on cycle time against traditional metals.
High performance composites are engineered material systems combining high-strength fibers with thermoset or thermoplastic matrices, typically achieving specific tensile strengths above 500 MPa and operating temperatures beyond 150°C for continuous service. Carbon fiber composites lead commercial value due to their stiffness-to-weight ratios in primary aircraft structures, while ceramic matrix composites represent the fastest-growing product category as turbine OEMs pursue higher thermal efficiency. Polymer matrix composites occupy the broadest application base across automotive and industrial equipment segments where processing scalability supports volume economics.
FAA certification protocols and EASA CS-25 airworthiness standards govern material qualification timelines and testing burdens for aerospace suppliers, while REACH and RoHS frameworks restrict certain resin chemistries in European industrial applications. The EU Green Deal's embodied carbon tracking requirements are forcing laminate producers to document lifecycle emissions across precursor supply chains. Stakeholders must monitor evolving qualification standards for recycled fiber content as sustainability specifications tighten across defense and commercial aerospace procurement.
Market Dynamics
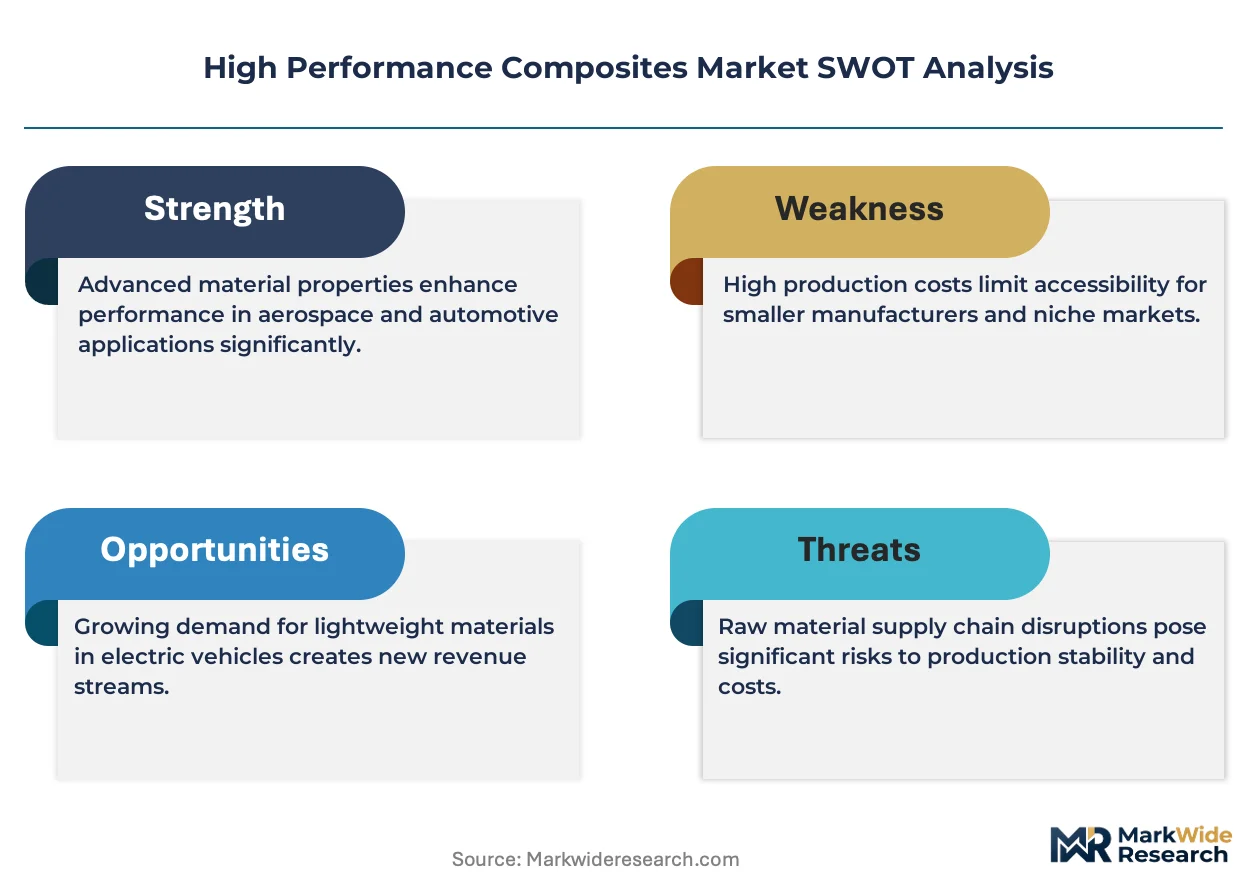
Carbon fiber-to-prepreg bundling is consolidating procurement power among aerospace tier-one suppliers, forcing laminate producers to absorb qualification costs and inventory risk while Teijin and Hexcel deepen captive supply chains.
Growth Catalysts
- FAA-EASA harmonized airworthiness standards:Streamlined dual certification paths compress timeline burdens for primary structure suppliers serving Boeing and Airbus programs simultaneously.
- Automotive lightweighting mandates:Germany's KBA enforcement of fleet CO2 targets accelerates chopped fiber thermoplastic adoption in BMW and Mercedes electric vehicle platforms.
- Ceramic matrix composite thermal efficiency gains:Turbine OEMs at GE Aviation and Rolls-Royce deploy CMCs in high-pressure sections to raise operating temperatures without cooling bleed air.
Market Restraints
- Acrylonitrile precursor cost volatility:Fossil-fuel-derived feedstock exposure ties carbon fiber margins to petrochemical pricing swings beyond producer control.
- Japanese carbon fiber supply concentration:Toray, Teijin, and Mitsubishi Chemical anchor 60% of global PAN-based precursor capacity, creating geographic chokepoint vulnerability.
- Thermoset recycling technical limitations:Cross-linked epoxy matrices resist depolymerization, blocking circular material flows under EU Green Deal embodied carbon tracking.
Strategic Opportunities
- India defense indigenization:DRDO procurement mandates under the Make in India framework open qualification pathways for foreign composite suppliers partnering with HAL.
- Wind blade carbon fiber penetration:Vestas and Siemens Gamesa specify hybrid glass-carbon spar caps for 15MW+ offshore turbines, creating volume pull for industrial-grade tow.
- Digital thread integration:Automated fiber placement combined with in-situ thermoplastic welding collapses layup-to-assembly time for next-generation aerostructures.
Industry Challenges
- Autoclave capacity scarcity:Out-of-autoclave curing qualification gaps force aerospace suppliers to queue for limited oven time at certified facilities.
- Polymer chemist workforce shortages:REACH-restricted resin formulation expertise concentrates among retiring specialists at European compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Composites Market |
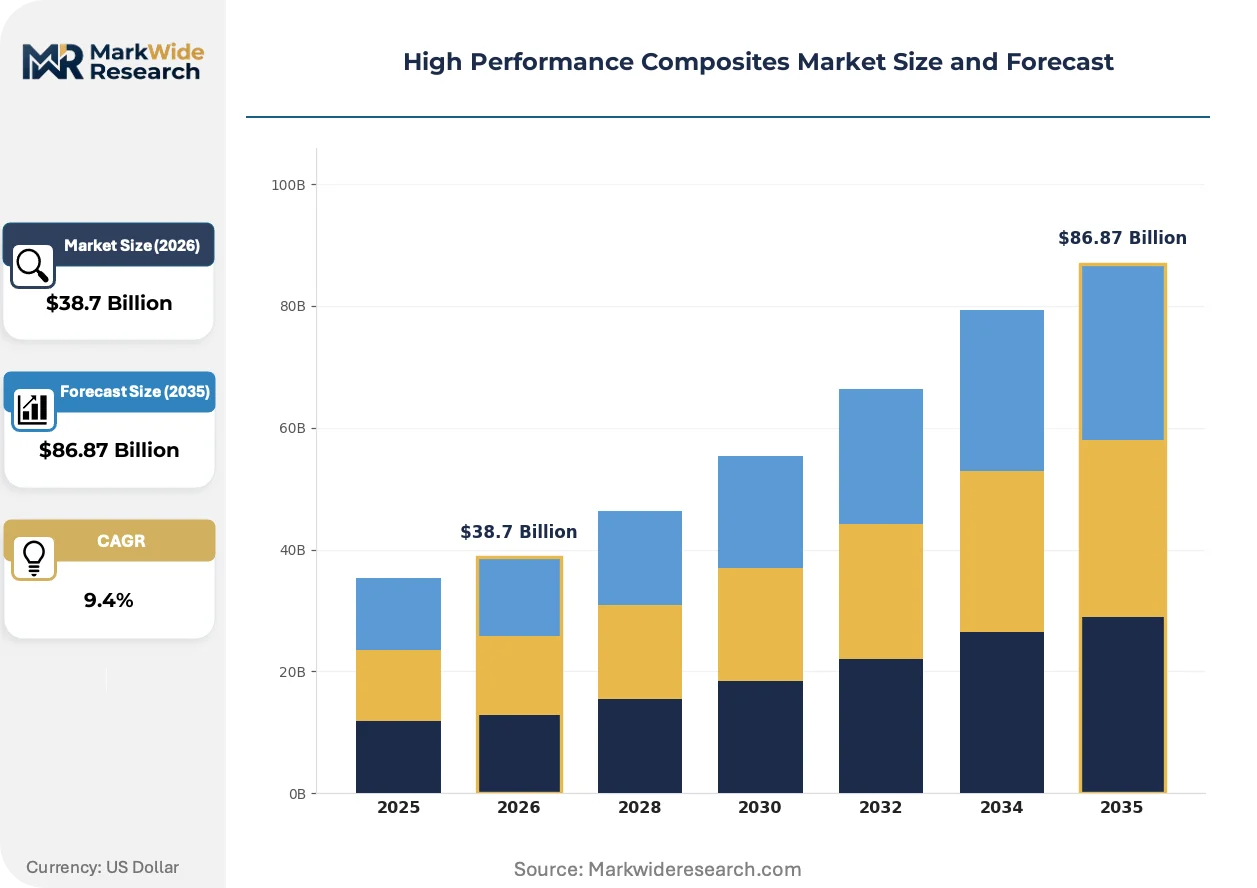
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Matrix Composites, Carbon Fiber Composites, Glass Fiber Composites, Polymer Matrix Composites Application: Aerospace, Automotive, Marine, Industrial Equipment End User: Defense, Healthcare, Construction, Electronics Form: Sheet, Rod, Tube, Custom Shapes |
| Companies Covered | Teijin Limited, SGL Carbon, Hexcel Corporation, DuPont, Owens Corning, Toray Industries, Mitsubishi Chemical Group, BASF, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Composites Market Emerging Trajectories
Material informatics and automated manufacturing are compressing development cycles while regulatory carbon accounting rewrites supplier qualification criteria across defense and commercial aerospace procurement.
Thermoplastic unidirectional tapes are integrating into primary aerostructures through automated fiber placement systems at Gulfstream and Dassault Aviation. The welding-enabled assembly eliminates drilling and fastening operations that damage carbon fiber continuity. This is integrating out-of-autoclave processing into mainstream airframe construction, collapsing capital intensity for new program entrants.
REACH authorization restrictions on bisphenol-A epoxies are forcing laminate producers to reformulate resin systems ahead of 2025 sunset dates. German automotive suppliers face immediate substitution deadlines under ECHA enforcement timelines. Aerospace qualification protocols lag chemical availability, creating formulation-evaluation bottlenecks at Tier 2 prepreggers serving Hamburg and Toulouse assembly lines.
Modular preform kit procurement is consolidating specification authority at Safran and Leonardo's aerostructures divisions. Standardized layup bundles displace raw material purchasing across European supply chains. Japanese trading houses now intermediate between precursor producers and Italian-Brazilian aerostructures joint ventures, capturing margin through logistics coordination rather than manufacturing.
High Performance Composites Market Segmentation
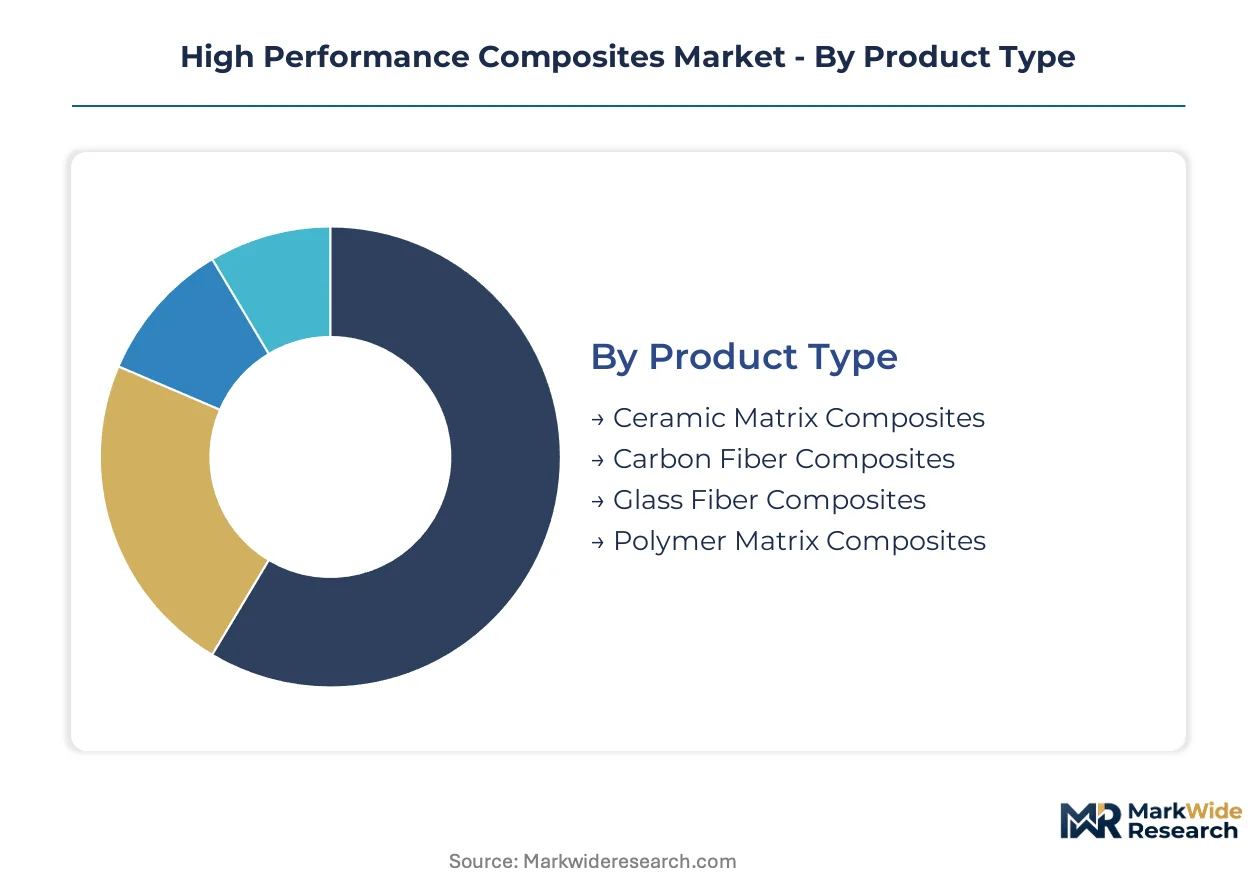
Segmentation in high performance composites determines qualification pathways, tooling investments, and margin structures. Product chemistry governs thermal envelope and mechanical properties. Application verticals dictate certification burdens and procurement scale.
Product Type:
Customization intensity varies from standardized chopped fiber formats to application-specific matrix formulations requiring dedicated autoclave protocols.
- Carbon Fiber Composites:PAN-based precursor systems achieve specific tensile strengths above 3,000 MPa with modulus exceeding 230 GPa. Aerospace manufacturers at Boeing and Airbus specify these for primary wing structures and fuselage barrels where stiffness-to-weight ratios determine fuel efficiency. FAA-EASA harmonized qualification protocols compress dual-certification timelines for prepreg suppliers.
- Ceramic Matrix Composites:Silicon carbide fiber-reinforced systems operate beyond 1,200°C in oxidizing environments. Turbine OEMs at GE Aviation deploy CMC shrouds and combustor liners to eliminate cooling bleed air, raising thermal efficiency in next-generation engines. Expanding most quickly as propulsion electrification and hydrogen combustion architectures demand refractory material solutions.
- Polymer Matrix Composites:Epoxy and thermoplastic matrices dominate automotive and industrial equipment where processing scalability supports volume economics.
- Glass Fiber Composites:E-glass and S-glass systems compete on cost in secondary structures and corrosion-resistant industrial applications.
Leading the category by volume: Polymer Matrix Composites. Climbing the fastest: Ceramic Matrix Composites.
Application:
Volume concentration tracks OEM platform cycles and regulatory compliance deadlines across defense and commercial procurement.
- Aerospace:Primary and secondary structures for commercial aircraft, rotorcraft, and space launch vehicles. Boeing 787 and Airbus A350 programs anchor carbon fiber demand at 50%+ airframe weight fraction. Tier-one suppliers consolidate procurement through modular preform kits, forcing laminate producers to absorb inventory risk.
- Automotive:BMW and Mercedes electric platforms specify chopped fiber thermoplastics for battery enclosures and body-in-white components. Germany's KBA enforces fleet CO2 targets that accelerate lightweighting mandates.
- Marine:Hull structures and superyacht components leverage corrosion resistance and radar transparency.
- Industrial Equipment:Chemical processing vessels, robotics arms, and precision tooling exploit dimensional stability and fatigue resistance.
Revenue concentration peaks in Aerospace. Procurement momentum is strongest in Automotive.
End User:
Specification authority varies from centralized defense procurement to fragmented construction subcontracting.
- Defense:Military aircraft, naval vessels, and armor systems require ITAR-controlled supply chains and dedicated qualification protocols. DRDO procurement mandates under India's Make in India framework open partnership pathways for foreign suppliers qualifying with HAL.
- Electronics:Thermal management substrates and RF-transparent enclosures demand tight dimensional tolerances.
- Healthcare:Imaging equipment housings and surgical instruments exploit radiolucency and sterilization compatibility.
- Construction:Bridge decks, seismic retrofit systems, and architectural facades deploy glass fiber and carbon fiber reinforcement.
Margin premiums concentrate in Defense. Volume scaling potential is greatest in Construction.
Form:
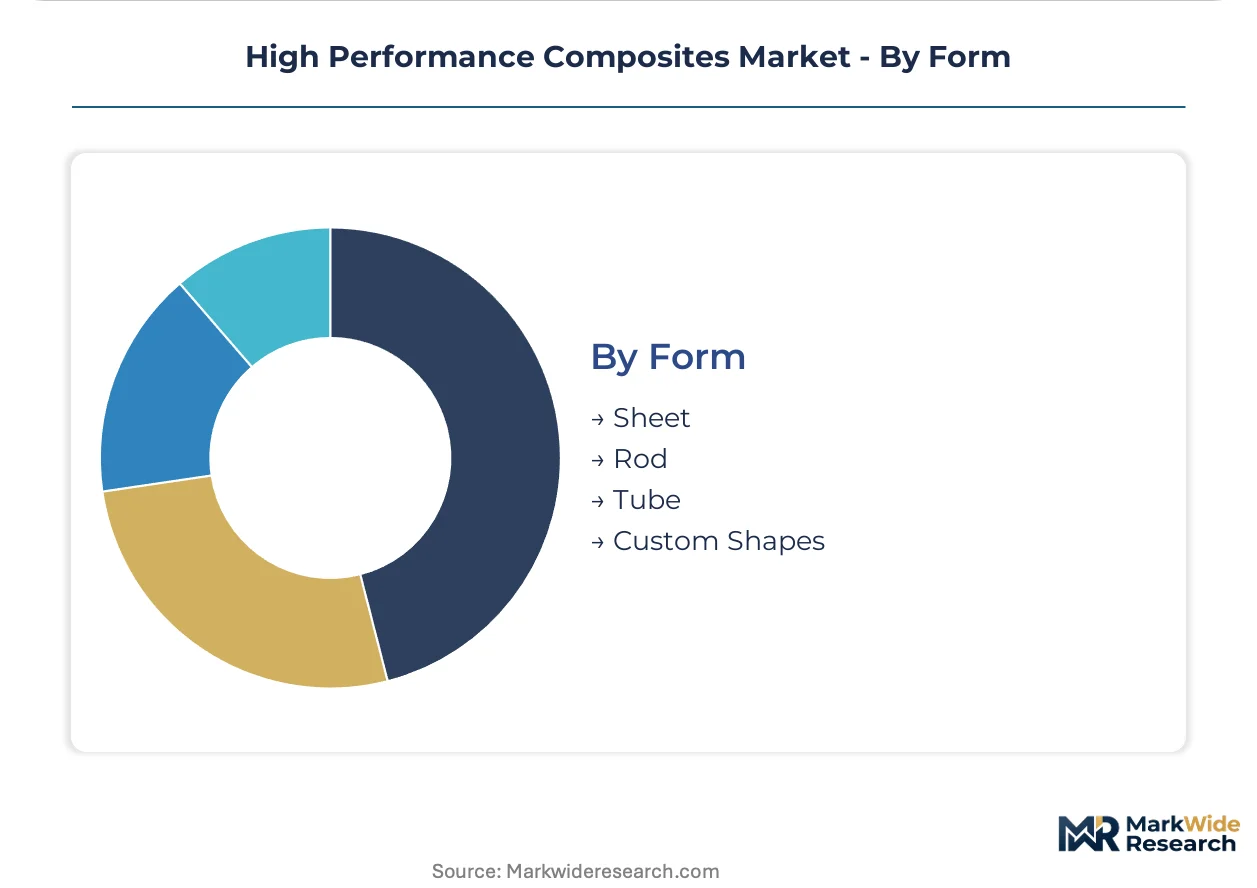
Processing method determines capital intensity and labor content across subtractive, formative, and additive manufacturing routes.
- Sheet:Unidirectional and woven prepreg formats dominate aerostructure layup operations. Automated fiber placement systems at Gulfstream and Dassault Aviation integrate thermoplastic unidirectional tapes through welding-enabled assembly.
- Custom Shapes:Near-net preforms and braided preforms reduce machining scrap in complex geometries. Japanese trading houses intermediate logistics between precursor producers and Italian-Brazilian aerostructures joint ventures.
- Rod:Pultruded profiles serve structural reinforcement and tension members.
- Tube:Filament-wound cylinders pressure vessels and drive shafts exploit hoop strength optimization.
Procurement standardization favors Sheet formats. Value-added differentiation concentrates in Custom Shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and Germany concentrate carbon fiber precursor production, while the United States and China absorb the bulk of finished composite consumption. This geographic split between upstream manufacturing and downstream fabrication creates logistics dependencies that trading houses increasingly intermediate. Aerospace qualification protocols further lock supply relationships across these production-consumption corridors.
United States
Boeing's 787 and 777X programs anchor demand for primary structure prepregs, with tier-one suppliers consolidating procurement through modular kit formats. FAA certification protocols govern material qualification timelines, compressing testing burdens for dual-certified suppliers. The Pacific Northwest aerospace cluster around Seattle and Charleston hosts dedicated autoclave capacity serving Boeing's final assembly lines.
Germany
BMW and Mercedes electric vehicle platforms specify chopped fiber thermoplastics for battery enclosures, accelerating lightweighting mandates. KBA enforcement of fleet CO₂ targets tightens material specifications across the automotive corridor. The Munich-Stuttgart manufacturing belt concentrates thermoplastic processing expertise for high-volume electric platform production.
Japan
Toray, Teijin, and Mitsubishi Chemical anchor sixty percent of global PAN-based precursor capacity, creating geographic concentration in carbon fiber feedstock. METI industrial policy supports advanced materials R&D through public-private partnerships. The Nagoya-Tokyo corridor integrates precursor production with aerospace qualification facilities serving domestic and export markets.
China
COMAC's C919 narrowbody program drives qualification demand for domestic composite suppliers, with MIIT standards governing material substitution in civil aviation. Dual carbon goals accelerate wind blade manufacturing, pulling industrial-grade carbon fiber tow for 15MW+ offshore turbines. The Yangtze River Delta hosts expanding prepreg capacity serving both aerospace and renewable energy fabrication.
India
DRDO procurement mandates under the Make in India framework open qualification pathways for foreign suppliers partnering with HAL on combat aircraft programs. BIS standards increasingly govern defense material specifications, creating compliance thresholds for import substitution. The Bangalore-Hyderabad aerospace corridor concentrates defense fabrication capabilities with expanding composite repair and overhaul infrastructure.
High Performance Composites Market Vendor Landscape
The competitive structure tilts toward integrated fiber-to-prepreg specialists with captive precursor supply. Japanese and European producers dominate upstream carbon fiber manufacturing, while North American fabricators anchor aerospace qualification depth. Three archetypes define positioning: integrated chemical conglomerates controlling precursor-to-laminate chains, specialized carbon fiber pure-plays serving automotive and industrial volume segments, and diversified materials multinationals leveraging polymer formulation expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as qualification timelines limit rapid market entry.
Among Japanese integrated producers, Teijin Limited and Toray Industries exemplify the fiber-to-prepreg archetype with upstream control over PAN precursor supply. Hexcel Corporation occupies a position within the North American aerospace qualification tier, anchoring supply relationships through dedicated autoclave capacity and FAA-EASA certification depth. SGL Carbon represents the automotive-specialist vector, with German GmbH structure signaling European industrial market focus.
| Leading Market Players |
|---|
| Teijin Limited |
| SGL Carbon |
| Hexcel Corporation |
| DuPont |
| Owens Corning |
| Toray Industries |
| Mitsubishi Chemical Group |
| BASF |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Aerospace tier-one suppliers at Boeing and Airbus anchor procurement through modular preform kits, imposing contract-based long-term offtake pricing that shifts inventory risk onto laminate producers. This buyer concentration rewards suppliers with FAA-EASA dual certification depth while squeezing margins on standardized formats.
Pricing Analysis
Cost-down pressure on aerospace-grade prepregs accelerates because tier-one suppliers consolidate specification authority through bundled kit procurement. Three-tier pricing structure across aerospace-qualified, industrial-grade, and automotive-chopped formats reflects certification burden and volume scale differentiation. Price differentiation traces to REACH-compliant resin formulations versus legacy epoxy systems facing sunset deadlines. Automotive OEMs exhibit highest price sensitivity as they benchmark chopped fiber thermoplastics against stamped aluminum; defense contractors show lowest sensitivity due to ITAR-controlled supply chain premiums.
Supply Chain Analysis
India's Make in India localization mandates and China's MIIT domestic-content requirements are reshaping sourcing patterns for defense and civil aviation composites. Feedstock supply concentrates in Japan, Germany, and the United States for PAN-based precursor and specialized resin systems. Manufacturing dependencies rest on acrylonitrile petrochemical feedstocks, silicon carbide ceramic fibers, and thermoplastic unidirectional tape formats. Single-source vulnerability concentrates in Japanese carbon fiber precursor capacity. Distribution runs through Japanese trading houses coordinating logistics between precursor producers and European aerostructures joint ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite welding technology is displacing thermoset autoclave curing across next-generation aerostructures, compressing capital intensity and collapsing traditional qualification timelines. Stakeholders must position against this process-transition inflection.
For Market Incumbents: Cement captive precursor supply through backward integration into PAN manufacturing or exclusive offtake agreements with Japanese chemical conglomerates. Deepen autoclave qualification moats at FAA-certified facilities to defend against out-of-autoclave process substitution. Lock tier-one supplier relationships through modular preform kit bundling before thermoplastic welding protocols mature.
For New Entrants and Emerging Players: India's defense procurement offices represent the most penetrable buyer archetype as DRDO indigenization mandates create qualification pathways for foreign suppliers partnering with HAL. Target wind blade manufacturers specifying hybrid glass-carbon spar caps for 15MW+ offshore turbines as volume-scaling entry points. Pursue joint-venture structures with domestic Indian fabricators to satisfy local-content thresholds while importing technical qualification expertise.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized carbon fiber pure-plays with automotive-grade chopped fiber capacity in Germany's Munich-Stuttgart corridor. Long-term viability hinges on thermoplastic processing expertise and REACH-compliant resin formulation capabilities. Monitor ECHA enforcement timelines for bisphenol-A epoxy restrictions as inflection signal for formulation-evaluation bottlenecks creating acquisition targets among distressed European preggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor | Captive PAN supply insulates margins from acrylonitrile volatility at Toray and Teijin. |
| Thermoplastic Welding Qualification | Out-of-autoclave protocols at Gulfstream collapse capital intensity for new aerostructure programs. |
| REACH-Compliant Resin Reformulation | ECHA sunset deadlines force substitution ahead of aerospace qualification lag at Hamburg suppliers. |
| Indian Joint Venture Structure | HAL partnership pathways satisfy DRDO local-content mandates for combat aircraft composite supply. |
| Wind Blade Spar Cap Supply Agreement | Vestas and Siemens Gamesa specifications pull industrial-grade tow volume for 15MW+ offshore turbines. |
Methodological Framework
Document review covered regulatory filings with FAA and EASA, trade data from customs authorities, and industry association publications from ACC and JIS, complemented by interviews with composite plant managers, aerospace procurement leads at tier-one suppliers, thermoplastic R&D directors, and distribution channel partners. Secondary validation drew from SEC 10-K filings, REACH authorization databases, and MIIT standards documentation. Bottom-up segment modeling triangulated against top-down macroeconomic drivers across the analysis window.
Historical volume trajectories cross-referenced against expert panel input from precursor producers and laminate fabricators shaped the analytical framework. Segmentation dimensions included matrix chemistry, fiber type, application vertical, and regional production cluster. CAGRs derived from regression analysis of qualification timeline compression and platform adoption curves. Forecast inputs incorporated wind turbine scaling specifications and automotive lightweighting mandate enforcement intensity.
Revisions become necessary when FAA-EASA harmonization protocols stall, REACH authorization timelines accelerate, or thermoplastic welding qualification gaps persist beyond projected closure. Forecasts reflect documented assumptions on precursor capacity expansion and defense procurement budget trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Laminar Composites Market
Composite Materials
Composite Preforms Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Pultrusion Market
Composite Materials
Global Sports Composites Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Synthetic Rope Market
Composite Materials
Structural Composites Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Pulp Moulding Tooling Market