
 Plant-Based Hydraulic Oil Market | 2026-2036
Plant-Based Hydraulic Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Hydraulic Oil Market Insights
Buyer concentration among construction machinery fleets is realigning procurement specifications toward biodegradable hydraulic fluids. PANOLIN AG leverages Swiss manufacturing depth to dominate high-performance biodegradable formulations. Fuchs Petrolub SE anchors European distribution through its established industrial lubricant network. Cargill competes with captive oilseed supply chains that reduce feedstock cost volatility.
Plant-based hydraulic oil consists of vegetable-derived base stocks, typically triglyceride esters from soybean or rapeseed, formulated with ashless additives to achieve ISO VG 32-68 viscosity grades and oxidative stability for high-pressure hydraulic systems. Agricultural Equipment applications lead volume uptake due to proximity-sensitive operations near waterways and soil. The Biodegradable grade segment captures premium positioning as OEMs embed environmental specifications into factory-fill contracts. Castor Oil formulations represent the fastest-growing product type because ricinoleic acid delivers superior lubricity and thermal stability compared to commodity oilseeds.
EPA Safer Choice and EU Ecolabel standards shape product formulation requirements across North American and European markets. BIS in India and China's MEE are developing comparable eco-label frameworks for industrial lubricants. The EU F-Gas Regulation and REACH compliance costs are accelerating substitution away from mineral-based alternatives. Stakeholders must monitor how national procurement codes incorporate biodegradability thresholds into public infrastructure equipment contracts.
Market Dynamics
EU Ecolabel and EPA Safer Choice standards are compressing formulation tolerances while construction machinery OEMs rewrite factory-fill specifications to mandate biodegradable base stocks.
Growth Catalysts
- Forestry Equipment Mandates:Germany's operational fluid regulations for equipment near waterways are forcing fleet operators to specify biodegradable hydraulic fluids in procurement contracts.
- OEM Specification Expansion:Construction machinery manufacturers are embedding environmental performance clauses into factory-fill agreements, creating guaranteed offtake for certified formulations.
- Castor Oil Chemistry:Ricinoleic acid structures deliver superior lubricity and thermal stability, enabling high-pressure system deployment where commodity vegetable oils previously failed.
Market Restraints
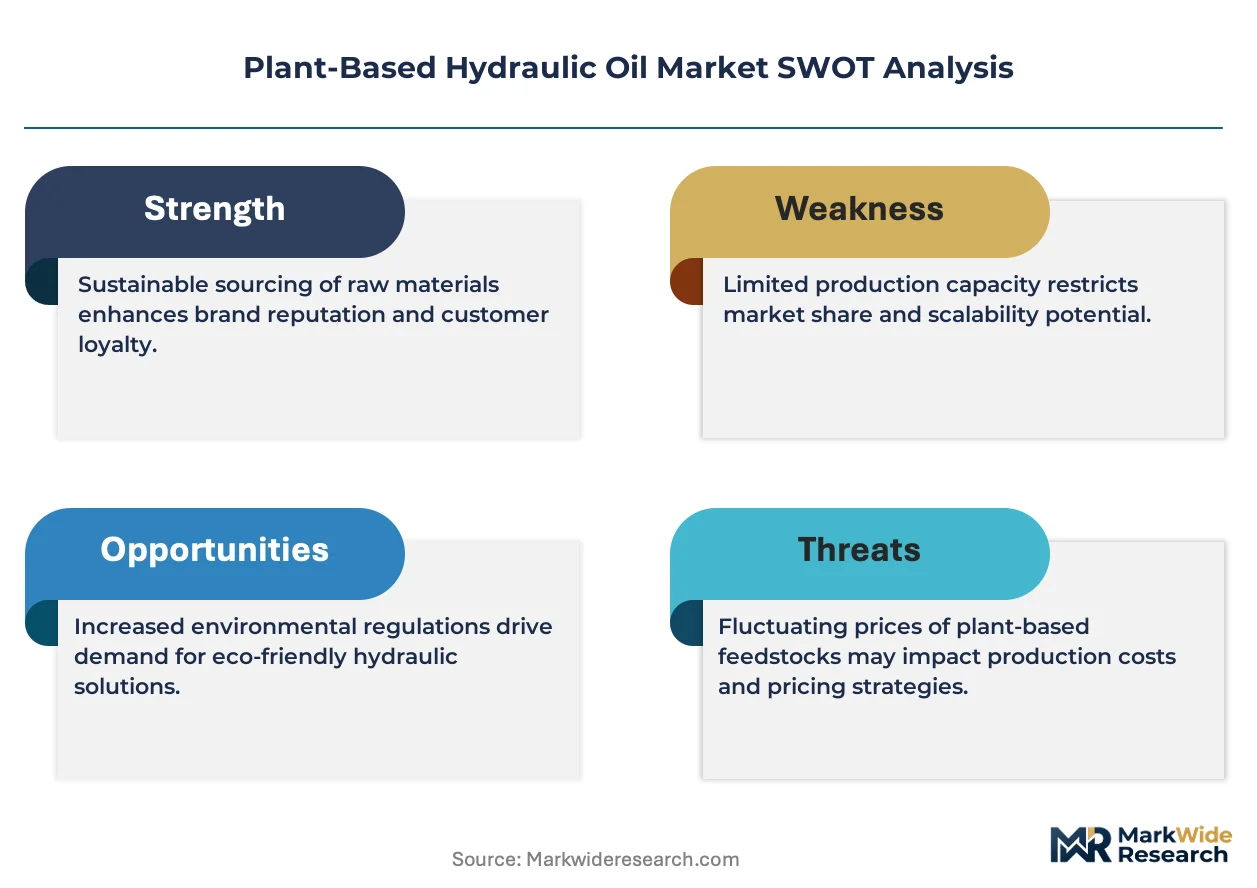
- Oilseed Feedstock Volatility:Soybean and rapeseed prices fluctuate with agricultural commodity cycles, compressing margin predictability for formulators lacking captive supply.
- REACH Compliance Burden:European additive registration costs and testing timelines create structural barriers for mid-scale producers entering the biodegradable segment.
- Mineral Oil Substitution Economics:Conventional hydraulic fluids retain cost advantages in price-sensitive emerging markets, limiting addressable market expansion.
Strategic Opportunities
- India BIS Eco-Label Development:India's Bureau of Indian Standards is drafting industrial lubricant environmental frameworks, creating first-mover positioning for compliant suppliers.
- Marine Hydraulic Systems:Offshore equipment and inland waterway vessels face spill-sensitive operating environments where biodegradable grades command specification premiums.
- Direct Fleet Contracting:Equipment leasing companies and large construction contractors are bypassing traditional distribution to negotiate volume supply agreements directly with formulators.
Industry Challenges
- Additive Compatibility Expertise:Formulating ashless additive packages that maintain oxidative stability in triglyceride base stocks requires specialized tribology capabilities scarce in conventional lubricant operations.
- OEM Factory-Fill Certification Timelines:Securing approved supplier status with construction equipment manufacturers involves extended field testing protocols that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Hydraulic Oil Market |
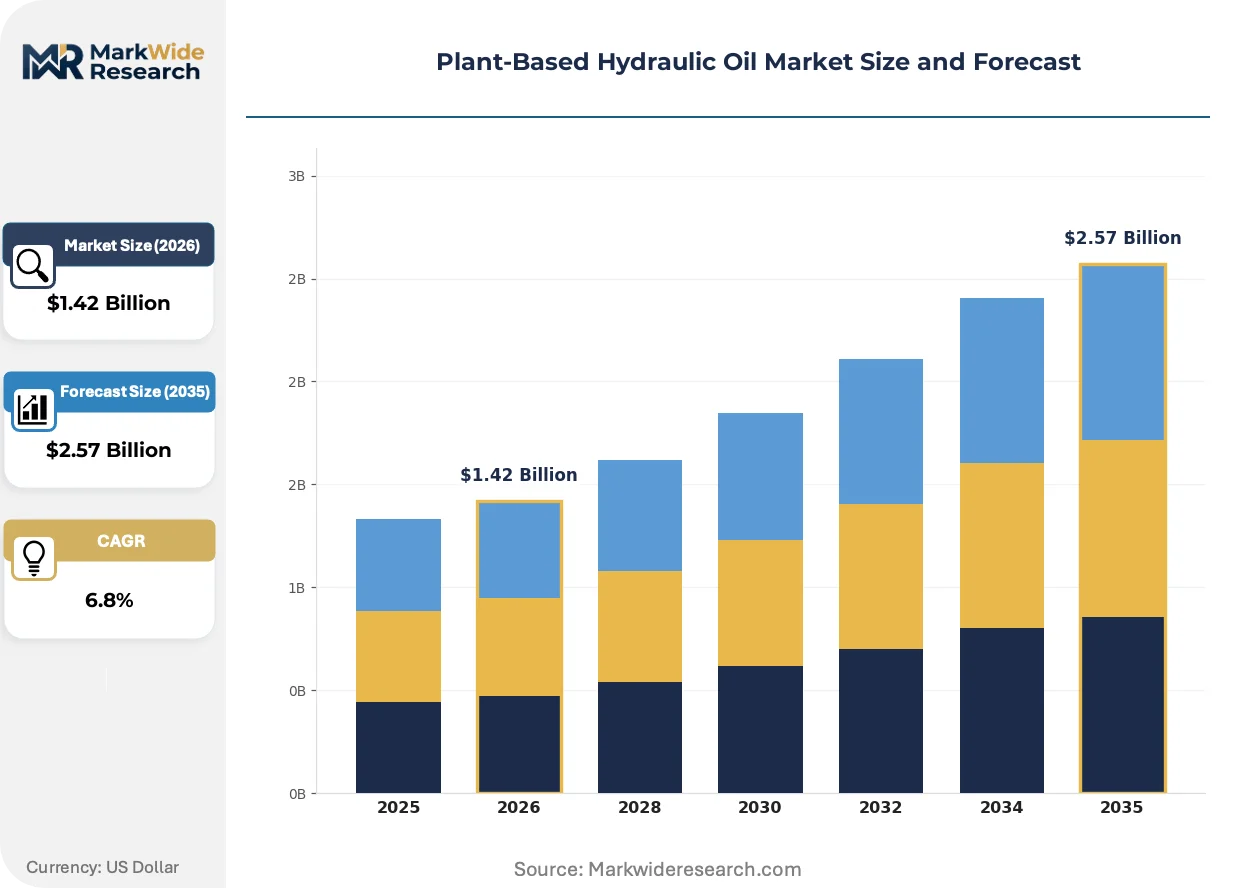
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Rapeseed Oil, Palm Oil, Castor Oil Application: Agricultural Equipment, Construction Machinery, Marine Equipment, Industrial Applications End User: Agriculture, Manufacturing, Forestry, Automotive Grade: Biodegradable, Non-Toxic, High-Viscosity, Eco-Friendly |
| Companies Covered | Renewable Lubricants, PANOLIN AG, Fuchs Petrolub SE, Cargill, BASF SE, BioBlend, Houghton International, Lubriplate Lubricants, Hydro Safe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Hydraulic Oil Market Trends and Innovations
Formulation chemistry and procurement specifications are converging to redefine competitive positioning, with regulatory compliance and feedstock innovation becoming inseparable from market access.
Castor oil-derived base stocks are consolidating technical credibility in high-performance biodegradable formulations. Forestry equipment operators in Germany and Austria specify these grades for steep-slope harvesters where thermal load exceeds commodity vegetable oil limits. The technology is consolidating supplier differentiation around lubricity performance rather than biodegradability certification alone.
EPA Safer Choice standards are tightening performance benchmarks for environmentally acceptable lubricants in North American markets. Industrial buyers now face procurement code amendments that embed biodegradability thresholds into public infrastructure equipment contracts. Construction machinery fleets in California and New York are responding fastest, rewriting fluid specifications to preempt state-level environmental mandates.
Buyer concentration among equipment leasing companies is compressing supplier negotiation leverage. Large fleet operators aggregate annual fluid volumes that exceed traditional distributor throughput, enabling direct manufacturer contracting that disintermediates regional lubricant distributors. This pattern is most visible in German-speaking Europe, where Komatsu and Volvo CE fleet managers negotiate pan-European supply agreements with single-source formulators.
Plant-Based Hydraulic Oil Market Segmentation
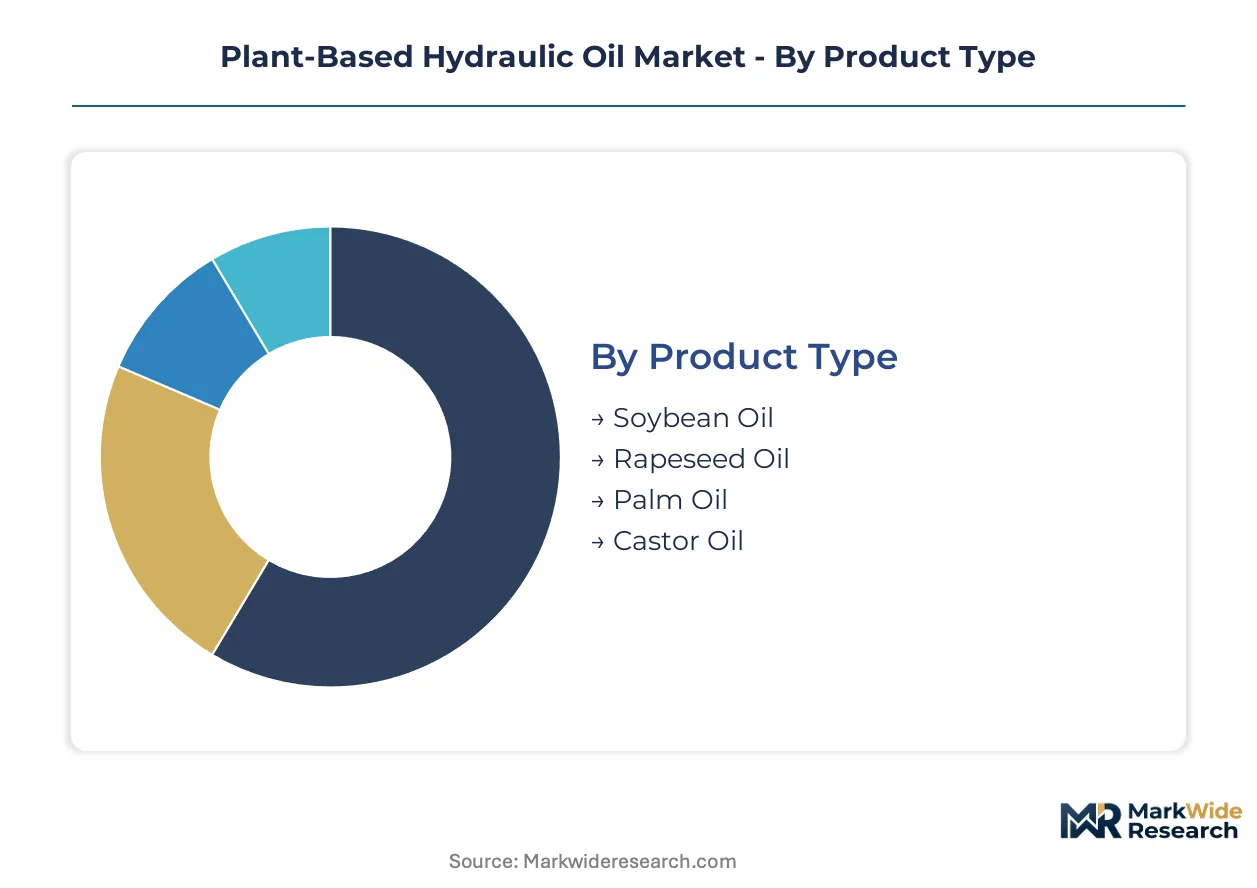
Segmentation in plant-based hydraulic oils reveals how feedstock chemistry, equipment specifications, and regulatory thresholds intersect to determine commercial viability. Equipment manufacturers and fleet operators select formulations based on operating pressure demands, biodegradability mandates, and proximity to sensitive environments.
Product Type:
Equipment replacement cycles and factory-fill contract renewals create upgrade windows where superior base stock chemistry displaces incumbent formulations.
- Soybean Oil:Triglyceride esters from soybean deliver cost-competitive base stocks for ISO VG 32-46 viscosity grades in moderate-pressure agricultural systems. Demand concentrates in Midwest US farm equipment fleets where supply chain proximity reduces landed costs and EPA Safer Choice procurement codes drive specification shifts.
- Castor Oil:Ricinoleic acid structures provide inherent lubricity and thermal stability exceeding commodity oilseeds, enabling deployment in high-pressure construction machinery hydraulics. German forestry equipment operators specify these grades for steep-slope harvesters where thermal loads surpass conventional vegetable oil limits.
- Rapeseed Oil:European cultivation networks support regional formulators with lower carbon intensity feedstock for mid-performance applications.
- Palm Oil:Southeast Asian supply bases compete on volume scale despite sustainability certification complexities in EU markets.
Volume placements concentrate in Soybean Oil; the faster expansion belongs to Castor Oil.
Application:
Cost tier stratification separates specification-intensive premium segments from price-sensitive standard deployments.
- Agricultural Equipment:Tractors and harvesters operating near waterways face spill-sensitive mandates that embed biodegradable fluid requirements into OEM factory-fill agreements. Demand clusters in Germany and California where operational fluid regulations and state procurement codes enforce environmental performance clauses.
- Construction Machinery:Excavators and loaders with high-pressure hydraulic systems above 300 bar require thermal stability that commodity vegetable oils fail to deliver, creating specification premiums for castor-derived formulations. Komatsu and Volvo CE fleet managers in German-speaking Europe negotiate pan-European supply agreements directly with formulators.
- Marine Equipment:Offshore vessels and inland waterway fleets operate under spill-sensitive conditions where biodegradable grades command certification premiums.
- Industrial Applications:Factory automation and metalworking hydraulics represent volume scale opportunities with moderate performance thresholds.
Procurement volumes cluster in Agricultural Equipment; Construction Machinery is gaining share fastest.
End User:
Customer concentration patterns determine whether distribution runs through equipment OEMs, regional lubricant distributors, or direct manufacturer contracts.
- Forestry:Steep-slope harvesting operations in Germany and Austria face the strictest operational fluid mandates, forcing fleet-wide biodegradable specifications and consolidating supplier relationships around high-performance formulations.
- Agriculture:Farm cooperatives and equipment leasing companies aggregate sufficient annual volumes to bypass traditional distribution channels.
- Manufacturing:Industrial plant maintenance departments prioritize cost predictability over environmental certification in the absence of regulatory pressure.
- Automotive:Limited penetration confined to specialty vehicle hydraulic systems with niche volume contribution.
Contract scale favors Agriculture; Forestry demonstrates the steepest specification upgrade trajectory.
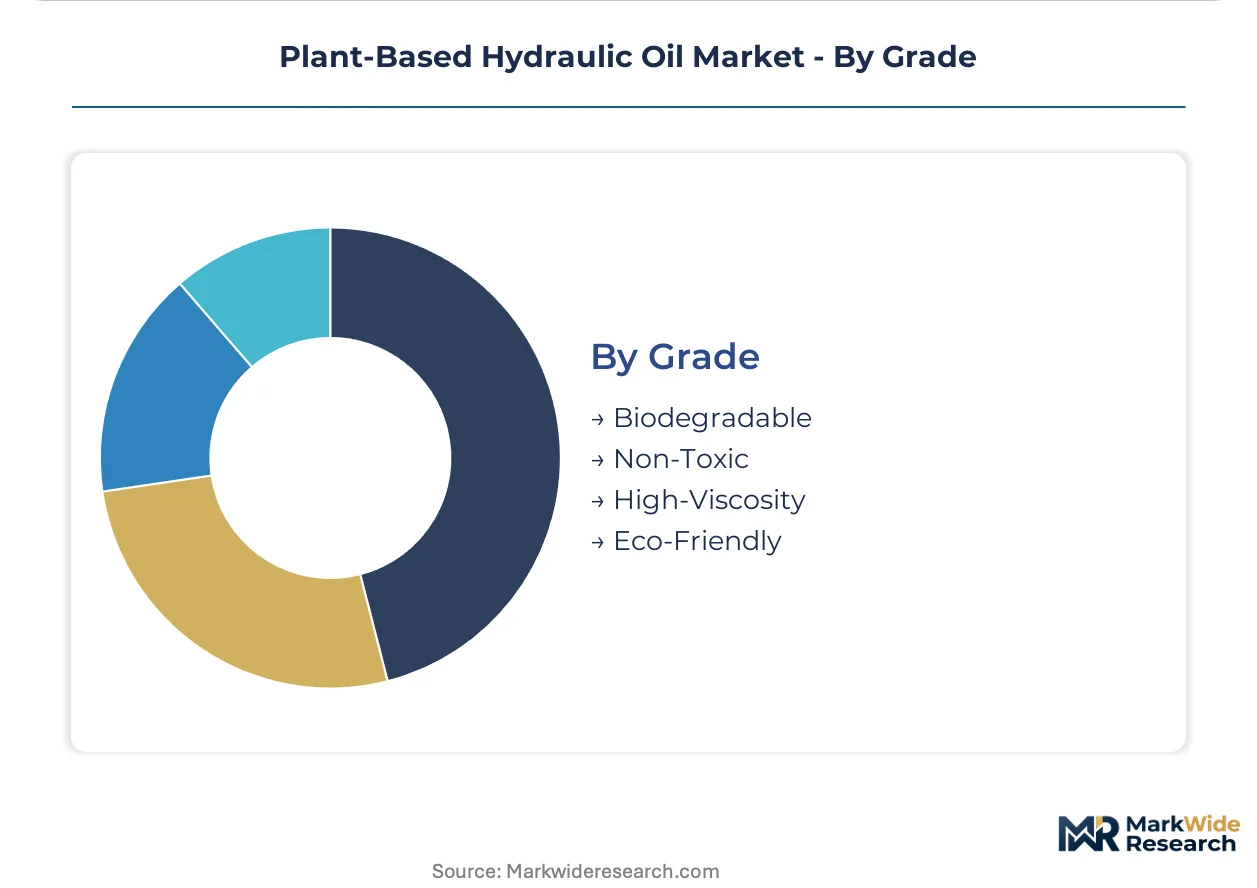
Grade:
Margin structure separates certified premium tiers from uncertified commodity positioning.
- Biodegradable:EU Ecolabel and EPA Safer Choice certification creates defensible pricing power for formulations meeting OECD 301B biodegradability thresholds. OEM factory-fill agreements in construction machinery embed these specifications as non-negotiable contract terms.
- High-Viscosity:ISO VG 68 grades serve heavy-load applications where thermal degradation resistance determines equipment uptime.
- Non-Toxic:Aquatic toxicity testing under REACH protocols supports marine and riparian operating environments.
- Eco-Friendly:Marketing designation without third-party certification competes on price in less regulated markets.
Revenue concentration sits with Biodegradable grades; High-Viscosity formulations are expanding most quickly in heavy machinery segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement specifications in Germany are compressing formulation standards across European supply chains. Fleet operators in forestry and construction machinery now embed biodegradable fluid mandates directly into vendor contracts. This demand concentration is reshaping where formulators invest certification resources.
Germany
Steep-slope harvester fleets in Bavaria and Baden-Württemberg face the EU's strictest operational fluid requirements near waterways. The EU Ecolabel and REACH compliance protocols force annual formulation recertification for hydraulic fluids used in public forest concessions. Equipment clusters around Stuttgart and Munich are negotiating pan-European supply agreements that bypass traditional lubricant distributors.
United States
Midwest agricultural equipment fleets and California construction machinery operators drive specification shifts toward EPA Safer Choice certified formulations. The EPA Safer Choice program and state-level procurement codes in California and New York embed biodegradability thresholds into public infrastructure contracts. Chicago and Los Angeles metropolitan equipment leasing companies aggregate sufficient annual volumes to negotiate direct manufacturer supply agreements.
India
Farm equipment cooperatives in Maharashtra and Gujarat are expanding procurement specifications to include environmental performance clauses for hydraulic systems operating near irrigation networks. The Bureau of Indian Standards is developing industrial lubricant eco-label frameworks that mirror EU Ecolabel structures. Manufacturing corridors around Pune and Ahmedabad are hosting pilot programs for biodegradable fluid deployment in state-subsidized agricultural machinery.
China
Construction machinery fleets in the Yangtze River Delta face tightening environmental enforcement for equipment operating near waterway protection zones. The Ministry of Ecology and Environment is drafting comparable eco-label standards for industrial lubricants under national dual carbon policy implementation. Shanghai and Suzhou industrial zones are testing biodegradable hydraulic formulations in high-pressure systems for port and inland waterway equipment.
Brazil
Sugarcane harvester fleets in São Paulo and Minas Gerais states operate under spill-sensitive mandates near watershed protection areas. National environmental licensing requirements for agricultural equipment are incorporating fluid biodegradability criteria into operating permits. Equipment concentration around Ribeirão Preto and Uberlândia is driving regional formulator investment in vegetable-derived base stock supply chains.
Plant-Based Hydraulic Oil Market Competitive Landscape
Swiss and German producers anchor the premium formulation tier; American specialists hold volume positions in agricultural equipment segments. The vendor structure concentrates around three to four integrated formulators with captive additive capabilities, while mid-scale regional blenders compete on price in less regulated markets. Strategic archetypes separate into vertically integrated oilseed processors, specialized biodegradable formulators, and diversified industrial lubricant conglomerates. Competitive moves concentrate on securing OEM factory-fill certification timelines and backward integration into oilseed crushing capacity.
Within the premium biodegradable tier, PANOLIN AG exemplifies Swiss manufacturing depth in high-performance formulations, while Fuchs Petrolub SE anchors European distribution scale through its established industrial lubricant network. Cargill occupies a position representing integrated oilseed supply chain control that reduces feedstock cost volatility for formulators. These three companies illustrate how competitive positioning increasingly depends on upstream raw material security rather than downstream formulation technology alone.
| Leading Market Players |
|---|
| Renewable Lubricants |
| PANOLIN AG |
| Fuchs Petrolub SE |
| Cargill |
| BASF SE |
| BioBlend |
| Houghton International |
| Lubriplate Lubricants |
| Hydro Safe |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU Ecolabel-certified biodegradable formulations and uncertified commodity vegetable oils manifests in both margin capture and procurement channel configuration. Premium grades command specification-locked factory-fill contracts with construction machinery OEMs, while commodity soy-based products compete on landed cost through agricultural distributor networks.
Pricing Analysis
Volume placements concentrate in cost-driven soybean oil tiers where farm cooperatives negotiate annual supply agreements; margin capture sits with castor-derived formulations serving German forestry equipment mandates. Price differentiation hinges on OECD 301B biodegradability certification and ISO VG 68 thermal stability performance. Pricing pressure stems from oilseed feedstock volatility compressing blender margins. Agricultural equipment fleets in the US Midwest exhibit highest price sensitivity; German construction machinery operators show lowest sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil suppliers facing EU sustainability certification barriers. Base stock production draws from soybean crushing capacity in the US Midwest, rapeseed processing in Germany, and castor seed networks in India. Supply chain risk centers on REACH additive registration delays blocking European market entry. Distribution runs through industrial lubricant distributors serving regional equipment dealers, with direct manufacturer contracting displacing traditional channels among large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and OEM factory-fill certification timelines are forcing mid-scale blenders toward exit or acquisition, consolidating competitive control among integrated formulators with captive additive capabilities.
For Market Incumbents: Cement approved supplier status with Komatsu and Volvo CE through accelerated field testing protocols for high-pressure hydraulic systems. Secure backward integration into oilseed crushing capacity to neutralize feedstock cost volatility threatening margin stability. For New Entrants and Emerging Players: Begin with India's Bureau of Indian Standards eco-label pilot programs in Maharashtra and Gujarat, where farm equipment cooperatives lack incumbent supplier relationships. Target marine hydraulic systems serving offshore vessels and inland waterway fleets with spill-sensitive operating mandates. For Investors and Strategic Acquirers: Re-rating potential sits with Swiss and German formulators holding EU Ecolabel certification breadth given accelerating OEM specification embedding. Long-term viability favors integrated players controlling both base stock supply and ashless additive formulation expertise. Monitor BIS framework finalization in India as inflection signal for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive soybean supply chains demonstrate feedstock cost predictability advantages over non-integrated competitors. |
| OEM Factory-Fill Certification Investment | PANOLIN AG's Swiss manufacturing depth secures construction machinery specification lock-in through extended field testing. |
| REACH Additive Registration Compliance | Fuchs Petrolub SE's established European industrial network absorbs regulatory burden that blocks mid-scale entrants. |
| Direct Fleet Contracting Bypass | German equipment leasing companies aggregate volumes enabling pan-European supply agreements disintermediating distributors. |
| Castor Oil Formulation Scale-Up | Ricinoleic acid thermal stability opens high-pressure construction machinery segments beyond commodity vegetable oil limits. |
Research Methodology
Independent corroboration across OEM procurement directors, lubricant formulator R&D heads, and agricultural fleet maintenance managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of diversified chemical conglomerates, and EU Ecolabel certification databases. Bottom-up volume estimates triangulated against top-down market sizing across feedstock, formulation, and end-use demand vectors.
Comparable-period anchoring to historical factory-fill contract renewal cycles and equipment replacement timelines structured the projection horizon. Segmentation dimensions modeled include base stock chemistry, viscosity grade tier, application pressure requirements, and regional regulatory cluster. CAGRs derived from equipment fleet growth rates, biodegradability mandate implementation schedules, and oilseed supply expansion trajectories. Forecast inputs incorporated OECD 301B certification adoption curves and REACH registration completion timelines.
Oilseed commodity price spikes, REACH additive restriction amendments, and OEM factory-fill specification reversals are the dominant revision risks. Forecasts reflect documented assumptions on regulatory enforcement intensity and equipment fleet electrification substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Naphthenic Acid Market