
 Composite Drums Market | 2026-2036
Composite Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Drums Market Outlook
North American drum fabricators is realigning capacity toward fiber-reinforced polymer lines to capture chemical sector contracts. Greif, Inc. leverages its integrated steel and composite manufacturing footprint to serve dual-material procurement strategies. Mauser Packaging Solutions anchors European operations with closed-loop reconditioning networks that extend drum lifecycle value. SCHUTZ GmbH & Co. KGaA differentiates through intermediate bulk container specialization in agricultural and food-grade applications.
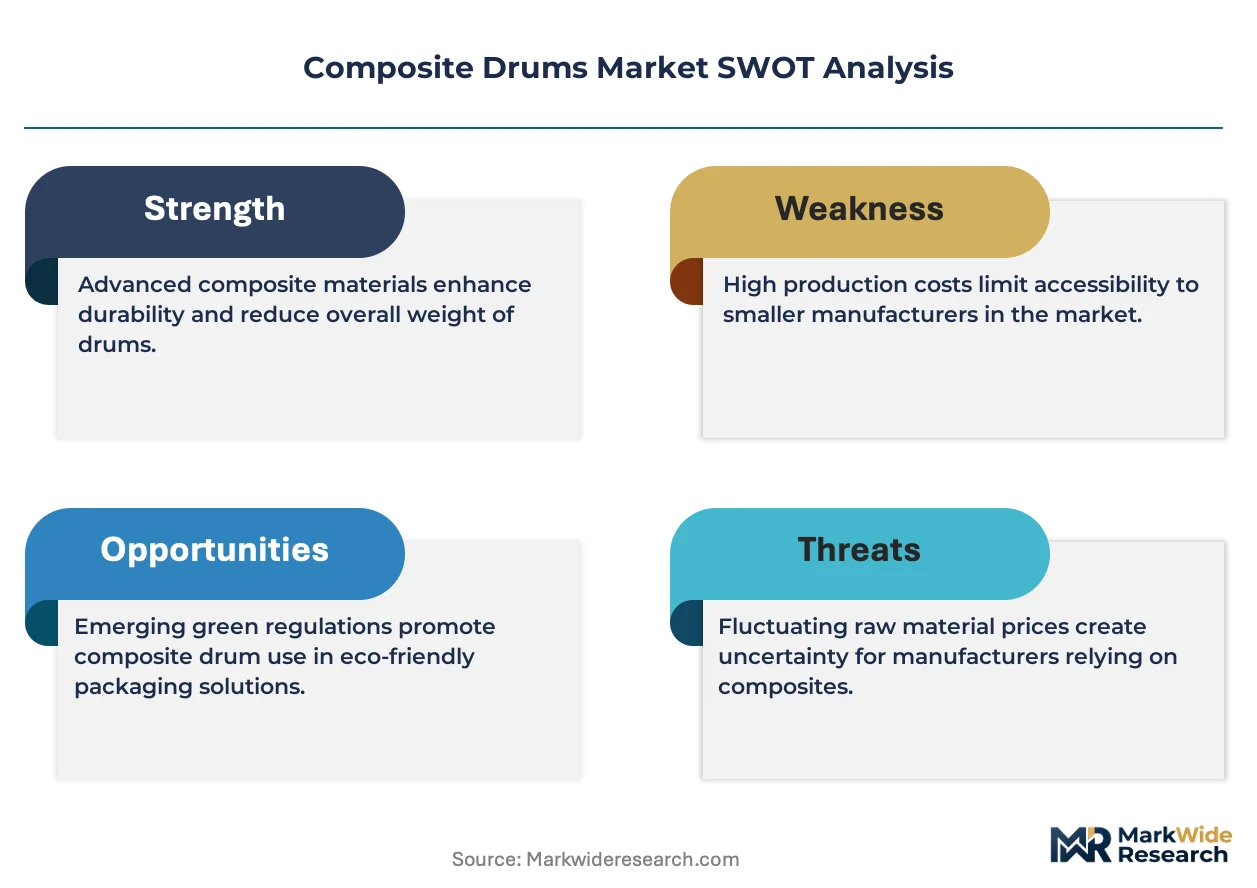
Composite drums are cylindrical industrial containers constructed from fiber-reinforced plastic, polyethylene, or hybrid material systems, typically manufactured through filament winding or rotational molding processes to achieve UN-certified performance ratings for hazardous liquid and solid containment. These vessels serve chemical, pharmaceutical, and food processing industries requiring corrosion resistance, reduced tare weight, and compliance with international dangerous goods transport codes. Tight head drums dominate hazardous chemical applications where vapor retention and leak-proof sealing command premium positioning, while open head configurations compete in solids handling and food ingredient segments where access and cleaning cycles matter. Fiber reinforced plastic materials are capturing share from steel in corrosive chemical service, though polyethylene maintains cost leadership in standard-duty pharmaceutical and food processing workflows.
EPA hazardous waste container standards and DOT 49 CFR shipping regulations govern material performance and testing protocols in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape chemical contact approvals and recyclability mandates across European markets. UN certification requirements for dangerous goods transport create structural barriers to entry that favor established testing relationships and multi-national compliance infrastructures. Stakeholders must monitor evolving state-level plastic packaging taxes and extended producer responsibility frameworks that could reshape total cost of ownership calculations between steel and composite alternatives.
Market Dynamics
UN certification requirements for dangerous goods transport are compressing supplier pools and forcing drum fabricators to maintain multi-jurisdictional testing relationships, fundamentally restructuring competitive access in hazardous chemical containment.
Growth Catalysts
- Fiber-reinforced polymer substitution:Chemical processors in Germany and the United States are systematically replacing steel drums with corrosion-resistant composite alternatives for acid and solvent handling.
- REACH compliance tightening:ECHA material specifications for hazardous goods transport are disqualifying legacy steel formulations from European chemical corridors.
- Domestic IBC manufacturing scale-up:India is expanding captive production capacity to serve pharmaceutical export corridors requiring UN-certified packaging.
Market Restraints
- Raw resin cost volatility:Polyethylene and epoxy feedstock prices fluctuate with crude oil indices, compressing margin predictability for rotational molders.
- Filament winding equipment concentration:High-performance fiber drum production depends on specialized machinery suppliers concentrated in Germany and Japan.
- Steel drum residual cost advantage:Standard-duty applications in bulk commodity chemicals retain incumbent metal packaging due to lower unit economics.
Strategic Opportunities
- Agricultural chemical packaging:Pesticide and fertilizer distributors in Brazil are converting to UV-stabilized polyethylene drums for field durability.
- Closed-loop reconditioning networks:Extended producer responsibility frameworks in France and Germany reward drum lifecycle extension services.
- Food-grade barrier coextrusion:Oxygen-scavenging liner technologies are opening dairy and edible oil applications previously closed to composites.
Industry Challenges
- UN certification timeline compression:Multi-drop testing protocols for new drum designs require 12-18 month approval cycles that delay product launches.
- Filament winding technician scarcity:Specialized composite manufacturing skills concentrate in aging workforces near legacy aerospace clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Drums Market |
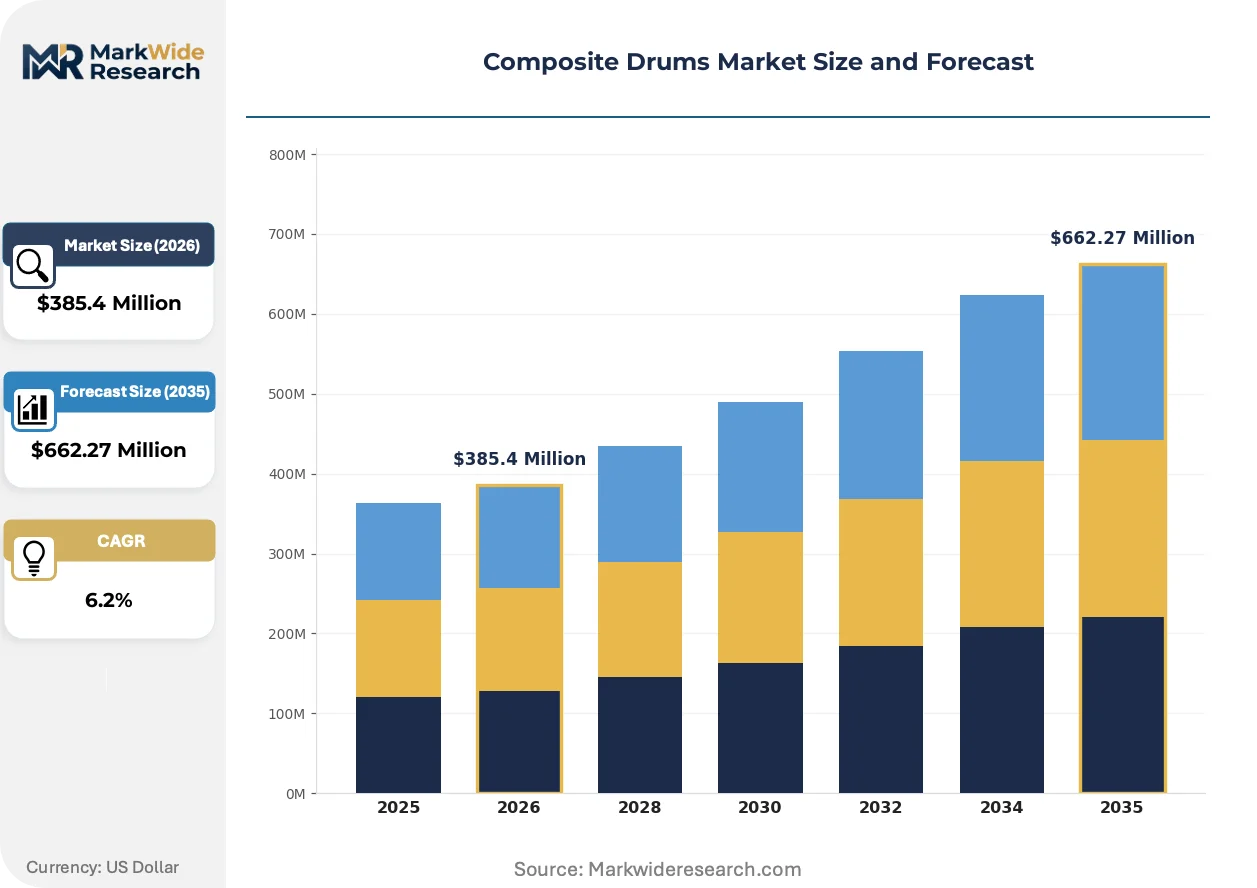
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head Drums, Tight Head Drums, Intermediate Bulk Containers, Vertical Drums Material: Polyethylene, Steel, Aluminum, Fiber Reinforced Plastic End User: Chemicals, Pharmaceuticals, Food & Beverage, Oil & Gas Capacity: 20 Liters, 50 Liters, 100 Liters, 200 Liters |
| Companies Covered | Greif, Inc., Mauser Packaging Solutions, SCHUTZ GmbH & Co. KGaA, Balmer Lawrie & Co. Ltd., Time Technoplast Ltd., Fibrestar Drums Ltd., Snyder Industries Inc., Sicagen India Ltd., ZBR Packaging Materials Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Drums Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to redefine drum performance specifications, with fabrication processes and supply chain configurations adapting to accommodate lighter-weight hazardous goods containment.
Hybrid fiber-metal drum construction is modularizing around standardized polyethylene liners wrapped with glass-reinforced polymer bands. Chemical distributors in the US Gulf Coast are piloting these systems for sulfuric acid transport. The approach is modularizing procurement decisions by separating liner replacement cycles from structural shell investments.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of legacy resin additives across European drum production. Compounders must validate alternative flame retardants and UV stabilizers through ECHA notification procedures. Agricultural chemical packaging in Eastern Europe faces the steepest compliance recertification burden.
Consolidated chemical distributors are unbundling drum procurement from logistics contracts, establishing direct specification authority over container performance tiers. Third-party reconditioning networks in Germany and the Netherlands are capturing service revenue previously embedded in supplier agreements. This pattern is most pronounced in specialty chemical segments where batch sizes favor flexible container sizing.
Composite Drums Market Segmentation
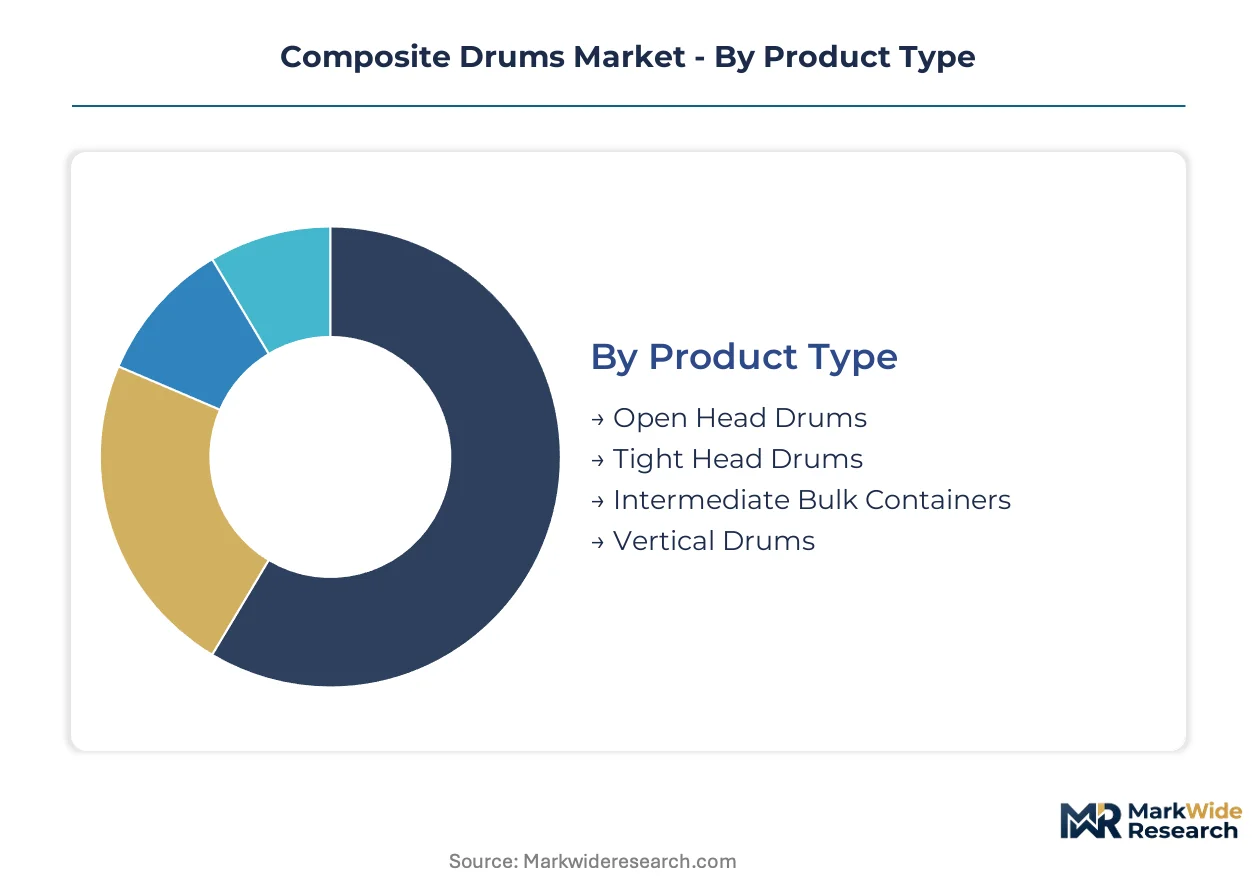
Drum specification tiers separate commodity chemical handlers from pharmaceutical and food-grade operators demanding certified performance. Material selection and head configuration choices cascade through UN certification pathways, reconditioning economics, and end-of-life recovery value.
Product Type:
Volume concentration sits with tight head configurations while premium positioning accrues to intermediate bulk systems.
- Tight Head Drums:Seamless construction with permanently attached lids achieves vapor-tight sealing required for UN-certified hazardous liquid transport. Chemical processors in Germany favor these for acid and solvent containment where leak-proof integrity commands specification priority.
- Intermediate Bulk Containers:Modular designs ranging from 275 to 330 gallons capture pharmaceutical export logistics through reduced handling costs per unit volume. Indian domestic manufacturing scale-up targets these systems for captive supply to active ingredient shippers.
- Open Head Drums:Removable lid configurations serve solids handling and food ingredient segments where access frequency and cleaning cycles matter more than vapor retention.
- Vertical Drums:Space-optimized profiles concentrate in warehousing-intensive operations where floor stacking density drives container geometry decisions.
Today's leader: Tight Head Drums. Tomorrow's challenger: Intermediate Bulk Containers.
Material:
Cost tiers separate polyethylene standard-duty applications from fiber-reinforced premium corrosion service.
- Fiber Reinforced Plastic:Glass-epoxy or glass-polyester composites achieve strength-to-weight ratios that displace steel in sulfuric acid and aggressive solvent handling. US Gulf Coast chemical distributors pilot hybrid banded systems here.
- Polyethylene:Rotational-molded high-density grades dominate pharmaceutical and food processing workflows where cost leadership outweighs extreme chemical resistance requirements.
- Steel:Carbon and stainless formulations retain bulk commodity chemical applications through residual unit cost advantage and established reconditioning infrastructure.
- Aluminum:Lightweight metal systems serve specialized aerospace and military logistics where tare weight reduction justifies material premium.
Current procurement gravity: Polyethylene. Steepest expansion trajectory: Fiber Reinforced Plastic.
End User:
Application maturity varies from saturated chemical commodity flows to emerging food-grade barrier requirements.
- Chemicals:Acid, solvent, and agrochemical handlers drive fiber-reinforced substitution as REACH Annex XVII restrictions disqualify legacy steel formulations from European corridors.
- Pharmaceuticals:Active ingredient and excipient manufacturers demand oxygen-scavenging liner technologies that open dairy and edible oil applications previously closed to composites.
- Food & Beverage:Barrier coextrusion advances are converting edible oil and dairy processors from tinplate to polyethylene-based systems with validated migration compliance.
- Oil & Gas:Lubricant and drilling fluid containment favors steel drum residual cost advantage in standard-duty bulk commodity flows.
Established revenue base: Chemicals. Gaining share fastest: Pharmaceuticals.
Capacity:
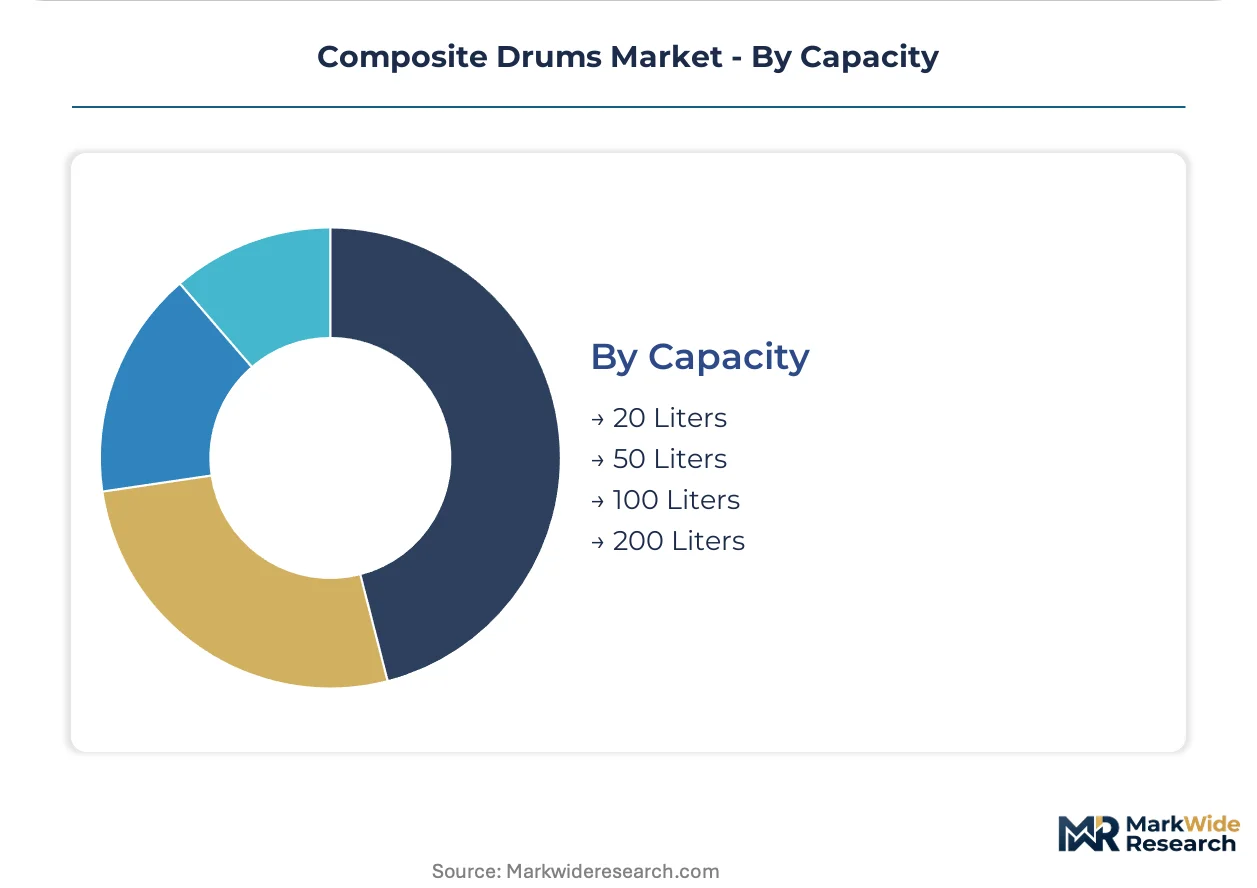
Customer type stratification separates laboratory-scale pharmaceutical operations from bulk chemical logistics.
- 200 Liters:Standard international shipping module captures chemical distributor procurement concentration and closed-loop reconditioning network economics.
- 100 Liters:Mid-scale configuration serves specialty chemical batch production where flexible container sizing matches variable order quantities.
- 50 Liters:Pharmaceutical pilot plant and sampling operations favor this scale for active ingredient handling with reduced contamination risk exposure.
- 20 Liters:Laboratory and clinical trial material containment drives specification for high-purity liner systems with validated cleaning protocols.
Dominant procurement scale: 200 Liters. Emerging specification growth: 50 Liters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing composite drum manufacturing toward jurisdictions with streamlined UN certification pathways and lower compliance overhead. Chemical processors in Germany and the United States absorb premium pricing for certified containers, while India scales domestic capacity to capture pharmaceutical export flows.
United States
EPA hazardous waste container standards and DOT 49 CFR shipping regulations govern material performance protocols for chemical distributors. Gulf Coast clusters around Houston and Baton Rouge pilot hybrid fiber-metal banded systems for sulfuric acid transport. Reconditioning networks in Texas and Louisiana extend drum lifecycle value through closed-loop service models.
Germany
REACH Annex XVII restrictions on persistent organic pollutants disqualify legacy steel formulations from chemical corridors. ECHA notification procedures force compounders to validate alternative flame retardants and UV stabilizers. Industrial concentration in North Rhine-Westphalia anchors filament winding expertise for high-performance fiber drum production.
India
Domestic manufacturing of intermediate bulk containers scales to serve pharmaceutical export corridors requiring UN-certified packaging. CDSCO alignment with international drug shipment standards drives specification authority toward domestic fabricators. Gujarat and Maharashtra host expanding rotational molding capacity for captive supply to active ingredient shippers.
China
GB standards for dangerous goods packaging create parallel certification requirements for export-oriented producers. Yangtze River Delta chemical clusters demand corrosion-resistant alternatives to steel for acid handling. Zhejiang and Jiangsu provinces concentrate filament winding equipment supply chains serving regional drum fabricators.
Brazil
ANVISA pharmaceutical packaging regulations and agricultural chemical distribution needs converge on UV-stabilized polyethylene drum specifications. São Paulo state anchors pesticide and fertilizer distributor conversion programs from metal to composite field containers. Southeast industrial corridors test barrier coextrusion technologies for edible oil applications.
Composite Drums Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and regional reconditioning services. The vendor base stratifies across integrated steel-composite manufacturers, pure-play fiber drum specialists, and reconditioning network operators. Three archetypes dominate: dual-material procurement strategists, closed-loop lifecycle service providers, and intermediate bulk container specialists. Consolidation pressure favors M&A activity targeting UN certification infrastructure and geographic expansion into pharmaceutical export corridors.
Among integrated packaging conglomerates, Greif, Inc. and Mauser Packaging Solutions exemplify dual-material positioning across steel and composite manufacturing footprints. SCHÜTZ GmbH & Co. KGaA anchors the intermediate bulk container specialization archetype through agricultural and food-grade application focus. These three represent distinct competitive vectors: procurement flexibility, lifecycle service integration, and volume-scale IBC configuration expertise.
| Leading Market Players |
|---|
| Greif, Inc. |
| Mauser Packaging Solutions |
| SCHÜTZ GmbH & Co. KGaA |
| Balmer Lawrie & Co. Ltd. |
| Time Technoplast Ltd. |
| Fibrestar Drums Ltd. |
| Snyder Industries Inc. |
| Sicagen India Ltd. |
| ZBR Packaging Materials Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII compliance gates qualified supply access and premium-tier pricing power, as ECHA-mandated reformulation of resin additives forces compounders through costly notification procedures that smaller molders cannot absorb. This environmental mandate stratifies the vendor base between certified premium suppliers and excluded commodity producers.
Pricing Analysis
Distributor margins compress as consolidated chemical buyers unbundle drum procurement from logistics contracts and establish direct specification authority. Three-tier pricing structure across UN-certified premium, standard industrial, and economy commodity levels separates fiber-reinforced systems from polyethylene and residual steel alternatives. Pricing pressure stems from raw resin cost volatility tracking crude oil indices, with rotational molders facing margin unpredictability. Specialty chemical processors show least price sensitivity due to batch-size flexibility and contamination risk exposure, while bulk commodity chemical handlers retain steel drums for unit cost advantage.
Supply Chain Analysis
Freight cost differentials between filament winding equipment concentrated in Germany and Japan versus rotational molding capacity scaling in India and China shape total landed cost structures. Raw material flows draw from epoxy and glass fiber suppliers in Germany, polyethylene resin producers in the US Gulf Coast, and HDPE compounders in India. Single-source vulnerability concentrates in specialized filament winding machinery where technician scarcity near legacy aerospace clusters limits expansion. Distribution runs through chemical distributor networks in Germany and the Netherlands, third-party reconditioning operators, and direct OEM contracts for pharmaceutical exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Germany and ECHA notification burdens create 15-20 point cost differentials against Indian domestic manufacturing scaling for pharmaceutical export corridors.
For Market Incumbents: Deploy closed-loop reconditioning network expansion to capture extended producer responsibility revenue streams in France and Germany. Anchor filament winding technician training programs near North Rhine-Westphalia industrial clusters to counter workforce aging. Defend against Indian domestic IBC manufacturers by accelerating hybrid fiber-metal banded system pilot programs with US Gulf Coast sulfuric acid distributors.
For New Entrants and Emerging Players: Capture agricultural chemical packaging conversion in Brazil where ANVISA regulations and field durability requirements converge on UV-stabilized polyethylene specifications. Target barrier coextrusion technology licensing for dairy and edible oil applications previously closed to composites. Penetrate through food-grade oxygen-scavenging liner partnerships with pharmaceutical excipient manufacturers seeking validated migration compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play rotational molders lacking UN certification infrastructure but holding pharmaceutical customer relationships. Long-term viability centers on regulatory compliance moats widening through ECHA notification backlogs and UN testing timeline compression. Watch for CDSCO alignment completion with international drug shipment standards as inflection signal for Indian domestic fabricator consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | ECHA notification control reduces reformulation risk exposure for REACH Annex XVII compliance. |
| Hybrid Fiber-Metal Banding Pilot Expansion | US Gulf Coast sulfuric acid distributors validate modular liner-shell separation economics. |
| Closed-Loop Reconditioning Network Buildout | French and German extended producer responsibility frameworks reward lifecycle extension services. |
| Food-Grade Barrier Coextrusion Licensing | Oxygen-scavenging liner technologies open dairy applications to polyethylene drum conversion. |
| Filament Winding Technician Training Hubs | North Rhine-Westphalia aerospace clusters supply scarce composite manufacturing skills. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chemical plant managers, pharmaceutical procurement leads, drum reconditioning network operators, and ECHA regulatory affairs specialists with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated packaging conglomerates, and UN dangerous goods testing protocol documentation. Bottom-up volume modeling across material grades and head configurations triangulated against top-down chemical sector packaging spend estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand patterns and post-regulatory-shift reconfiguration phases. The analytical framework modeled segmentation across tight head, open head, and intermediate bulk container formats; fiber-reinforced plastic, polyethylene, steel, and aluminum materials; and chemical, pharmaceutical, food, and oil and gas end-use industries. CAGRs derived from weighted average of volume trajectories and value capture per unit shifts, incorporating filament winding capacity expansion timelines and REACH Annex XVII compliance recertification cycles as industry-specific inputs.
Underlying measurement precision varies by segment; tight head drum and fiber-reinforced plastic categories carry tighter precision than emerging barrier coextrusion applications. Forecasts reflect assumptions about ECHA notification processing speeds, resin feedstock price correlation with crude indices, and Indian pharmaceutical export growth trajectories. Stakeholders should weight assumptions against their own operating context and regulatory compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Epoxy Composite Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Composites Testing Market
Composite Materials
Laminar Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
Plastic Composites Market
Composite Materials
Structural Core Materials Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Reinforced Nonwoven Plastics Market