
 Ballistic Material Market | 2026-2036
Ballistic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Material Market Insights
The NIJ 0101.07 standard revision is pivoting the cost-of-entry calculus for armor suppliers by mandating new threat-level classifications and rigorous backface deformation testing. DuPont leverages its aramid fiber heritage to sustain leadership in soft armor substrates against emerging UHMWPE rivals. Teijin Limited anchors its position through integrated para-aramid production from polymer to finished fabric. Honeywell International Inc. competes on Spectra fiber purity and controlled molecular weight distribution in polyethylene tapes.
Ballistic materials encompass engineered fibers, ceramics, metals, and composites designed to absorb, disperse, or defeat kinetic energy from projectiles and fragmentation, typically measured against V50 ballistic limit or backface signature thresholds in standardized testing. Aramid fibers and ultra-high molecular weight polyethylene dominate soft armor applications where areal density below five kilograms per square meter governs wearability, while ceramic composites lead hard armor plates against armor-piercing threats. The form dimension shows laminates capturing premium value in multi-hit capable systems, whereas plates concentrate volume in military vehicle integration. Aerospace shielding remains nascent but commands outsized margins due to qualification cycles and material traceability requirements.
The United States Department of Defense, NATO STANAG working groups, and India's DRDO establish the tripartite regulatory architecture governing threat specification, interoperability, and local content mandates. NIJ certification governs law enforcement procurement access in the United States, while STANAG 4569 defines vehicle protection levels for coalition interoperability. Stakeholders must monitor evolving drone-borne threat profiles and corresponding updates to testing protocols that could obsolete current material configurations before end-of-design-life.
Market Dynamics
Defense procurement cycles are compressing as ministries accelerate armor modernization programs in response to evolving drone-borne threats and revised threat-level specifications. This structural pressure is forcing material suppliers to recertify product portfolios against higher performance thresholds while maintaining cost discipline.
Growth Catalysts
- NIJ 0101.07 Recertification Mandate:United States law enforcement agencies must upgrade to higher threat-level classifications, creating immediate replacement demand for certified suppliers.
- India's Defense Indigenization:Domestic production mandates under the country's defense procurement policies are redirecting material sourcing from imports to local aramid and UHMWPE manufacturing.
- Drone Fragmentation Threats:Emerging unmanned aerial vehicle attack profiles are expanding vehicle armor requirements beyond traditional ballistic specifications.
Market Restraints
- High-Purity Polymer Feedstock Concentration:Ultra-high molecular weight polyethylene production depends on specialized catalyst systems controlled by a limited supplier base in Western Europe and North America.
- Backface Deformation Testing Costs:The NIJ 0101.07 standard's rigorous deformation protocols require expensive ballistic gelatin and high-speed imaging infrastructure that smaller suppliers cannot fund.
- Ceramic Tile Brittleness:Alumina and silicon carbide plates suffer catastrophic failure modes under multi-hit scenarios, constraining their adoption in wearable systems despite superior areal density.
Strategic Opportunities
- Aerospace Shielding Qualification:Commercial aviation and spacecraft applications remain underpenetrated due to extended certification timelines, creating first-mover margin advantages for qualified suppliers.
- Hybrid Soft-Hard Systems:Convergence of UHMWPE unidirectional laminates with ceramic strike faces enables lighter multi-hit protection for dismounted infantry.
- NATO STANAG Harmonization:Coalition vehicle protection standardization is creating cross-border procurement pools that reward suppliers with multi-national certification.
Industry Challenges
- Ballistic Engineer Scarcity:Specialized expertise in V50 testing protocols and backface signature analysis concentrates at legacy defense contractors, constraining new market entry.
- End-to-End Traceability Infrastructure:Military-grade material qualification requires lot-level fiber origin documentation that many suppliers cannot implement without significant information technology investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Material Market |
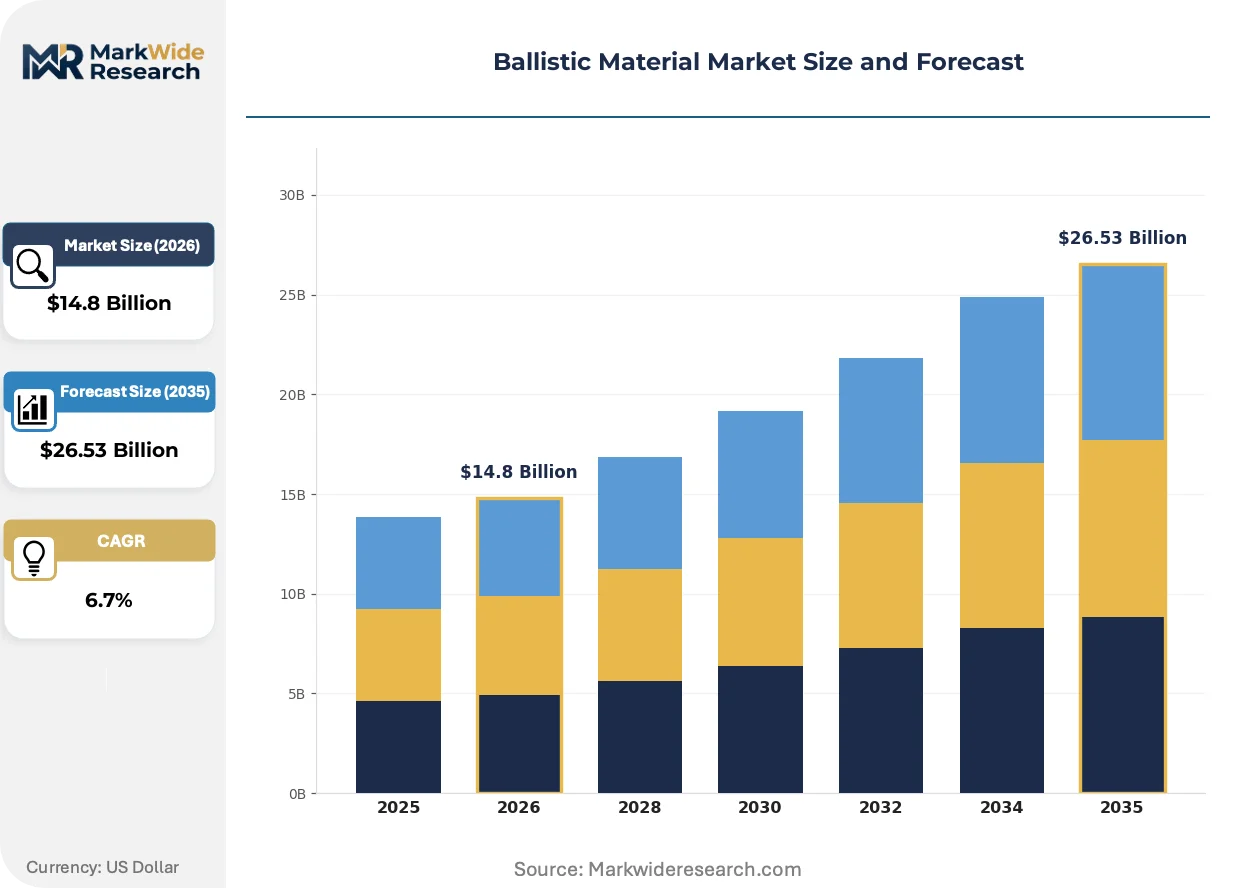
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aramid Fibers, Ultra-High Molecular Weight Polyethylene, Ceramic Composites, Steel Alloy, Carbon Nanotubes Form: Sheets, Fibers, Plates, Laminates, Foams Application: Military Armor, Law Enforcement, Personal Protection, Aerospace Shielding, Riot Gear End User: Defense Forces, Security Agencies, Private Security Firms, Aerospace Manufacturers, Correctional Facilities |
| Companies Covered | Honeywell International Inc., DuPont, Teijin Limited, BAE Systems, Avient Corporation, Morgan Advanced Materials, 3M, Saint-Gobain, TenCate Protective Fabrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Material Market Trends and Innovations
Material science advances are compressing the performance gap between aramid and polyethylene fiber systems while ceramic-matrix composites gain traction in vehicle applications. These developments are reshaping supplier positioning across soft and hard armor segments.
Non-oxide ceramic matrices, particularly boron carbide and silicon carbide reinforced with carbon fiber, are integrating into next-generation vehicle armor systems. Military procurement offices in NATO member states are specifying these materials for crew protection modules. This integration is enabling weight reductions exceeding fifteen percent compared to traditional alumina tiles while maintaining multi-hit integrity against armor-piercing threats.
REACH regulation amendments in the European Union are restricting per- and polyfluoroalkyl substances used in water-repellent ballistic fabric treatments. Manufacturers serving European defense ministries must reformulate protective coatings without degrading moisture management performance. Suppliers with established fluorine-free chemistry pipelines are capturing specification advantages in French and German tender processes.
Buyer preference is migrating toward integrated system procurement rather than discrete material supply. Defense ministries now require armor suppliers to deliver finished plate carriers and vehicle appliqué kits with embedded sensing for impact detection. This pattern is most visible in United States Special Operations Command programs, where end-users demand lifecycle support contracts bundling material, fabrication, and field maintenance.
Ballistic Material Market Segmentation
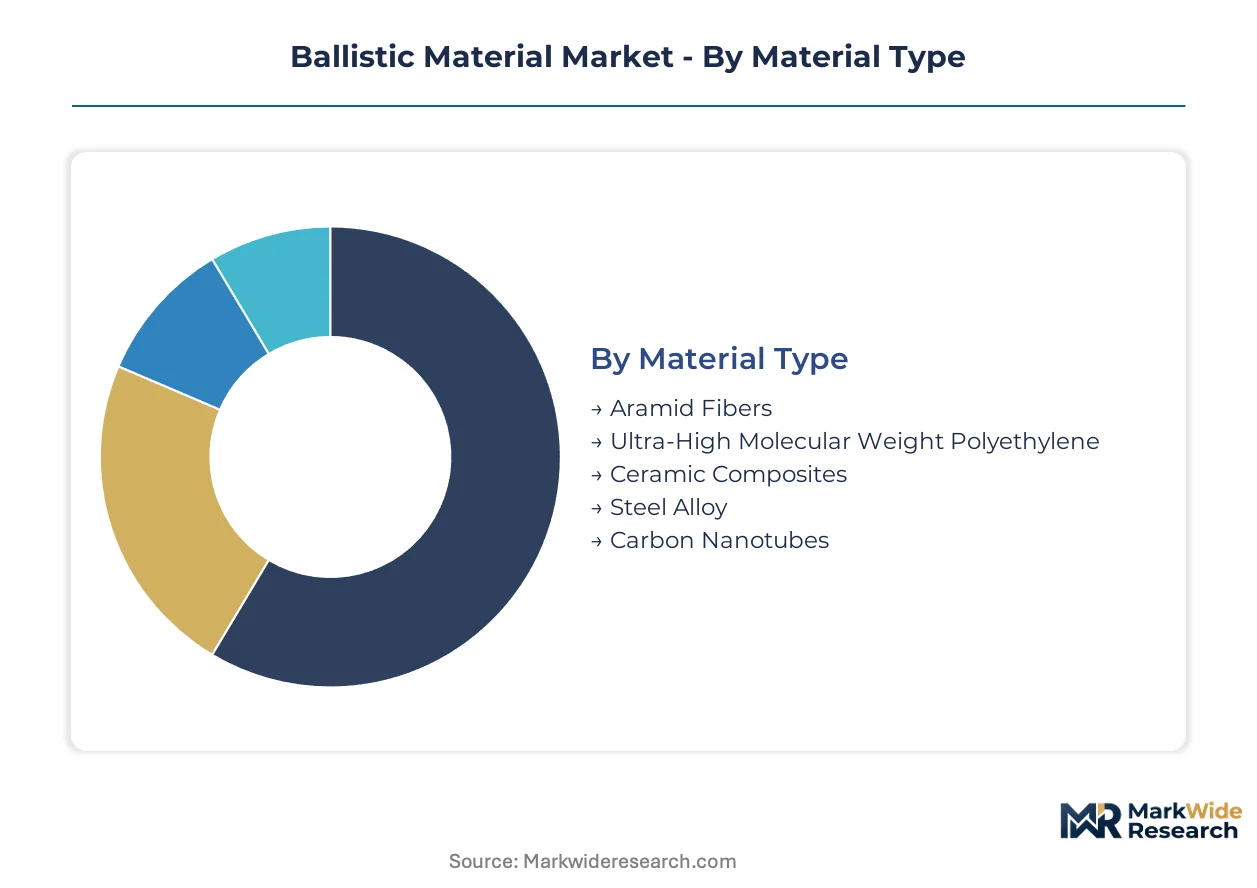
Ballistic material procurement decisions cascade across material chemistry, physical form, and end-use specifications. Each segmentation dimension carries distinct certification requirements and margin structures that reshape supplier competitiveness.
Material Type:
NIJ 0101.07 recertification cycles are forcing defense ministries to reassess fiber-to-ceramic trade-offs against higher threat-level thresholds.
- Aramid Fibers:Para-aramid polymers deliver tensile strength exceeding 3 GPa with inherent flame resistance for soft armor vests. India's DRDO indigenization mandates are redirecting procurement toward domestic aramid spinning capacity under defense procurement preference rules.
- Ultra-High Molecular Weight Polyethylene:UHMWPE tapes achieve specific strength metrics superior to aramid at 40% lower areal density, though thermal degradation above 130°C constrains vehicle engine compartment placement. United States Special Operations Command specifications favor UHMWPE for maritime operations where buoyancy matters.
- Ceramic Composites:Alumina and silicon carbide strike faces defeat armor-piercing rounds through fracture cone formation; NATO STANAG 4569 Level 4 vehicle specifications drive multi-hit ceramic tile procurement.
- Steel Alloy:Rolled homogeneous armor retains cost advantage for vehicle hull base layers despite weight penalties exceeding 50% versus ceramic alternatives.
- Carbon Nanotubes:Multi-walled nanotube dispersions remain pre-commercial for ballistic textiles, with pilot production concentrated at United States national laboratory spinouts.
Volume placements concentrate in aramid fibers; the faster expansion belongs to ultra-high molecular weight polyethylene.
Form:
Cost tier differentiation separates commodity fiber supply from value-added laminate fabrication requiring ballistic press infrastructure.
- Sheets:Woven aramid and UHMWPE fabrics ship in roll form for in-house armor fabrication by tier-one defense contractors. French Ministry of Armed Forces procurement bundles sheet supply with domestic weaving requirements.
- Fibers:Spun para-aramid and gel-spun polyethylene filaments serve as upstream inputs for both textile weavers and unidirectional tape manufacturers. Germany's KBA vehicle certification protocols reference fiber denier specifications for automotive armor integration.
- Plates:Monolithic ceramic and composite plates dominate hard armor inserts for military plate carriers; backface deformation testing per NIJ 0101.07 Level III mandates governs United States law enforcement procurement.
- Laminates:Cross-plied unidirectional UHMWPE layers bonded under heat and pressure deliver multi-hit capability with areal density below 4 kg/m² for dismounted infantry systems.
- Foams:Metallocene polyolefin and phenolic foams absorb blast overpressure in vehicle hull cavities; United Kingdom Ministry of Defence specifications for protected mobility vehicles include foam-backed armor appliqué.
Revenue margins peak in laminates; foams gain share fastest in vehicle blast protection retrofits.
Application:
Customer type segmentation reveals divergent certification burdens between military-grade qualification cycles and commercial security procurement.
- Military Armor:Platform-integrated protection for ground vehicles, rotorcraft, and naval vessels demands STANAG 4569 or equivalent national ballistic standards. India's Army Design Bureau issues qualitative requirements that specify indigenous content minimums for armor steel and ceramic tiles.
- Law Enforcement:NIJ 0101.07 compliance governs United States police department vest procurement, with special threat testing protocols for rifle-rated plates. The FBI's Ballistic Research Facility maintains reference ammunition for certification consistency.
- Personal Protection:Civilian concealed carry and executive protection markets favor flexible soft armor with moisture-wicking carriers; European REACH restrictions on PFAS treatments force coating reformulations.
- Aerospace Shielding:Commercial aviation and spacecraft applications require FAA or EASA material flammability certification alongside ballistic performance; qualification timelines extend beyond 24 months.
- Riot Gear:Helmets, shields, and limb protectors blend impact absorption with flame resistance; French CRS and German Bereitschaftspolizei specifications drive polycarbonate and aramid composite demand.
Procurement volume concentrates in military armor; aerospace shielding expands most quickly as satellite constellation deployment accelerates.
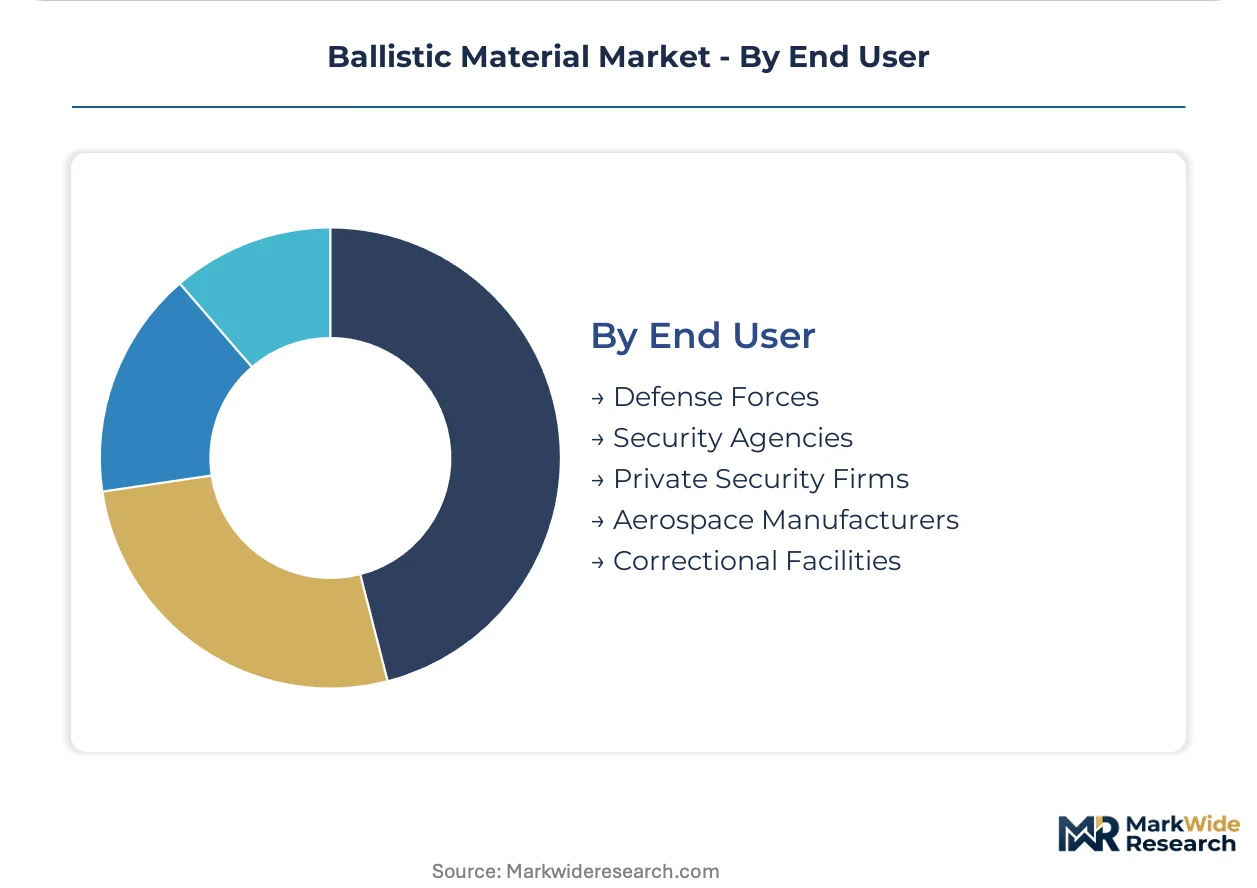
End User:
Supply concentration varies sharply between concentrated defense ministry procurement and fragmented private security purchasing.
- Defense Forces:National military procurement offices aggregate demand through multi-year framework agreements; United States Defense Logistics Agency manages body armor stockpiles with vendor-managed inventory clauses.
- Security Agencies:Federal and state police forces in Germany, France, and Italy operate decentralized procurement with national reference standards; BSI Kitemark and AFNOR certification govern product eligibility.
- Private Security Firms:Corporate executive protection and cash-in-transit operators purchase through distributors; price sensitivity favors imported ceramic plates over domestic aramid vests in cost-conscious markets.
- Aerospace Manufacturers:Boeing, Airbus, and satellite prime contractors specify shielding materials with full traceability documentation; AS9100 quality system certification gates supplier qualification.
- Correctional Facilities:Prison systems in the United States and United Kingdom procure stab-resistant vests with lower ballistic ratings; procurement prioritizes durability and cleaning protocol compatibility over weight minimization.
Contract value concentrates in defense forces; private security firms represent the steepest expansion trajectory as executive protection markets professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's western development corridors concentrate new aramid and UHMWPE spinning capacity. Defense procurement mandates in these zones redirect material flows toward domestic military supply chains. Tax incentives for capital-intensive fiber production accelerate facility commissioning timelines.
United States
Department of Defense modernization programs drive demand for next-generation body armor and vehicle protection systems. The NIJ 0101.07 standard revision compels law enforcement agencies to recertify vest procurement against higher threat levels. South Carolina's Upstate region hosts consolidated ballistic fiber weaving and laminate pressing operations serving Special Operations Command requirements.
India
Defense indigenization mandates under the Defence Acquisition Procedure redirect armor material sourcing from imports to domestic production. BIS certification requirements govern local content thresholds for aramid and ceramic tile procurement. Tamil Nadu's Oragadam industrial belt anchors new para-aramid spinning capacity under DRDO technology transfer agreements.
Germany
NATO STANAG 4569 harmonization creates cross-border vehicle armor procurement pools for coalition interoperability. KBA vehicle certification protocols specify fiber denier and ceramic multi-hit performance standards. Bavaria's Munich-Augsburg corridor concentrates composite armor R&D facilities serving Leopard platform upgrade programs.
China
Western development initiatives under the dual carbon goals subsidize advanced materials production in interior provinces. GB standards for ballistic resistance govern domestic law enforcement and paramilitary procurement specifications. Sichuan-Chongqing's Chengdu cluster hosts integrated UHMWPE gel-spinning and unidirectional tape manufacturing for regional defense supply.
United Kingdom
Ministry of Defence protected mobility vehicle programs specify blast-resistant foam-backed armor appliqué for retrofitted platforms. REACH regulation amendments restrict PFAS treatments in water-repellent fabric coatings, forcing reformulation compliance. Midlands manufacturing corridors around Birmingham maintain ceramic tile pressing and vehicle integration capabilities.
Ballistic Material Market Competitive Landscape
North American chemical conglomerates anchor one tier through integrated polymer-to-fiber production; Japanese and European specialists hold differentiated positions in high-performance para-aramid and ceramic-matrix systems. The supplier base concentrates around three strategic archetypes: diversified materials conglomerates with captive fiber production, pure-play fiber specialists controlling molecular weight distribution, and system integrators bundling materials with finished armor fabrication. Competitive dynamics center on backward integration into polymer feedstock and multi-national certification acquisition for NATO procurement access.
Within the diversified conglomerate tier, Honeywell International Inc. and DuPont occupy positions defined by decades of fiber chemistry heritage and defense procurement relationships. Teijin Limited exemplifies the integrated specialist archetype through captive para-aramid production from polymer synthesis to finished fabric. These three anchors represent the competitive fault lines between polyethylene and aramid fiber systems, with each positioning around distinct thermal performance and areal density trade-offs in soft armor applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| DuPont |
| Teijin Limited |
| BAE Systems |
| Avient Corporation |
| Morgan Advanced Materials |
| 3M |
| Saint-Gobain |
| TenCate Protective Fabrics |
| Others |
Pricing and Supply Chain Analysis
Captive polymer-to-fiber production anchors supplier pricing power in ballistic materials, with DuPont, Teijin, and Honeywell controlling molecular weight distribution and spinning purity that downstream weavers cannot replicate. This backward integration into specialized catalyst systems and gel-spinning infrastructure creates cost advantages that resist price erosion even as NIJ recertification demands intensify.
Pricing Analysis
Lead-time premiums command substantial markups in ballistic material procurement, with United States Special Operations Command contracts paying premiums for sub-90-day delivery of NIJ 0101.07-certified laminates while spot inventory of uncertified fiber trades at discounts. Three-tier pricing structure across certified military-grade, law enforcement-compliant, and commercial security tiers separates buyers by documentation burden and testing rigor. Cost compression in law enforcement vests intensifies as municipal budget constraints force procurement officers toward multi-year framework agreements with volume discounts. Private security firms exhibit highest price sensitivity, prioritizing imported ceramic plates over domestic aramid systems when specifications permit.
Supply Chain Analysis
Certification gating restricts qualified supplier pools to fiber producers with documented lot-level traceability and ballistic gelatin testing infrastructure, concentrating tier-one supply among United States, Japanese, and Western European manufacturers. Raw material dependencies center on high-purity UHMWPE resin from specialized catalyst systems, para-aramid polymer intermediates, and boron carbide ceramic precursors. Single-source vulnerability in metallocene polyolefin foam supply for vehicle blast protection creates exposure to United Kingdom Ministry of Defence specification changes. Distribution runs through defense ministry procurement offices with vendor-managed inventory clauses, bypassing traditional distributor networks for military-grade material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ballistic Material Market functions as a cost-of-compliance arena where NIJ 0101.07 recertification mandates erect capital barriers that favor incumbent suppliers with existing testing infrastructure and defense procurement relationships.
For Market Incumbents: Acquire ballistic testing facilities and backface deformation imaging infrastructure to internalize certification costs that smaller competitors cannot fund. Expand unidirectional laminate pressing capacity in South Carolina's Upstate region to service Special Operations Command consolidated procurement. Threats from UHMWPE thermal degradation constraints in vehicle engine compartments create openings for aramid fiber positioning in next-generation platforms. For New Entrants and Emerging Players: Capture aerospace shielding qualification opportunities where 24-month FAA and EASA certification timelines deter established defense suppliers focused on faster-turn military contracts. India's Tamil Nadu Oragadam industrial belt offers penetrable entry through DRDO technology transfer agreements for domestic aramid spinning. Go-to-market positioning should emphasize fluorine-free water-repellent coatings ahead of European REACH enforcement to secure French and German tender advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in defense conglomerate acquisition of pure-play fiber specialists lacking system integration capabilities. Long-term viability favors suppliers with demonstrated multi-national NATO STANAG certification and captive polymer production. Watch for drone-borne threat specification updates as the inflection signal that could obsolete current material configurations before design-life expiration.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ 0101.07 Recertification Investment | Defense ministry procurement access requires certified backface deformation testing infrastructure that smaller rivals cannot fund. |
| Backward Integration into Polymer Feedstock | Captive UHMWPE resin production through specialized catalyst systems insulates margin from Western European supplier concentration. |
| Multi-National NATO Certification Acquisition | STANAG 4569 qualification unlocks cross-border vehicle armor procurement pools in Germany, France, and coalition partners. |
| Fluorine-Free Coating Pipeline Development | European REACH PFAS restrictions favor suppliers with reformulated water-repellent chemistry ahead of enforcement deadlines. |
| Integrated System Procurement Capability | United States Special Operations Command lifecycle support contracts bundle material, fabrication, and field maintenance into single-vendor relationships. |
Research Methodology
Independent corroboration across ballistic testing laboratory directors, defense procurement officers at United States Defense Logistics Agency, and composite armor R&D heads in Germany's Munich-Augsburg corridor underwrites the qualitative findings. Primary fieldwork with plant managers at para-aramid spinning facilities, technical directors at ceramic tile pressing operations, and channel partners supplying private security distributors combined with secondary validation from NIJ certification registries, NATO STANAG working group documentation, and BIS indigenization compliance records. Bottom-up fiber volume estimates and top-down defense budget allocation analysis provided triangulation checks across the analysis window.
Comparable-period anchoring to historical NIJ standard revision cycles and India's Defence Acquisition Procedure amendment timelines structured the forecast framework. Segmentation modeling spanned material chemistry, physical form, application tier, and end-user concentration across the projection horizon. CAGRs derived from defense ministry modernization program announcements and law enforcement agency vest replacement schedules. Industry-specific inputs included V50 ballistic limit testing data trends and backface signature threshold evolution under revised threat specifications.
The model holds under stable defense procurement budget trajectories and continued NIJ 0101.07 enforcement; deviation in drone-borne threat specification updates or REACH PFAS restriction acceleration would shift material demand mix and supplier qualification timelines. Forecasts reflect assumptions regarding certification backlog duration and polymer feedstock capacity expansion cadence. A model refresh is warranted upon material change in NATO STANAG harmonization progress or India's domestic spinning capacity commissioning rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Europe Green Steel Market