
 Plastic Recycling Machine Market | 2026-2036
Plastic Recycling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Recycling Machine Market Intelligence
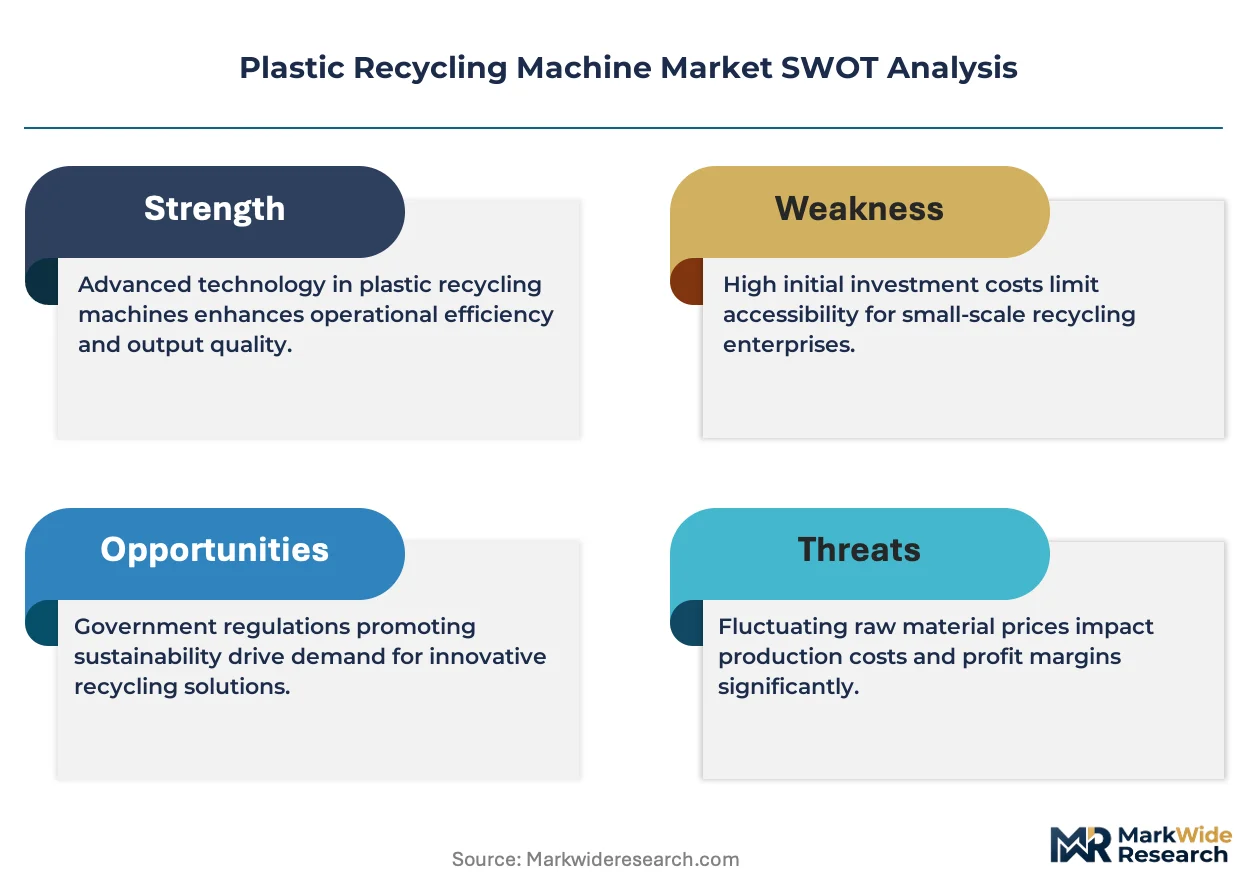
The push for food-grade recycled materials is bifurcating the market between standard and high-purity processing lines. EREMA leverages its expertise in advanced extrusion and filtration systems to serve the high-purity segment. ByFusion Global specializes in transforming difficult-to-recycle plastics into construction materials, occupying a unique niche. Meanwhile, Neowaste positions itself with modular systems catering to both small-scale recyclers and large waste management firms.
A plastic recycling machine is a piece of industrial equipment designed to convert plastic waste into reusable pellets, flakes, or powders. These systems often integrate multiple functions, including shredding materials to a uniform size, washing contaminants, and melting plastic for extrusion. Mechanical technology remains the dominant process, valued for its efficiency in handling PET and HDPE streams. Within the equipment portfolio, extruders and granulators represent the core components for most recycling facilities, defining throughput capacity.
Regulatory frameworks are a primary catalyst for equipment investment. The EU Green Deal mandates recycled content in products, while the US EPA's National Recycling Strategy encourages domestic processing. China's policies under its dual carbon goals promote internal circular economy development, restricting scrap imports. The critical decision for operators involves balancing investment in single-polymer lines against flexible systems for mixed waste streams.
Market Dynamics
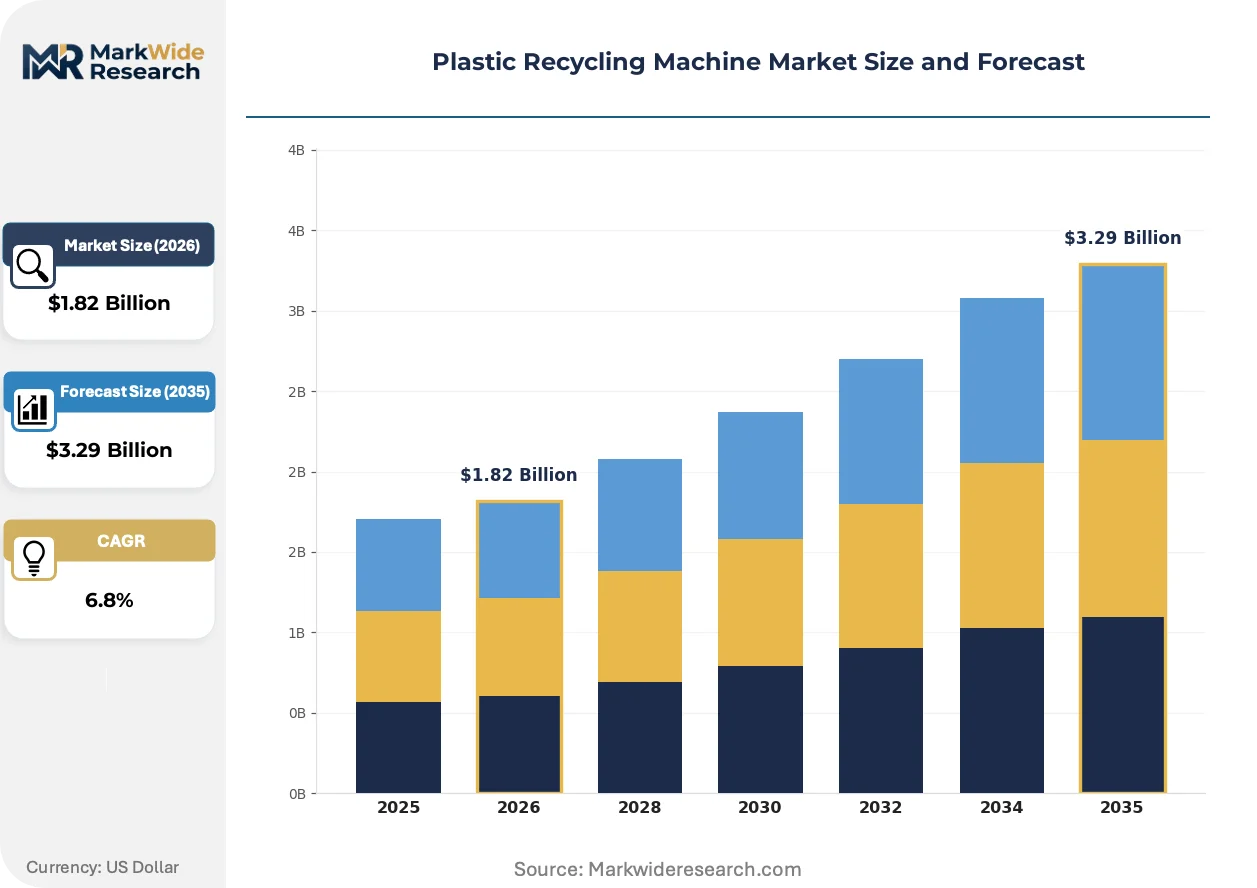
The market's expansion is fundamentally tied to intensifying regulatory mandates for circular economy practices. Policies like the EU Green Deal and China's dual carbon goals compel investment in advanced processing infrastructure to meet recycled content targets.
Growth Catalysts
- EU Green Deal Mandates:Regulations requiring recycled content in PET bottles directly stimulate demand for high-purity systems across European Union members.
- Packaging Sector Procurement:CPG company demand for food-grade rPET to meet sustainability targets drives investment in advanced wash lines and extruders.
- Advanced Sorting Technology:Integrating optical sorters improves flake purity, enabling recyclers to produce higher-value materials and access premium end markets.
Market Restraints
- Feedstock Contamination:Inconsistent quality and high contamination in post-consumer waste increase operational costs and require sophisticated washing and filtration systems.
- Energy Price Volatility:Energy-intensive melting and extrusion processes make operations sensitive to electricity price fluctuations, impacting profitability, especially in Europe.
- Multi-Layer Plastic Processing:Current mechanical technologies struggle to process complex multi-layer films, limiting recovery of these common packaging materials.
Strategic Opportunities
- Chemical Recycling Feedstock:Mechanical systems can pre-process waste for chemical recycling facilities, creating an opportunity to supply densified feedstock for pyrolysis.
- Southeast Asian Markets:Rising waste generation and new regulations in Vietnam and Indonesia present opportunities for deploying modular recycling systems.
- IIoT and Process Control:Integrating IIoT sensors allows real-time monitoring of melt quality, enabling process optimization and predictive maintenance.
Industry Challenges
- High Initial Investment:The significant capital expenditure for high-capacity extrusion and super-clean PET systems creates a substantial barrier to entry for new operators.
- Specialized Operator Shortage:A lack of skilled technicians to operate and maintain advanced filtration and sorting equipment limits the efficiency of modern plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Recycling Machine Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shredders, Granulators, Crushers, Extruders Technology: Mechanical, Chemical, Thermal, Biological End User: Manufacturers, Waste Management Companies, Municipalities, Recycling Facilities Application: Textiles, Packaging, Automotive, Construction |
| Companies Covered | Neowaste, Rhea's Factory, EREMA, PolyGone Systems, ByFusion Global, Invoitplast Machinery, Pyrelis, Circular.co, Reclamation Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Recycling Machine Market Strategic Shifts & Innovations
A push toward material-specific processing and data-driven optimization is defining the next generation of recycling machinery. This evolution favors systems that guarantee output quality and integrate into digitalized plant management workflows.
Chemical recycling pre-processing equipment prepares mixed plastic waste by shredding and densifying it for advanced processes like pyrolysis. Petrochemical majors and specialized startups are adopting these systems to secure consistent feedstock. This development is fragmenting the equipment market into distinct segments for mechanical (pellet output) versus chemical (feedstock prep) lines.
The US EPA’s National Recycling Strategy encourages the development of domestic processing capacity and a more circular economy for plastics. This federal guidance, with state-level extended producer responsibility (EPR) laws, incentivizes investment in new recycling facilities in the United States. The HDPE and PP recycling segments are most affected as brands seek reliable domestic sources of post-consumer resin.
Customers are increasingly favoring modular, containerized recycling systems over large, monolithic plant installations. This trend disrupts the traditional sales model of custom-engineered plants, creating space for suppliers offering scalable, plug-and-play solutions. This is most visible among new market entrants and municipalities in North America and Europe seeking decentralized waste processing.
Plastic Recycling Machine Market Segmentation
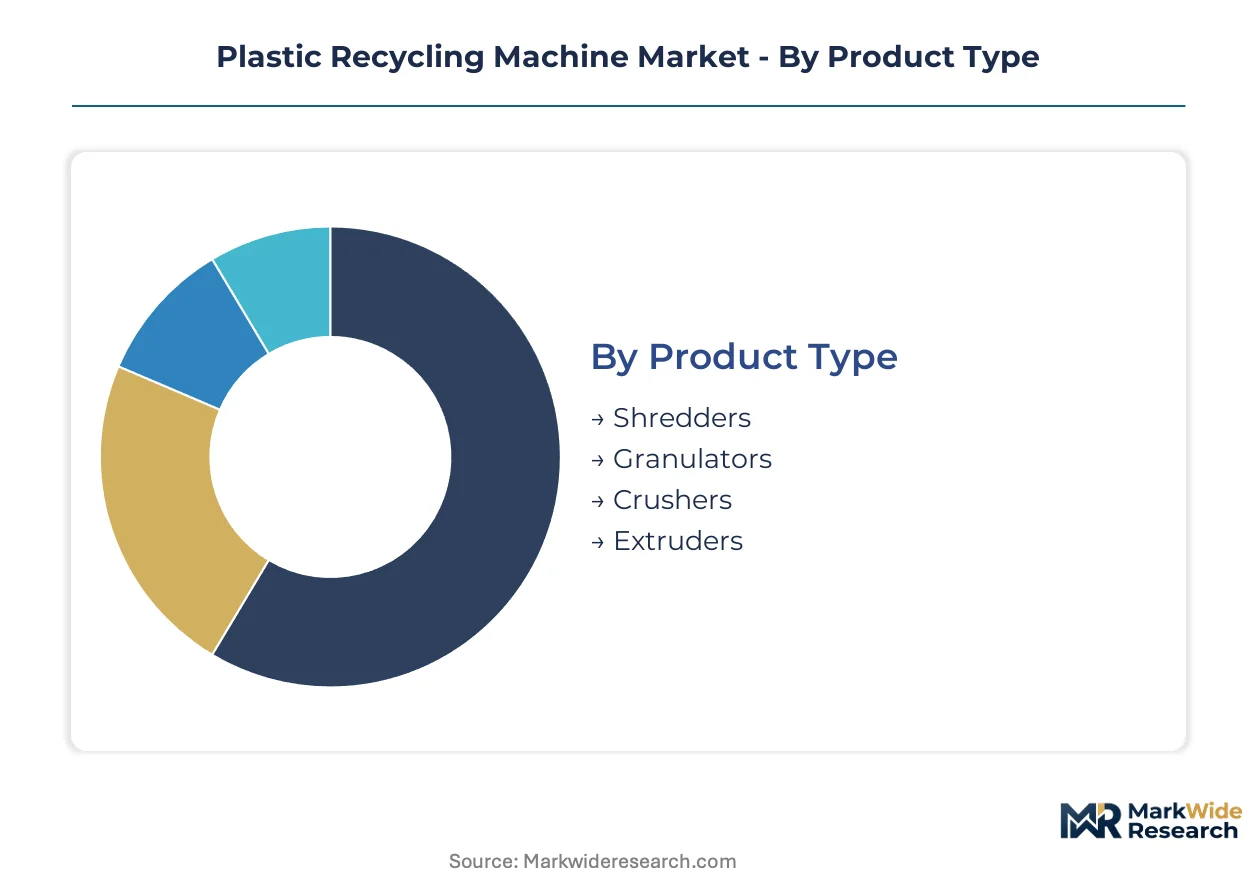
The plastic recycling machine market's segmentation reveals the diverse operational requirements and technological approaches employed across the industry. Understanding these distinctions helps pinpoint specific investment areas and technological advancements driving market evolution. Each segment reflects unique challenges and opportunities in converting plastic waste into reusable materials.
Product Type:
The product type segment illustrates where traditional mechanical processes face pressure from specialized equipment for specific waste streams.
- Extruders:These machines melt and homogenize plastic flakes or pellets, forming a continuous strand that is then cooled and cut into new pellets. High-capacity extruders are essential for producing consistent, high-purity resin for packaging applications, especially in Germany and the United States.
- Granulators:Granulators reduce plastic waste, such as bottles and films, into uniform flakes or granules through high-speed rotary blades. Their efficiency directly impacts the quality and throughput of subsequent washing and extrusion processes, driving demand in facilities processing PET and HDPE.
- Shredders:Shredders perform initial size reduction of large or bulky plastic waste, preparing material for further processing.
- Crushers:These machines break down rigid plastics into smaller, manageable pieces before granulation or washing stages.
Extruders retain volume leadership; Granulators hold the steepest expansion curve.
Technology:
Technology differentiation often correlates with capital expenditure requirements and operational costs.
- Mechanical:This dominant technology involves physical processes like shredding, washing, grinding, and melting plastic waste into new pellets or flakes. Mechanical recycling is valued for its efficiency in handling clean, single-polymer streams such as PET and HDPE.
- Chemical:Chemical recycling technologies break down plastic polymers into their molecular components, which can then be used to create virgin-quality plastics. Mechanical systems often pre-process waste for these facilities, supplying densified feedstock for pyrolysis.
- Thermal:Thermal technologies, including pyrolysis and gasification, convert plastic waste into fuels or chemical feedstocks using high heat in the absence of oxygen.
- Biological:This emerging technology uses enzymes or microorganisms to break down complex plastic polymers into simpler compounds.
Mechanical technology dominates current capacity; Chemical processes attract significant new investment.
End User:
Customer segmentation reveals varied operational scales and material input requirements.
- Recycling Facilities:These dedicated plants process large volumes of post-consumer and post-industrial plastic waste, converting it into recycled raw materials for various industries. They often invest in high-capacity systems for PET and HDPE streams.
- Manufacturers:Manufacturers integrate recycled plastics into their production lines, either by purchasing recycled content or by processing their own waste streams. CPG companies procuring food-grade rPET exemplify this segment's demand.
- Waste Management Companies:These firms collect, sort, and pre-process plastic waste before sending it to recycling facilities or other end-users.
- Municipalities:Local government bodies manage residential and commercial waste collection programs, often operating material recovery facilities or contracting with private recyclers.
Recycling Facilities form the largest direct user base; Manufacturers drive demand for integrated solutions.
Application:
Application areas dictate material specifications and potential for premium recycled content.
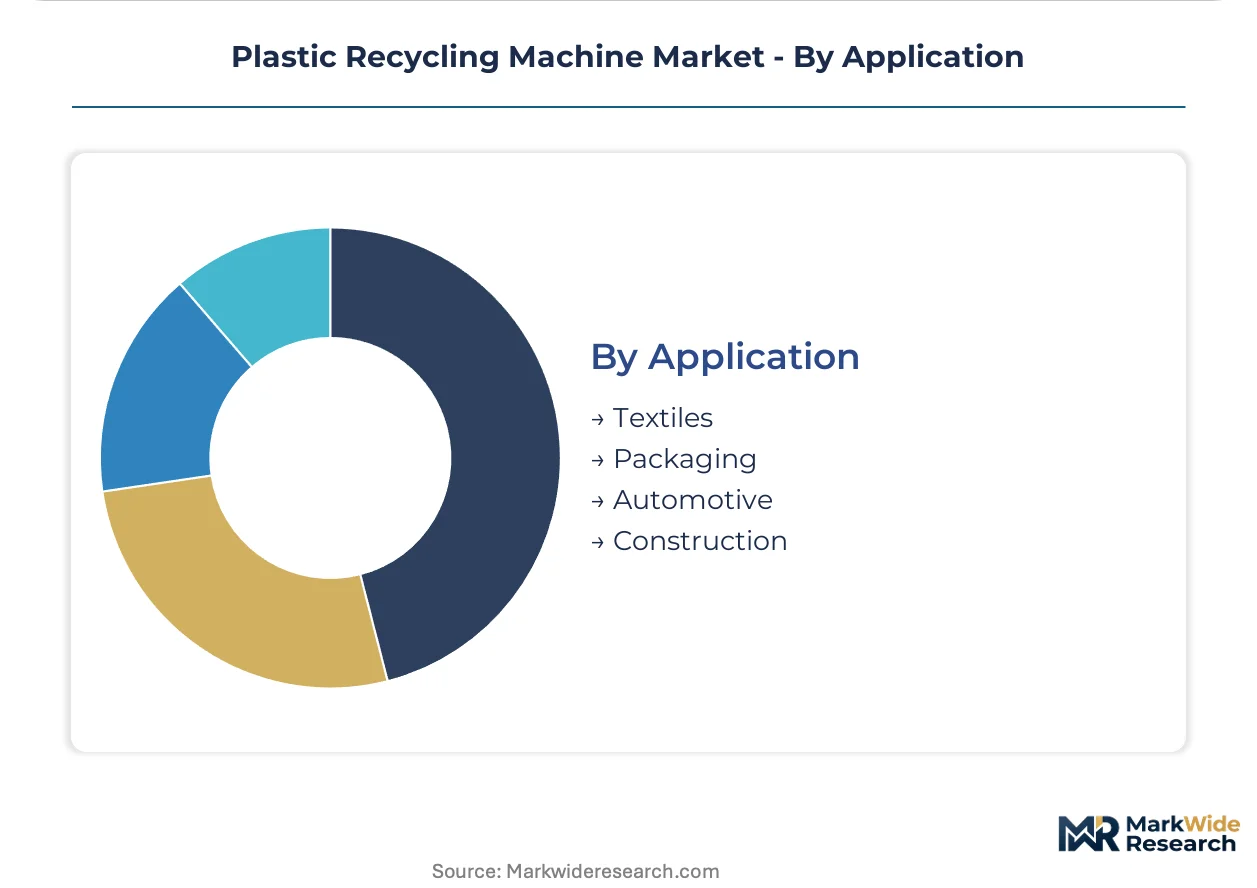
- Packaging:This segment represents a primary driver for plastic recycling machine demand, as companies seek to increase recycled content in bottles, films, and containers. The EU Green Deal mandates for recycled content directly impact this application.
- Construction:The construction sector utilizes recycled plastics for various products, including composite lumber, insulation, and pipes, often incorporating difficult-to-recycle plastics. ByFusion Global specializes in this niche.
- Textiles:Recycled plastics, particularly PET, are processed into fibers for apparel, carpeting, and other textile products.
- Automotive:The automotive industry uses recycled plastics for interior components, under-the-hood parts, and exterior trim to meet sustainability targets.
Packaging remains the primary application driver; Construction offers a specialized outlet for difficult plastics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for plastic recycling machines varies significantly across regions; some markets prioritize high-purity output regardless of cost, while others seek economical, high-throughput solutions for basic processing. This bifurcation reflects differing regulatory pressures and end-market requirements for recycled content. Investment patterns reflect these regional nuances for processing capabilities.
Germany
Demand for advanced extrusion systems is strong, driven by high-value packaging applications. The EU Green Deal mandates for recycled content compel significant investment in high-purity processing lines. German manufacturing hubs in Bavaria and North Rhine-Westphalia concentrate innovation in precision recycling machinery.
United States
Domestic processing capacity expands due to increasing brand commitments for recycled content. The US EPA’s National Recycling Strategy encourages domestic processing, incentivizing new facility development. Material recovery facilities in California and Texas are upgrading to handle larger volumes of post-consumer plastics.
China
Investment in circular economy infrastructure is accelerating to meet ambitious environmental targets. China's dual carbon goals promote internal circular economy development and restrict scrap imports. Industrial parks in the Yangtze River Delta focus on high-capacity systems for diverse plastic waste streams.
Vietnam
Rising waste generation and new national regulations are creating opportunities for modular recycling systems. Government initiatives to manage plastic pollution drive demand for efficient processing solutions. Industrial zones near Ho Chi Minh City and Hanoi are attracting investments in scalable recycling technologies.
India
The packaging sector's procurement of recycled content stimulates demand for efficient granulators and extruders. India's Plastic Waste Management Rules encourage recycling infrastructure development. Manufacturing clusters in Gujarat and Maharashtra are expanding their capabilities for processing PET and HDPE waste.
Plastic Recycling Machine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the plastic recycling machine market. The landscape exhibits a tiered structure, with established players focusing on high-end, specialized solutions and newer entrants targeting modular, cost-effective systems. Strategic archetypes include high-purity specialists, general mechanical recyclers, and niche solution providers addressing specific waste challenges. Companies are pursuing geographic expansion and advanced sorting technology integration to enhance material recovery capabilities.
Specialists in advanced extrusion and filtration systems, such as EREMA, exemplify the high-purity segment, delivering consistent material quality for demanding packaging applications. Neowaste occupies a position among providers of modular systems, catering to diverse operational scales for both small-scale recyclers and large waste management firms. ByFusion Global represents a niche player, transforming difficult-to-recycle plastics into construction materials, thereby addressing specific waste streams often overlooked by conventional mechanical processes. These companies anchor different segments, reflecting varied technological approaches and end-market focus across the industry value chain, influencing procurement strategies for operators globally.
| Leading Market Players |
|---|
| Neowaste |
| Rhea's Factory |
| EREMA |
| PolyGone Systems |
| ByFusion Global |
| Invoitplast Machinery |
| Pyrelis |
| Circular.co |
| Reclamation Factory |
| Others |
Cost & Logistics Intelligence
The substitution of virgin plastics with recycled content reshapes supply geography and pricing economics simultaneously. Demand for high-purity recycled polymers in packaging applications drives investment in advanced processing lines, influencing equipment costs and material availability globally.
Pricing Analysis
After-sales service and spare parts revenue drives significant lifetime value for equipment manufacturers. The dominant pricing model for plastic recycling machines remains project-based, reflecting the custom engineering often required for high-capacity systems. Price differentiation stems from the output quality grade, such as food-grade rPET certification, and the level of customization for specific waste streams. Pricing softness reflects intense competition from Chinese manufacturers in the standard mechanical recycling segment. Small-scale recyclers and municipalities exhibit the highest price sensitivity, favoring modular, cost-effective solutions.
Supply Chain Analysis
Just-in-time inventory strategies for core components face challenges due to global logistics and specialized part availability. Geographic supply concentration for advanced components centers on Germany, the United States, and increasingly China for standard parts. Raw material dependencies include specialized filtration membranes, high-grade steel for extruders, and advanced sensor technologies. A structural supply chain risk involves single-source vulnerability for highly specialized control systems. Equipment distribution typically occurs through direct sales channels for large projects and regional distributors for smaller, modular systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic recycling machine market presents a service-attach opportunity, with IIoT-enabled process optimization and predictive maintenance services expanding faster than core machinery sales.
For Market Incumbents: Consolidate market share by acquiring specialized firms with advanced sorting and pre-processing technologies. This defends against the threat of new entrants offering modular, integrated systems. Invest in R&D for next-generation filtration systems that can handle increasingly contaminated mixed plastic streams. Expand localized service hubs in high-growth regions like Southeast Asia to enhance customer support.
For New Entrants and Emerging Players: Modular system deployment services represent an underserved gap where incumbents typically focus on large, custom installations. Target decentralized waste processing needs in North American municipalities and developing Southeast Asian markets. A key go-to-market angle involves offering plug-and-play solutions with integrated financing options, lowering initial capital expenditure barriers for operators. Focus on flexible systems capable of handling diverse waste types.
For Investors and Strategic Acquirers: EU Green Deal mandates reshape the acquisition landscape, favoring companies that enable compliance with recycled content targets. Long-term viability rests on robust demand for circular economy solutions across all industries. Seek acquisition targets with proprietary chemical recycling pre-processing technology or advanced material sorting capabilities. The signal to watch is an increase in government R&D grants for novel plastic recycling technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Germany and the United States | Increases domestic processing capabilities to meet escalating demand for recycled content. |
| Advanced Sorting Technology Integration | Enhances flake purity, enabling recyclers to produce higher-value materials for premium end markets. |
| Modular System Product Launch | Addresses the growing demand for scalable, decentralized waste processing solutions globally. |
| Chemical Recycling Feedstock Partnership | Secures consistent material supply for advanced recycling processes, bridging mechanical and chemical systems. |
| IIoT and Process Control Platform Development | Optimizes machine performance, reduces operational costs, and enables predictive maintenance for operators. |
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Paint Knife Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Bamboo Products Market