
 Thermal Scanners Market | 2026-2036
Thermal Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Scanners Market Intelligence
Production of high-sensitivity microbolometer cores is consolidating around specialized foundries in North America and Europe, creating high entry barriers. Teledyne FLIR LLC leverages its deep vertical integration into sensor manufacturing to control a significant portion of the value chain. Fluke Corporation competes effectively through its strong distribution network for handheld devices used in predictive maintenance. L3Harris Technologies sustains its market position by developing advanced systems for defense clients.
A thermal scanner is an optoelectronic device that detects infrared radiation and converts it into a visible image, or thermogram, showing temperature variations. These devices typically operate in the long-wave infrared (LWIR) spectrum, from 8 to 14 micrometers, to visualize surface heat without physical contact. Handheld scanners represent the largest product segment due to their versatility in predictive maintenance and electrical inspections. Fixed mount systems, however, are gaining share rapidly for continuous security surveillance in manufacturing plants and critical infrastructure.
Product standards are governed by regulations such as CE marking requirements in Europe and specific GB standards for electronic equipment in China. In the United States, agencies like the FDA review thermal scanners for fever screening, while the NHTSA influences automotive applications. Future competitiveness depends on navigating complex export controls on sensitive infrared technology while scaling production of lower-cost sensor cores.
Market Dynamics
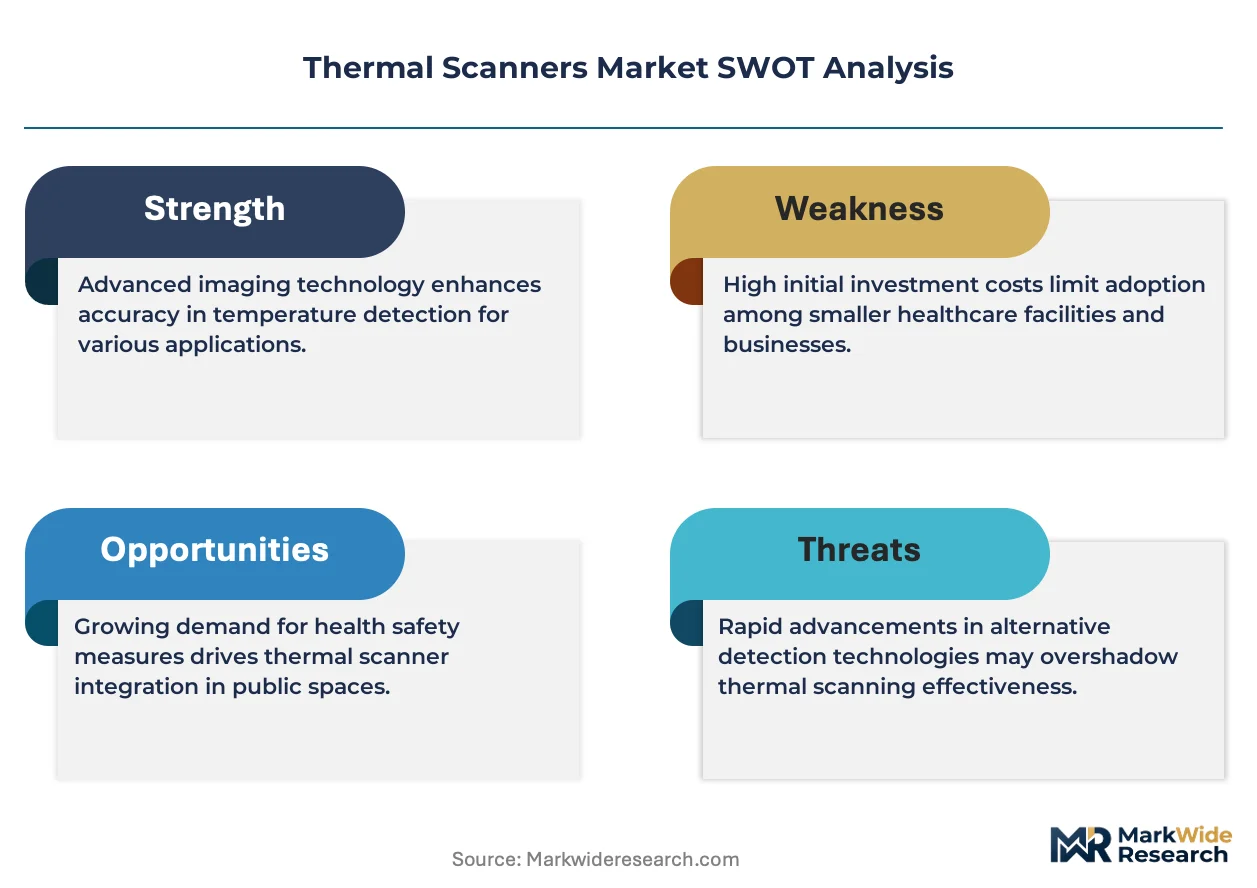
The consolidation of high-sensitivity microbolometer core production within a few specialized foundries in North America and Europe is the central structural force shaping the thermal scanner market, creating high entry barriers and influencing cost structures across the value chain.
Growth Catalysts
- Industrial Automation:Expanding use in predictive maintenance for manufacturing plants and electrical utilities drives consistent demand for handheld and fixed-mount scanners to prevent equipment failure.
- Infrastructure Security Mandates:Government requirements in countries like China for continuous monitoring of critical infrastructure, including transportation hubs and power grids, accelerate fixed system adoption.
- Sensor Miniaturization:Ongoing reductions in the size and cost of microbolometer cores enable integration into new commercial products, such as drones and consumer electronics.
Market Restraints
- Export Controls:Strict regulations on the export of sensitive infrared technology, particularly high-resolution sensors from North America, limit market access and complicate international supply chains.
- High Production Costs:The capital-intensive nature of fabricating high-sensitivity microbolometer cores in specialized foundries keeps unit costs elevated, particularly for advanced cooled detectors.
- Atmospheric Interference:The accuracy of long-range thermal imaging is inherently limited by environmental factors like humidity, fog, and dust, which absorb and scatter infrared radiation.
Strategic Opportunities
- Automotive Integration:The development of lower-cost uncooled microbolometers creates an opportunity for wider integration into advanced driver-assistance systems (ADAS) for enhanced night vision and pedestrian detection.
- Industrialization in India:India’s expanding manufacturing and infrastructure sectors represent an underpenetrated market for predictive maintenance and process monitoring applications using thermal scanners.
- AI-Powered Analytics:Converging thermal imaging with artificial intelligence enables automated anomaly detection in security surveillance and industrial quality control, creating new value-added software services.
Industry Challenges
- Navigating Divergent Standards:Manufacturers face complexity in meeting disparate regional standards, such as Europe's CE marking and China's GB standards for electronic equipment, increasing compliance costs.
- Skilled Technician Scarcity:A shortage of certified thermographers capable of accurately interpreting thermal data and diagnosing faults in industrial or building inspections limits the effective use of advanced systems.
Report Scope
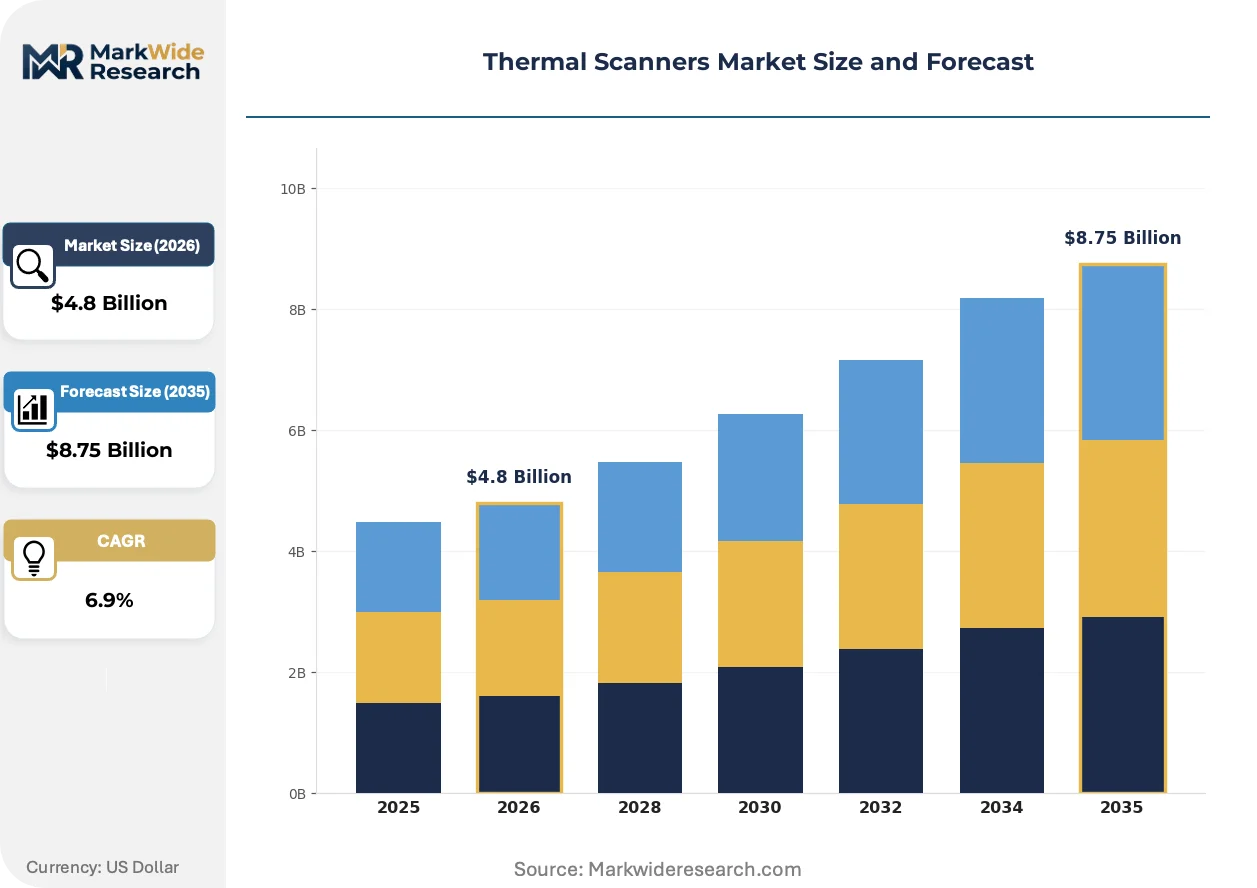
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Scanners Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed Mount, Smartphone Compatible, Rugged, Portable Technology: Infrared, Microbolometer, Quantum Well Infrared Photodetector, Thermopile, Pyroelectric Application: Security Surveillance, Predictive Maintenance, Firefighting, Electrical Inspections, HVAC Monitoring End User: Law Enforcement, Manufacturing Plants, Fire Departments, Energy Suppliers, Construction Firms |
| Companies Covered | Teledyne FLIR LLC, Fluke Corporation, L3Harris Technologies, Leonardo S.p.A., AMETEK Land, Opgal Optronic Industries Ltd., Axis Communications AB, 3M, Optotherm, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Scanners Market Strategic Shifts & Innovations
A fundamental shift from pure hardware performance to integrated, data-driven solutions is reshaping the market. This evolution prioritizes analytical software, automated workflows, and connectivity over standalone imaging capabilities, creating new competitive dynamics for vendors.
Edge computing, integrating AI processors directly within the thermal camera, allows for real-time analysis without relying on a central server. Industrial quality control and critical infrastructure security are the primary adopters of this intelligent hardware. This on-device processing capability is absorbing the value previously held by separate analytics software suites, bundling intelligence directly into the sensor platform.
The National Highway Traffic Safety Administration (NHTSA) in the United States evaluates thermal imaging to improve pedestrian detection in low-light conditions. These assessments influence the development of advanced driver-assistance systems (ADAS). The automotive segment is most affected, with suppliers developing more affordable LWIR cameras to meet potential future safety mandates for vehicle perception.
End-users increasingly favor subscription-based models for advanced thermal analysis software over perpetual licenses tied to hardware. This change disrupts the traditional one-time sales model, shifting revenue toward recurring service contracts. The trend is most prominent in industrial process control and continuous monitoring applications where data management is critical.
Thermal Scanners Market Segmentation
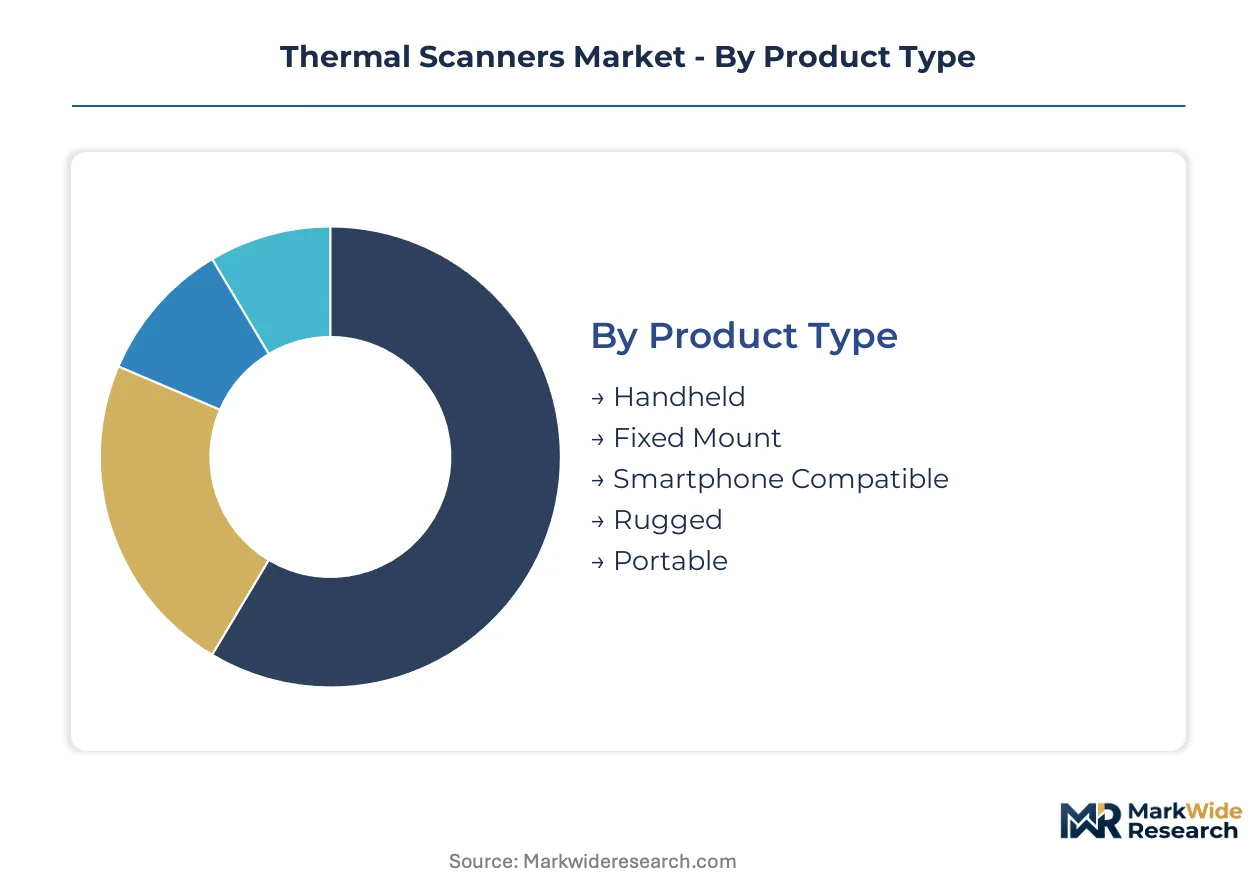
Understanding the thermal scanner market through segmentation reveals distinct product functionalities, technological underpinnings, and end-user requirements. This granular view allows manufacturers to tailor product development and go-to-market strategies effectively. Each segment reflects specific user needs and operational environments.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, mass-produced devices to specialized, application-specific solutions.
- Handheld:These portable devices offer immense versatility for on-site diagnostics and inspections, providing immediate thermal insights. Demand concentrates in industrial manufacturing and electrical utilities for predictive maintenance, preventing costly equipment failures.
- Fixed Mount:Designed for continuous operation, these systems are permanently installed to provide uninterrupted monitoring and surveillance. Adoption is accelerating in critical infrastructure and manufacturing plants, driven by security mandates in countries like China.
- Smartphone Compatible:These compact attachments integrate thermal imaging capabilities directly with mobile devices, leveraging existing computational power and display. Miniaturization of microbolometer sensors enables broader consumer and commercial accessibility.
- Rugged:Engineered to withstand harsh industrial or outdoor conditions, these durable scanners ensure reliable performance in challenging environments. Defense and heavy industry sectors frequently deploy ruggedized units.
- Portable:Offering a balance between mobility and advanced features, portable scanners facilitate flexible deployment across various field applications. Technicians use these for diverse inspection tasks.
Leading the category by volume: Handheld. Growing fastest: Fixed Mount.
Technology:
The technology segment reflects the maturity and supply concentration of core infrared detection methods, influencing performance and cost structures.
- Microbolometer:An uncooled thermal sensor that detects infrared radiation by measuring changes in electrical resistance due to temperature variations. Ongoing miniaturization efforts are integrating these sensors into a wider range of commercial products, including drones and automotive ADAS.
- Infrared:This fundamental technology converts invisible infrared radiation into a visible thermogram, allowing non-contact temperature measurement. Industrial process control and building diagnostics widely employ infrared principles for efficiency and safety.
- Quantum Well Infrared Photodetector:These cooled semiconductor devices offer extremely high sensitivity and speed, requiring cryogenic cooling for optimal operation. Defense and scientific research applications utilize these advanced detectors for precision imaging.
- Thermopile:Comprising multiple thermocouples connected in series, thermopile sensors produce a voltage proportional to incident infrared radiation. Simpler designs make them suitable for low-cost, low-resolution applications.
- Pyroelectric:Operating on the principle of temperature-dependent spontaneous polarization, pyroelectric sensors are uncooled and respond to changes in infrared radiation. These are often found in motion detectors and basic security systems.
The most mature technology is Infrared. The technology expanding most quickly is Microbolometer.
Application:
Application segmentation illustrates the diverse functional utility of thermal scanners across various operational contexts and industries.
- Predictive Maintenance:Thermal scanners identify overheating components or abnormal temperature patterns in machinery, preventing unexpected equipment failures. Industrial manufacturing plants and electrical utilities are primary adopters, seeking to minimize downtime.
- Security Surveillance:These systems provide continuous monitoring capabilities, detecting intruders or suspicious activity in low-light conditions. Critical infrastructure sites and transportation hubs increasingly deploy thermal surveillance, especially in China.
- Firefighting:Thermal imagers allow firefighters to see through smoke, locate victims, and identify hot spots within burning structures. First responders rely on this capability for enhanced safety and operational effectiveness.
- Electrical Inspections:Detecting abnormal heat signatures in electrical panels, wiring, and components helps prevent outages and fires. Energy suppliers and facility managers conduct regular thermal scans.
- HVAC Monitoring:Assessing temperature uniformity and detecting energy leaks in heating, ventilation, and air conditioning systems improves building efficiency. Commercial and residential building management benefits from this application.
Predictive Maintenance accounts for the largest share of applications. Security Surveillance is demonstrating the steepest expansion trajectory.
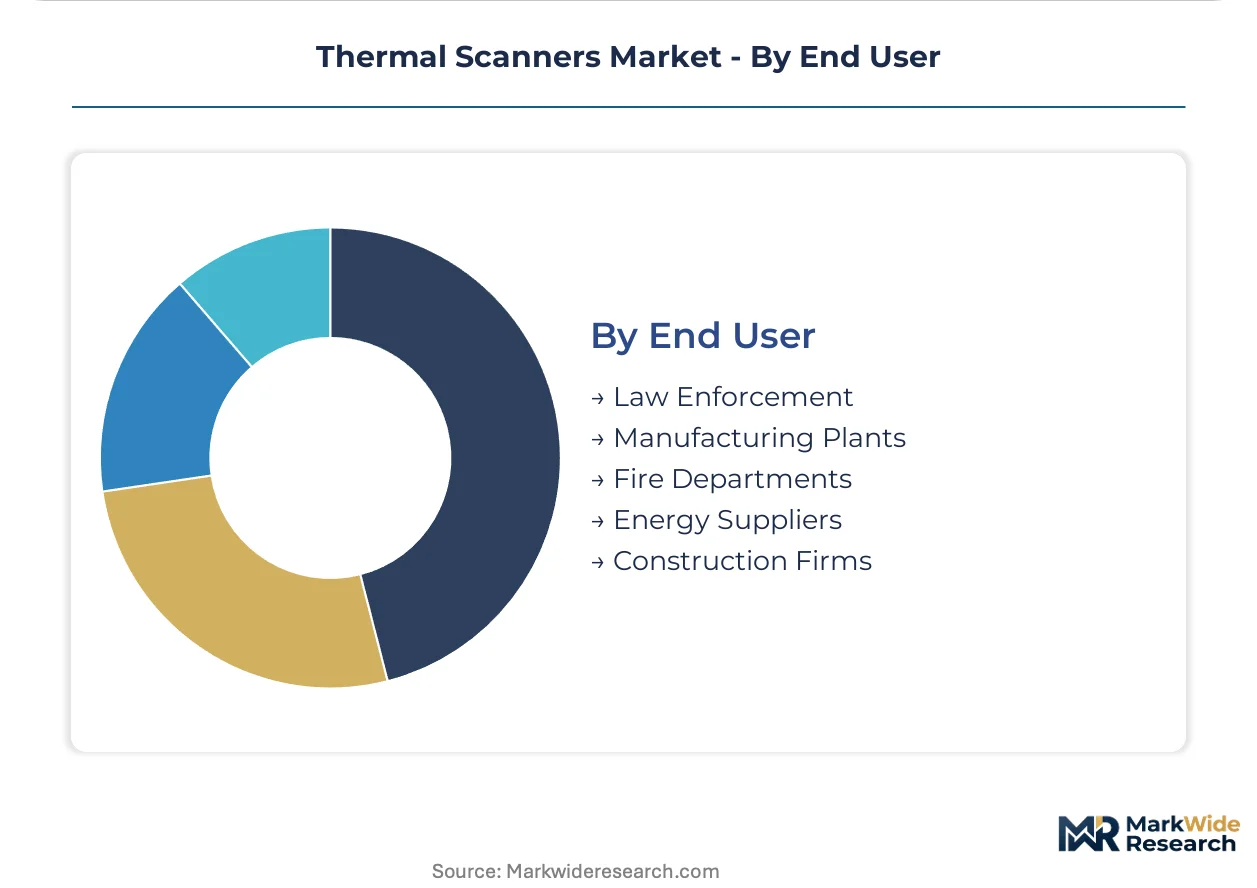
End User:
The end-user segmentation categorizes demand based on organizational structure and specific industry requirements for thermal imaging solutions.
- Law Enforcement:Agencies utilize thermal scanners for night vision, search and rescue operations, and suspect apprehension, enhancing situational awareness. Public safety mandates drive consistent procurement in this sector.
- Manufacturing Plants:These facilities deploy thermal imagers for process control, quality assurance, and equipment monitoring, ensuring operational efficiency and safety. Industrial automation initiatives in Europe and North America boost adoption.
- Fire Departments:First responders integrate thermal imaging into their equipment for navigating smoke-filled environments and identifying heat sources during emergencies. Life safety protocols mandate the use of these critical tools.
- Energy Suppliers:Utilities employ thermal scanners to inspect power lines, substations, and generation equipment for potential faults or inefficiencies. Grid reliability is a primary concern for these organizations.
- Construction Firms:Builders use thermal imaging for identifying insulation gaps, moisture intrusion, and structural anomalies in new and existing buildings. Quality control and energy efficiency drive this adoption.
Manufacturing Plants represent the largest end-user segment. Law Enforcement is consistently expanding its thermal scanner deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a primary hub for specialized microbolometer core foundries, anchors advanced thermal scanner technology development. This concentration influences supply chains and innovation globally. Demand patterns reflect diverse industrial and security needs across major economies.
United States
United States demand for thermal scanners stems from predictive maintenance in industrial plants and automotive ADAS integration. The NHTSA influences automotive applications for enhanced pedestrian detection. Silicon Valley firms integrate advanced thermal sensors into consumer electronics and AI analytics platforms.
China
China's market expansion is driven by extensive industrial automation and critical infrastructure security mandates. GB standards for electronic equipment dictate compliance for thermal scanner imports and production. Yangtze River Delta manufacturing hubs rapidly adopt fixed-mount systems for continuous surveillance.
Germany
Germany exhibits strong demand from high-value industrial manufacturing and advanced automotive applications. CE marking requirements ensure product safety and quality for thermal scanners throughout the European Union. Bavaria's automotive industry integrates thermal imagers for enhanced night vision and advanced driver-assistance systems.
India
India's expanding manufacturing and infrastructure sectors represent a significant demand driver for predictive maintenance. BIS standards for electronic goods are increasingly relevant for market entry and product certification. Industrial corridors around Mumbai and Chennai are adopting thermal solutions for process monitoring and quality control.
Japan
Japan's thermal scanner demand arises from precision manufacturing quality control and aging infrastructure inspection needs. JIS standards guide product development and ensure interoperability in complex industrial settings. Tokyo's advanced robotics sector integrates miniaturized thermal sensors into automated inspection and surveillance systems.
Thermal Scanners Market Key Industry Players
Global majors compete with regional champions across technology leadership and distribution network strength. The thermal scanner market exhibits a tiered structure, with a few vertically integrated players dominating core sensor production. Strategic archetypes include specialized sensor manufacturers, broad-portfolio industrial solution providers, and niche application developers. Companies primarily engage in capacity expansion and strategic partnerships to extend market reach.
Within the specialized sensor manufacturing segment, Teledyne FLIR LLC exemplifies extensive upstream control over microbolometer core production. This allows them to offer a broad range of products from components to finished systems. Fluke Corporation represents a strong distribution network for handheld devices, particularly in predictive maintenance applications, leveraging established channels to reach industrial end-users globally. L3Harris Technologies anchors the advanced systems segment, developing sophisticated thermal imaging solutions primarily for defense and critical infrastructure clients, where high performance and reliability are paramount.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Fluke Corporation |
| L3Harris Technologies |
| Leonardo S.p.A. |
| AMETEK Land |
| Opgal Optronic Industries Ltd. |
| Axis Communications AB |
| 3M |
| Optotherm, Inc. |
| Others |
Cost & Logistics Intelligence
Ongoing miniaturization of microbolometer sensors reconfigures cost economics and intensifies supply concentration for core components. This shift influences pricing power across the value chain for thermal scanner manufacturers.
Pricing Analysis
Warranty and service bundling increasingly differentiate thermal scanner offerings, particularly for advanced software analytics packages. The dominant pricing model for hardware remains per-unit transactional, while software services often adopt subscription-based tiers. Price differentiation stems from vertical integration into sensor manufacturing and the specific certification level achieved, such as CE marking or GB standards. Pricing pressure arises from the commoditization of lower-resolution microbolometers, especially in consumer-facing applications. The automotive ADAS segment demonstrates high price sensitivity, contrasting with the lower sensitivity in defense and critical infrastructure sectors.
Supply Chain Analysis
Reverse-logistics for sensor refurbishment and module remanufacturing are becoming more critical as product lifecycles extend. Geographic supply concentration for high-sensitivity microbolometer cores centers in North America and Europe. Raw material dependencies include specialized semiconductor wafers and germanium for optical components. Export controls on sensitive infrared technology present a significant structural risk, complicating international procurement. Distribution runs through direct sales channels for complex fixed-mount systems and specialized industrial distributors for handheld devices, with OEM integration common for automotive and consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermal scanner market is a vertical-integration race, with players pursuing upstream control over microbolometer core production to secure supply and manage costs.
For Market Incumbents: Deploy vertical integration into microbolometer core production to mitigate supply chain risks and control intellectual property. Consolidate specialized foundries and invest in advanced AI-powered analytics to maintain differentiation against emerging lower-cost sensor manufacturers. Reinforce strong distribution networks for handheld devices to counter commoditization pressure. Expand R&D into next-generation sensor materials to stay ahead of technological substitution threats.
For New Entrants and Emerging Players: Capture white-space opportunities in the automotive ADAS and consumer electronics integration segments. Penetrate the smartphone-compatible thermal attachment market and low-cost drone camera applications through strategic partnerships. Focus on developing specialized software solutions that leverage existing hardware, offering value-added services. Target regions like India with expanding industrial and infrastructure sectors for new demand.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given their control over critical microbolometer core technology. Long-term viability remains strong due to sustained demand in industrial automation, security surveillance, and emerging automotive applications. Acquire specialized foundries with unique sensor IP or AI analytics software providers to enhance market position. Monitor regulatory mandates for ADAS thermal vision and significant microbolometer cost breakthroughs for early signals of market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Microbolometer foundry capacity ensures stable supply for growing automotive ADAS demand. |
| Software Integration | AI-powered analytics integrate thermal data for automated anomaly detection in industrial quality control. |
| Strategic Partnerships | OEM collaborations accelerate thermal sensor adoption in new commercial and consumer devices. |
| Vertical Integration | Upstream control of sensor manufacturing reduces core production costs and enhances supply security. |
| Geographic Expansion | Market entry into India's industrial sector captures new demand for predictive maintenance solutions. |
Research Approach
Document review covered industry reports, company filings, and regulatory documents from agencies like NHTSA and those governing CE marking, complemented by interviews. This process involved synthesizing insights from manufacturing plant managers, certified thermographers, defense procurement officers, and automotive engineers. Secondary data sources included SEC filings of public companies, government technology reports, patent databases, and trade association publications. Bottom-up market sizing was performed, with top-down validation ensuring data accuracy.
Volume and value projections were developed using a proprietary analytical framework, incorporating historical data extrapolation and future trend analysis across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from a synthesis of primary and secondary data, with industrial automation investment rates and microbolometer cost reduction trajectories serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts affecting export controls and rapid technological breakthroughs in sensor design. Forecasts reflect assumptions regarding market dynamics and regulatory stability. Practitioners should monitor new ADAS safety standards and significant microbolometer cost breakthroughs for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Temperature Controller Market