
 Electric Vehicle (EV) Sensor Market | 2026-2036
Electric Vehicle (EV) Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Sensor Market Analysis
Fleet operators and autonomous shuttle developers is bifurcating demand away from traditional private-vehicle sensor procurement. Infineon Technologies AG leverages its SiC powertrain integration to dominate current sensing for high-voltage architectures. Robert Bosch GmbH sustains broad portfolio coverage across pressure and proximity modules for European OEM programs.
Electric Vehicle (EV) Sensors are electromechanical transducers that convert physical stimuli—temperature, pressure, electromagnetic fields, or optical reflections—into processable electrical signals, typically operating within automotive-grade temperature ranges of minus forty to one hundred fifty degrees Celsius and ISO 26262 functional safety thresholds. These devices enable real-time closed-loop control of traction motors, thermal regulation circuits, and advanced driver-assistance perception stacks. Current sensors and pressure sensors anchor the highest-margin product tiers due to their criticality in battery thermal runaway prevention and high-voltage isolation monitoring. LiDAR and radar technologies within the technology dimension are capturing disproportionate R&D allocation as Level Three automation timelines compress development cycles.
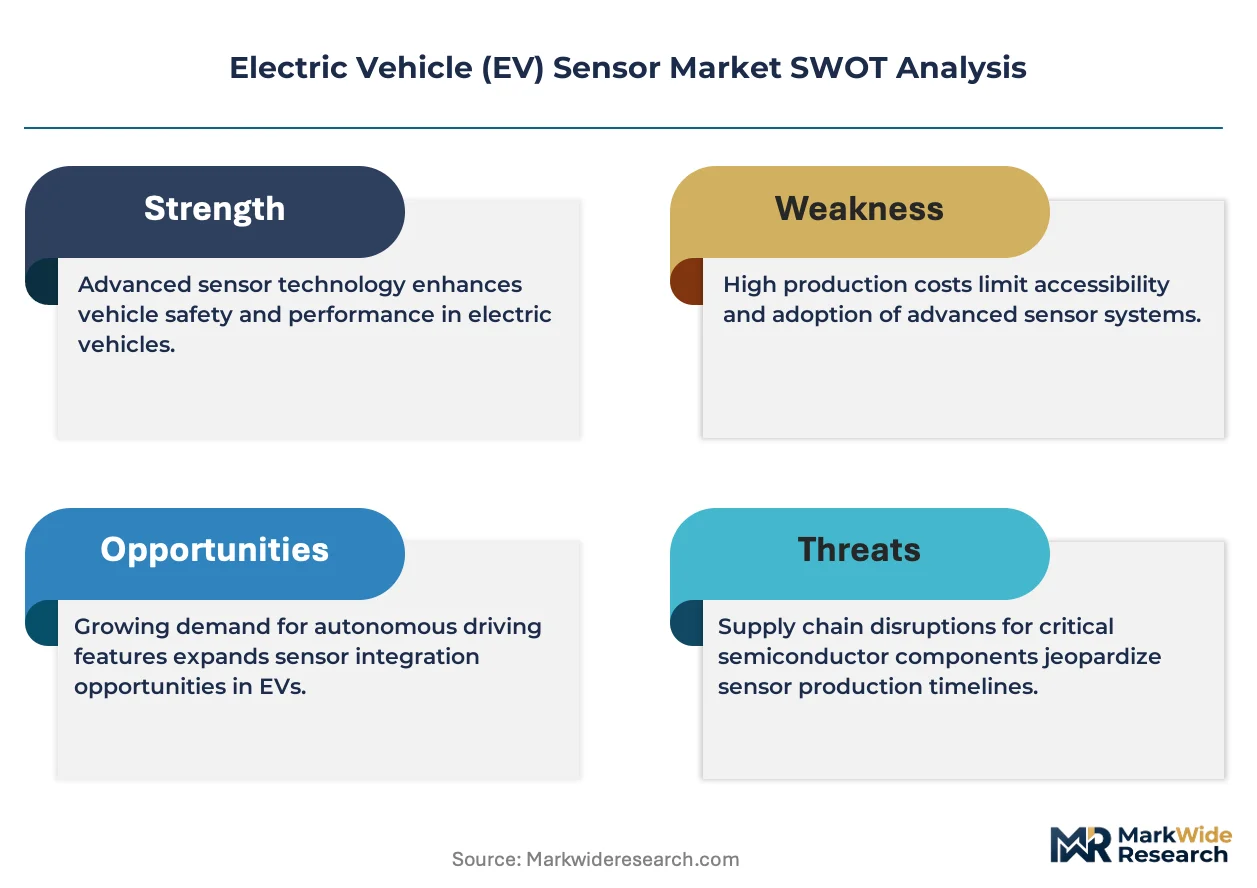
The US NHTSA and EPA jointly shape sensor mandate timelines through crashworthiness testing protocols and zero-emission vehicle credit structures that reward precision battery-state reporting. Europe's EU AI Act and MDR-equivalent automotive safety framework under ECE R79/R157 are forcing sensor redundancy and validation documentation upgrades for lane-keeping and automated lane-change systems. Stakeholders must weigh regulatory divergence between Washington and Brussels when selecting single-platform versus regionally adapted sensor architectures.
Market Dynamics
The transition to 800-volt architectures is compressing sensor qualification timelines as OEMs demand components that withstand higher electromagnetic interference and isolation voltages. This voltage migration is forcing simultaneous redesigns of current sensing, thermal monitoring, and position detection subsystems across the supply base.
Growth Catalysts
- China's MIIT dual carbon mandates:Vehicle safety regulations now require redundant battery monitoring systems, expanding sensor counts per pack by 40-60% for thermal runaway detection.
- Autonomous shuttle procurement:Fleet operators in Germany's Stuttgart-Munich corridor are specifying LiDAR-integrated sensor suites for Level Four depot-to-depot logistics.
- SiC powertrain adoption:Silicon carbide inverters generate switching frequencies above 50 kHz, necessitating high-bandwidth current sensors with sub-microsecond response times.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependencies for position sensors concentrate in Chinese processing facilities, exposing Hall-effect sensor producers to input volatility.
- ISO 26262 ASIL-D certification costs:Functional safety validation for battery management sensors requires 18-24 month qualification cycles that freeze design iterations.
- Optical sensing substitution:Camera-based perception stacks in premium EVs are displacing short-range ultrasonic sensors in parking assistance applications.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized sensor manufacturing incentives are opening capacity for temperature and pressure modules serving two-wheeler electrification.
- Vehicle-to-grid integration:Bidirectional charging protocols require new current sensing architectures that monitor power flow direction with utility-grade accuracy.
- EU AI Act compliance services:Sensor fusion validation documentation represents a service revenue stream for testing laboratories certifying automated lane-change systems.
Industry Challenges
- Electromagnetic compatibility engineering:High-voltage switching transients in 800-volt platforms induce noise that corrupts low-level analog sensor signals, demanding shielding redesigns.
- Calibration equipment capex:Production test systems for LiDAR alignment require investments exceeding two million dollars per line, squeezing mid-tier suppliers.
- Legacy CAN bus integration:New sensor protocols must bridge to existing vehicle networks without latency penalties that compromise real-time battery state estimation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Sensor Market |
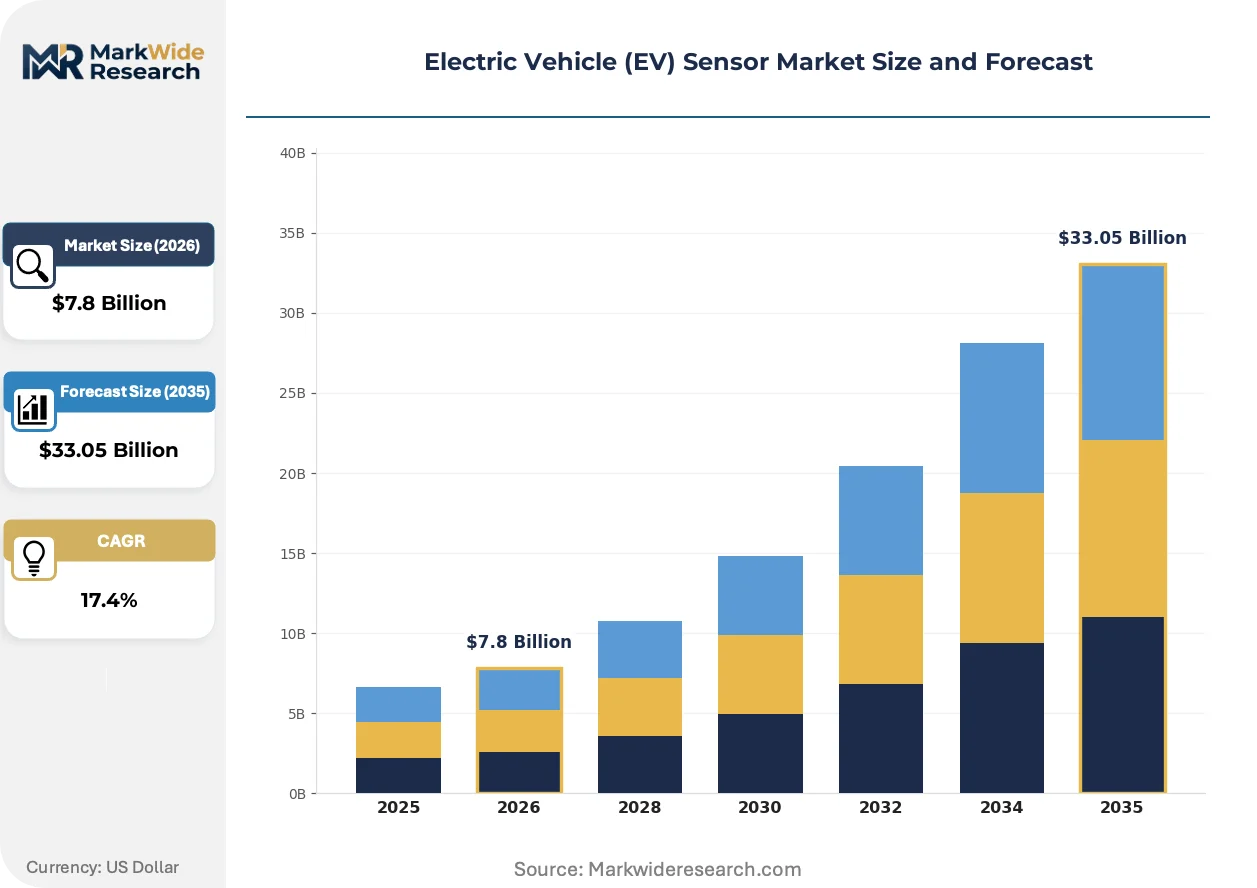
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $33.05 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Temperature Sensor, Proximity Sensor, Pressure Sensor, Current Sensor Application: Battery Management, Vehicle Stability, Navigation Assistance, Collision Avoidance Technology: LiDAR, Radar, Ultrasonic, Optical End User: OEMs, Aftermarket Suppliers, Fleet Operators, Research Institutions |
| Companies Covered | Infineon Technologies AG, Sensata Technologies, Denso Corporation, Analog Devices, Texas Instruments Incorporated, Robert Bosch GmbH, NXP Semiconductors, ZF Friedrichshafen AG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Sensor Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete component boundaries as EV platforms consolidate perception, powertrain, and thermal monitoring into unified compute domains. This integration is redrawing competitive boundaries between semiconductor, optical, and electromechanical specialists.
Solid-state LiDAR is bifurcating the perception sensor market. MEMS-based scanning arrays deliver 200-meter range detection for highway pilot functions. Premium passenger EV manufacturers in Germany are adopting these modules for Level Three automation timelines. The technology is bifurcating development roadmaps away from mechanical spinning units toward chip-scale integration that reduces unit costs and vibration susceptibility.
Europe's ECE R157 regulation for automated lane-keeping systems mandates redundant steering angle sensing with independent power supplies. This framework is forcing dual-sensor architectures where single-string designs previously sufficed. Tier One suppliers are responding with magnetoresistive position sensors packaged with isolated communication transceivers.
Fleet procurement contracts now specify sensor lifecycle data rights as separable from hardware purchase. Logistics operators in California and Texas are demanding API access to degradation telemetry for predictive maintenance scheduling. This unbundling is compressing traditional component margins while opening subscription revenue pools for analytics-enabled sensor vendors.
Electric Vehicle (EV) Sensor Market Segmentation
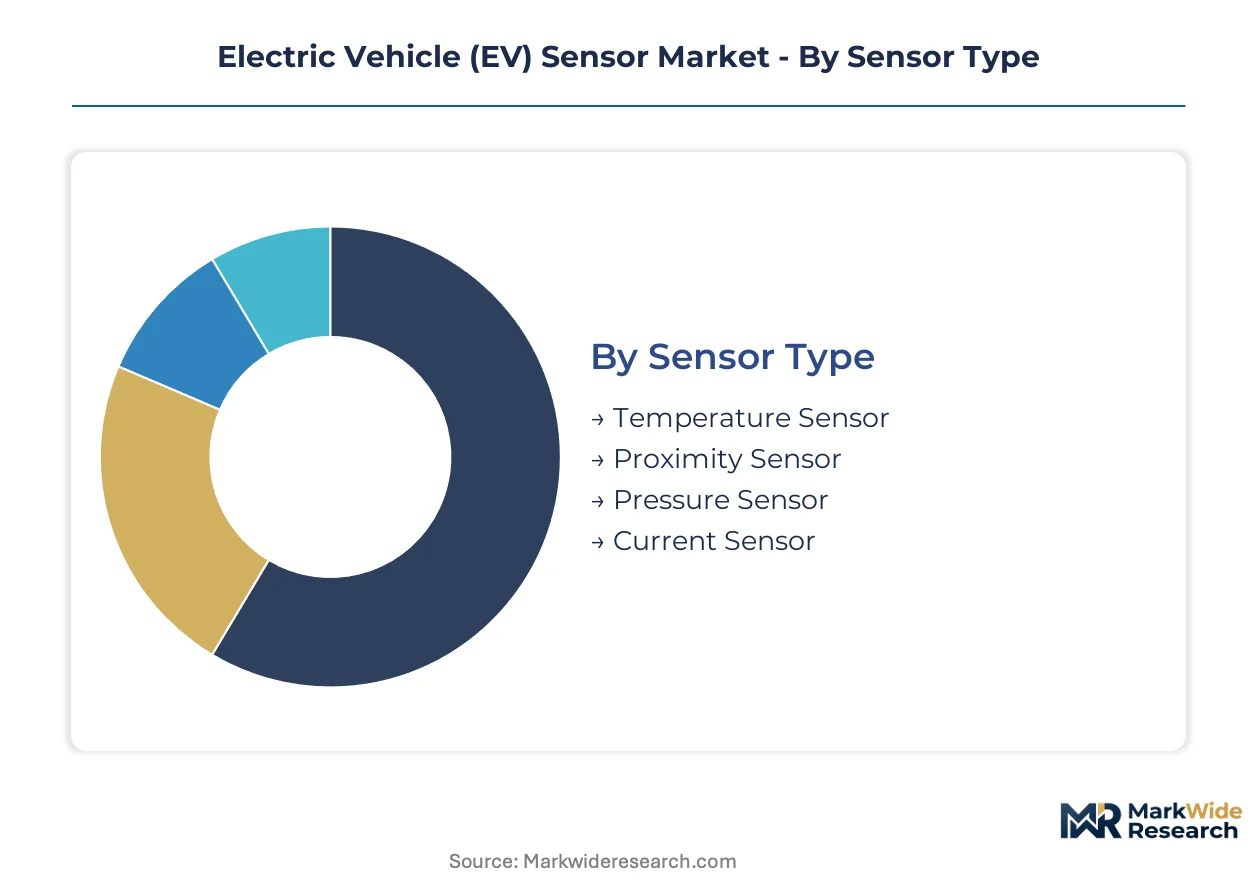
Sensor segmentation in the EV market determines procurement strategies across voltage architectures and automation tiers. Category boundaries are blurring as 800-volt platforms and Level Three autonomy force multi-sensor integration.
Sensor Type:
Margin pools concentrate in high-voltage isolation and thermal runaway detection functions where ASIL-D certification creates pricing power.
- Current Sensor:Hall-effect and shunt-based architectures monitor traction inverter and battery pack power flow with sub-microsecond response times. German OEMs in the Stuttgart-Munich corridor specify these for SiC powertrain integration where switching frequencies exceed 50 kHz.
- Pressure Sensor:MEMS-based cells track thermal management system coolant and refrigerant states across minus forty to one hundred fifty degrees Celsius operating envelopes. China's NMPA vehicle safety mandates now require redundant pressure monitoring for battery thermal runaway prevention, expanding sensor counts per pack.
- Temperature Sensor:NTC thermistor and RTD elements embed within cell modules and cooling circuits.
- Proximity Sensor:Inductive and capacitive variants handle charge port alignment and pedestrian detection at low speeds.
Current sensors hold installed capacity. Pressure sensors are rotating up the share rankings.
Application:
Volume concentrates in powertrain electrification functions, though fastest expansion sits in perception stacks for automated driving.
- Battery Management:Voltage, current, and temperature sensing arrays feed state-of-charge and state-of-health algorithms with ISO 26262 ASIL-C or ASIL-D ratings. China's MIIT dual carbon goals mandate redundant monitoring architectures that increase sensor density per pack by forty to sixty percent.
- Collision Avoidance:Fusion of LiDAR, radar, and optical inputs enables automatic emergency braking and cross-traffic alert. US NHTSA crashworthiness testing protocols now weight sensor precision in five-star rating calculations, tightening performance thresholds.
- Vehicle Stability:Inertial measurement units and steering angle sensors support electronic stability control.
- Navigation Assistance:GNSS-IMU integration enables lane-level positioning for highway pilot functions.
Battery management anchors revenue. Collision avoidance is expanding most quickly.
Technology:
Cost tier stratification separates premium long-range perception from commodity short-range detection.
- LiDAR:Solid-state MEMS and OPA architectures deliver two-hundred-meter range detection with chip-scale integration reducing unit costs. Premium passenger EV manufacturers in Germany adopt these for Level Three automation timelines, displacing mechanical spinning units.
- Radar:77 GHz and 4D imaging variants provide all-weather velocity and range data for adaptive cruise control. Europe's ECE R157 regulation for automated lane-keeping systems mandates radar redundancy with independent power supplies, forcing dual-sensor architectures.
- Optical:Camera-based perception stacks leverage deep learning for traffic sign and lane marking recognition.
- Ultrasonic:Short-range parking assistance faces displacement by camera-based alternatives in premium segments.
LiDAR claims the steepest expansion trajectory. Radar maintains broadest platform penetration.
End User:
Procurement patterns diverge between specification-controlled OEM programs and lifecycle-cost-optimized fleet operations.
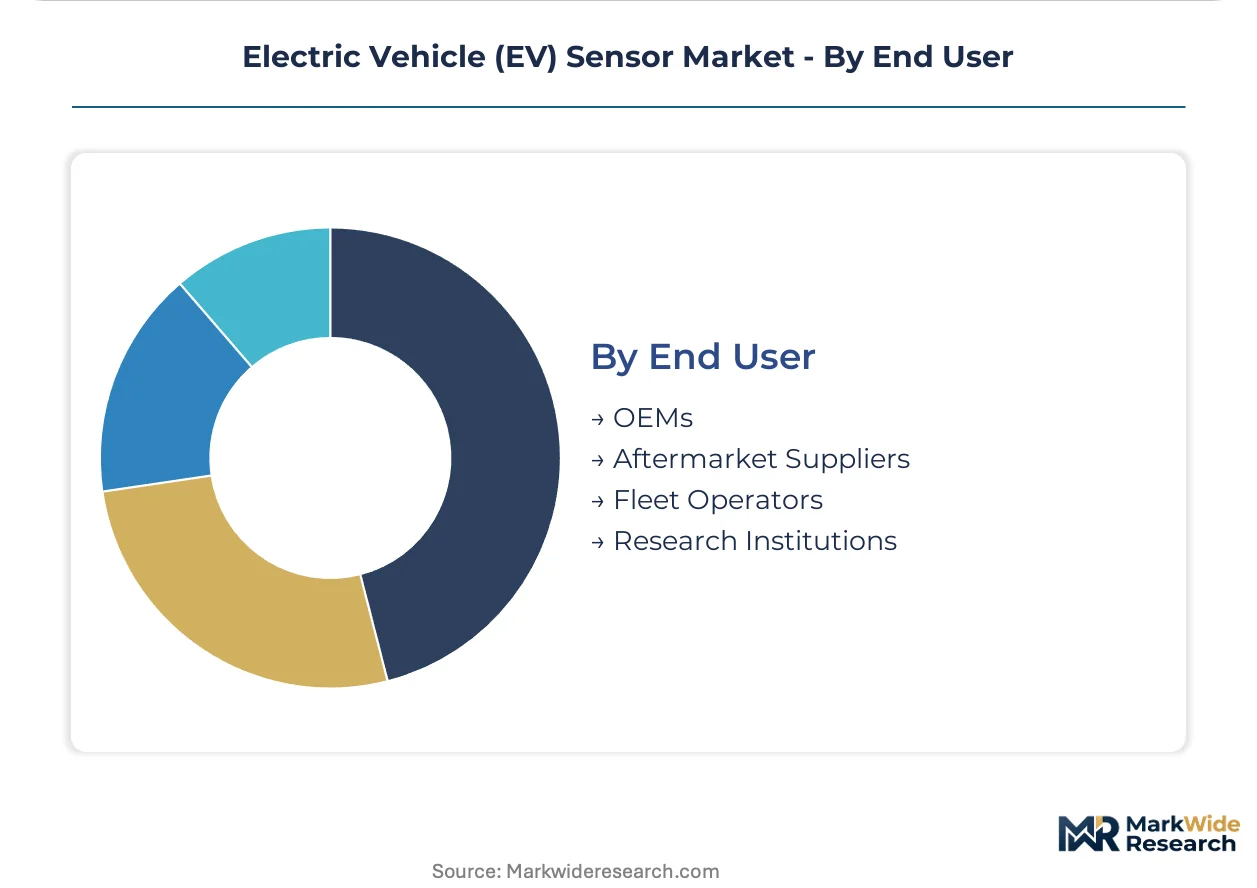
- OEMs:Integrated sensor module sourcing for platform-scale programs with multi-year qualification cycles. European OEMs specify ECE R79 and R157-compliant architectures with validation documentation packages for EU AI Act alignment.
- Fleet Operators:Autonomous shuttle and logistics depot operators in California and Texas demand API access to sensor degradation telemetry, unbundling hardware purchase from data rights.
- Aftermarket Suppliers:Replacement and upgrade modules for legacy EV platforms.
- Research Institutions:Development platforms for next-generation fusion algorithms and calibration methods.
OEMs control specification authority. Fleet operators are gaining procurement leverage through data rights demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor around Stuttgart and Munich exports sensor modules to Chinese EV manufacturers expanding under MIIT dual carbon mandates. This trade flow anchors the transnational supply architecture for high-voltage current sensing and battery monitoring systems.
China
Domestic EV production scales drive sensor procurement for battery management and thermal runaway detection. MIIT dual carbon goals and NMPA vehicle safety mandates now require redundant monitoring architectures that expand sensor counts per pack. The Yangtze River Delta manufacturing cluster around Shanghai hosts integrated module production for both local OEMs and export programs.
Germany
Premium passenger EV manufacturers specify LiDAR-integrated sensor suites for Level Three automation timelines. ECE R79 and R157 regulations mandate redundant steering angle sensing with independent power supplies for automated lane-keeping systems. The Stuttgart-Munich corridor concentrates supplier engineering centers for SiC powertrain-integrated current sensing.
United States
Fleet operators in California and Texas demand API access to sensor degradation telemetry for predictive maintenance scheduling. NHTSA crashworthiness testing protocols and EPA zero-emission vehicle credit structures shape precision battery-state reporting requirements. The Detroit automotive engineering base and Silicon Valley perception software clusters drive fusion architecture development.
India
Two-wheeler electrification creates localized demand for temperature and pressure sensing modules. The PLI scheme for automotive components incentivizes domestic manufacturing capacity expansion. The Maharashtra-Gujarat industrial corridor hosts emerging sensor assembly operations serving both domestic OEMs and regional export markets.
South Korea
Battery cell manufacturers source high-precision current sensors for gigafactory-scale production lines. METI-equivalent industrial policy supports automotive semiconductor localization initiatives. The Seoul Capital Area concentrates R&D facilities for next-generation magnetoresistive position sensing technologies.
Electric Vehicle (EV) Sensor Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification tiers. The vendor base stratifies between consolidated semiconductor platforms and fragmented electromechanical component suppliers. Three archetypes dominate: integrated powertrain semiconductor vendors, multi-sensor module integrators, and specialized magnetic sensing developers. Competitive moves center on SiC powertrain co-design partnerships and ISO 26262 ASIL-D validation documentation services.
Within the integrated semiconductor tier, Infineon Technologies AG and Robert Bosch GmbH exemplify platform-scale positioning. Sensata Technologies occupies a specialist role in pressure and proximity module integration. These anchors represent divergent strategic postures—broad portfolio coverage versus targeted high-margin sensing applications—without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Sensata Technologies |
| Denso Corporation |
| Analog Devices |
| Texas Instruments Incorporated |
| Robert Bosch GmbH |
| NXP Semiconductors |
| ZF Friedrichshafen AG |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Silicon carbide inverter adoption is displacing conventional IGBT architectures and simultaneously redrawing procurement geography toward German engineering centers while compressing margins on legacy Hall-effect current sensors. This substitution dynamic concentrates pricing power with vendors qualified for 800-volt architectures while forcing tier-two suppliers into commodity positioning for 400-volt residual demand.
Pricing Analysis
Technology-generation pricing gaps separate ASIL-D-certified modules for 800-volt platforms from ASIL-B equivalents serving 400-volt legacy programs and pre-certified next-gen solid-state architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and switching-frequency bandwidth. Pricing pressure stems from Chinese OEM procurement consolidation around integrated powertrain modules. Fleet operators exhibit highest price sensitivity through unbundled data-rights negotiations, while German premium OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Strategic stockpiling of neodymium magnets and SiC substrates is displacing just-in-time preferences as tier-one suppliers buffer against rare-earth processing concentration and semiconductor foundry allocation volatility. Manufacturing concentrates in China, Germany, and South Korea. The supply chain draws from Malaysian rare-earth separation facilities, Taiwanese SiC wafer foundries, and Japanese magnetoresistive sensor die production. Single-source vulnerability in Chinese rare-earth processing exposes Hall-effect sensor producers to input disruption. Distribution runs through Stuttgart-Munich corridor engineering centers to global OEM platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26262 ASIL-D validation capabilities are bottlenecking supplier expansion, with fewer than twelve qualified laboratories capable of certifying battery management sensors within acceptable timelines. This scarcity concentrates margin capture with incumbents holding captive certification relationships.
For Market Incumbents: Consolidate magnetoresistive position sensing capabilities through selective acquisition of specialized developers in South Korea's Seoul Capital Area. Defend margin position by embedding subscription telemetry services into hardware contracts before fleet operators standardize API specifications. Prioritize SiC powertrain co-design partnerships with German OEMs launching 800-volt platforms.
For New Entrants and Emerging Players: ISO 26262 fast-track certification services in India's Maharashtra-Gujarat corridor offer the most penetrable entry vector, leveraging PLI scheme manufacturing incentives and shorter qualification queues. Target two-wheeler electrification temperature and pressure modules where ASIL requirements remain less stringent. Pursue vehicle-to-grid bidirectional current sensing architectures as utilities finalize interconnection standards.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive semiconductor specialists seeking exit liquidity after multi-year ASIL-D investment cycles. Long-term viability hinges on sensor fusion algorithm IP and data-rights contract structures rather than hardware unit economics. Watch for inflection when California or Texas fleet operators mandate predictive maintenance API access as standard procurement terms.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Powertrain Co-Design Partnership | Secures preferred-supplier status with German OEMs launching 800-volt platforms ahead of ECE R157 compliance deadlines. |
| ASIL-D Certification Fast-Track Investment | Compresses 18-24 month qualification cycles to capture battery thermal runaway detection mandates from China's MIIT. |
| Sensor Telemetry Subscription Launch | Unbundles hardware margins from recurring data-rights revenue serving California fleet operator predictive maintenance demands. |
| Neodymium Magnet Backward Integration | Reduces exposure to Chinese rare-earth processing volatility for Hall-effect position sensor production. |
| Solid-State LiDAR Module Integration | Displaces mechanical spinning units for Level Three automation timelines specified by premium German passenger EV manufacturers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator telematics managers; and secondary validation against vehicle production databases, NHTSA crashworthiness testing protocols, MIIT regulatory filings, and IHS Markit registration data. Bottom-up sensor unit economics triangulated against top-down EV production forecasts across the analysis window.
Forecast boundaries span the projection horizon without annual disaggregation. Segmentation dimensions include sensor type, application function, technology tier, propulsion architecture, and regional production cluster. CAGRs derive from installed base growth rates, content-per-vehicle expansion for 800-volt migration, and automation tier sensor density curves. Forecast inputs incorporate SiC inverter adoption trajectories and ECE R157 redundant sensing mandates.
Decision-makers should treat outputs as directional under assumptions of continued 800-volt platform migration and sustained MIIT dual carbon enforcement; material deviation would warrant model refresh. Specific risks include neodymium supply disruption, ISO 26262 qualification timeline extension, and optical sensing substitution accelerating beyond baseline assumptions. Revision becomes warranted when solid-state LiDAR cost curves cross mechanical unit thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Digital Flow Meter Market