
 Global Blind Spot Monitor Market | 2026-2036
Global Blind Spot Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blind Spot Monitor Market Analysis
Fleet operator procurement of blind spot monitor systems is expanding as logistics companies standardize on collision-avoidance specifications across heavy-duty vehicle contracts. ZF Friedrichshafen AG leverages its radar portfolio to anchor supply relationships with European truck manufacturers. Robert Bosch GmbH competes through integrated sensor fusion architectures that combine camera and radar inputs. Denso Corporation specializes in compact ultrasonic modules calibrated for tight packaging constraints in Asian vehicle platforms.
Blind spot monitors are proximity-sensing systems that detect objects outside a driver's direct field of vision, typically employing 24 GHz or 77 GHz radar modules, CMOS image sensors, or ultrasonic transducers mounted in side mirrors or rear quarter panels. Their primary commercial purpose is to reduce lane-change collisions by generating haptic, visual, or audible warnings when another vehicle occupies the monitored zone. Radar-based systems dominate the product type landscape due to superior performance in adverse weather conditions and longer detection ranges, while camera-based configurations are gaining ground where cost sensitivity and multi-function integration with surround-view systems matter. Factory-fitted installation leads the installation type structure because OEMs embed blind spot monitors within broader ADAS packages, though retrofitted solutions sustain a niche among commercial fleet operators extending vehicle lifecycles.
The EU General Safety Regulation mandates blind spot information systems on new trucks and buses, while NHTSA's five-star safety ratings in the United States incentivize passenger car OEM fitment. Japan's Ministry of Land, Infrastructure, Transport and Tourism has aligned type-approval standards with UN ECE R151, creating a harmonized compliance pathway for exporters. Stakeholders must monitor how software-defined vehicle architectures reshape sensor fusion requirements and whether LIDAR cost curves open a fourth product category beyond incumbent radar, camera, and ultrasonic technologies.
Market Dynamics
The EU General Safety Regulation is compressing factory-fitment timelines for heavy-duty vehicles while software-defined vehicle architectures are collapsing sensor fusion costs across passenger car platforms. These dual pressures are restructuring how Tier-1 suppliers allocate R&D budgets between radar module refinement and camera-based integration paths.
Growth Catalysts
- EU General Safety Regulation:Mandates blind spot information systems on all new trucks and buses registered in European Union member states, eliminating aftermarket-only pathways for commercial vehicle OEMs.
- Japan's MLIT type-approval alignment:Harmonization with UN ECE R151 creates export certification efficiency for Japanese suppliers serving Southeast Asian markets.
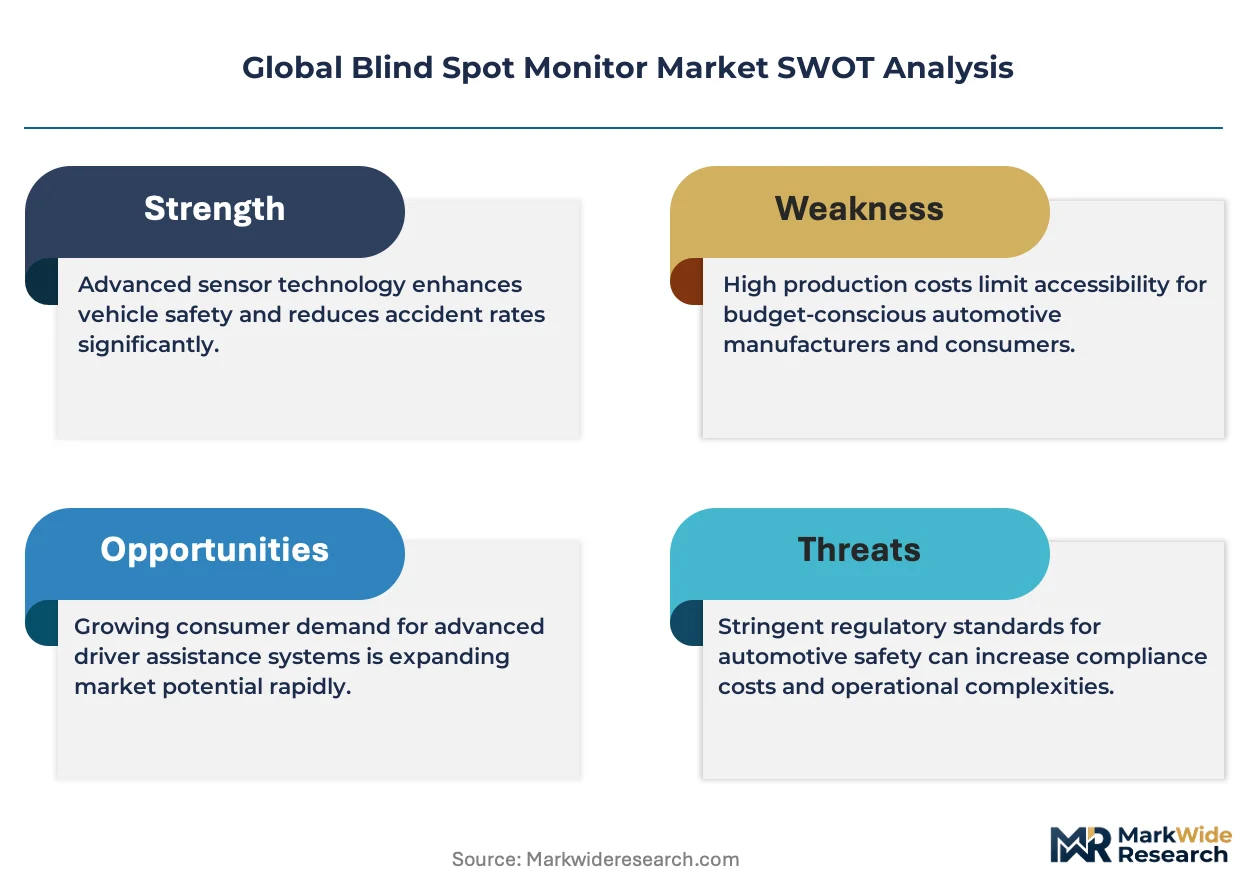
- Radar module cost curves:77 GHz semiconductor fabrication scale economies are reducing per-unit sensor costs below ultrasonic alternatives in certain packaging configurations.
Market Restraints
- Silicon germanium wafer supply concentration:Foundry capacity for automotive-grade radar substrates clusters in Taiwan and South Korea, exposing Tier-2 suppliers to single-source disruption risk.
- LIDAR substitution threat:Solid-state LIDAR cost compression below $200 per unit at volume threatens to displace radar-camera fusion in premium vehicle segments by 2028.
- NHTSA five-star rating threshold:The specific test protocol for blind spot monitoring creates design constraints that limit sensor placement flexibility and increase calibration complexity.
Strategic Opportunities
- Indian commercial vehicle retrofit:The country's central transport regulator is evaluating mandatory blind spot detection for inter-city buses, opening a retrofit channel absent in developed markets.
- Camera-radar fusion convergence:Integration with surround-view parking systems allows suppliers to amortize sensor costs across multiple ADAS functions.
- Fleet telematics integration:Logistics operators in Germany are specifying blind spot event data logging as a contract condition, creating recurring software revenue streams.
Industry Challenges
- Calibration technician scarcity:Radar alignment requires specialized microwave testing equipment and trained personnel that dealer networks lack in secondary cities.
- Legacy CAN bus integration:Commercial vehicles with pre-2018 electrical architectures require gateway module upgrades to support real-time blind spot data transmission.
- Functional safety certification:ISO 26262 ASIL-B compliance for camera-based systems extends development timelines by 8-14 months versus radar-only configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blind Spot Monitor Market |
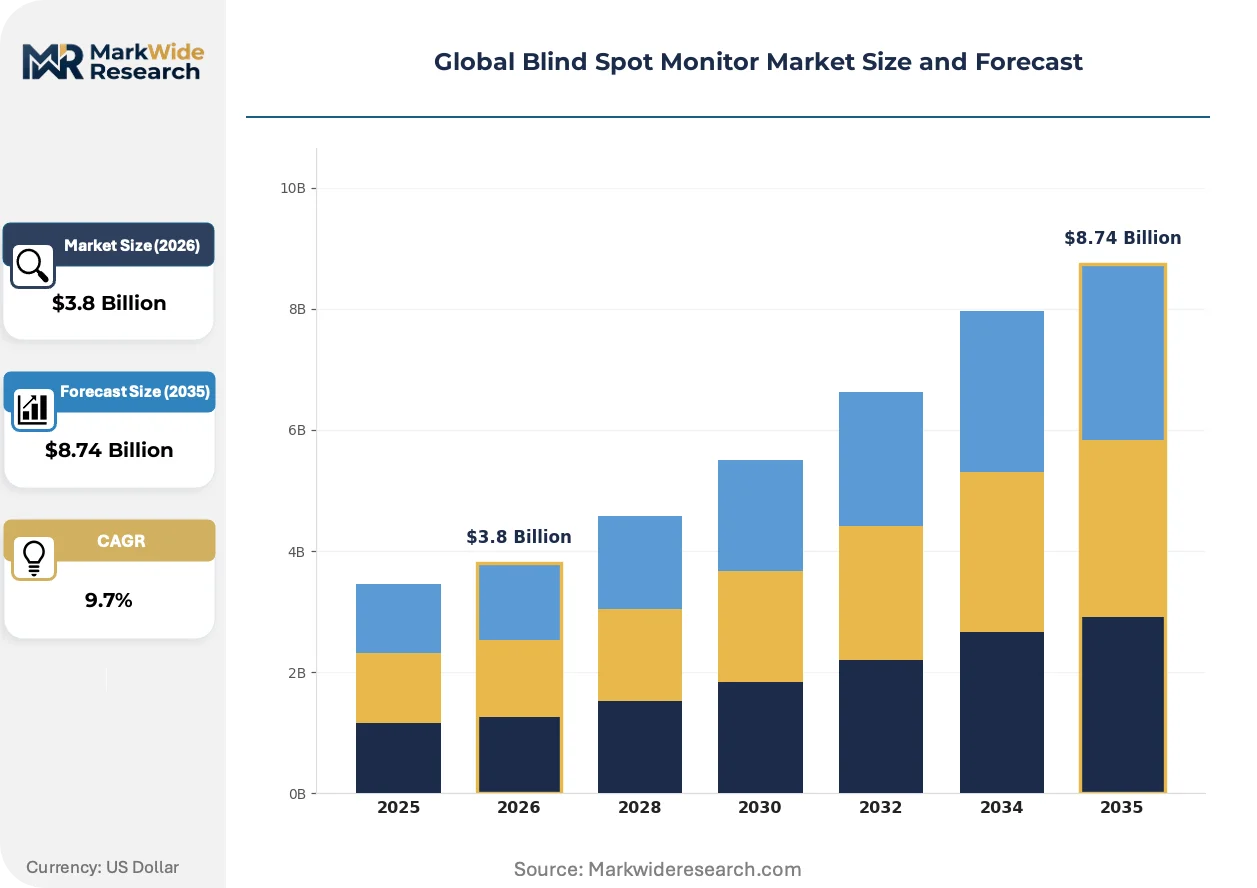
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar-Based, Camera-Based, Ultrasonic, LIDAR End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Installation Type: Integrated, Plug-and-Play, Retrofitted, Factory-Fitted Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles |
| Companies Covered | ZF Friedrichshafen AG, Magna International Inc., Robert Bosch GmbH, Aptiv PLC, Valeo SA, Continental AG, Autoliv Inc., Hyundai Mobis Co., Ltd., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blind Spot Monitor Market Emerging Trajectories
Sensor fusion architectures are collapsing the historical separation between parking assistance and highway-speed blind spot functions. This convergence is forcing suppliers to restructure hardware roadmaps around software-defined perception stacks rather than discrete sensor categories.
Edge computing is decentralizing image processing from centralized domain controllers to camera-mounted system-on-chip modules. ZF Friedrichshafen and Denso have both introduced side-mirror-integrated processors that handle object classification locally. This architecture reduces wiring harness complexity and enables sub-100-millisecond warning latency. The shift is compressing Tier-1 margins on gateway electronics while expanding software licensing opportunities.
REACH compliance deadlines for automotive electronics are accelerating substitution of halogenated flame retardants in radar housing materials. The European Chemicals Agency's 2025 restriction timeline is forcing suppliers to validate polyamide alternatives without compromising 77 GHz signal transparency. German truck manufacturers are prioritizing suppliers with certified material portfolios to avoid homologation delays.
Leasing companies in the United States are unbundling ADAS maintenance from standard service contracts. Fleet managers now negotiate separate blind spot calibration schedules based on mileage thresholds rather than fixed intervals. This consumption-based model is visible most acutely in California and Texas, where large commercial fleets dominate heavy-duty vehicle procurement.
Global Blind Spot Monitor Market Segmentation
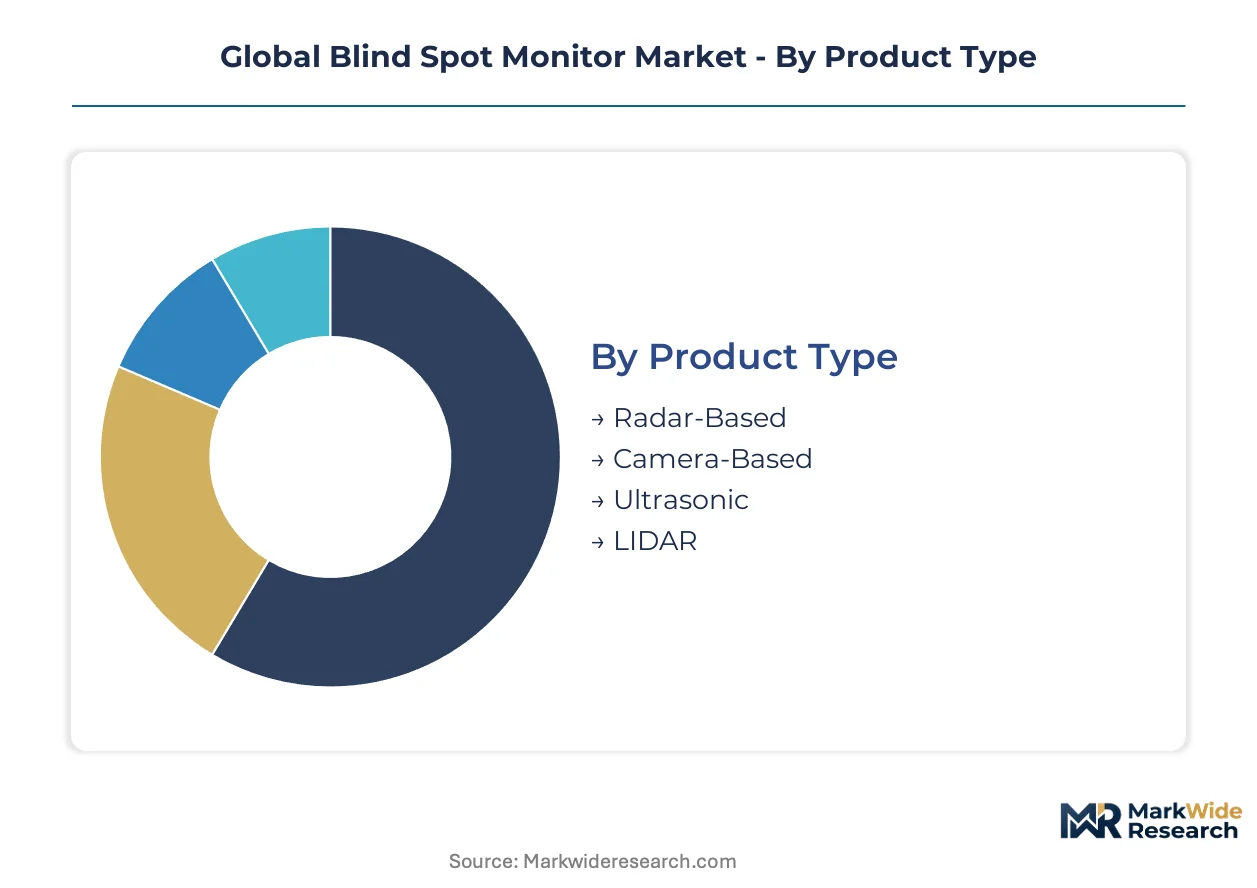
Blind spot monitor suppliers configure their product roadmaps around four distinct segmentation axes. Each axis carries different margin profiles, certification requirements, and customer concentration patterns that reshape competitive positioning.
Product Type:
Supply concentration clusters around radar module fabrication, with 77 GHz semiconductor foundry capacity constraining Tier-2 sourcing flexibility.
- Radar-Based:77 GHz and 24 GHz modules dominate highway-speed detection with all-weather reliability. Demand concentrates in German truck manufacturing where EU General Safety Regulation mandates factory-fitment on new heavy-duty vehicles.
- Camera-Based:CMOS image sensors enable multi-function integration with surround-view parking systems. Japanese OEMs in the mass-market passenger segment favor this technology for cost amortization across ADAS bundles.
- Ultrasonic:Compact transducers suit tight packaging constraints on Asian vehicle platforms with limited mirror housing volume.
- LIDAR:Solid-state configurations threaten incumbent technologies in premium segments as unit costs compress toward volume viability.
Today's leader: Radar-Based. Tomorrow's challenger: LIDAR.
End User:
Cost tier differentiation separates factory-integrated procurement from aftermarket retrofit channels with diverging margin structures.
- OEMs:Factory-integrated ADAS packages embed blind spot monitors within broader safety system architectures. European passenger car manufacturers specify radar-camera fusion to satisfy NHTSA five-star rating protocols.
- Fleet Operators:Logistics companies in Germany and the United States standardize collision-avoidance specifications across heavy-duty vehicle contracts, creating concentrated procurement volume.
- Aftermarket Providers:Service networks address legacy vehicle populations with calibration-dependent retrofit solutions.
- Insurance Companies:Risk-based premium adjustments incentivize policyholder installation of certified blind spot systems.
Volume concentrates with OEMs. Margin expansion sits with Fleet Operators.
Installation Type:
Application context determines whether sensor fusion demands embedded electrical architecture or standalone module compatibility.
- Factory-Fitted:OEMs embed sensors during vehicle assembly with domain controller integration and homologation-aligned calibration.
- Integrated:Multi-function ADAS packages combine blind spot monitoring with lane-keeping and adaptive cruise control through shared perception stacks.
- Retrofitted:Commercial fleet operators extend vehicle lifecycles through gateway module upgrades supporting real-time data transmission.
- Plug-and-Play:Simplified aftermarket solutions target owner-operated vehicles with minimal installation complexity.
Dominant share: Factory-Fitted. Steepest expansion trajectory: Retrofitted.
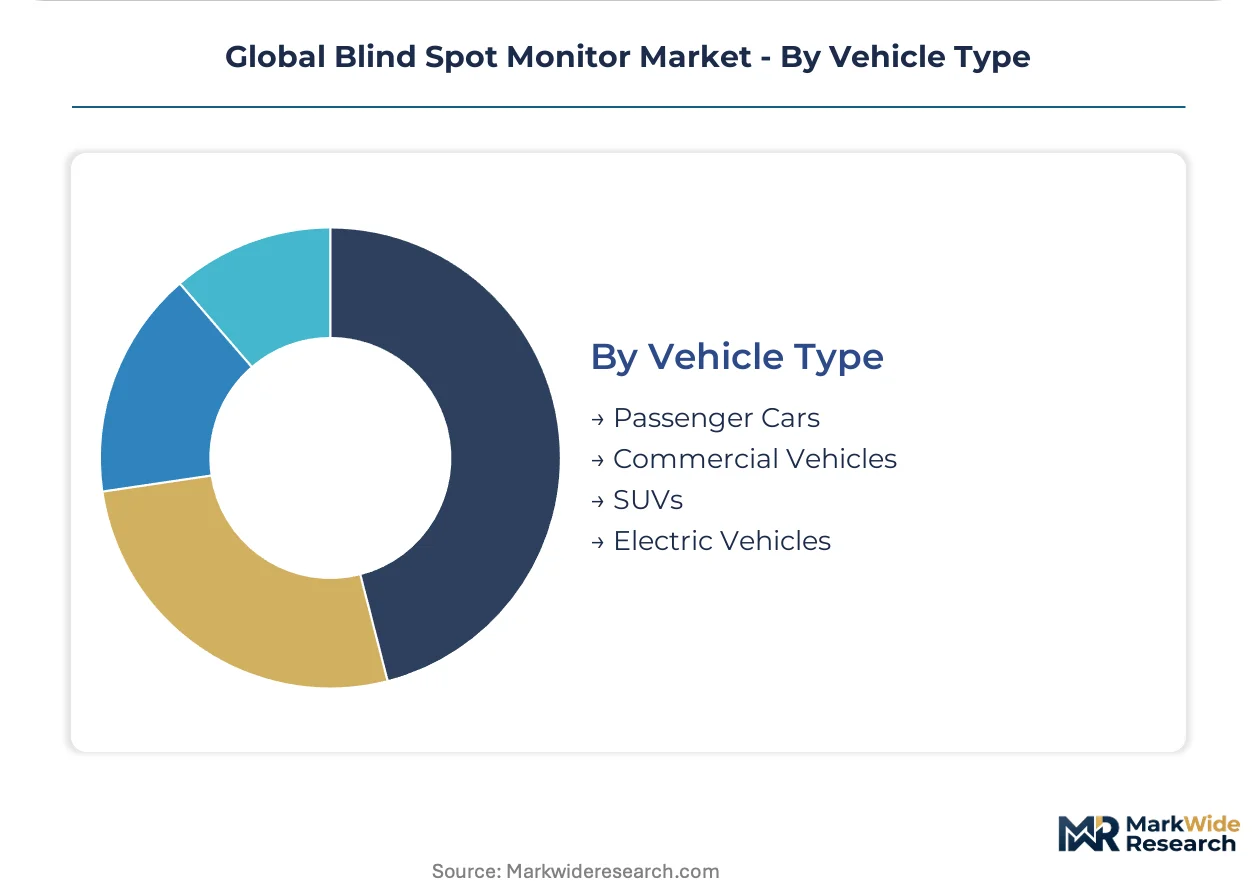
Vehicle Type:
Customer type separation between private ownership and commercial duty cycles drives divergent performance specifications and warranty terms.
- Commercial Vehicles:Heavy-duty trucks and buses face EU General Safety Regulation mandates for blind spot information systems. German manufacturers prioritize suppliers with REACH-compliant material portfolios.
- Passenger Cars:Mass-market OEMs balance cost sensitivity with NHTSA rating incentives, favoring camera-radar fusion architectures.
- SUVs:Larger blind spot zones and premium positioning support higher sensor count configurations.
- Electric Vehicles:Software-defined architectures enable over-the-air calibration updates and telematics-integrated event logging.
Regulatory tailwind: Commercial Vehicles. Technology integration frontier: Electric Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan command contrasting positions in the blind spot monitor supply chain, with German OEMs driving regulatory-mandated factory fitment while Japanese suppliers optimize compact sensor architectures for export markets.
United States
NHTSA five-star safety ratings incentivize passenger car OEMs to embed blind spot monitors within broader ADAS packages. California and Texas fleet operators negotiate consumption-based calibration schedules tied to mileage thresholds rather than fixed service intervals. Detroit's automotive engineering corridor concentrates radar module integration expertise for domestic truck manufacturers.
Germany
EU General Safety Regulation mandates eliminate aftermarket pathways for commercial vehicle OEMs serving German logistics operators. Stuttgart and Munich anchor Continental AG and Robert Bosch GmbH engineering centers where REACH-compliant material portfolios receive priority validation. KBA type-approval processes set the compliance benchmark for exporters across Central Europe.
Japan
MLIT alignment with UN ECE R151 streamlines certification for suppliers targeting Southeast Asian export markets. Denso Corporation and Hyundai Mobis Co., Ltd. optimize compact ultrasonic modules for tight packaging constraints on domestic vehicle platforms. Nagoya's Chubu region concentrates sensor fusion R&D facilities serving Toyota and Honda procurement networks.
China
Domestic EV manufacturers integrate blind spot monitors within software-defined vehicle architectures enabling over-the-air calibration updates. MIIT type-approval standards for intelligent connected vehicles create a parallel compliance pathway distinct from UN ECE frameworks. Shanghai's Yangtze River Delta cluster hosts radar semiconductor foundry capacity for automotive-grade substrate fabrication.
South Korea
Hyundai Mobis Co., Ltd. anchors domestic supply relationships with captive sensor fusion development for Hyundai-Kia vehicle platforms. Seoul Capital Area engineering centers specialize in 77 GHz radar module calibration protocols. MFDS automotive electronics certification requirements align with export market access strategies for European and North American OEM contracts.
Global Blind Spot Monitor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Tier-1 suppliers with multi-ADAS portfolios leverage sensor fusion architectures to amortize R&D across collision-avoidance functions. Three archetypes dominate: diversified automotive electronics conglomerates with captive semiconductor capabilities, pure-play sensor specialists optimizing single-modality performance, and vertically integrated chassis suppliers controlling mirror housing integration. Competitive moves concentrate on strategic partnerships for software-defined perception stacks and geographic expansion into Indian commercial vehicle retrofit channels.
Within the diversified conglomerate tier, ZF Friedrichshafen AG and Continental AG occupy positions spanning chassis systems through domain controller integration. Robert Bosch GmbH exemplifies the radar-centric archetype with semiconductor fabrication scale economies. Denso Corporation represents the compact module specialist optimizing for Asian OEM packaging constraints.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Robert Bosch GmbH |
| Aptiv PLC |
| Valeo SA |
| Continental AG |
| Autoliv Inc. |
| Hyundai Mobis Co., Ltd. |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Silicon germanium wafer spot indices in Taiwan and South Korea cascade through Tier-2 radar substrate suppliers into three-tier pricing structures across premium, standard, and economy levels. Contract manufacturers in these geographies pass foundry cost volatility to OEM procurement teams through quarterly adjustment clauses.
Pricing Analysis
Capacity additions in China are reshaping price floors for camera-based modules while radar configurations retain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates 77 GHz radar fusion from 24 GHz single-sensor and ultrasonic alternatives. Price differentiation hinges on ISO 26262 ASIL-B certification status and volume procurement scale. Cost compression in ultrasonic tiers is intensifying because Asian OEMs are consolidating sensor counts into surround-view bundles. Fleet operators in Germany exhibit lowest price sensitivity due to EU General Safety Regulation compliance deadlines, while Indian retrofit channels show acute cost responsiveness.
Supply Chain Analysis
Calibration technician shortages in Stuttgart and Nagoya constrain module final-assembly throughput despite upstream semiconductor availability. Automotive-grade radar fabrication draws from Taiwan, South Korea, and China, with 77 GHz semiconductor foundry capacity anchoring Tier-2 sourcing flexibility. Polyamide housing materials, CMOS image sensors, and ultrasonic transducers constitute critical component dependencies. Single-source vulnerability concentrates in silicon germanium wafer supply from TSMC-dominated foundry networks. Distribution runs through captive OEM supply agreements rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Blind Spot Monitor Market represents a late-cycle quality story as logistics operators shift procurement specifications toward REACH-compliant material portfolios and telematics-integrated event logging. Premium sensor fusion architectures command widening margin premiums over commodity ultrasonic alternatives.
For Market Incumbents: Anchor factory-fitment relationships through backward integration into 77 GHz semiconductor calibration protocols. Secure REACH-compliant polyamide housing supply chains ahead of European Chemicals Agency deadlines. Defend against solid-state LIDAR substitution by embedding radar-camera fusion within broader ADAS domain controller architectures. For New Entrants and Emerging Players: Indian commercial fleet retrofit channels offer concentrated white-space opportunity as the central transport regulator evaluates mandatory blind spot detection for inter-city buses. Target owner-operated truck segments in secondary Chinese cities lacking authorized dealer calibration infrastructure. Pursue software-defined vehicle platform partnerships enabling over-the-air calibration update revenue streams. For Investors and Strategic Acquirers: Asymmetric upside sits with compact module specialists possessing validated UN ECE R151 certification pathways and captive relationships with Japanese OEM export networks. Long-term viability favors suppliers integrating edge-computing system-on-chip architectures that reduce wiring harness complexity. Watch for LIDAR cost compression below critical volume thresholds as the inflection signal threatening radar incumbency.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Enables Denso and ZF to amortize R&D across parking assistance and highway-speed functions. |
| 77 GHz Semiconductor Backward Integration | Robert Bosch GmbH secures captive supply of automotive-grade radar substrates against foundry concentration risk. |
| REACH-Compliant Material Portfolio Certification | German truck manufacturers prioritize Continental AG to avoid European Chemicals Agency homologation delays. |
| Fleet Telematics Integration Partnership | Logistics operators in California specify blind spot event data logging as contract conditions. |
| Indian Commercial Vehicle Retrofit Channel Expansion | Opens aftermarket pathway absent in EU General Safety Regulation-mandated developed markets. |
Methodological Framework
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operations directors grounded qualitative assessments. Secondary validation drew from NHTSA safety rating protocols, EU General Safety Regulation documentation, UN ECE R151 type-approval standards, and vehicle production registration databases. Bottom-up sensor shipment tallies and top-down ADAS content-per-vehicle estimates were triangulated to reconcile volume figures.
Segment-level outputs across the analysis window reflect disaggregated modeling of product type, installation configuration, vehicle class, and regional production cluster dimensions. CAGRs were derived from regression-adjusted shipment trajectories incorporating semiconductor foundry capacity expansion schedules and regulatory mandate phase-in timelines. Radar module cost curves and LIDAR substitution elasticity parameters informed technology-transition assumptions.
Underlying measurement precision varies by segment; factory-fitted OEM channels carry tighter precision than fragmented aftermarket retrofit due to consolidated procurement visibility. Forecasts reflect documented assumptions regarding EU mandate enforcement timing and semiconductor supply normalization. Material deviation in solid-state LIDAR cost compression trajectories or Taiwan foundry geopolitical stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Micro-Electro Mechanical Systems Market