
 Vacuum Leak Detectors Market | 2026-2036
Vacuum Leak Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Leak Detectors Market Analytics
Helium detection sensitivity at 10^-9 Pa·m³/s is redrawing competitive benchmarks across the vacuum leak detectors landscape. INFICON leverages captive ion source technology to sustain leadership in high-vacuum semiconductor applications. Agilent Technologies anchors its position through mass spectrometry platforms that dominate pharmaceutical cleanroom validation protocols. Leybold GmbH competes via turbomolecular pumping systems that extend reach into fusion energy research installations.
Vacuum leak detectors are instruments that identify and quantify unintended gas ingress in sealed systems, typically employing helium as a tracer gas with mass spectrometry achieving detection thresholds below 10^-12 mbar·L/s. These devices ensure process integrity in semiconductor lithography, pharmaceutical freeze-drying, and aerospace propulsion testing where even microscopic breaches compromise safety or yield. Mass spectrometry detectors command premium positioning due to unmatched sensitivity requirements in nuclear and space applications, while helium detectors capture volume through faster cycle times in automotive air conditioning and industrial refrigeration. Ultrasonic detectors occupy a mature, cost-driven tier suited to compressed air and HVAC maintenance where pinpoint location matters more than quantification precision.
FDA 21 CFR Part 11 compliance requirements shape pharmaceutical adoption by mandating electronic records and audit trails for leak test validation data. EPA Section 608 refrigerant regulations and EU F-Gas Regulation phase-down schedules force automotive and HVAC sectors toward automated, traceable leak detection workflows. Semiconductor manufacturers navigating ISO 14644-1 and SEMI standards face escalating vacuum integrity specifications as node geometries shrink. Stakeholders must weigh capital intensity against regulatory exposure when selecting between portable field units and integrated inline systems.
Market Dynamics
Helium supply volatility and semiconductor node shrinkage are compressing detection cycle times while elevating sensitivity requirements across vacuum-dependent manufacturing processes.
Growth Catalysts
- EPA Section 608 refrigerant mandates:HVAC and automotive manufacturers in the United States must deploy automated leak detection systems to maintain compliance with tightened refrigerant management protocols.
- Semiconductor yield sensitivity:Taiwan and South Korean fabs are expanding helium leak detection programs to satisfy ISO 14644-1 cleanroom standards as lithography nodes advance below 3nm.
- EU F-Gas Regulation phase-down:European industrial refrigeration operators face compulsory leak inspection frequencies that drive replacement of manual sniffers with continuous monitoring systems.
Market Restraints
- Helium cost volatility:Global helium supply concentrates in Qatar and the United States, exposing detector operators to price swings that elevate total cost of ownership for mass spectrometry platforms.
- Technical sensitivity ceiling:Conventional helium detectors face fundamental limits near 10^-9 Pa·m³/s, constraining penetration into fusion energy research requiring 10^-12 mbar·L/s thresholds.
- Capital intensity barrier:Integrated inline systems for semiconductor fabs demand seven-figure investments that exclude smaller contract manufacturers from automated quality protocols.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with FDA 21 CFR Part 11 creates demand for validated leak detection systems in sterile injectable production facilities.
- Hydrogen economy infrastructure:Hydrogen fuel cell and storage applications require modified tracer gas protocols, opening adjacent demand for hydrogen-calibrated detection platforms.
- Service model convergence:Detector-as-a-service offerings bundling hardware, calibration, and compliance documentation are penetrating mid-tier automotive suppliers previously priced out of ownership.
Industry Challenges
- Calibration technician scarcity:Mass spectrometry maintenance demands specialized vacuum physics expertise that outpaces vocational training pipeline output in East Asian manufacturing clusters.
- Legacy system integration:Pharmaceutical freeze-drying lines built to 1990s specifications require costly retrofitting to accommodate digital audit trails mandated by FDA 21 CFR Part 11.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Leak Detectors Market |
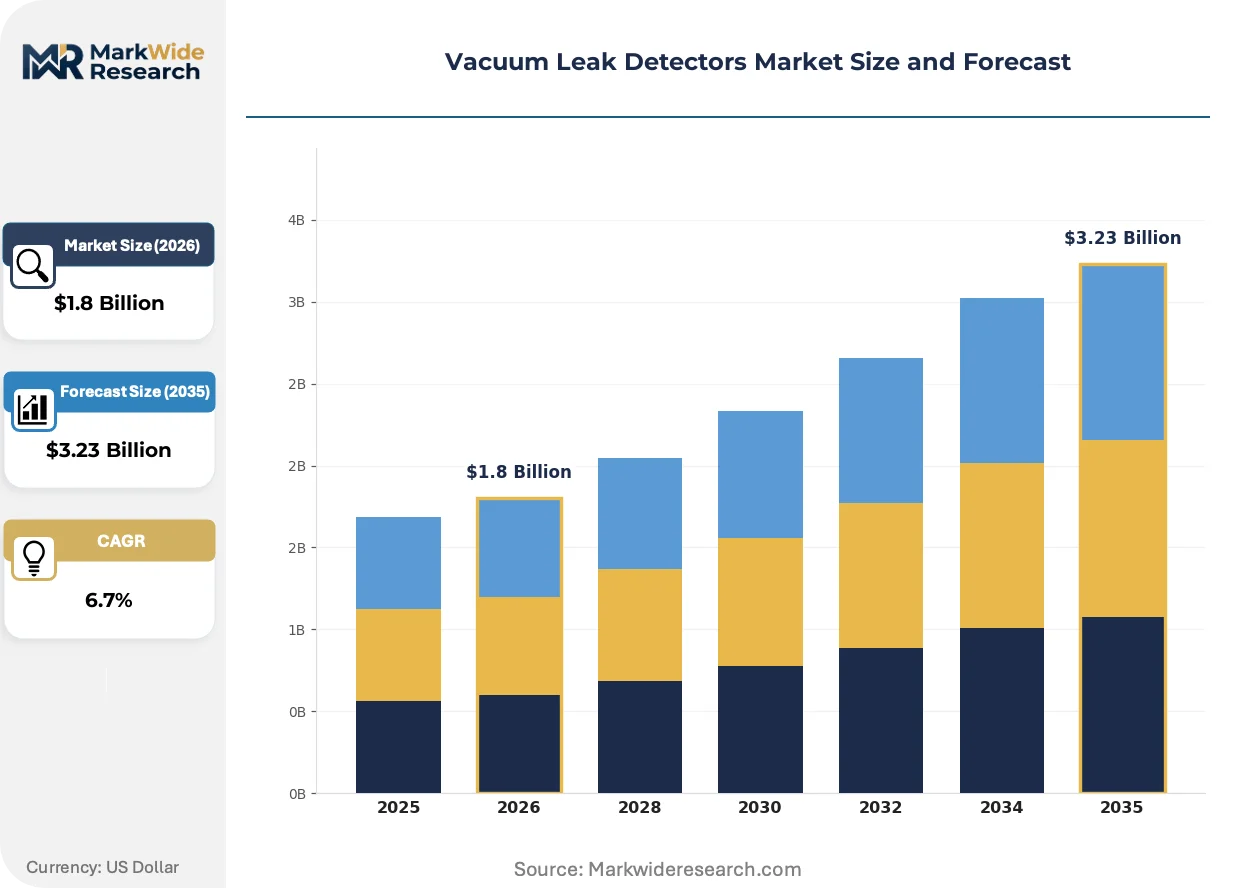
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Detectors, Ultrasonic Detectors, Mass Spectrometry, Helium Detectors Technology: Optical, Acoustic, Vacuum Pump Technology, Laser-based End User: Aerospace, Automotive, Pharmaceutical, Food Processing Application: Research Facilities, Manufacturing, Quality Control, Packaging |
| Companies Covered | INFICON, Agilent Technologies, Leybold GmbH, Pfeiffer Vacuum, Edwards Vacuum, ATEQ Corporation, Cincinnati Test Systems, Vacuum Instruments Corporation, Furness Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Leak Detectors Market Evolving Landscape
Detection methodology is fragmenting along sensitivity-versus-speed tradeoffs, with divergent technology paths serving semiconductor precision and industrial throughput respectively.
Quadrupole mass spectrometry is bifurcating the high-performance segment. Semiconductor lithography tool vendors in Taiwan and South Korea specify 10^-12 mbar·L/s detection thresholds for EUV vacuum chambers. This capability compression is marginalizing residual gas analyzers in sub-5nm node qualification workflows.
REACH and EU F-Gas Regulation amendments are accelerating refrigerant tracer gas diversification. Industrial HVAC manufacturers face mandatory leak rate documentation for systems above 3kg charge. This compliance pressure is stimulating hydrogen and forming gas detector adoption in European automotive air conditioning assembly plants.
After-sales service unbundling is disrupting traditional equipment procurement. Japanese pharmaceutical manufacturers now separately contract calibration and validation services rather than accepting bundled maintenance. This purchasing pattern shift concentrates service revenue with third-party metrology specialists in Osaka and Tokyo pharmaceutical clusters.
Vacuum Leak Detectors Market Segmentation
Segmentation in vacuum leak detection equipment separates sensitivity-driven premium systems from throughput-optimized industrial units. Technology choices cascade into compliance obligations, calibration requirements, and total cost structures that reshape procurement patterns across semiconductor, pharmaceutical, and automotive verticals.
Product Type:
Mass spectrometry and helium detector segments face acute substitution pressure from emerging hydrogen tracer protocols, while ultrasonic and electronic alternatives compete on capital efficiency in less regulated applications.
- Mass Spectrometry:Quadrupole and magnetic sector instruments achieve detection thresholds below 10^-12 mbar·L/s through ion source and electron multiplier architectures. EUV lithography tool vendors in Taiwan and South Korea specify these systems for sub-3nm node vacuum chamber qualification where yield sensitivity mandates absolute leak quantification.
- Helium Detectors:Sniffer and hard vacuum configurations exploit helium's low atmospheric abundance and high ionization efficiency to balance speed against sensitivity. Semiconductor fabs across Hsinchu and Pyeongtaek expand fleet deployments to satisfy ISO 14644-1 cleanroom standards, though helium supply volatility from Qatar and US sources elevates operating cost uncertainty.
- Electronic Detectors:Thermal conductivity and infrared absorption platforms target compressed air and HVAC maintenance where leak location speed outweighs quantification precision.
- Ultrasonic Detectors:Heterodyne frequency translation devices convert turbulent gas escape into audible signals for rapid field diagnostics in refrigeration and compressed gas distribution networks.
Helium detectors retain volume leadership; mass spectrometry holds the steepest expansion curve.
Technology:
Cost tier stratification separates laser-based precision platforms from acoustic and optical alternatives suited to mid-market budgets and maintenance workflows.
- Laser-based:Tunable diode laser absorption spectroscopy achieves non-contact, non-destructive leak detection with ppb-level sensitivity for hydrogen and methane tracer gases. Fusion energy research installations in France and Japan specify these systems for tokamak vacuum vessel integrity verification where conventional helium methods face access constraints.
- Vacuum Pump Technology:Turbomolecular and cryogenic pumping configurations establish the pressure differential foundation for high-vacuum detection protocols. Semiconductor equipment OEMs integrate these subsystems into inline process tools to eliminate external pumping infrastructure and reduce footprint in cleanroom environments.
- Optical:LED and infrared imaging systems visualize refrigerant escape through fluorescence or thermal contrast for rapid HVAC assembly line screening.
- Acoustic:Airborne and structure-borne ultrasonic sensors detect turbulent flow signatures without tracer gas consumption, serving compressed air audit and steam trap maintenance applications.
Vacuum pump technology anchors revenue concentration; laser-based platforms are climbing the fastest.
End User:
Application maturity varies sharply, with pharmaceutical and automotive sectors facing the most intensive regulatory documentation requirements while aerospace maintains the most stringent performance specifications.
- Pharmaceutical:FDA 21 CFR Part 11 and EMA Annex 15 compliance mandates electronic records and audit trails for leak test validation in sterile injectable and lyophilized product manufacturing. Freeze-drying equipment operators in Ireland and Switzerland retrofit legacy lines with digital detection systems to satisfy regulatory inspection protocols.
- Automotive:EPA Section 608 and EU F-Gas Regulation enforcement compels air conditioning assembly plants toward automated helium or hydrogen leak detection with traceable documentation. Electric vehicle battery pack sealing validation creates adjacent demand for high-sensitivity detection in cell and module production facilities.
- Aerospace:Propulsion system and satellite payload testing requires 10^-9 Pa·m³/s sensitivity thresholds for mission-critical vacuum integrity verification.
- Food Processing:Modified atmosphere packaging line validation employs cost-optimized sniffers to ensure seal integrity in high-speed tray and pouch forming operations.
Automotive applications dominate unit volume; pharmaceutical end use shows the steepest expansion trajectory.
Application:
Customer type differentiation separates capital-intensive inline manufacturing integration from portable field service and laboratory research procurement patterns.
- Manufacturing:Inline vacuum leak detection systems integrate directly into semiconductor lithography, pharmaceutical freeze-drying, and automotive HVAC assembly lines for 100% production screening. Seven-figure capital investments exclude smaller contract manufacturers, concentrating automated quality protocols among tier-one fabs and OEMs.
- Quality Control:Statistical sampling protocols in pharmaceutical release testing and aerospace component qualification demand calibrated, traceable detection with documented measurement uncertainty.
- Research Facilities:National laboratories and university physics departments operate custom detection configurations for fusion energy, particle accelerator, and space simulation vacuum system development.
- Packaging:High-speed leak testing of pharmaceutical vials, medical devices, and food containers employs pressure decay and vacuum decay methods with cycle time optimization for throughput-critical lines.
Manufacturing integration captures the largest revenue share; research facility procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium supply chains concentrate in Qatar and the United States, creating procurement dependencies that reshape detector deployment economics across manufacturing clusters worldwide.
United States
EPA Section 608 refrigerant mandates compel HVAC and automotive assembly plants toward automated leak detection systems with traceable documentation. Domestic helium extraction from the Federal Helium Reserve and Wyoming fields supports semiconductor fabs in Arizona and Texas expanding EUV lithography programs. The EPA enforces tightened refrigerant management protocols that elevate compliance costs for manual detection methods.
Taiwan
TSMC and UMC fabs in Hsinchu and Tainan drive demand for 10^-12 mbar·L/s sensitivity thresholds in sub-3nm node qualification workflows. ISO 14644-1 cleanroom standards enforce escalating vacuum integrity specifications as lithography geometries shrink. The Industrial Technology Research Institute coordinates domestic detector calibration infrastructure to reduce foreign equipment dependency.
Germany
Automotive OEMs in Stuttgart and Munich retrofit air conditioning assembly lines for hydrogen and forming gas detection protocols under EU F-Gas Regulation phase-down schedules. BASF and Merck pharmaceutical operations in Ludwigshafen and Darmstadt demand FDA 21 CFR Part 11 compliant validation systems for sterile injectable production. The Federal Environment Agency enforces mandatory leak inspection frequencies that displace manual sniffers.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Icheon expand helium leak detection fleets to satisfy SEMI vacuum standards for advanced memory manufacturing. The Ministry of Trade, Industry and Energy funds domestic turbomolecular pumping development to reduce Japanese equipment reliance. Electric vehicle battery pack sealing validation creates adjacent demand in Ulsan automotive clusters.
Japan
Pharmaceutical manufacturers in Osaka and Tokyo unbundle after-sales service contracts, concentrating calibration revenue with third-party metrology specialists. METI supports fusion energy research at Naka and Rokkasho requiring 10^-9 Pa·m³/s detection thresholds for tokamak vacuum vessel integrity. Domestic detector vendors face margin pressure from Taiwanese and Korean equipment imports.
Vacuum Leak Detectors Market Competitive Landscape
Concentration sits with diversified vacuum technology conglomerates and specialized semiconductor equipment suppliers. The vendor base stratifies across three tiers: integrated platform providers commanding seven-figure fab installations, mid-scale system integrators serving automotive and pharmaceutical verticals, and regional calibration service specialists. Competitive dynamics center on technology licensing agreements and captive ion source development rather than price-based rivalry. Geographic expansion through distributor networks and strategic partnerships with lithography tool vendors represent dominant competitive moves.
Within the diversified vacuum technology tier, INFICON, Agilent Technologies, and Leybold GmbH exemplify contrasting strategic positions. INFICON anchors Swiss precision instrumentation heritage through captive technology development. Agilent Technologies occupies a position bridging analytical instrumentation and semiconductor process control. Leybold GmbH represents German engineering consolidation in turbomolecular pumping and high-vacuum system integration. These three entities collectively demonstrate how geographic origin and corporate structure shape competitive archetype formation in detector manufacturing.
| Leading Market Players |
|---|
| INFICON |
| Agilent Technologies |
| Leybold GmbH |
| Pfeiffer Vacuum |
| Edwards Vacuum |
| ATEQ Corporation |
| Cincinnati Test Systems |
| Vacuum Instruments Corporation |
| Furness Controls |
| Others |
Value Network & Pricing Analysis
Capacity utilization at turbomolecular pumping fabs in Germany and Japan sits above 85%, compressing lead times for semiconductor-grade detection systems and elevating price floors for integrated inline configurations. This scale concentration reinforces supplier pricing power while forcing mid-tier buyers toward detector-as-a-service models that externalize capital intensity.
Pricing Analysis
EPA Section 608 dictates the pricing tier structure across the United States HVAC and automotive assembly plant segments. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry platforms with 21 CFR Part 11 compliance from hard vacuum helium units and portable sniffers. Price differentiation hinges on ISO 14644-1 certification grade and after-sales calibration bundling. Cost compression in the standard tier is intensifying because helium supply volatility from Qatar fields elevates operating expenditure uncertainty. Contract manufacturers in East Asia exhibit the highest price sensitivity; EU pharmaceutical operations show the lowest due to regulatory non-negotiability.
Supply Chain Analysis
Inventory cycles for ion source assemblies and electron multipliers extend 16-20 weeks, constraining rapid fleet expansion by semiconductor fabs in Taiwan and South Korea. Manufacturing concentration rests on Germany, Switzerland, and Japan for precision pumping subsystems and mass spectrometer cores. Raw material dependencies center on rare earth magnets for turbomolecular rotors, high-purity helium tracer gas, and specialized ceramics for vacuum chambers. Single-source vulnerability pervades the electron multiplier supply channel where one Japanese component supplier dominates global output. Distribution runs through lithography tool OEMs for inline systems and third-party metrology specialists for calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum physics expertise for mass spectrometry maintenance outpaces vocational training output in East Asian manufacturing clusters, creating persistent capability gaps that reshape competitive entry barriers and acquisition premiums.
For Market Incumbents: Fortify captive ion source technology development to sustain differentiation against quadrupole mass spectrometry substitution from analytical instrumentation vendors. Expand calibration infrastructure in Hsinchu and Pyeongtaek to reduce service revenue leakage toward third-party metrology specialists. Capacity addition in Taiwan addresses the technician scarcity threat while reinforcing channel control over semiconductor fab accounts. For New Entrants and Emerging Players: FDA 21 CFR Part 11 certification fast-track opens pharmaceutical freeze-drying retrofit opportunities in Ireland and Switzerland where legacy line integration demands mid-tier system integrators. White-space concentration sits with hydrogen-calibrated detection platforms for fuel cell sealing validation in Ulsan and Stuttgart automotive clusters. Target pharmaceutical contract manufacturing organizations with validation-documentation bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors turbomolecular pumping subsystem specialists with semiconductor equipment OEM relationships over standalone detector assembly operations. Long-term viability hinges on fusion energy research procurement scaling and EUV lithography node advancement sustaining 10^-12 mbar·L/s sensitivity demand. The acquisition target archetype combines vacuum pump technology with established pharmaceutical validation protocols. Watch helium supply contract renegotiation cycles as the inflection indicator for operating margin compression across mass spectrometry platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ion Source Development | INFICON and Agilent sustain semiconductor fab dominance through proprietary electron multiplier architectures. |
| Calibration Infrastructure Expansion | Third-party metrology specialists in Osaka and Tokyo capture unbundled pharmaceutical service contracts from OEMs. |
| Hydrogen Detection Protocol Adaptation | EU F-Gas Regulation phase-down forces Stuttgart automotive OEMs toward forming gas tracer alternatives. |
| Detector-as-a-Service Launch | Mid-tier automotive suppliers in Ulsan access automated quality protocols without seven-figure capital deployment. |
| Pharmaceutical Validation Documentation Bundling | CDSCO alignment with FDA 21 CFR Part 11 creates sterile injectable production demand in Indian manufacturing clusters. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor fab process engineers, pharmaceutical quality assurance directors, HVAC assembly plant maintenance managers, and vacuum equipment procurement leads and refined through secondary validation. Primary fieldwork encompassed 40+ structured interviews across Hsinchu, Pyeongtaek, Stuttgart, and Osaka manufacturing clusters. Secondary sources included SEC 10-K filings from listed vacuum technology conglomerates, EPA Section 608 enforcement documentation, EU F-Gas Regulation amendment texts, and SEMI standards publications. Bottom-up unit economics from equipment procurement databases were triangulated against top-down market sizing from customs trade flows in turbomolecular pumping subsystems.
Variance decomposition across technology segments, end-use verticals, and geographic manufacturing clusters anchored the analytical framework throughout the projection horizon. Segmentation dimensions encompassed detection methodology, sensitivity tier, compliance certification level, and regional regulatory enforcement intensity. CAGRs were derived from installed base expansion rates, replacement cycle compression, and sensitivity requirement escalation at sub-3nm semiconductor nodes. Industry-specific forecast inputs included EUV lithography tool deployment schedules and helium supply contract pricing trajectories from Qatar and Wyoming sources.
Decision-makers should treat outputs as directional under assumptions of continued EPA Section 608 enforcement, EU F-Gas Regulation phase-down adherence, and semiconductor node advancement below 3nm; material deviation in helium supply geopolitics or fusion energy research funding would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Pedestrian Detection System Market