
 Europe Fingerprint Sensor Market | 2026-2036
Europe Fingerprint Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fingerprint Sensor Market Foresight
Silicon is consolidating its position as the dominant substrate material across capacitive and ultrasonic sensor architectures, displacing legacy glass-and-coil constructions that carried higher per-unit assembly costs. Fingerprint Cards AB leverages vertical integration across ASIC design and module packaging to sustain cost leadership in high-volume smartphone contracts. IDEX Biometrics anchors its competitive position through flexible polymer substrate expertise that differentiates its offerings in wearable payment form factors. Thales SA dominates the government and civil ID vertical through certified secure-element integration that meets Common Criteria EAL thresholds.
A fingerprint sensor converts ridge-and-valley skin topography into an electrical or optical signal for identity verification, typically achieving resolutions of 500 dots per inch or higher to satisfy ISO/IEC 19794-2 minutiae-extraction standards. The device serves as the front-end acquisition component in biometric authentication chains spanning mobile unlock, physical access control, and payment authorization workflows. Capacitive sensors retain the largest installed base across consumer electronics due to decades of process refinement and foundry scale, though ultrasonic modules are gaining structural momentum in premium handsets where sub-surface imaging defeats spoof attempts through gelatin or latex overlays. Banking and government end-user segments command superior margin pools compared to commoditized consumer electronics volumes, reflecting stringent certification requirements and longer contract tenors.
REACH compliance and RoHS substance restrictions govern material selection and hazardous-substance thresholds for sensors manufactured or imported into European Economic Area member states. The EU AI Act's biometric identification provisions impose conformity-assessment obligations that filter market access for vendors lacking notified-body certification. GDPR data-protection rules shape sensor-system architecture by mandating on-device template storage and limiting centralized biometric database proliferation. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national cybersecurity certification schemes in France, Germany, and Italy that could fragment compliance requirements across the continent's procurement landscape.
Market Dynamics
EU AI Act conformity-assessment obligations are compressing vendor certification timelines and filtering market access for biometric identification systems deployed across European banking and government verticals.
Growth Catalysts
- EU AI Act compliance mandates:Risk-based classification frameworks for biometric systems accelerate procurement cycles among sensor vendors seeking notified-body certification for high-stakes applications.
- Automotive fleet management integration:German OEMs embed fingerprint modules into vehicle access and driver authentication systems, creating sustained module demand from industrial automation suppliers.
- Capacitive sensor foundry scale:Decades of process refinement across Taiwanese and European semiconductor fabs sustain cost competitiveness for high-volume consumer electronics contracts.
Market Restraints
- Silicon substrate cost volatility:Wafer pricing fluctuations from concentrated East Asian foundry capacity squeeze margin pools for mid-tier sensor vendors lacking long-term supply agreements.
- Ultrasonic module technical limitations:Sub-surface imaging architectures require thicker cover glass and higher power budgets, constraining adoption in ultra-thin wearable form factors.
- GDPR template storage mandates:On-device biometric data residency requirements increase ASIC complexity and memory footprint, elevating per-unit hardware costs against centralized alternatives.
Strategic Opportunities
- Italian industrial automation corridors:Lombardy and Emilia-Romagna manufacturing clusters show underpenetrated demand for secure access control in pharmaceutical and precision engineering facilities.
- Convergence of fingerprint and secure-element technologies:Common Criteria EAL-certified integration opens government ID and payment card verticals previously served by discrete component architectures.
- French national cybersecurity certification schemes:ANSSI-led qualification pathways create first-mover advantages for vendors achieving domestic security approval ahead of harmonized EU standards.
Industry Challenges
- Biometric algorithm engineer scarcity:Minutiae-extraction and liveness-detection expertise concentrates among a small pool of specialists, inflating compensation costs for R&D teams.
- Common Criteria EAL certification timelines:Government and civil ID contracts require 12-24 month evaluation periods, locking working capital and delaying revenue recognition.
- Legacy physical access control retrofit complexity:Existing Wiegand and OSDP infrastructure in European commercial buildings demands middleware development for seamless biometric integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fingerprint Sensor Market |
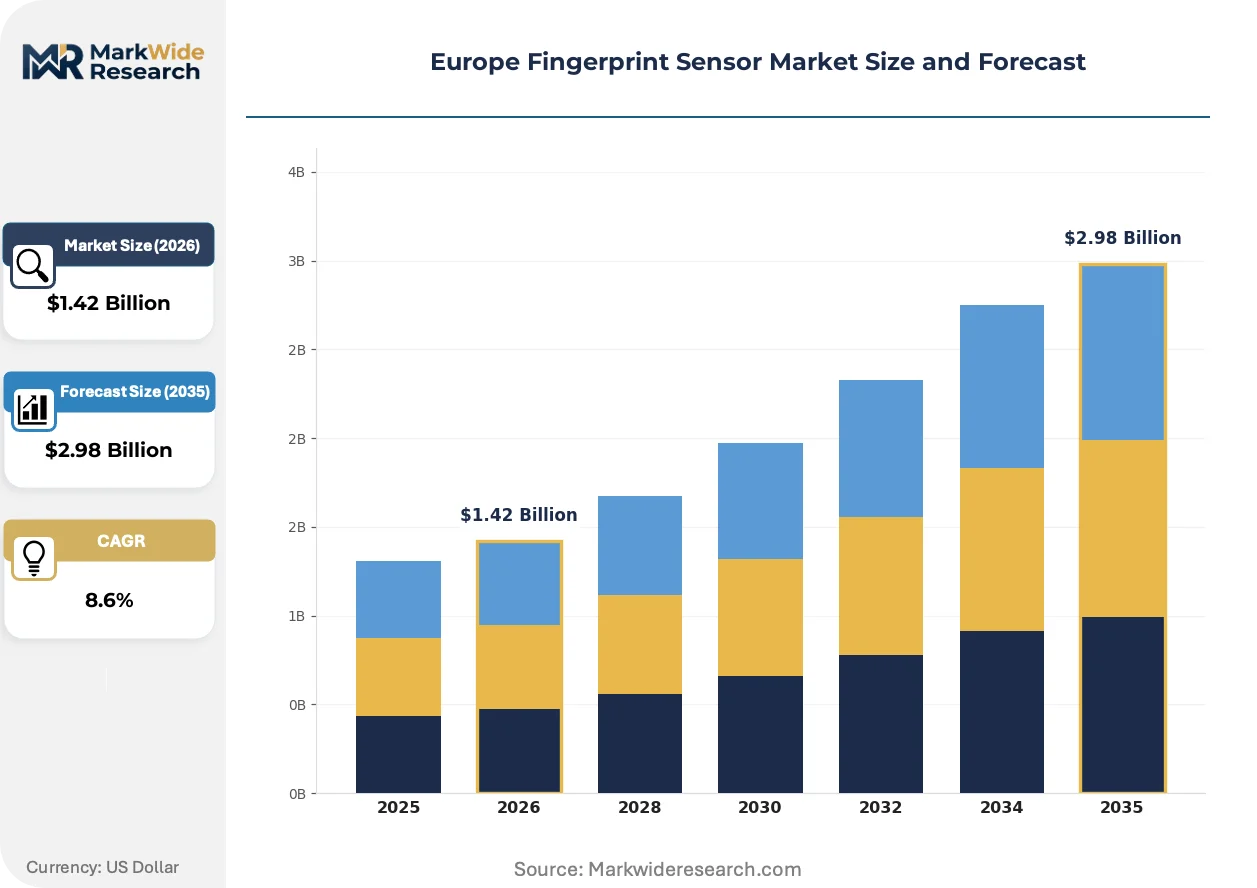
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Optical, Ultrasonic, Thermal Technology: Fingerprint Scanners, Sensor Modules, Smart Sensors, Biometric Systems End User: Consumer Electronics, Banking, Government, Healthcare Application: Mobile Devices, Access Control, Payment Systems, Time Management |
| Companies Covered | Fingerprint Cards AB, IDEX Biometrics, Thales SA, Dermalog Identification Systems GmbH, Jenetric GmbH, STMicroelectronics NV, Synaptics Incorporated, NEXT Biometrics Group, IDEMIA France SAS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fingerprint Sensor Market Shifts & Advancements
Silicon substrate dominance, regulatory compliance automation, and procurement model evolution are restructuring how fingerprint sensors reach end-users across European banking, automotive, and government sectors.
Ultrasonic sensing architecture is decentralizing biometric acquisition from smartphone bezels to full-display and rear-panel configurations. German automotive suppliers adopt these modules for steering-column and center-console integration. The technology compresses design constraints that previously fragmented sensor placement across vehicle interiors.
REACH substance restrictions and RoHS hazardous-material thresholds are tightening material selection for sensors manufactured or imported into European Economic Area member states. ECHA enforcement actions against non-compliant suppliers accelerate vendor transitions to halogen-free substrates and lead-free solder processes. Industrial automation and medical device segments face the steepest compliance adaptation costs due to legacy supply chain entrenchment.
Banking procurement departments are consolidating biometric authentication contracts under framework agreements with pre-certified sensor vendors. Tier-one financial institutions in France and Spain bypass traditional distribution channels to negotiate direct module supply with manufacturers holding EU AI Act conformity documentation. This concentration shifts pricing power toward vendors with vertical control over ASIC design and secure-element integration capabilities.
Europe Fingerprint Sensor Market Segmentation
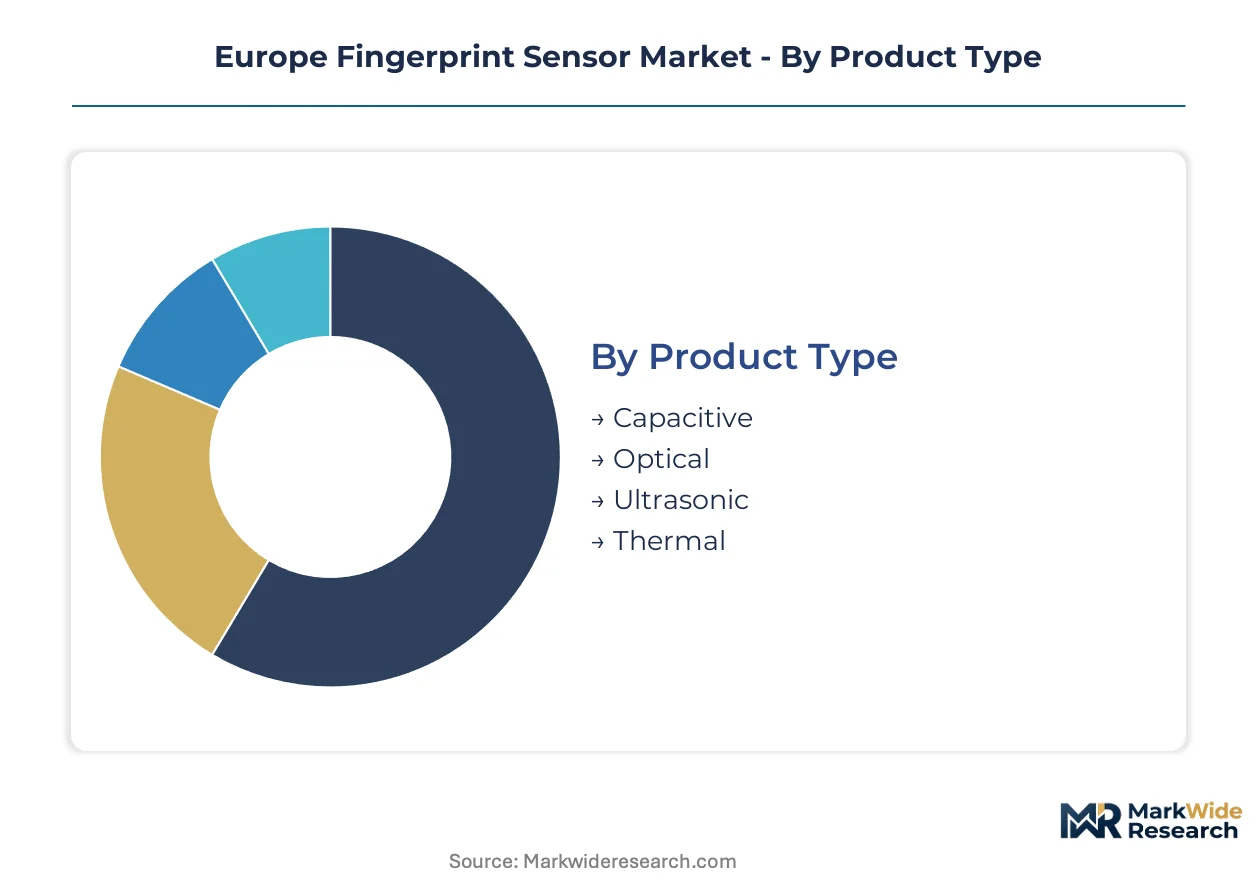
Technology architecture and compliance requirements fragment the Europe fingerprint sensor market into distinct procurement channels. Vendors must align substrate engineering, certification pathways, and integration protocols to each segment's technical and regulatory thresholds.
Product Type:
Substrate physics and manufacturing economics differentiate sensor architectures across European banking, automotive, and consumer verticals.
- Capacitive:Silicon-based capacitive arrays measure ridge-to-valley capacitance differentials through direct skin contact, achieving sub-100ms acquisition speeds. German automotive OEMs embed these modules into steering-column authentication systems, prioritizing the technology's proven reliability in high-vibration environments. Foundry scale across Taiwanese and European semiconductor fabs sustains cost competitiveness for high-volume contracts.
- Ultrasonic:Piezoelectric transducers emit acoustic pulses that penetrate sub-surface skin layers, defeating spoof attempts through gelatin or latex overlays. Premium smartphone manufacturers in France and Spain specify ultrasonic modules for full-display integration, accepting thicker cover glass and higher power budgets. EU AI Act conformity documentation accelerates procurement cycles for biometric identification systems using this architecture.
- Optical:CMOS-based optical imaging captures ridge patterns through prism-based total internal reflection, constrained by surface contamination sensitivity in industrial settings.
- Thermal:Pyroelectric sensors detect temperature differentials between ridges and air gaps, finding niche deployment in low-power access control terminals.
Capacitive leads on scale; ultrasonic leads on momentum.
Technology:
System integration depth determines margin capture across component, module, and full-stack procurement tiers.
- Fingerprint Scanners:Discrete imaging engines output raw ridge-pattern data to host processors, serving legacy access control retrofit projects. Italian pharmaceutical manufacturers specify scanner-only procurement for middleware-flexible integration into existing Wiegand infrastructure.
- Sensor Modules:ASIC-packaged units with embedded minutiae-extraction firmware dominate smartphone and payment terminal volumes. Module vendors with vertical control over design and secure-element integration capture framework agreements from tier-one French and Spanish banks.
- Smart Sensors:Edge-processing architectures execute template matching on-device, satisfying GDPR biometric data residency mandates without host processor dependency.
- Biometric Systems:Turnkey enrollment-to-authentication platforms bundle sensors, algorithms, and management software for government ID and civil registry contracts requiring Common Criteria EAL certification.
Sensor modules concentrate volume; biometric systems concentrate value.
End User:
Certification stringency and contract tenor separate commoditized consumer volumes from premium institutional procurement.
- Banking:Payment terminal and branch access deployments demand EU AI Act conformity assessment and PSD2 strong customer authentication alignment. Pre-certified sensor vendors negotiate direct supply contracts with procurement departments, bypassing traditional distribution channels.
- Government:National ID, civil registry, and border control systems require 12-24 month Common Criteria EAL evaluation periods, locking working capital but securing multi-year revenue tenors.
- Consumer Electronics:Smartphone and laptop manufacturers drive high-volume, price-sensitive demand with compressed product cycles and limited certification overhead.
- Healthcare:Medical device authentication and patient identity management face steep REACH and RoHS adaptation costs due to legacy supply chain entrenchment.
Banking leads on procurement velocity; government leads on contract duration.
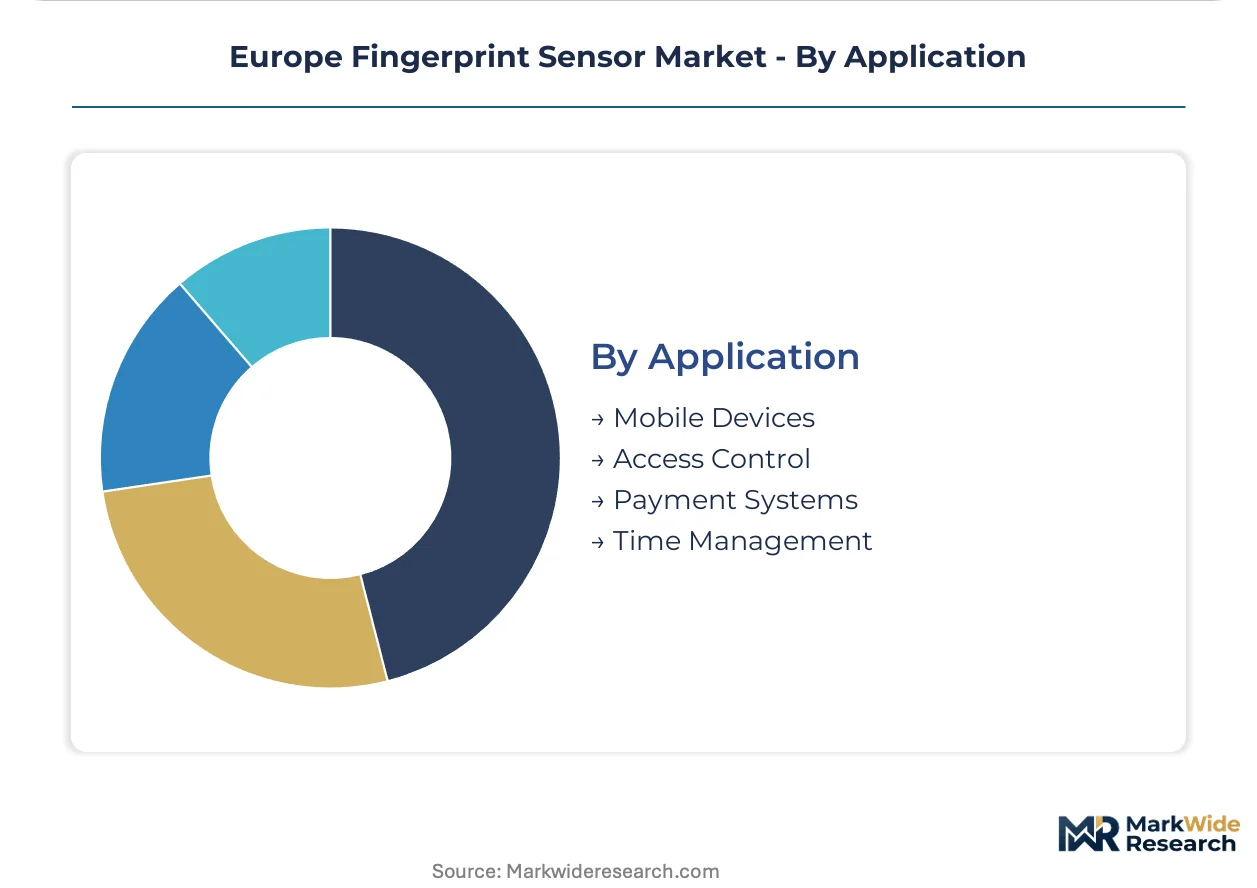
Application:
Integration context shapes power budgets, form factor constraints, and security architecture across deployment scenarios.
- Mobile Devices:Smartphone and tablet integration demands sub-millimeter z-height profiles and full-display compatibility. Ultrasonic architectures displace capacitive sensors in premium handsets where sub-surface imaging defeats presentation attacks.
- Access Control:Physical entry systems for commercial buildings and industrial facilities require middleware development for seamless integration with legacy Wiegand and OSDP infrastructure.
- Payment Systems:POS terminals and wearable form factors prioritize liveness detection and secure-element integration to meet PCI DSS and EU AI Act biometric identification thresholds.
- Time Management:Workforce attendance tracking systems emphasize cost minimization and rapid enrollment throughput over advanced anti-spoofing capabilities.
Mobile devices lead on unit volume; payment systems lead on security specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridors anchor European fingerprint sensor procurement, with OEMs embedding biometric modules into fleet management and driver authentication systems. The continent's regulatory fragmentation between EU harmonized standards and emerging national cybersecurity schemes shapes vendor market access strategies across procurement landscapes.
Germany
Automotive OEMs in Stuttgart and Munich drive biometric integration into vehicle access systems, while industrial automation suppliers in Baden-Württemberg embed sensors into secure manufacturing environments. The KBA oversees vehicle-type approval processes that increasingly incorporate biometric authentication standards. Bavarian precision engineering clusters around Ingolstadt and Nuremberg represent the continent's densest concentration of fingerprint module deployments for factory floor access control.
France
Tier-one banking institutions in Paris bypass traditional distribution channels to negotiate direct sensor supply contracts with pre-certified vendors. ANSSI-led national cybersecurity certification schemes create qualification pathways that filter market access ahead of harmonized EU standards. The Île-de-France financial services corridor concentrates demand for payment terminal and branch access biometric systems requiring EU AI Act conformity documentation.
Italy
Pharmaceutical manufacturers in Lombardy and precision engineering facilities in Emilia-Romagna show underpenetrated demand for secure access control systems. REACH substance restrictions and RoHS hazardous-material thresholds govern material selection for sensors imported into Italian manufacturing operations. Milan's industrial automation corridor represents an emerging procurement node for middleware-flexible biometric integration into existing Wiegand infrastructure.
United Kingdom
London-based financial services procurement departments consolidate biometric authentication contracts under framework agreements with pre-certified vendors. GDPR data-protection rules shape sensor-system architecture by mandating on-device template storage for UK banking deployments. The Southeast England technology corridor hosts middleware developers bridging legacy physical access control infrastructure with modern biometric systems.
Spain
Banking procurement concentration in Madrid accelerates direct manufacturer negotiations for payment terminal biometric modules. Spanish financial institutions prioritize EU AI Act conformity assessment alignment in vendor selection criteria. Barcelona's electronics manufacturing ecosystem supports module assembly operations serving Southern European consumer electronics and payment system demand.
Europe Fingerprint Sensor Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek notified-body certification alignment for EU AI Act compliance. The market exhibits tiered concentration, with a handful of vertically integrated specialists commanding premium procurement channels while mid-tier vendors compete on foundry scale for commoditized consumer volumes. Three archetypes define competitive positioning: ASIC-design-integrated module suppliers, flexible-substrate specialists for wearable form factors, and secure-element-integrated government ID vendors. Technology licensing agreements and backward integration into semiconductor fabrication represent the dominant competitive moves reshaping vendor capabilities.
Among Nordic-origin biometric specialists, Fingerprint Cards AB and IDEX Biometrics occupy distinct positioning archetypes, with the former exemplifying cost leadership through captive supply of ASIC design and module packaging, and the latter representing flexible polymer substrate expertise for emerging wearable payment applications. Thales SA anchors the government and civil ID vertical through certified secure-element integration capabilities. Dermalog Identification Systems GmbH and Jenetric GmbH exemplify German-engineered precision in industrial and government authentication systems. STMicroelectronics NV and Synaptics Incorporated represent scale-driven semiconductor fabricators with foundry relationships spanning Taiwanese and European production capacity.
| Leading Market Players |
|---|
| Fingerprint Cards AB |
| IDEX Biometrics |
| Thales SA |
| Dermalog Identification Systems GmbH |
| Jenetric GmbH |
| STMicroelectronics NV |
| Synaptics Incorporated |
| NEXT Biometrics Group |
| IDEMIA France SAS |
| Others |
Supply & Pricing Matrix
Biometric algorithm engineer scarcity concentrated in Nordic and German R&D clusters widens labor-cost differentials between premium certified-module suppliers and economy-tier scanner vendors. These workforce premiums translate directly into pricing-tier spreads across European banking and government procurement channels.
Pricing Analysis
Wafer pricing fluctuations from concentrated East Asian foundry capacity pass through unevenly to module vendors lacking long-term supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates Common Criteria EAL-certified biometric systems from middleware-flexible scanner engines and commodity capacitive modules. Cost compression in mid-tier sensor modules is intensifying because silicon substrate volatility squeezes margin pools for vendors without captive fab access. Consumer electronics OEMs exhibit highest price sensitivity, while government ID contractors accept extended payment tenors for certified integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive OEMs and French banking consortiums, while distribution partners serve fragmented industrial automation accounts. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany, with ASIC design dependencies resting on photolithography equipment and specialty substrate materials. Single-source vulnerability around piezoelectric transducer supply for ultrasonic architectures creates procurement risk for premium handset manufacturers. Distribution runs through authorized component distributors for smaller Italian and Spanish industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe fingerprint sensor market functions as a regulatory compounder where EU AI Act conformity-assessment obligations accelerate procurement cycles and filter vendor access across banking and government verticals.
For Market Incumbents: Anticipate margin compression from ultrasonic module technical limitations constraining ultra-thin wearable adoption, and respond through backward integration into secure-element design to capture Common Criteria EAL-certified contract premiums. Deepen foundry partnerships in Taiwan and Germany to lock wafer supply against silicon cost volatility threatening mid-tier positioning. For New Entrants and Emerging Players: EU AI Act biometric identification provisions in the European Economic Area open a window for specialist vendors achieving notified-body certification ahead of harmonized standards. Target Italian pharmaceutical manufacturing clusters in Lombardy and Emilia-Romagna showing underpenetrated demand for middleware-flexible access control integration. Pursue direct procurement relationships with tier-one French and Spanish banks consolidating framework agreements. For Investors and Strategic Acquirers: Valuations sit cheapest among flexible-substrate specialists with polymer expertise for wearable payment form factors, a segment drawing accelerating interest from automotive and healthcare OEMs. Long-term viability centers on vendors with vertical control over ASIC design and secure-element integration capabilities. Monitor ANSSI-led national cybersecurity certification scheme announcements as inflection indicators for French market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Notified-body approval unlocks high-stakes banking and government procurement channels previously inaccessible. |
| Secure-Element Integration Partnership | Common Criteria EAL-certified bundling opens multi-year civil ID contracts with Thales SA and IDEMIA France SAS incumbent positions. |
| Flexible Polymer Substrate Scale-Up | IDEX Biometrics-style wearable form factor expertise addresses underpenetrated pharmaceutical and precision engineering access control demand. |
| German Automotive OEM Direct Supply Agreement | Stuttgart and Munich vehicle access system integration creates sustained module demand with longer contract tenors than consumer electronics. |
| REACH and RoHS Compliance Automation | Halogen-free substrate transition defends market access against ECHA enforcement actions targeting non-compliant imports. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with biometric algorithm engineers, sensor module procurement managers at German automotive OEMs, EU AI Act conformity assessment officers, and secure-element integration specialists combined with secondary validation from ECHA regulatory filings, EU AI Act implementation guidance, SEC semiconductor disclosures, and customs import data for fingerprint sensor modules. Triangulation between vendor shipment reports and end-user deployment tracking ensures consistency across volume estimates.
Historical trendline analysis of capacitive and ultrasonic sensor adoption patterns across European banking, automotive, and government verticals established baseline growth trajectories. Segmentation modeling spans technology architecture, system integration depth, end-user certification requirements, and application power budgets. CAGRs derive from regression analysis of foundry capacity expansion, regulatory milestone timing, and procurement cycle compression. Industry-specific forecast inputs include EU AI Act implementation velocity and Common Criteria EAL certification queue lengths.
Revisions become necessary when semiconductor wafer pricing volatility exceeds modeled bands, when national cybersecurity certification schemes fragment ahead of harmonized EU standards, or when ultrasonic module power consumption breakthroughs alter wearable form factor feasibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Global Blind Spot Monitor Market