
 Global Color Detection Sensors Market | 2026-2036
Global Color Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Color Detection Sensors Market Analysis
Packaging quality assurance is restructuring demand patterns across the color detection sensors landscape. Keyence Corporation leverages optical triangulation expertise to dominate high-speed line inspection. SICK AG anchors its position through deep integration with German automotive OEM conveyor systems. ams-OSRAM AG specializes in miniaturized RGB modules for consumer electronics assembly.
Color detection sensors are photoelectric devices that measure spectral reflectance across defined wavelength bands, typically operating at sampling rates exceeding 10 kHz for real-time process control. These instruments serve industrial automation by converting surface color into digital signals for sorting, matching, or rejection decisions. RGB sensors occupy the volume tier due to cost efficiency in basic discrimination tasks, while multispectral variants capture expanding margin pools in pharmaceutical and food safety applications where wavelength granularity determines compliance outcomes. CCD-based architectures retain relevance in imaging-intensive quality control despite CMOS displacement in adjacent sensor categories.
FDA traceability mandates for medical device manufacturing tighten calibration documentation requirements across US-installed bases. EMA and EU MDR frameworks in Europe impose similar audit trails on packaging lines serving pharmaceutical clients. IEC colorimetry standards govern cross-border equipment certification, creating compliance complexity for vendors serving multiple jurisdictions. Stakeholders must monitor evolving spectral accuracy benchmarks as end-users shift from pass-fail detection toward quantitative colorimetric data integration with MES and ERP platforms.
Market Dynamics
Automotive paint verification protocols are compressing sensor refresh cycles below 5 milliseconds, forcing suppliers to recalibrate wavelength discrimination algorithms for real-time defect rejection on moving assembly lines.
Growth Catalysts
- EU MDR packaging mandates:Pharmaceutical serialization requirements in Europe demand spectral verification of label color consistency across batch runs, pulling multispectral sensors into secondary packaging lines previously served by monochrome vision systems.
- Japan METI smart factory subsidies:Precision manufacturing clusters in Aichi and Kanagawa prefectures deploy RGB modules for cosmetic defect sorting in electronics assembly, accelerating replacement of manual inspection stations.
- Food-grade polymer sorting:Near-infrared capable sensors separate post-consumer plastics by resin type and color simultaneously, opening material recovery facilities to premium sensor tiers previously reserved for virgin material producers.
Market Restraints
- Indium phosphide wafer supply:Shortwave infrared detector substrates concentrate among three Japanese and German substrate vendors, exposing sensor manufacturers to 18-month qualification timelines for alternative sourcing.
- IEC 61466-1 certification friction:Cross-border colorimetry standard harmonization lags between European Notified Bodies and US NIST-traceable labs, delaying product launches by 8-14 months for dual-market vendors.
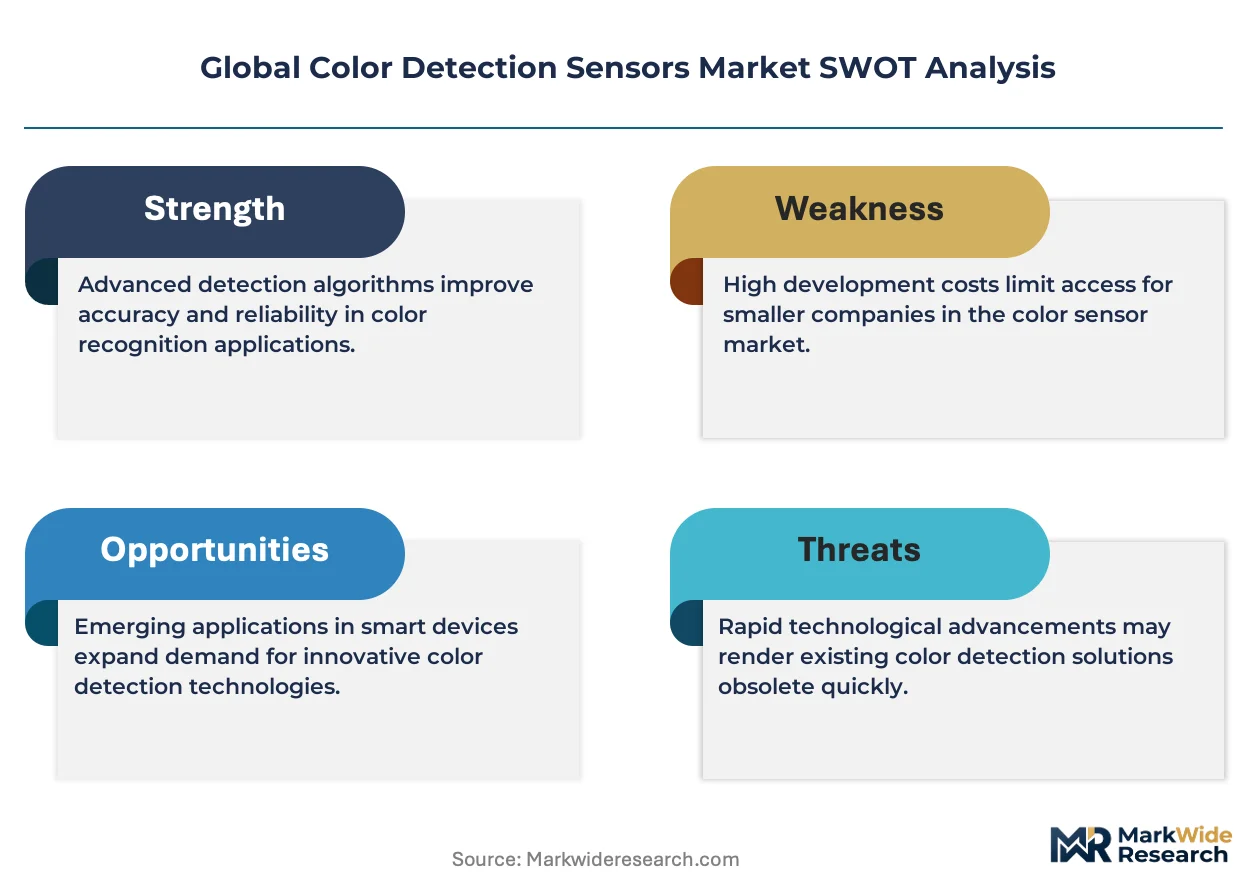
- Hyperspectral camera substitution:Falling price curves for push-broom imaging systems threaten discrete point sensors in pharmaceutical tablet coating inspection where spatial mapping adds marginal value.
Strategic Opportunities
- Brazilian meatpacking automation:ANVISA traceability rules for export-certified beef create first-mover openings for fat-to-lean ratio sensors that integrate color with spectral fat detection in slaughterhouse grading tunnels.
- India PLI scheme leverage:Smartphone assembly incentives under the Production Linked Incentive program attract module suppliers to Gujarat and Tamil Nadu clusters, compressing logistics costs for display panel color calibration tools.
- Hyperspectral-RGB fusion:Hybrid architectures that embed coarse spectral sampling within standard RGB footprints enable tier-two automotive suppliers to access pharmaceutical-grade color discrimination without full multispectral hardware cost.
Industry Challenges
- Optical calibration technician scarcity:Factory-floor personnel capable of maintaining NIST-traceable white point references across temperature drift conditions command 40% wage premiums in Stuttgart and Nagoya manufacturing corridors.
- MES integration complexity:Legacy SCADA architectures in German automotive paint shops require custom OPC-UA middleware development to ingest quantitative L*a*b* data streams from modern sensors, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Color Detection Sensors Market |
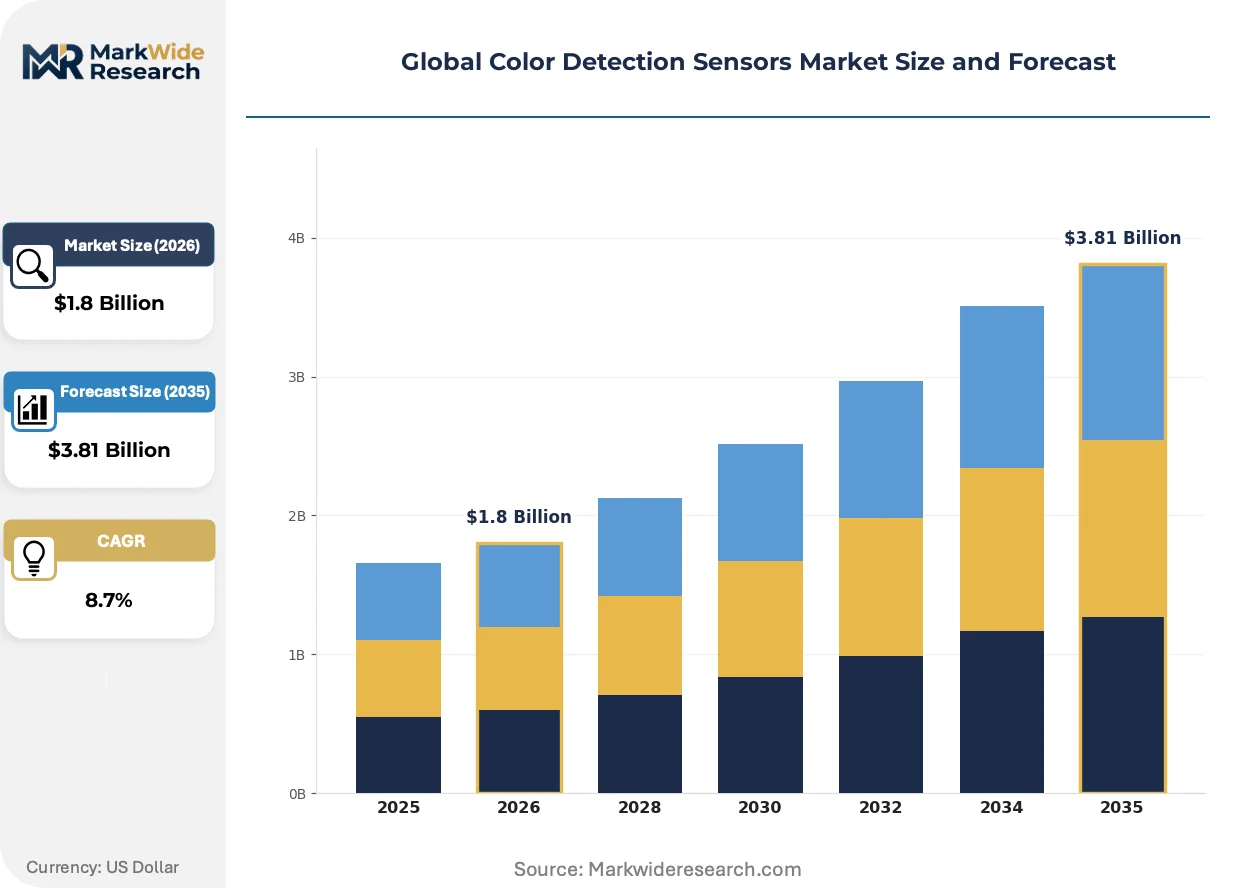
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RGB Sensors, Multispectral Sensors, Laser Color Sensors, CCD Sensors Technology: Optical, Electromagnetic, Digital, Analog End User: Manufacturing, Automotive, Packaging, Consumer Electronics Application: Color Matching, Quality Control, Environmental Monitoring, Image Processing |
| Companies Covered | ams-OSRAM AG, Datalogic, SICK AG, Banner Engineering, Vishay Intertechnology, Keyence Corporation, Hamamatsu Photonics, Pepperl+Fuchs, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Color Detection Sensors Market Emerging Trajectories
Sensor architectures are bifurcating between cost-optimized RGB triads for high-volume sorting and precision multispectral arrays for regulated industries, with software-defined spectral bands bridging the gap.
CMOS-based color sensors with on-chip spectral filtering is overtaking discrete filter wheel assemblies in pharmaceutical tablet inspection. Contract manufacturers in Ireland and Singapore adopt these solid-state alternatives to eliminate moving parts in 24/7 packaging operations. The shift is overtaking incumbent CCD suppliers in mid-range quality control applications where vibration tolerance outweighs absolute quantum efficiency.
REACH restrictions on cadmium-based quantum dot phosphors force sensor manufacturers to reformulate reference light sources for color calibration stations. Industrial lighting vendors in the EU accelerate adoption of perovskite and indium phosphide alternatives, compressing available supply for sensor emitters. German automotive OEMs now require RoHS-III compliance documentation across entire conveyor subsystems, not merely end-point instruments.
Subscription-based sensor health monitoring displaces transactional hardware sales in North American food processing. Plant operators in Wisconsin and California dairy corridors pay per-inspection-cycle fees that bundle hardware, cloud-based drift detection, and automatic recalibration dispatch. The model concentrates vendor cash flow predictability while transferring obsolescence risk from capital-constrained processors to sensor suppliers.
Global Color Detection Sensors Market Segmentation
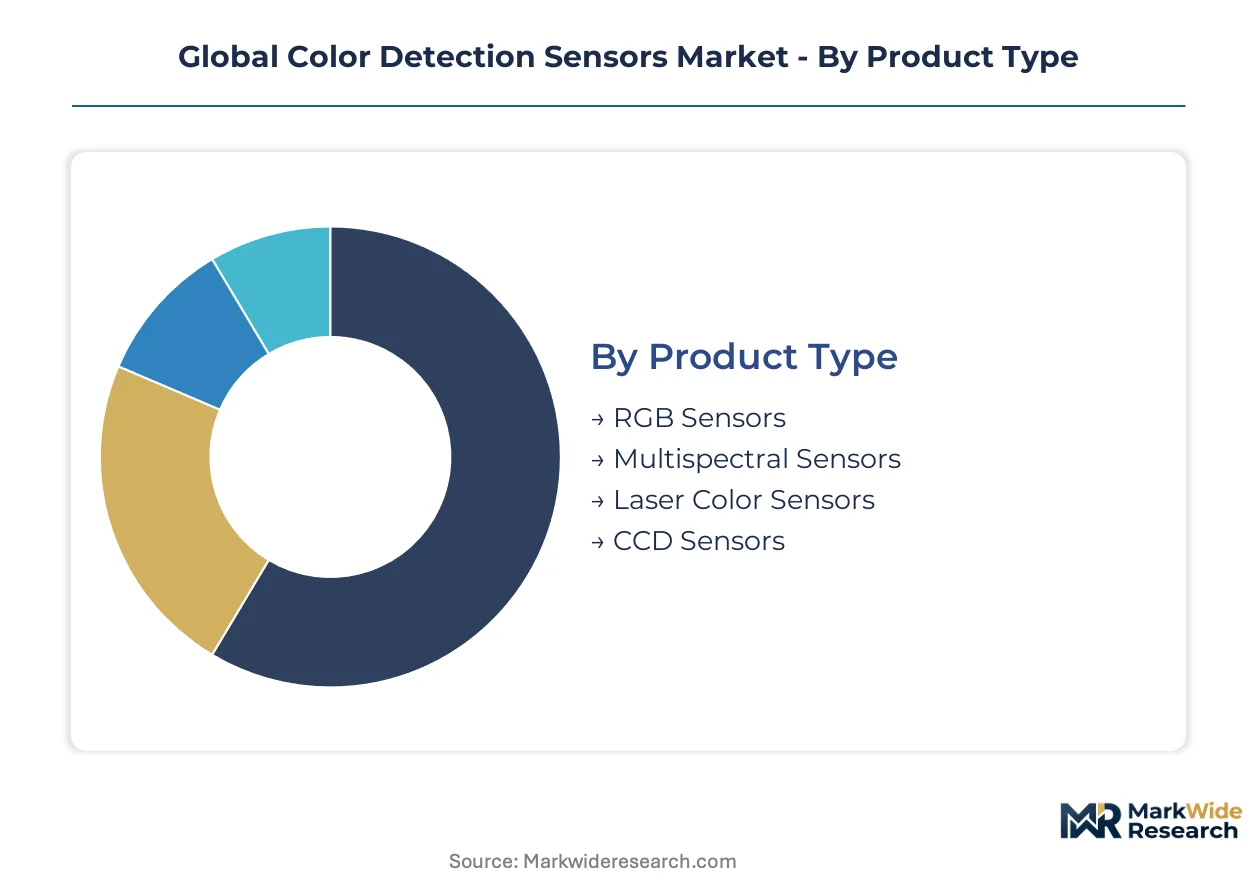
Color detection sensors fragment across four dimensions that dictate procurement priorities and vendor specialization. Product type determines spectral capability and price positioning. End user concentration in German automotive and Japanese electronics clusters shapes regional demand intensity.
Product Type:
Supply of advanced spectral components concentrates among Japanese substrate vendors and German optical foundries, creating tiered availability that segments the hardware landscape.
- RGB Sensors:Tri-channel photodiode arrays with integrated color filters discriminate red, green, and blue reflectance bands at sampling rates exceeding 10 kHz. Demand concentrates in Aichi and Kanagawa prefectures where METI smart factory subsidies accelerate replacement of manual cosmetic inspection in electronics assembly.
- Multispectral Sensors:Discrete filter arrays or tunable Fabry-Perot interferometers capture 8-16 spectral bands beyond visible range, enabling pharmaceutical label verification under EU MDR serialization mandates. These units command premium positioning in secondary packaging lines previously served by monochrome vision systems.
- Laser Color Sensors:Confocal chromatic aberration measurement for non-contact surface profiling in automotive paint shops.
- CCD Sensors:Charge-coupled device architectures retain relevance in imaging-intensive quality control despite CMOS displacement in adjacent categories.
Today's leader: RGB Sensors. Tomorrow's challenger: Multispectral Sensors.
Technology:
Cost tier separation between solid-state digital architectures and legacy analog signal chains determines retrofit versus greenfield deployment patterns.
- Optical:Triangulation and reflectance-based systems leveraging Keyence Corporation's patent portfolio for high-speed line inspection dominate volume tiers.
- Electromagnetic:Inductive and capacitive proximity methods for metallic substrate color detection in coil coating operations.
- Digital:On-chip spectral filtering in CMOS arrays eliminates moving parts in 24/7 pharmaceutical packaging operations across Ireland and Singapore.
- Analog:Voltage-output photodiode circuits persist in legacy SCADA environments requiring minimal middleware conversion.
Digital architectures are expanding most quickly. Analog maintains entrenched positions in brownfield automotive paint facilities.
End User:
Application maturity varies sharply across customer types, with regulated industries demanding quantitative colorimetric data integration with MES platforms.
- Manufacturing:Discrete assembly lines in Stuttgart and Nagoya manufacturing corridors deploy sensors for component sorting and surface defect rejection.
- Automotive:German OEM conveyor systems integrate sensors for real-time paint verification with refresh cycles compressed below 5 milliseconds.
- Packaging:Serialization requirements from FDA and EMA frameworks pull multispectral units into pharmaceutical secondary packaging.
- Consumer Electronics:Display panel color calibration tools concentrate in Gujarat and Tamil Nadu clusters under India's PLI scheme incentives.
Automotive commands current revenue concentration. Consumer electronics offers steepest expansion trajectory as smartphone assembly automation accelerates.
Application:
Margin pools concentrate where wavelength granularity determines compliance outcomes rather than simple pass-fail discrimination.
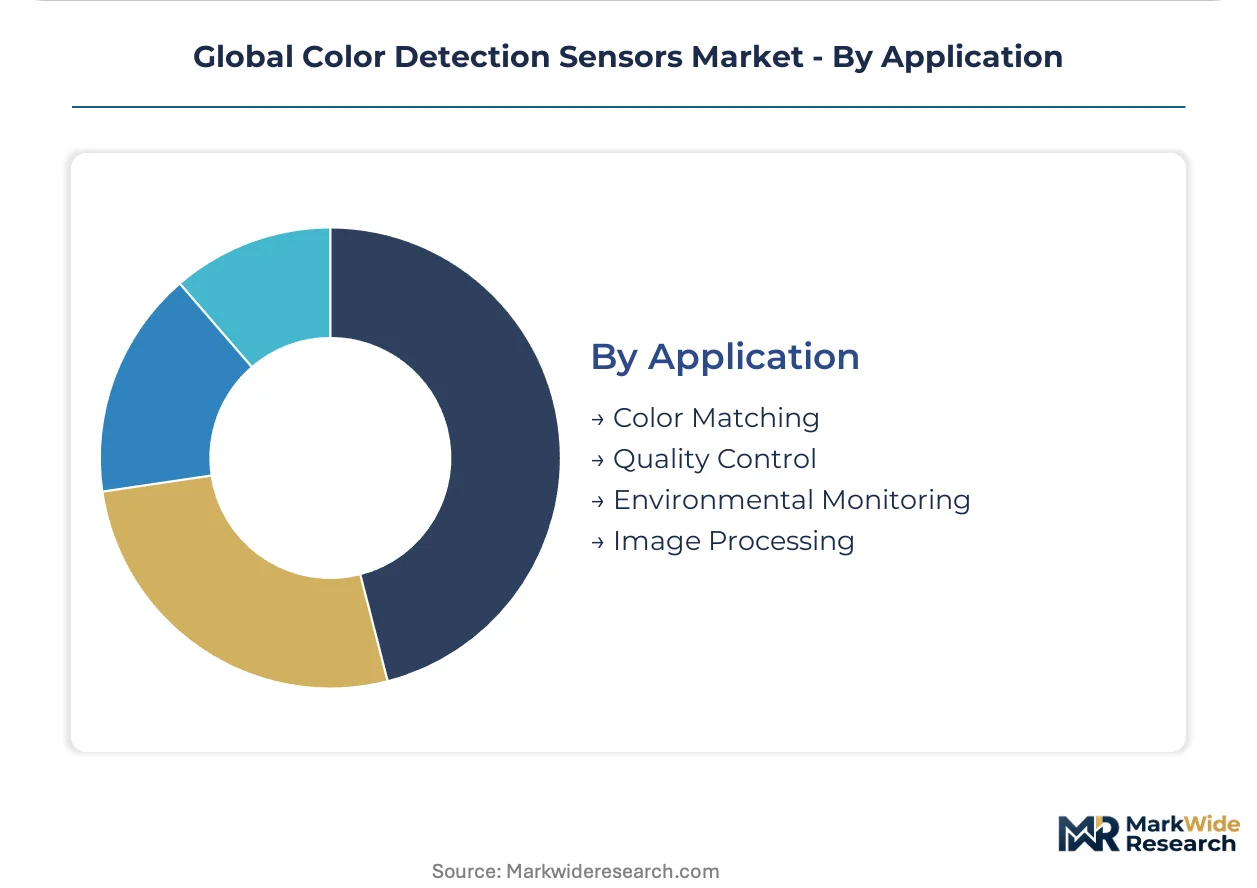
- Color Matching:L*a*b* coordinate measurement for textile and coating formulation in batch production environments.
- Quality Control:Real-time defect rejection on moving assembly lines with NIST-traceable calibration documentation.
- Environmental Monitoring:Water quality and atmospheric particulate analysis using spectral absorption signatures.
- Image Processing:Spatial color mapping for pharmaceutical tablet coating inspection where hyperspectral camera substitution threatens discrete point sensors.
Quality control anchors current installed base. Image processing faces technology substitution pressure from push-broom imaging systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting sensor procurement toward jurisdictions where calibration documentation costs diverge sharply from end-market value. Manufacturers in lower-compliance-cost environments now supply precision instruments to regulated markets through distributor channels.
Germany
Automotive paint verification protocols at BMW and Mercedes-Benz plants in Stuttgart and Munich compress sensor refresh cycles below 5 milliseconds. KBA vehicle certification rules mandate NIST-traceable calibration chains for all inline quality systems. Bavarian and Baden-Württemberg manufacturing corridors concentrate demand for multispectral units in secondary packaging lines.
Japan
METI smart factory subsidies accelerate RGB module deployment for cosmetic defect sorting in Aichi and Kanagawa electronics clusters. PMDA pharmaceutical serialization requirements pull spectral verification into label printing operations. Hamamatsu Photonics anchors substrate supply for shortwave infrared detector components used across automotive and medical applications.
United States
FDA traceability mandates for medical device manufacturing tighten calibration documentation requirements across installed bases in Massachusetts and Minnesota medical technology hubs. Wisconsin and California dairy processors adopt subscription-based sensor health monitoring for fat-to-lean ratio detection. EPA water quality monitoring programs expand environmental sensing procurement.
South Korea
MFDS pharmaceutical packaging regulations drive multispectral sensor adoption in Incheon and Songdo biotech clusters. Samsung and LG Display operations in Gyeonggi-do deploy color calibration tools for OLED panel production under national dual carbon goals. Daegu-Gyeongbuk machinery builders integrate sensors for automotive component sorting.
India
PLI scheme incentives for smartphone assembly attract module suppliers to Gujarat and Tamil Nadu display panel operations. CDSCO pharmaceutical serialization rules create demand for label verification in Hyderabad and Mumbai formulation facilities. BIS certification requirements for imported industrial equipment slow entry but reward local calibration service partnerships.
Global Color Detection Sensors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with volume-tier RGB modules consolidating around optical component integrators while multispectral arrays fragment among niche spectral engineering houses. Three archetypes dominate: Japanese-German substrate vendors controlling shortwave infrared detector supply, Swiss-Austrian precision optics specialists serving pharmaceutical compliance markets, and Korean-Taiwanese CMOS foundries pushing cost curves downward. Competitive moves center on backward integration into indium phosphide wafer sourcing and cloud-based calibration subscription models that transfer obsolescence risk from processors to vendors.
Among German automation specialists, SICK AG exemplifies the conveyor-system integration archetype through deep relationships with automotive OEMs. Japanese precision component houses anchor the substrate tier, with Hamamatsu Photonics representing concentrated capability in photodetector manufacturing. Keyence Corporation occupies a position exemplifying the high-speed optical triangulation specialist model that dominates volume inspection applications. These three entities collectively illustrate how geographic clustering around precision manufacturing corridors shapes competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| Datalogic |
| SICK AG |
| Banner Engineering |
| Vishay Intertechnology |
| Keyence Corporation |
| Hamamatsu Photonics |
| Pepperl+Fuchs |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Indium phosphide wafer spot indices cascade through three pricing tiers for color detection sensors, compressing margins on shortwave infrared variants while amplifying premium capture for vendors with captive substrate supply. Automotive OEMs in Stuttgart and Nagoya absorb cost pass-throughs for sub-5-millisecond refresh units, whereas food processors in Wisconsin resist subscription-fee escalations for RGB modules.
Pricing Analysis
Distributor margins of 18-22% separate factory pricing from end-user landed costs, with direct-to-OEM contracts commanding 12-15% discounts for multispectral arrays. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and economy-RGB levels tracks certification complexity rather than component cost alone. Price differentiation hinges on IEC 61466-1 traceability documentation and NIST-calibrated white point references. Cost compression in economy RGB tiers is intensifying because Korean-Taiwanese CMOS foundries push wafer cost curves downward. Automotive paint shops show least price sensitivity due to downtime cost exposure, while Indian smartphone assemblers under PLI schemes negotiate hardest on module pricing.
Supply Chain Analysis
Single-source vulnerability sits with Japanese substrate vendors Hamamatsu and Sumitomo for indium phosphide wafers, exposing sensor manufacturers to 18-month qualification timelines for alternative sourcing. Geographic supply concentration centers on Japan for photodetector substrates, Germany for precision optical foundries, and South Korea for CMOS foundry capacity. Raw material dependencies encompass indium phosphide wafers, perovskite phosphors substituting cadmium quantum dots, and rare-earth doped glass for filter arrays. Tariff exposure looms for EU-sourced calibration equipment entering US medical device facilities under evolving trade frameworks. Distribution runs through German automation distributors for European automotive OEMs, Japanese trading houses for Aichi electronics clusters, and direct field service teams for North American food processing subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global color detection sensors constitute a late-cycle quality story as end-users shift from pass-fail detection toward quantitative L*a*b* data integration with MES platforms, elevating premium specifications over volume throughput. Pharmaceutical serialization mandates in Europe and traceability rules in Brazil reward vendors with calibration documentation depth.
For Market Incumbents: Hedge hyperspectral camera substitution threat in pharmaceutical tablet inspection by embedding coarse spectral sampling within standard RGB footprints, preserving margin pools without full multispectral hardware cost. Deepen backward integration into indium phosphide wafer sourcing to neutralize Japanese substrate vendor concentration risk. Defend installed base in Stuttgart automotive paint shops through OPC-UA middleware development for legacy SCADA integration, extending switching costs.
For New Entrants and Emerging Players: CMOS-based on-chip spectral filtering offers a technology-first wedge into pharmaceutical packaging operations across Ireland and Singapore, displacing filter wheel assemblies with solid-state alternatives. Target Brazilian meatpacking automation where ANVISA traceability rules for export-certified beef create first-mover openings for fat-to-lean ratio sensors. Pursue Gujarat and Tamil Nadu smartphone assembly clusters under India's PLI scheme, compressing logistics costs for display panel color calibration tools through local module partnerships.
For Investors and Strategic Acquirers: Consolidation pressure builds where optical calibration technician scarcity in Stuttgart and Nagoya manufacturing corridors commands 40% wage premiums, favoring vendors with automated recalibration capabilities and cloud-based drift detection. Long-term viability favors subscription-model sensor health monitoring platforms that transfer obsolescence risk from capital-constrained processors to vendors, generating predictable cash flow. Target acquisition archetype: Swiss-Austrian precision optics specialists with pharmaceutical compliance market access and spectral engineering depth. Signal to watch: IEC-NIST harmonization progress on cross-border colorimetry certification, which would unlock dual-market product launches for compliant vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Phosphide Sourcing | Captive wafer supply neutralizes 18-month qualification risk from Japanese substrate concentration. |
| Hyperspectral-RGB Fusion Architecture Development | Hybrid spectral sampling bridges pharmaceutical-grade discrimination with automotive cost constraints. |
| Cloud-Based Calibration Subscription Launch | Per-inspection-cycle pricing transfers obsolescence risk to vendors in North American food processing. |
| OPC-UA Middleware for Legacy SCADA Integration | Custom protocol development locks in German automotive paint shop installed bases. |
| Perovskite Phosphor Reference Source Reformulation | REACH-compliant alternatives to cadmium quantum dots satisfy RoHS-III conveyor subsystem mandates. |
Methodological Framework
Direct dialogue with optical systems engineers, pharmaceutical packaging line managers, automotive paint shop quality directors, and industrial automation procurement leads grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings for medical device manufacturing equipment, EMA regulatory guidance on pharmaceutical serialization, IEC colorimetry standard documentation, and SEC 10-K disclosures from listed sensor manufacturers. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Bottom-up modeling built from individual sensor unit pricing, regional installation density, and replacement cycle assumptions, cross-checked against top-down industry spend estimates from automation capital expenditure surveys. Segmentation dimensions encompassed product type (RGB through hyperspectral), technology architecture (optical, electromagnetic, digital, analog), end user concentration (automotive, packaging, electronics, food), and application maturity (quality control versus environmental monitoring). CAGRs derived from regression analysis of historical shipment data against regulatory mandate timelines and subsidy program schedules. Industry-specific forecast inputs included METI smart factory subsidy disbursement rates and EU MDR serialization phase-in compliance curves.
The model holds under stable indium phosphide wafer supply and continued regulatory divergence between IEC and NIST colorimetry frameworks; deviation in substrate vendor consolidation or harmonization acceleration would shift premium-mass market bifurcation timing. Forecasts reflect assumptions about OEM capital expenditure cycles, pharmaceutical serialization compliance deadlines, and CMOS cost curve trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market