
 Global Pyrometer Market | 2026-2036
Global Pyrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pyrometer Market Outlook
Buyer concentration among steel and aluminum producers is recalibrating procurement patterns across the pyrometer supply chain. AMETEK Land dominates furnace monitoring installations through its specialized infrared product lines. Fluke Corporation competes in portable diagnostics for maintenance crews across power generation facilities. Advanced Energy Industries anchors semiconductor thermal process control with solid-state sensing architectures.
A pyrometer measures surface temperature through thermal radiation detection without physical contact, typically operating across spectral bands from 0.5 to 14 micrometers depending on target emissivity and ambient conditions. Stationary installations command the largest revenue share due to permanent integration into glass, cement, and metal production lines. Portable units represent the fastest-expanding category as maintenance departments prioritize flexible spot-checking over fixed instrumentation. Non-contact technology leads adoption in hazardous environments where thermocouple immersion risks contamination or mechanical failure.
EPA emissions tracking in US steelmaking and MEE air quality enforcement in China both mandate precise combustion temperature logging that pyrometers provide. CE marking under EU machinery directives shapes product design for European furnace builders and system integrators. Stakeholders must monitor evolving IEC standards for radiation thermometry and assess whether dual-spectral or ratio pyrometry better serves emerging hydrogen-fired furnace applications.
Market Dynamics
Steel decarbonization mandates are forcing furnace operators to replace thermocouple arrays with optical pyrometers capable of measuring hydrogen combustion flames where traditional sensors fail. This technology substitution wave is redrawing equipment specifications across primary metals processing.
Growth Catalysts
- MEE air quality enforcement:Chinese steel mills must log combustion temperatures with certified non-contact instruments to demonstrate emission compliance. Pyrometer installations satisfy this mandate while eliminating thermocouple contamination risks in molten metal environments.
- Semiconductor node shrinkage:Advanced logic foundries in Taiwan and South Korea require sub-degree thermal precision during epitaxial growth. Ratio pyrometry with silicon carbide sensing elements meets these tolerances where single-wavelength devices falter.
- India's PLI scheme for specialty steel:Domestic producers expanding electric arc furnace capacity under government incentive programs are specifying integrated temperature monitoring systems as standard equipment packages.
Market Restraints
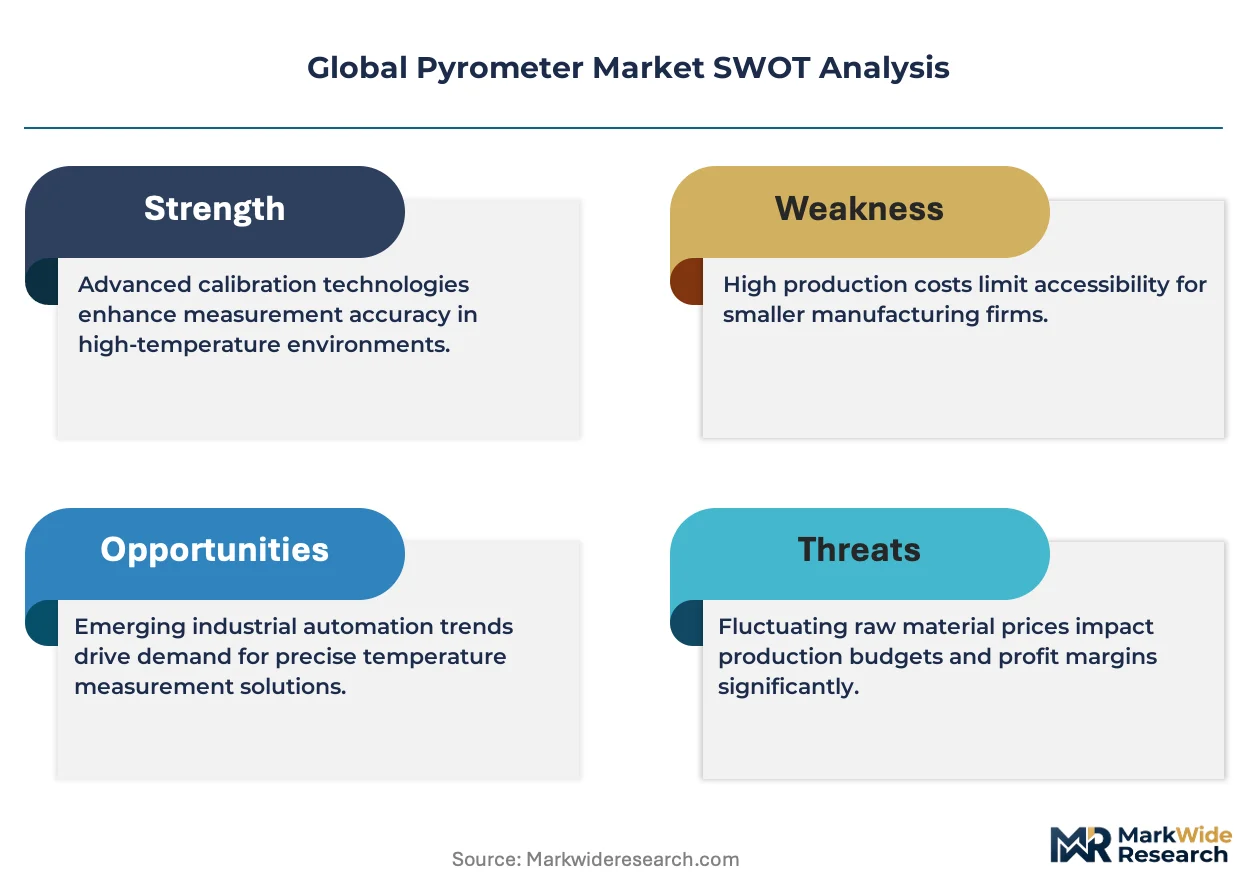
- Indium gallium arsenide detector costs:Short-wavelength pyrometers depend on III-V semiconductor materials concentrated among limited compound foundries. Input price volatility constrains margin flexibility for mid-tier instrument manufacturers.
- Calibration infrastructure scarcity:National metrology institutes in emerging manufacturing economies lack blackbody furnace traceability chains. Users face extended downtime sending sensors to Germany or the United States for recertification.
- Dual-spectral complexity premium:Ratio pyrometry requires sophisticated signal processing algorithms that inflate unit costs versus single-color alternatives. Cost-sensitive cement and glass sectors defer upgrades despite accuracy advantages.
Strategic Opportunities
- Saudi Arabia giga-project construction:NEOM and Red Sea tourism developments specify smart building materials requiring continuous kiln monitoring. Greenfield ceramic and glass facilities present unserved demand for integrated pyrometer networks.
- Hydrogen-fired furnace retrofit wave:European steel consortiums piloting hydrogen injection need flame-transparent measurement solutions. Two-color pyrometry with specialized spectral filtering captures temperature data through hydrogen combustion spectra.
- Direct-to-plant digital distribution:Industrial sensor marketplaces connecting OEMs with maintenance departments are compressing traditional distributor markups. Platform procurement channels enable price transparency for replacement sensor heads.
Industry Challenges
- IEC 62485 radiation thermometry certification timelines:Revised international standards for non-contact temperature measurement require extensive interlaboratory testing. Manufacturers face eighteen-month validation cycles before commercial release.
- Emissivity compensation algorithm integration:Legacy distributed control systems in North American aluminum smelters lack processing bandwidth for real-time emissivity correction. Retrofit projects demand parallel computing hardware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pyrometer Market |
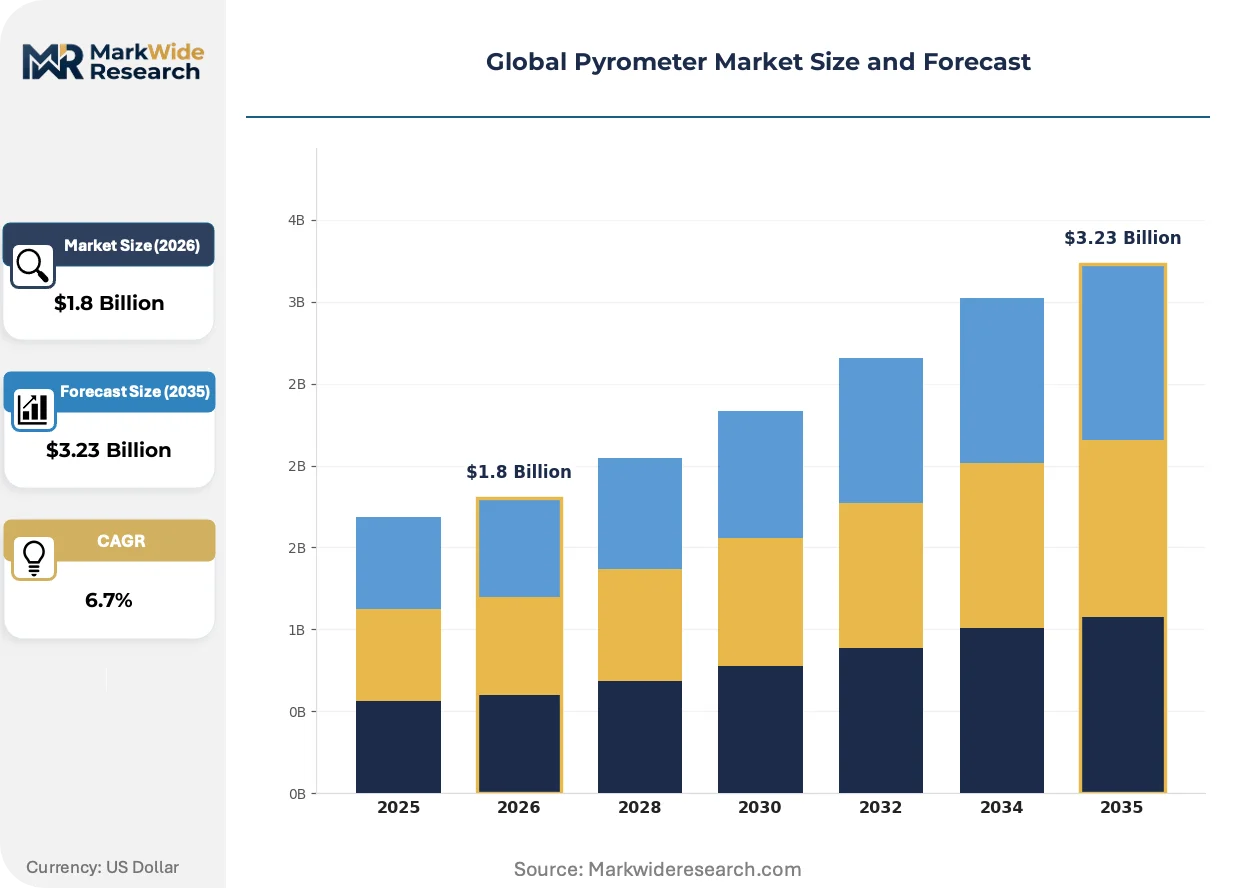
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Infrared, Optical Temperature Range: High-Temperature, Medium-Temperature, Low-Temperature, Ultra-High-Temperature End User: Manufacturing, Aerospace, Automotive, Energy Technology: Rayleigh Scattering, Thermocouple, Solid-State, Non-Contact |
| Companies Covered | AMETEK Land, Fluke Corporation, Advanced Energy Industries, Inc., CHINO Corporation, DIAS Infrared GmbH, OMEGA Engineering Inc., Optris GmbH, Calex Electronics Limited, PCE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pyrometer Market Strategic Shifts
Pyrometer architecture is converging around solid-state sensing and embedded intelligence, compressing the traditional separation between measurement hardware and process control software. Vendors are repositioning around data service revenue rather than unit sales.
Silicon photodiode arrays with integrated micro-optics are unifying multi-point temperature mapping into single sensor packages. Glass tempering lines in Italy and Turkey are adopting these distributed architectures to eliminate scanning mirror maintenance. The technology is unifying furnace zone control with quality documentation, collapsing separate instrumentation and data logging capital budgets into unified procurement decisions.
EPA Greenhouse Gas Reporting Program amendments now mandate continuous temperature monitoring for large combustion sources above defined heat input thresholds. Steel mini-mills across Ohio and Indiana are deploying fiber-optic pyrometers to satisfy hourly averaging requirements without probe degradation. The regulatory pressure is accelerating replacement cycles for thermocouple-based systems that cannot sustain measurement continuity.
Maintenance departments at German automotive foundries are unbundling sensor calibration from original equipment service contracts. Third-party metrology providers with portable blackbody sources are capturing recurring revenue through on-site certification visits. This service fragmentation is most visible in Bavaria's supplier park clusters, where just-in-time production tolerances demand minimal instrument downtime.
Global Pyrometer Market Segmentation
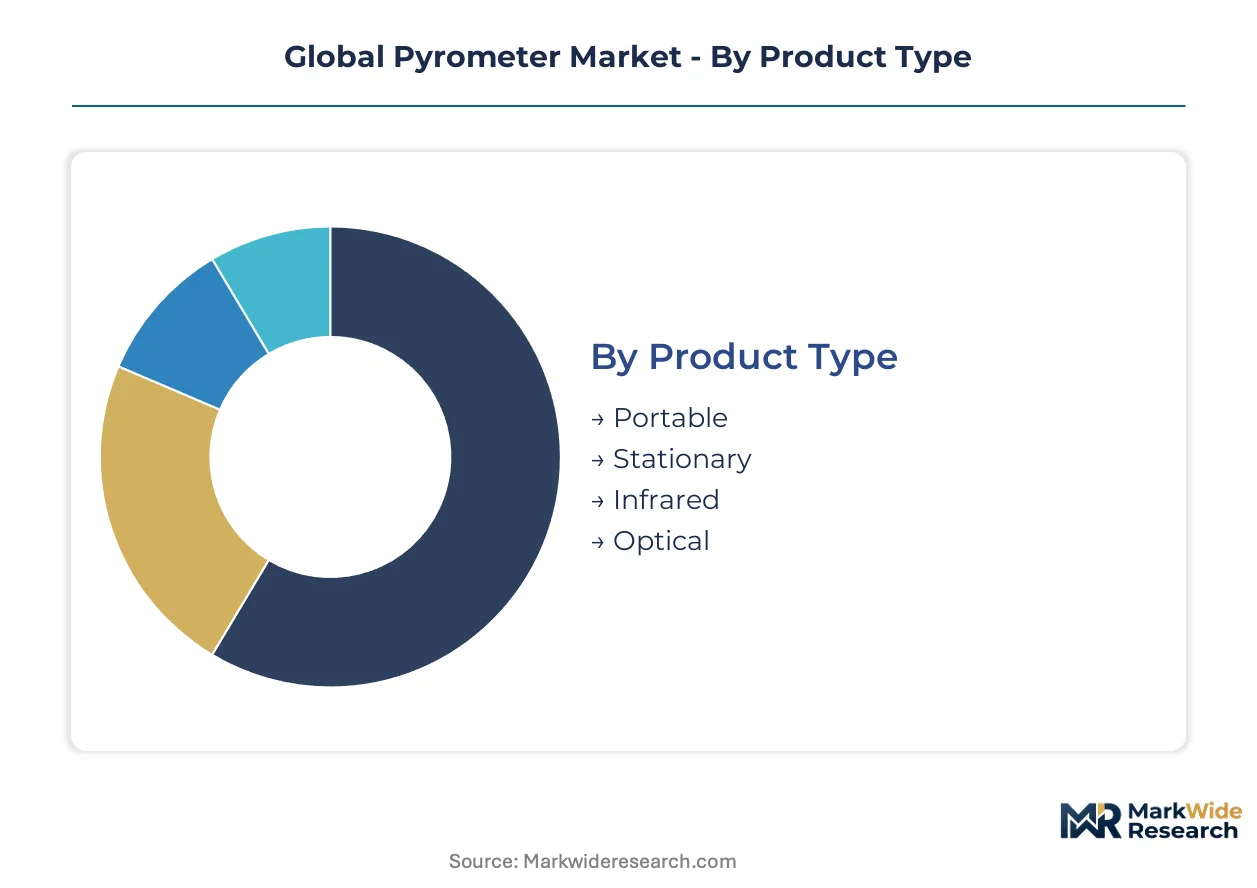
Pyrometer procurement decisions diverge sharply across operating environments. Certification requirements for steel mill installations differ fundamentally from semiconductor cleanroom specifications. Understanding these segment boundaries clarifies where technical standards create pricing power versus commodity pressure.
Product Type:
CE marking under EU machinery directives governs stationary furnace installations. Portable units for field diagnostics face lighter conformity assessment but demand IEC 62485 radiation thermometry traceability.
- Stationary:Fixed-mount sensors integrate permanently into glass, cement, and primary metals production lines. Chinese steel producers under MEE air quality mandates specify these for continuous combustion temperature logging. CE marking and IEC certification inflate upfront costs but eliminate thermocouple replacement cycles.
- Portable:Handheld units serve maintenance crews across power generation and automotive foundries. German automotive supplier parks in Bavaria drive demand for flexible spot-checking with minimal instrument downtime. Third-party metrology providers now capture recurring calibration revenue through on-site certification visits.
- Infrared:Non-contact thermal radiation detection spans 0.5 to 14 micrometers depending on target emissivity. EPA Greenhouse Gas Reporting Program amendments mandate this architecture for large combustion sources above defined heat input thresholds.
- Optical:High-precision instruments concentrate in semiconductor fabrication and advanced ceramics processing. Ratio pyrometry with silicon carbide sensing elements serves Taiwan and South Korea logic foundries requiring sub-degree thermal precision.
Leading the category by volume: Stationary. Growing fastest: Portable.
Temperature Range:
Cost tiers stratify sharply by detector material requirements. Short-wavelength instruments depend on indium gallium arsenide concentrated among limited compound foundries.
- High-Temperature:Instruments measure above 1000°C in steel electric arc furnaces and cement kilns. India's PLI scheme for specialty steel drives integrated temperature monitoring system procurement as standard equipment packages. Hydrogen-fired furnace retrofits in Europe demand flame-transparent measurement solutions.
- Ultra-High-Temperature:Specialized optics survive above 2000°C in aerospace material testing and advanced ceramics sintering. Saudi Arabia's NEOM giga-project construction specifies smart building materials requiring continuous kiln monitoring.
- Medium-Temperature:Aluminum smelters and glass tempering lines deploy these for zone control applications. Silicon photodiode arrays with integrated micro-optics now unify multi-point temperature mapping into single sensor packages.
- Low-Temperature:Semiconductor epitaxial growth and pharmaceutical lyophilization require precise sub-500°C measurement. Solid-state sensing architectures with embedded intelligence compress hardware-software separation.
Dominant by installed base: High-Temperature. Steepest expansion trajectory: Ultra-High-Temperature.
End User:
Customer type determines service contract structure and calibration frequency. Steel producers unbundle sensor maintenance from original equipment agreements.
- Manufacturing:Glass, cement, and metal production lines anchor stationary pyrometer demand. Italian and Turkish glass tempering operations adopt distributed architectures to eliminate scanning mirror maintenance.
- Energy:Power generation facilities prioritize portable diagnostics for turbine and boiler maintenance. Fiber-optic pyrometers sustain measurement continuity without probe degradation in Ohio and Indiana steel mini-mills.
- Automotive:German foundries demand just-in-time production tolerances with minimal instrument downtime. Maintenance departments specify on-site certification to avoid extended blackbody furnace recertification queues.
- Aerospace:Material testing and jet engine component validation require ultra-high-temperature capability. Precision specifications align with advanced ceramics processing requirements.
Largest revenue concentration: Manufacturing. Gaining share fastest: Energy.
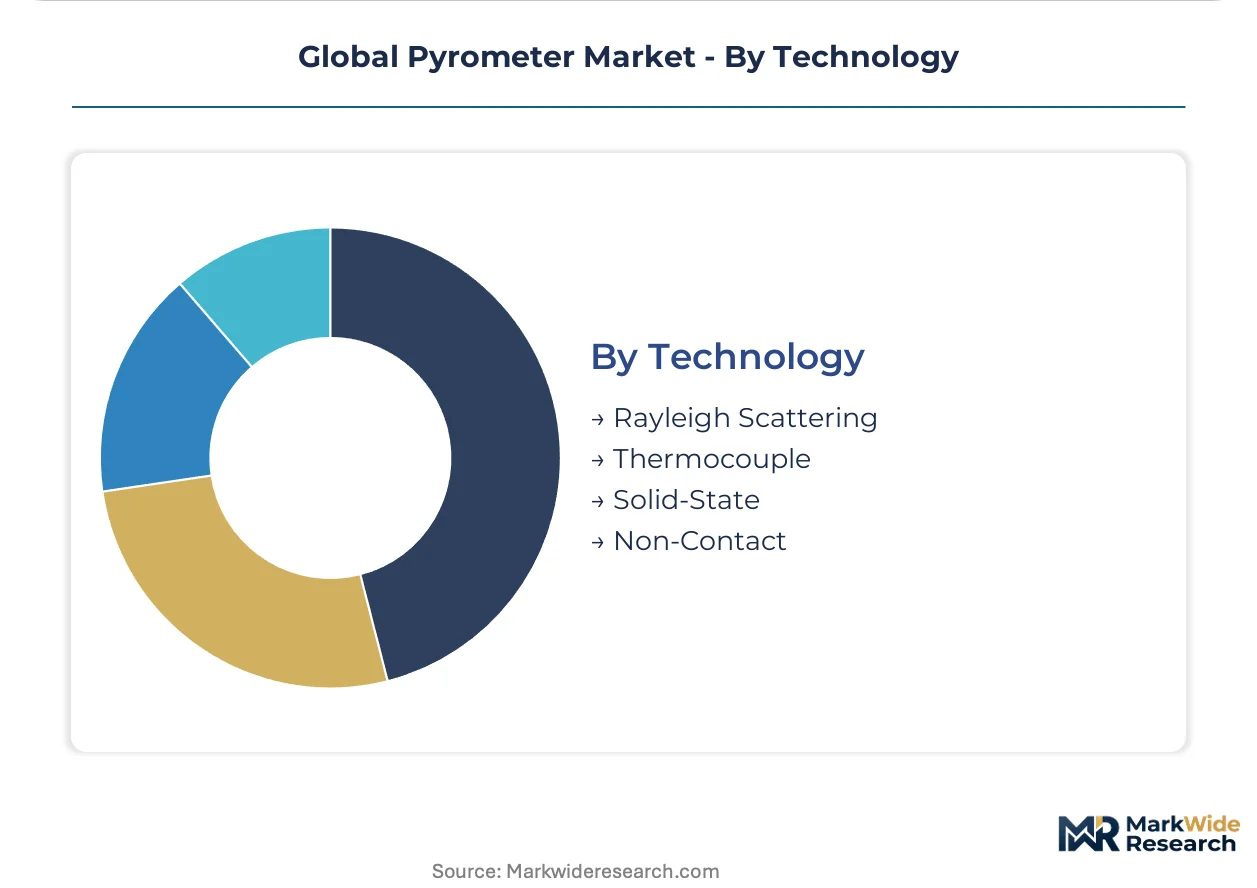
Technology:
Maturity curves separate legacy thermocouple replacement from solid-state adoption waves. Hydrogen combustion measurement is accelerating optical pyrometry substitution.
- Non-Contact:Thermal radiation detection eliminates physical contamination risks in molten metal environments. Chinese steel mills satisfy MEE emission compliance mandates while avoiding thermocouple mechanical failure.
- Solid-State:Silicon carbide sensing elements and embedded signal processing anchor semiconductor thermal process control. Advanced logic foundries in Taiwan and South Korea require ratio pyrometry tolerances where single-wavelength devices falter.
- Rayleigh Scattering:Specialized spectral filtering captures temperature data through hydrogen combustion spectra. European steel consortiums piloting hydrogen injection specify these flame-transparent solutions.
- Thermocouple:Legacy distributed control systems in North American aluminum smelters face retrofit demands for real-time emissivity correction bandwidth. Steel decarbonization mandates are forcing systematic replacement with optical alternatives.
Highest deployment volume: Non-Contact. Climbing the fastest: Solid-State.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rare earth processing dominance anchors pyrometer demand for high-temperature industrial monitoring across steel and semiconductor fabrication clusters.
China
Steel mills in Hebei and Jiangsu provinces deploy non-contact temperature logging to satisfy MEE air quality enforcement mandates. The Ministry of Ecology and Environment requires certified combustion temperature documentation for emission compliance. Baowu Steel's Shanghai operations exemplify large-scale pyrometer integration for continuous furnace monitoring.
Germany
Automotive foundries in Bavaria and North Rhine-Westphalia demand sub-degree thermal precision for just-in-time production tolerances. CE marking under EU machinery directives shapes furnace builder procurement specifications. Siemens Energy's turbine manufacturing in Berlin-Brandenburg drives portable diagnostic instrument demand for maintenance crews.
United States
Steel mini-mills across Ohio and Indiana install fiber-optic pyrometers to meet EPA Greenhouse Gas Reporting Program amendments. The Environmental Protection Agency mandates hourly temperature averaging for large combustion sources above defined heat input thresholds. Cleveland-Cliffs' integrated mills in the Midwest anchor stationary instrument deployments.
India
Electric arc furnace expansion under the PLI scheme for specialty steel drives integrated temperature monitoring system procurement. The Central Electricity Authority oversees power generation facility standards that prioritize portable diagnostics. Tata Steel's Kalinganagar complex in Odisha specifies pyrometer networks as standard equipment packages.
Japan
Logic foundries in Kyushu and the Tokyo metropolitan area require ratio pyrometry with silicon carbide sensing elements for epitaxial growth precision. METI industrial standards govern semiconductor thermal process control equipment. Tokyo Electron's fabrication supply chain in Hiroshima prefecture concentrates high-precision optical instrument demand.
Global Pyrometer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solid-state sensing architectures and embedded intelligence integration. The vendor base stratifies across three maturity levels: multinational instrumentation conglomerates with furnace integration expertise, mid-tier specialists in portable diagnostics, and component-level sensor fabricators. Two strategic archetypes dominate: full-system integrators bundling hardware with calibration services, and modular sensor suppliers targeting replacement part procurement. Competitive moves center on technology licensing for hydrogen-fired furnace applications and backward integration into detector material supply.
Among Germany-based infrared specialists, DIAS Infrared GmbH and Optris GmbH exemplify the precision-tier archetype with concentrated European industrial automation exposure. AMETEK Land anchors the full-system integration segment through its furnace monitoring positioning. These three entities represent distinct competitive vectors: component specialization, regional automation integration, and end-to-end thermal process control.
| Leading Market Players |
|---|
| AMETEK Land |
| Fluke Corporation |
| Advanced Energy Industries, Inc. |
| CHINO Corporation |
| DIAS Infrared GmbH |
| OMEGA Engineering Inc. |
| Optris GmbH |
| Calex Electronics Limited |
| PCE Instruments |
| Others |
Value Chain & Pricing Dynamics
Chinese steel mill procurement under MEE enforcement mandates anchors contract-based long-term offtake agreements, concentrating pricing power with certified system integrators who bundle stationary installations with calibration services. This buyer concentration compresses margin flexibility for mid-tier instrument manufacturers competing on per-unit transactional sales.
Pricing Analysis
High-volume stationary furnace installations trade margin for multi-year service contracts, while portable diagnostic units capture premium pricing through third-party metrology bundling. Price differentiation separates IEC 62485-certified instruments from uncertified alternatives, with CE marking under EU machinery directives adding compliance cost tiers. Pricing pressure stems from indium gallium arsenide detector cost volatility concentrated among limited compound foundries. Cement and glass sectors exhibit highest price sensitivity, deferring dual-spectral upgrades despite accuracy advantages; semiconductor foundries in Taiwan and South Korea show lowest sensitivity, prioritizing sub-degree precision over unit economics.
Supply Chain Analysis
Reverse-logistics flows for recalibration and sensor head replacement dominate aftermarket revenue, with German automotive foundries unbundling service contracts to capture on-site certification efficiency. Detector material supply concentrates in Japan, Germany, and the United States, with indium gallium arsenide and silicon carbide sensing elements drawing from specialized III-V semiconductor foundries. Single-source vulnerability pervades short-wavelength pyrometer architectures dependent on limited compound foundry capacity. Distribution runs through industrial sensor marketplaces compressing traditional distributor markups, with direct-to-plant digital channels gaining share for replacement procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium gallium arsenide foundry capacity constraints prop pricing premiums for short-wavelength instruments, creating durable margin pools for suppliers with captive detector supply or long-term material offtake agreements.
For Market Incumbents: Anticipate hydrogen-fired furnace retrofit waves across European steel consortiums by securing two-color pyrometry with specialized spectral filtering ahead of IEC 62485 revision cycles. Backward integration into silicon carbide sensing element production defends margin position against Advanced Energy Industries' solid-state architecture dominance in semiconductor thermal process control. Prioritize calibration infrastructure investments in India and Saudi Arabia to capture recurring service revenue from emerging manufacturing economies lacking national metrology institute traceability chains. For New Entrants and Emerging Players: Solid-state sensing with embedded intelligence offers technology-first wedge into portable diagnostics segments where maintenance departments prioritize flexible spot-checking over fixed instrumentation. Target Saudi Arabia giga-project construction and India's PLI scheme-driven electric arc furnace expansion as white-space geographies with unserved demand for integrated pyrometer networks. Pursue platform procurement channel partnerships with industrial sensor marketplaces to bypass entrenched distributor relationships and establish price transparency. For Investors and Strategic Acquirers: The window for entry favors component-level sensor fabricators with silicon photodiode array capabilities and micro-optics integration expertise. Mid-cap specialists with captive detector material supply or specialized spectral filtering intellectual property present acquisition targets with defensible positioning through hydrogen combustion measurement cycles. Monitor IEC 62485 certification timeline announcements and European steel consortium hydrogen injection pilot results as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Captive indium gallium arsenide supply insulates margins from compound foundry price volatility. |
| Hydrogen-Fired Furnace Certification Investment | Two-color pyrometry with spectral filtering captures European steel decarbonization retrofit demand. |
| Calibration Infrastructure Regionalization | Portable blackbody capability in India and Saudi Arabia eliminates extended recertification downtime. |
| Platform Distribution Partnership | Industrial sensor marketplace integration compresses distributor markups and accelerates replacement part velocity. |
| Solid-State Architecture R&D Scale-Up | Silicon carbide sensing elements with embedded signal processing anchor semiconductor foundry thermal process control. |
Study Parameters
SEC filings, IEC standards documentation, and national metrology institute calibration records formed the secondary backbone, cross-referenced with customs data on detector material trade flows. Primary interviews with furnace operators at Baowu Steel and Cleveland-Cliffs, maintenance directors at German automotive foundries, and procurement leads at Taiwan logic foundries validated demand assumptions. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across stationary, portable, infrared, and optical product categories.
Bottom-up modeling built from individual country regulatory mandates—MEE air quality enforcement in China, EPA Greenhouse Gas Reporting Program amendments in the United States, PLI scheme implementation in India—aggregated through end-use verticals including steel, semiconductor, glass, and cement production. Top-down verification applied macro-industrial production indices and capital expenditure disclosures from furnace builders and system integrators. Segmentation dimensions spanned product type, temperature range, end user, and technology architecture across the projection horizon. CAGRs derived from regression analysis of historical substitution patterns between thermocouple and optical pyrometry, weighted by regulatory compliance deadline clustering.
Several conditions sit outside the modeled scope, including potential IEC 62485 revision delays extending commercial release timelines, and unanticipated breakthroughs in thermocouple materials science reversing optical substitution trends. Forecasts reflect assumptions regarding sustained indium gallium arsenide supply concentration and continued hydrogen-fired furnace pilot progression. Practitioners should monitor MEE enforcement intensity fluctuations, European steel consortium hydrogen injection scale-up announcements, and national metrology institute capacity expansion in emerging manufacturing economies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market