
 Thermal Imaging Systems Market | 2026-2036
Thermal Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Imaging Systems Market Outlook
Military-grade resolution standards are reorganizing supplier hierarchies in thermal imaging. Teledyne FLIR leverages its cooled-detector heritage to dominate aerospace and defense contracts. Raytheon Technologies anchors naval and ground-vehicle platform integration through captive sensor production. L3Harris Technologies competes across multi-spectral fusion systems for border surveillance and airborne missions.
Thermal imaging systems detect infrared radiation emitted by objects and convert it into visible images using detector arrays operating across specific wavelength bands, typically 7-14 μm for long-wave infrared applications. These systems enable non-contact temperature measurement and night-vision capability in industrial, medical, and security environments. Handheld cameras and fixed installations lead commercial revenue pools, while unmanned aerial vehicle payloads represent the fastest-expanding application segment as drone regulations mature. Long-wave infrared technology sustains the largest installed base due to uncooled detector cost efficiency, though dual-use technology configurations command premium pricing in defense-linked contracts.
FDA 510(k) clearance pathways shape medical diagnostic device commercialization timelines in the United States, while ITAR and EAR export controls administered by the US State Department and Commerce Department restrict thermal sensor transfer to designated countries. The EU AI Act and CE marking under the MDR framework increasingly govern automated thermal screening deployments in European healthcare and public safety contexts. Stakeholders must monitor evolving classification thresholds that could reclassify thermal sensors as dual-use items under multilateral export regimes.
Market Dynamics
Uncooled microbolometer focal plane array technology is collapsing unit costs below $500 for commercial-grade sensors, triggering volume expansion in industrial automation and drone payload applications while compressing margins for legacy cooled-detector suppliers.
Growth Catalysts
- ITAR Category XII modernization:The US State Department's revised export licensing thresholds for uncooled sensors below 640x480 resolution are accelerating commercial market entry for dual-use manufacturers.
- Industrial predictive maintenance:Manufacturing facilities in Germany and Japan are mandating thermal inspection protocols for electrical infrastructure, creating installed-base demand for fixed-mount monitoring systems.
- Swarm drone payload miniaturization:UAV operators require sub-150 gram thermal modules with sub-50 mK noise-equivalent temperature difference, driving sensor packaging innovation.
Market Restraints
- Vanadium oxide supply concentration:Thin-film deposition capacity for microbolometer thermistor materials concentrates in three East Asian foundries, creating input cost volatility.
- Long-wave infrared atmospheric attenuation:Water vapor absorption limits effective range beyond 2 kilometers in maritime environments, constraining coastal surveillance deployments.
- EAR licensing friction:US Commerce Department restrictions on focal plane array exports to Tier 2 countries block revenue capture in emerging industrial automation markets.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor packaging create localized assembly opportunities for export-restricted sensor modules.
- EU AI Act biometric screening carve-outs:Automated thermal fever detection systems receive regulatory clarity for public health deployments, opening healthcare infrastructure retrofit demand.
- Multi-spectral fusion convergence:Integration of thermal cores with visible-light CMOS and SWIR sensors enables single-payload solutions for precision agriculture and search-and-rescue operations.
Industry Challenges
- MEMS fabrication talent scarcity:Cleanroom process engineers with vanadium oxide deposition expertise command premium compensation, constraining foundry expansion timelines.
- FDA 510(k) thermal diagnostic certification:Clinical validation requirements for medical-grade temperature measurement accuracy extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Imaging Systems Market |
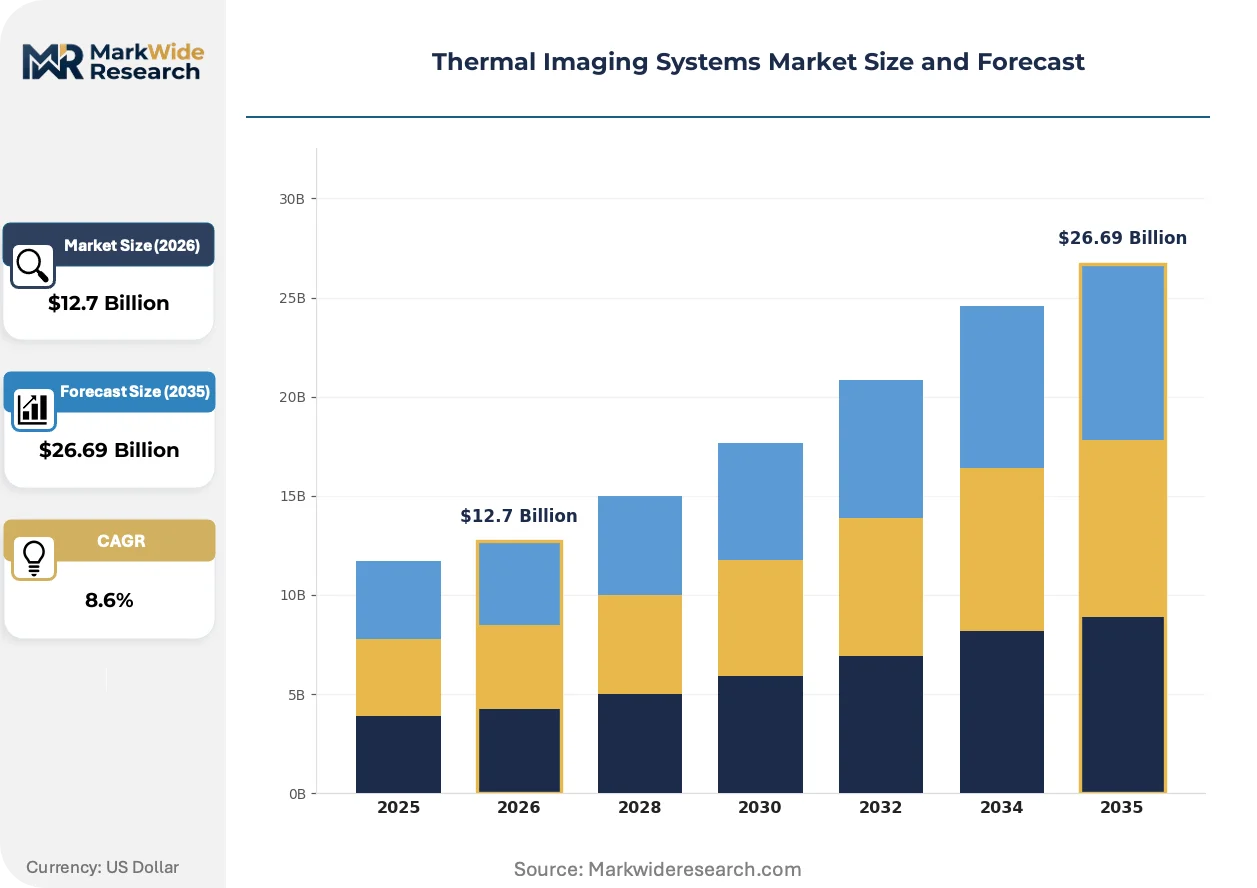
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Fixed Cameras, Thermal Scanners, Unmanned Aerial Vehicles Technology: Long-Wave Infrared, Short-Wave Infrared, Medium-Wave Infrared, Dual-Use Technology Application: Building Inspection, Surveillance, Medical Diagnostics, Industrial Maintenance End User: Manufacturing, Healthcare, Defense, Emergency Services |
| Companies Covered | Raytheon Technologies, Lockheed Martin, Teledyne FLIR, Seek Thermal, BAE Systems, Fluke Corporation, Thales Group, Jenoptik AG, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Imaging Systems Market Strategic Shifts
Sensor fusion architectures and edge-processing capabilities are redefining competitive differentiation, moving value capture from hardware specifications toward software-defined imaging pipelines and real-time analytics integration.
Wafer-level vacuum packaging for microbolometer arrays is decomposing the traditional ceramic-package supply chain. Automotive Tier 1 suppliers in Germany are adopting these sensors for night-vision pedestrian detection at 10x the 2019 procurement rate. The shift enables direct chip-on-board mounting, eliminating wire-bond subcontractors and compressing bill-of-materials costs by eliminating hermetic package suppliers.
The EU AI Act's risk-based classification system is mandating conformity assessments for automated thermal screening in public spaces. Airport operators and healthcare facilities must document algorithmic transparency and bias mitigation for fever-detection deployments. German hospital procurement committees are now requiring CE-MDR dual certification for clinical-grade devices, filtering out uncertified Asian suppliers.
Buyer consolidation among defense primes is compressing supplier negotiation cycles. Raytheon Technologies and L3Harris now mandate open-architecture sensor interfaces compatible with their multi-spectral fusion platforms. This forces component vendors to abandon proprietary SDKs and adopt standardized video output formats, eroding software lock-in strategies that previously protected margin structures.
Thermal Imaging Systems Market Segmentation
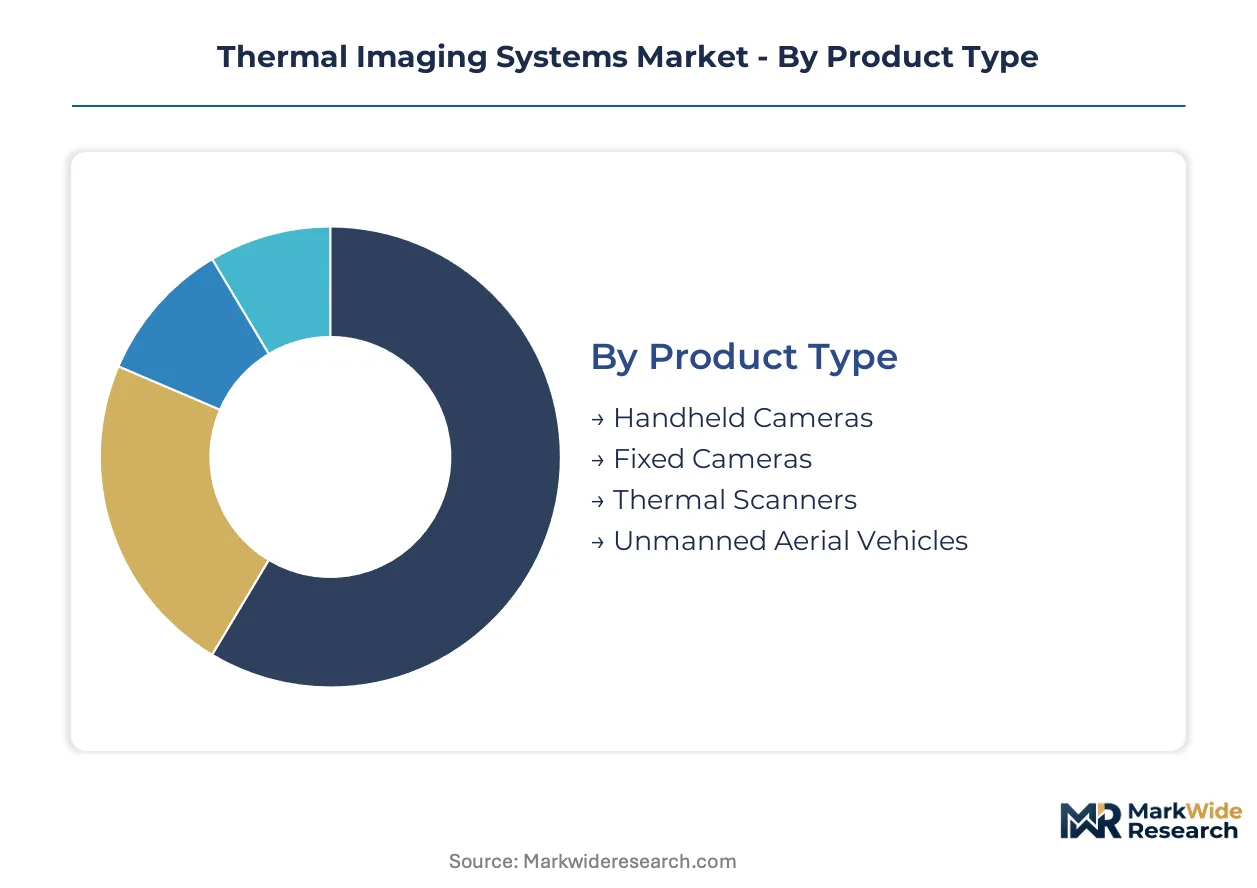
Thermal imaging markets fragment across detector physics, deployment form factors, and regulatory compliance tiers. Each segmentation axis carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
FDA 510(k) clearance and ITAR licensing thresholds split commercial viability across portable versus fixed installations.
- Handheld Cameras:Battery-powered units with uncooled microbolometer arrays dominate electrical inspection and firefighting applications. German industrial facilities mandate these for predictive maintenance under DGUV regulations.
- Fixed Cameras:Permanent-mount systems with Ethernet connectivity anchor manufacturing line monitoring and perimeter security. Japanese automotive plants deploy these for continuous thermal process verification.
- Thermal Scanners:Fever-detection gateways require CE-MDR dual certification for EU healthcare entry.
- Unmanned Aerial Vehicles:Sub-150 gram payloads serve precision agriculture and search-and-rescue missions.
Handheld cameras handle the majority of throughput; unmanned aerial vehicles are the fastest mover on share.
Technology:
Detector cooling requirements create three distinct cost-performance tiers that align with end-use budget cycles.
- Long-Wave Infrared:Uncooled vanadium oxide microbolometers operating at 7-14 μm dominate commercial volume. Unit costs below $500 unlock industrial automation and drone payload markets in the United States and Japan.
- Short-Wave Infrared:InGaAs photodiode arrays penetrate semiconductor wafer inspection and moisture detection. German machine vision integrators drive specification standards.
- Medium-Wave Infrared:Cooled mercury cadmium telluride detectors serve gas leak detection and high-temperature process monitoring.
- Dual-Use Technology:ITAR-controlled configurations with sub-50 mK NETD anchor NATO defense procurement.
Long-wave infrared carries the volume base; dual-use technology commands the premium tier on per-unit economics.
Application:
End-use certification intensity varies from voluntary industrial standards to mandatory medical device pathways.
- Building Inspection:Energy audit protocols in Germany and envelope moisture detection drive handheld procurement.
- Surveillance:Border security and critical infrastructure monitoring require ITAR-compliant or EU AI Act-conformant systems.
- Medical Diagnostics:FDA 510(k) and CE-MDR pathways govern clinical fever screening and vascular imaging. Validation timelines extend commercialization by 18-24 months.
- Industrial Maintenance:Predictive protocols for electrical infrastructure create recurring replacement demand in Japanese manufacturing.
Industrial maintenance absorbs the largest equipment flow; medical diagnostics is climbing the fastest on regulatory clarity.
End User:
Procurement authority centralization shapes vendor relationship structures and contract renewal patterns.
- Manufacturing:Plant engineering departments specify fixed-mount systems for continuous monitoring. German automotive Tier 1s drive wafer-level packaging adoption.
- Healthcare:Hospital procurement committees require dual certification for clinical-grade deployments. EU AI Act conformity assessments filter supplier pools.
- Defense:NATO modernization programs and India PLI scheme localization mandates reshape supply chains.
- Emergency Services:Fire departments and search teams prioritize handheld durability and battery autonomy.
Manufacturing represents the deepest installed base; defense is expanding most quickly on procurement budget growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vanadium oxide deposition capacity concentrates in East Asian foundries, yet procurement authority distributes across NATO defense budgets and German industrial automation mandates. The United States, Germany, and Japan absorb the dominant equipment flows, while India's PLI scheme and EU AI Act compliance requirements reshape localization strategies.
United States
Defense procurement budgets at Raytheon Technologies and L3Harris drive cooled-detector demand for aerospace and ground-vehicle integration. ITAR Category XII modernization by the US State Department accelerates commercial entry for uncooled sensors below 640x480 resolution. Boston-area defense clusters and Arizona semiconductor packaging facilities anchor dual-use manufacturing expansion.
Germany
Automotive Tier 1 suppliers adopt wafer-level vacuum packaging for night-vision pedestrian detection at tenfold 2019 procurement rates. DGUV regulations mandate handheld thermal cameras for electrical infrastructure predictive maintenance across industrial facilities. Bavarian automotive plants and Baden-Württemberg machine vision integrators drive specification standards for European export markets.
Japan
Manufacturing facilities deploy fixed-mount systems for continuous thermal process verification under METI industrial automation directives. JIS standards govern detector array performance benchmarks for domestic and export-qualified equipment. Nagoya-area automotive clusters and Tokyo electronics assembly corridors concentrate microbolometer integration expertise.
India
Production-linked incentive schemes for semiconductor packaging create localized assembly pathways for export-restricted sensor modules. DGFT licensing frameworks and defense modernization programs stimulate domestic thermal camera procurement for border surveillance applications. Bengaluru electronics manufacturing and Hyderabad defense research clusters attract component packaging investments.
United Kingdom
Border surveillance and critical infrastructure monitoring programs require ITAR-compliant or EU AI Act-conformant thermal systems post-Brexit regulatory alignment. Thales Group and BAE Systems anchor naval platform integration demand through captive sensor production. Scottish defense electronics corridors and Southeast England aerospace clusters sustain cooled-detector maintenance capabilities.
Thermal Imaging Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the thermal imaging value chain. Cooled-detector heritage defines premium-tier positioning for aerospace and defense contracts, while uncooled microbolometer scale operations capture industrial automation volume. Three archetypes dominate: defense-integrated primes with captive sensor production, commercial-focused component suppliers leveraging wafer-level packaging, and dual-use specialists navigating ITAR licensing thresholds. Consolidation pressure intensifies through open-architecture mandates and backward integration into focal plane array fabrication.
Within the defense-integrated tier, Raytheon Technologies, Teledyne FLIR, and L3Harris Technologies occupy positions shaped by NATO procurement cycles and export control compliance. Raytheon Technologies exemplifies naval and ground-vehicle platform anchoring through in-house detector production. Teledyne FLIR represents cooled-detector heritage translation into aerospace contract dominance. L3Harris Technologies sits within multi-spectral fusion system supply for border surveillance and airborne missions, illustrating how procurement consolidation forces standardized interface adoption across component vendors.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Lockheed Martin |
| Teledyne FLIR |
| Seek Thermal |
| BAE Systems |
| Fluke Corporation |
| Thales Group |
| Jenoptik AG |
| L3Harris Technologies |
| Others |
Value Chain & Pricing Dynamics
Wafer-level vacuum packaging substitution for ceramic hermetic enclosures is collapsing packaging costs while redistributing manufacturing gravity toward German automotive Tier 1 suppliers and Japanese electronics assemblers. This input replacement simultaneously erodes legacy wire-bond subcontractor margins and compresses bill-of-materials differentials between premium and standard thermal sensor tiers.
Pricing Analysis
ITAR Category XII licensing thresholds dictate the pricing tier structure by bifurcating the market into export-controlled sub-50 mK NETD configurations and commercial-grade uncooled alternatives. Three-tier pricing structure across ITAR-restricted, CE-MDR certified, and uncertified industrial grades reflects certification burden and detector cooling requirements. Cost compression in commercial microbolometers stems from vanadium oxide deposition yield improvements at East Asian foundries. Industrial automation buyers exhibit highest price sensitivity, while defense primes prioritize performance specifications over unit economics.
Supply Chain Analysis
Japan, Germany, and the United States anchor microbolometer integration and system assembly, though vanadium oxide thin-film deposition capacity concentrates in East Asian foundries. Raw material dependencies span indium antimonide for cooled detectors, germanium substrates for LWIR optics, and specialized ceramic feedthroughs for legacy packaging. Single-source vulnerability characterizes thermistor material deposition, where three foundries control global thin-film capacity. Distribution runs through defense prime captive procurement, automotive Tier 1 direct sourcing, and industrial distributor networks serving facility maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom process engineers with vanadium oxide deposition expertise command compensation premiums that constrain foundry expansion timelines, creating a structural bottleneck that favors incumbents with established talent pools and challenges entrants seeking scale.
For Market Incumbents: Shield aerospace and defense contract margins by accelerating backward integration into focal plane array fabrication, eliminating ceramic package supplier dependencies before wafer-level packaging achieves full cost parity. Lock in MEMS fabrication talent through captive training pipelines and equity retention structures, as emerging Chinese foundries attempt to poach experienced deposition engineers. For New Entrants and Emerging Players: Cloud-native thermal analytics software represents the most penetrable service-layer gap, as legacy vendors cling to proprietary SDKs that defense primes now reject. Target Indian electronics manufacturing services seeking sensor module assembly partnerships under PLI scheme incentives, positioning for re-export to Middle Eastern and Southeast Asian markets blocked by direct US EAR licensing. Lead with open-architecture API compatibility and edge-processing integration to bypass hardware specification barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial component suppliers that scaled uncooled microbolometer production during drone payload expansion but now face margin compression from Chinese price competition. Five-to-ten year viability hinges on successful certification navigation for medical and defense adjacent markets rather than pure volume scale. Watch for FDA 510(k) clearance announcements from previously industrial-only suppliers as the inflection signal indicating successful capability migration into premium healthcare tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Transition | Eliminates wire-bond subcontractors and compresses German automotive Tier 1 procurement costs. |
| Open-Architecture Sensor Interface Adoption | Aligns component vendors with Raytheon and L3Harris multi-spectral fusion platform mandates. |
| India PLI Scheme Localization | Creates assembly pathways for export-restricted modules serving Middle Eastern defense markets. |
| CE-MDR Dual Certification Investment | Filters Asian competitors from German hospital procurement committees under EU AI Act conformity requirements. |
| MEMS Fabrication Talent Pipeline Development | Secures vanadium oxide deposition expertise against East Asian foundry compensation escalation. |
Study Parameters
Initial hypotheses were tested against primary input from defense procurement officers at NATO primes, MEMS fabrication engineers at microbolometer foundries, hospital biomedical equipment committees, and automotive Tier 1 sensor integration teams, then refined through secondary validation against FDA 510(k) clearance databases, ITAR licensing records from the US State Department, EU AI Act implementation guidance, and METI industrial automation directive filings. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Variance decomposition across detector physics, deployment form factor, and regulatory compliance tier shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cooling requirement, resolution specification, end-use certification intensity, and geographic procurement authority concentration. CAGRs derived from shipment-volume elasticity to defense modernization cycle timing and industrial automation mandate adoption curves, with sensor fusion convergence rates and drone payload miniaturization trajectories as industry-specific forecast inputs.
Underlying assumptions cover ITAR licensing threshold stability, vanadium oxide deposition capacity expansion rates, and EU AI Act enforcement consistency, with deviation risk concentrated in export control reclassification events and MEMS fabrication talent migration patterns. Recalibration cycles align with material shifts in NATO procurement budget allocations and East Asian foundry capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Japan Digital X-Ray Market
Imaging
Photoacoustic Tomography Market
Imaging
Global Trail Camera Market
Imaging
Facial Recognition Machine Market
Imaging
Photoacoustic Microscope Market
Imaging
PET Scanners Market
Imaging
North America IP Camera Market
Imaging
Mobile Camera Module Market
Imaging
Thermal Imaging Market
Imaging
Industrial Computed Tomography Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Borescope Market
Imaging
Global Document Scanner Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
High-Speed Camera Market