
 Position Sensor Market | 2026-2036
Position Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Position Sensor Market Analysis
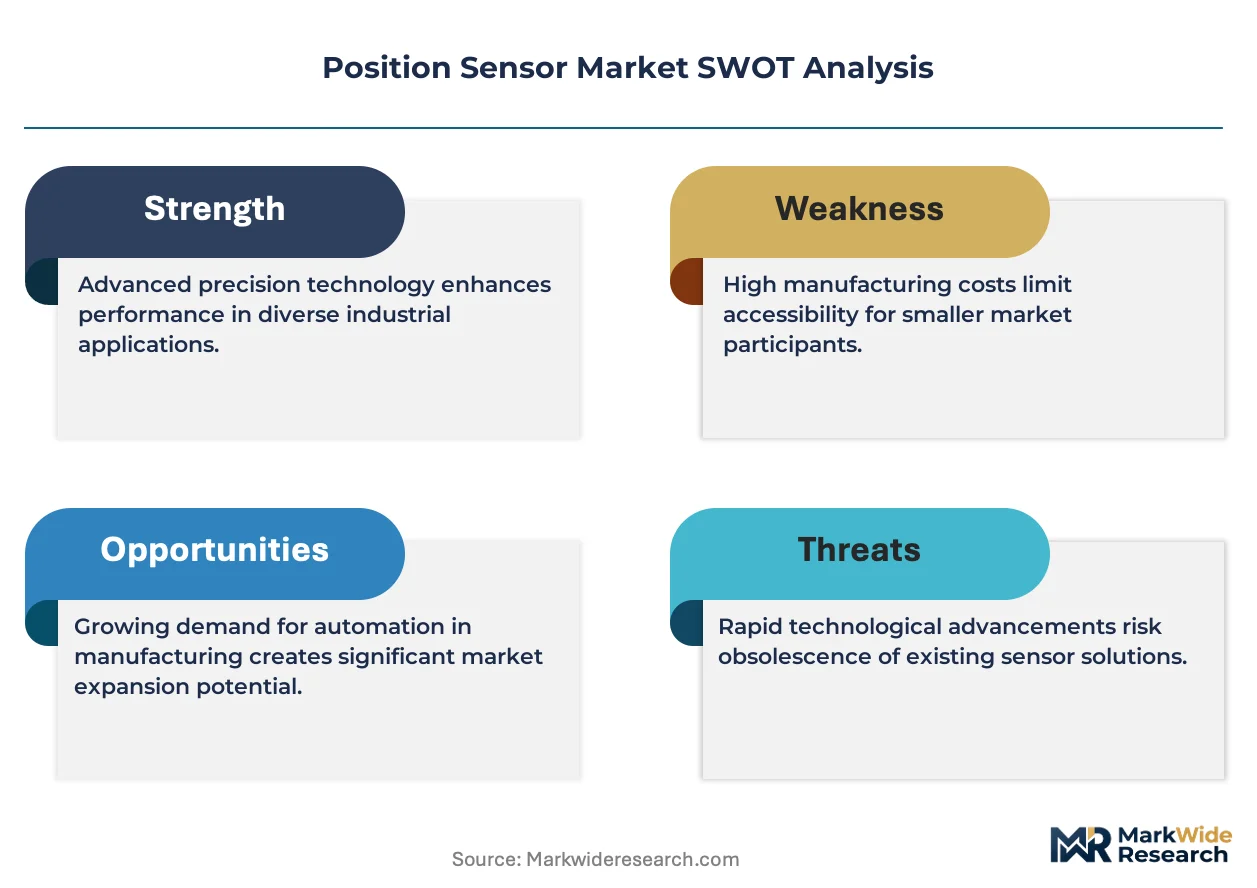
Non-contact sensing architectures is tilting position sensor design toward magnetoresistive and optical encoder platforms that eliminate mechanical wear. Honeywell International Inc. leverages its aerospace heritage to dominate high-reliability rotary applications for flight control surfaces. STMicroelectronics anchors its portfolio in magnetic angle sensors with ISO 26262 functional safety certification for automotive traction motors. Infineon Technologies AG specializes in inductive position sensing for electric vehicle powertrains, competing on temperature stability across extreme operating ranges.
A position sensor detects and converts mechanical displacement into electrical signals with typical resolution ranging from micrometers to sub-arc-minute precision, serving closed-loop control in machinery, vehicles, and instrumentation. Magnetic technology leads volume shipments due to cost efficiency and immunity to contaminants in factory environments, while optical encoders command premium positioning in semiconductor lithography and medical imaging where nanometer precision is mandatory. Among end users, industrial automation sustains the largest installed base, though robotics applications are expanding fastest as collaborative robot deployments multiply across assembly and logistics operations.
Functional safety mandates from ISO 13849 and IEC 61508 shape product design for industrial and machinery applications, while automotive OEMs require AEC-Q100 qualification and ISO 26262 ASIL ratings from suppliers. The EPA and NHTSA in the United States, alongside REACH and RoHS frameworks in Europe, constrain material selection and manufacturing processes for sensors deployed in mobility and environmental applications. Stakeholders must monitor how emerging IEC standards for collaborative robot safety recalibrate encoder accuracy and response-time requirements.
Market Dynamics
Automotive electrification mandates are compressing development cycles for position sensors, forcing suppliers to recalibrate magnetic and optical platforms for ISO 26262 ASIL-D functional safety compliance in traction motor and battery management deployments.
Growth Catalysts
- EU Green Deal vehicle electrification:Binding CO2 fleet targets accelerate sensor integration in electric powertrains across German and French OEM supply chains.
- Collaborative robot safety standards:Emerging IEC 62443 and ISO/TS 15066 requirements expand encoder demand in Chinese and Japanese assembly automation.
- Inductive sensing:Temperature-stable architectures displace Hall-effect devices in EV battery thermal management systems.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing dependence on Chinese refiners exposes magnetic sensor producers to input volatility and export restriction risk.
- Optical encoder cost structure:Precision glass scale and laser diode inputs sustain 3-5x manufacturing cost premiums versus magnetic alternatives, constraining adoption outside semiconductor lithography.
- Functional safety certification friction:ISO 13849 and IEC 61508 validation timelines extend 18-24 months, delaying product launches for industrial automation suppliers.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for robotics and electronics manufacturing create greenfield demand for cost-optimized magnetic angle sensors.
- Medical imaging precision:Sub-micron optical encoder requirements in MRI and CT scanner gantries command premium pricing and long-term supply contracts.
- Wireless inductive convergence:Integration of energy harvesting and position sensing eliminates cabling in rotating machinery across wind turbine and aerospace applications.
Industry Challenges
- Embedded software competency gaps:Sensor-fusion algorithm development and ASIL-compliant firmware engineering outpace available talent pools in Midwest US and Central European industrial corridors.
- Legacy system integration complexity:Analog output formats and proprietary fieldbus protocols in installed industrial bases complicate digital encoder retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Position Sensor Market |
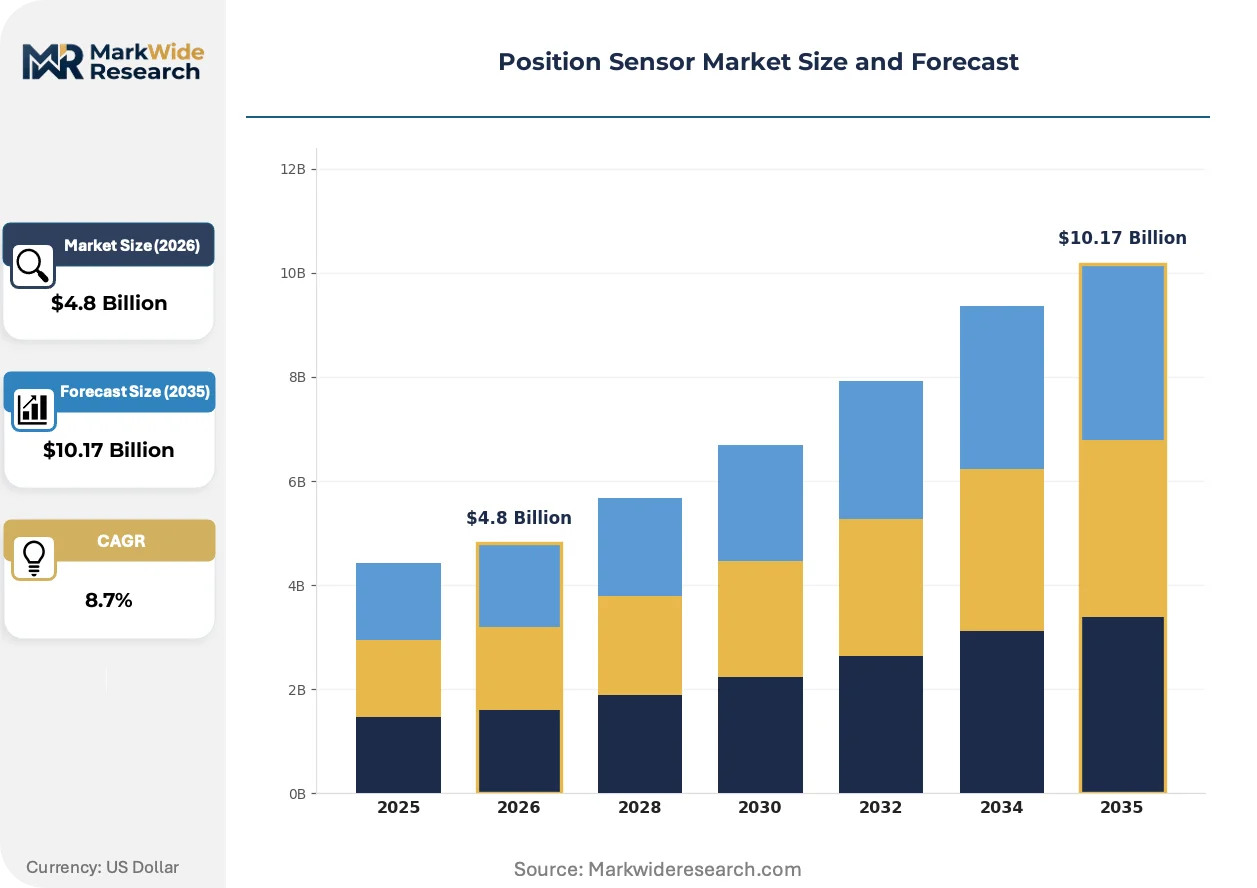
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inductive, Capacitive, Magnetic, Optical End User: Automotive, Industrial Automation, Aerospace, Consumer Electronics Application: Motion Control, Robotics, HVAC Systems, Medical Devices Form Factor: Linear, Rotary, Angle, Proximity |
| Companies Covered | Honeywell International Inc., TDK Corporation, STMicroelectronics, TE Connectivity, SICK AG, Infineon Technologies AG, Texas Instruments Incorporated, Analog Devices Inc., Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Position Sensor Market Emerging Trajectories
Position sensing architectures are fragmenting across three vectors: magnetic-optical hybrid platforms, safety-critical certification acceleration, and procurement model compression toward module-level supplier consolidation.
Magnetoresistive sensor technology is hybridizing with optical encoder precision in unified packages that switch sensing modalities based on contamination exposure and accuracy requirements. Automotive tier-1 suppliers in Germany and Japan are qualifying these dual-mode devices for steer-by-wire and brake-by-wire systems. The convergence is collapsing the traditional premium-economy tier boundary in automotive position sensing.
REACH substance restrictions and RoHS material constraints are forcing reformulation of solder alloys and encapsulant compounds in European sensor manufacturing. ECHA's SVHC candidate list expansion is accelerating substitution of lead-containing piezoelectric materials in ultrasonic position sensors. Medical device and food processing equipment producers face the steepest compliance recalibration timelines.
Automotive OEMs are consolidating position sensor procurement at the e-axle module level rather than discrete component sourcing, compressing supplier tiers and shifting design-in authority to powertrain integrators. This reconfiguration is most advanced in German and South Korean EV platforms, where magnetic angle sensor specifications are now locked by tier-1 motor suppliers rather than OEM engineering teams.
Position Sensor Market Segmentation
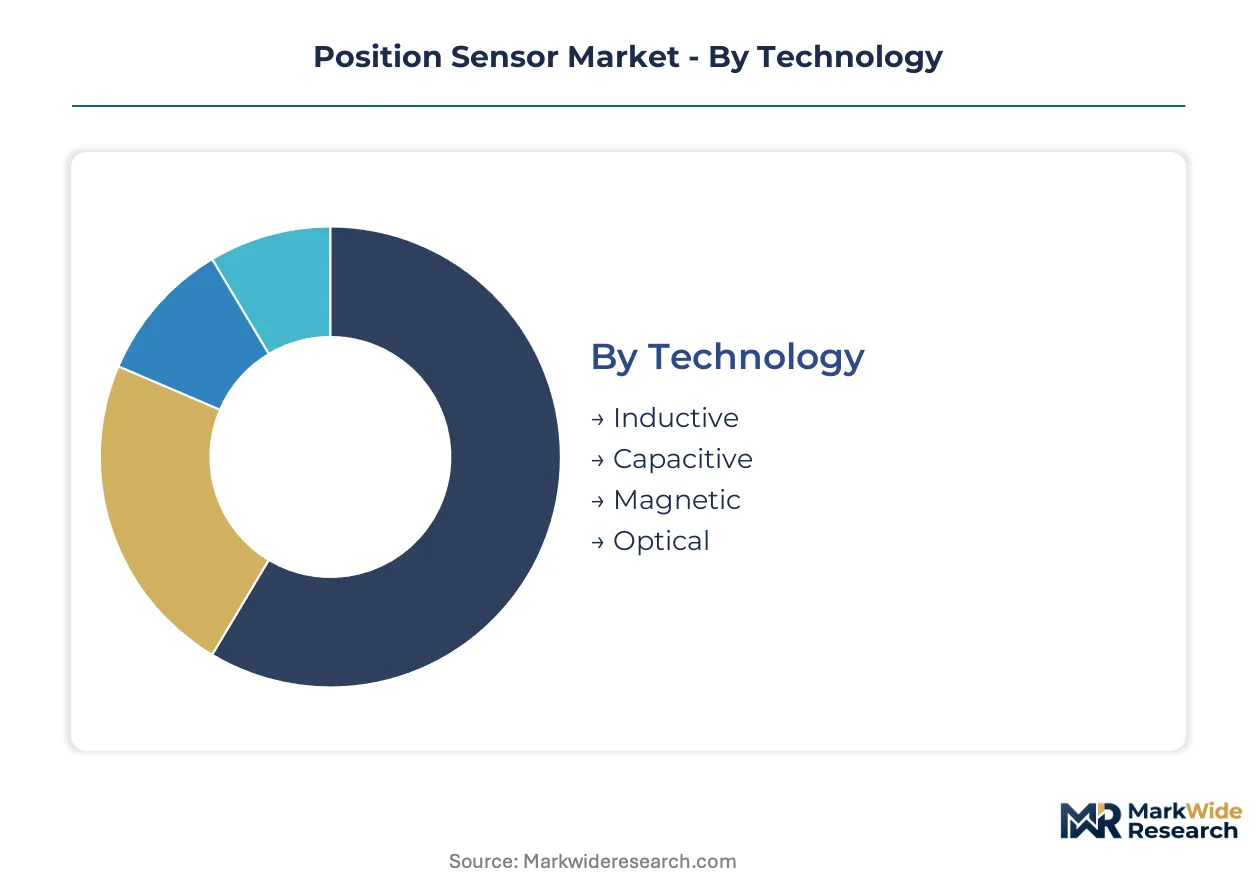
Position sensor architectures fragment across four distinct dimensions, each dictating procurement priorities and supplier qualification pathways. Technology selection determines contamination immunity and precision ceilings, while end-user verticals impose divergent certification regimes.
Technology:
Magnetic and optical platforms anchor opposite ends of the cost-precision spectrum, with inductive architectures emerging as the temperature-stable middle ground for electric vehicle powertrains.
- Magnetic:Hall-effect and magnetoresistive elements deliver sub-degree angular resolution with inherent immunity to dust, oil, and moisture. German and Japanese automotive OEMs specify magnetic angle sensors for traction motor commutation, prioritizing ISO 26262 ASIL-D compliance over absolute precision.
- Optical:Interferometric and photoelectric encoders achieve nanometer-scale linear resolution through glass scale gratings and laser diode illumination. Semiconductor lithography equipment in Taiwan and the Netherlands commands this tier, where vacuum-compatible packaging justifies manufacturing cost premiums.
- Inductive:Eddy-current and resonant inductive sensing eliminates rare-earth magnet dependencies while maintaining stability across −40°C to 150°C operating ranges. EV battery thermal management systems in the United States and South Korea are displacing Hall-effect devices with inductive alternatives.
- Capacitive:Dielectric variation detection enables non-contact displacement measurement with minimal power draw. Consumer electronics touch interfaces and MEMS accelerometers in Shenzhen manufacturing clusters absorb capacitive position sensing at high volumes.
The dominant share belongs to magnetic sensing, while inductive architectures are closing the gap fastest.
End User:
Automotive qualification timelines stretch 24-36 months, compressing supplier margins, whereas industrial automation permits faster design-in cycles with lower certification overhead.
- Automotive:Electric powertrain integration demands redundant position feedback for motor commutation, steering angle, and pedal position. NHTSA FMVSS requirements and EPA electrification mandates in the United States converge with EU Green Deal fleet targets to accelerate sensor deployment.
- Industrial Automation:Servo motor encoders and linear scale feedback systems populate Chinese factory floors at scale. Collaborative robot safety standards IEC 62443 and ISO/TS 15066 are expanding encoder specifications for force-limited articulated arms.
- Aerospace:DO-178C software assurance and DO-254 hardware certification constrain supplier pools to aerospace heritage manufacturers. Flight control surface position feedback requires hermetic packaging and radiation-hardened electronics.
- Consumer Electronics:Camera autofocus mechanisms and gaming controller joysticks prioritize cost minimization over precision. Shenzhen and Taipei manufacturing ecosystems drive capacitive and Hall-effect integration at consumer price points.
Industrial automation sustains the largest installed base, though automotive electrification is expanding most quickly.
Application:
Motion control and robotics applications diverge in precision requirements, with medical devices imposing the most stringent validation protocols.
- Motion Control:CNC machine tool linear encoders and servo motor feedback systems demand sub-micron repeatability. German machine builders specify Heidenhain and Renishaw optical scales for five-axis machining centers.
- Robotics:Six-axis articulated arms and SCARA systems require absolute encoders with battery-free multiturn counting. Chinese logistics automation deployments are multiplying demand for compact magnetic encoders with SIL-2 functional safety.
- HVAC Systems:Damper position feedback and variable refrigerant flow valve control prioritize cost efficiency over precision. Building automation integrators in the United States specify potentiometric and Hall-effect sensors for commercial climate control.
- Medical Devices:MRI scanner gantry positioning and surgical robot arm feedback command sub-micron optical encoder performance. FDA 510(k) clearance timelines and IEC 60601-1 electrical safety requirements extend product development cycles.
Motion control retains volume leadership, while medical devices command the steepest pricing premiums.
Form Factor:
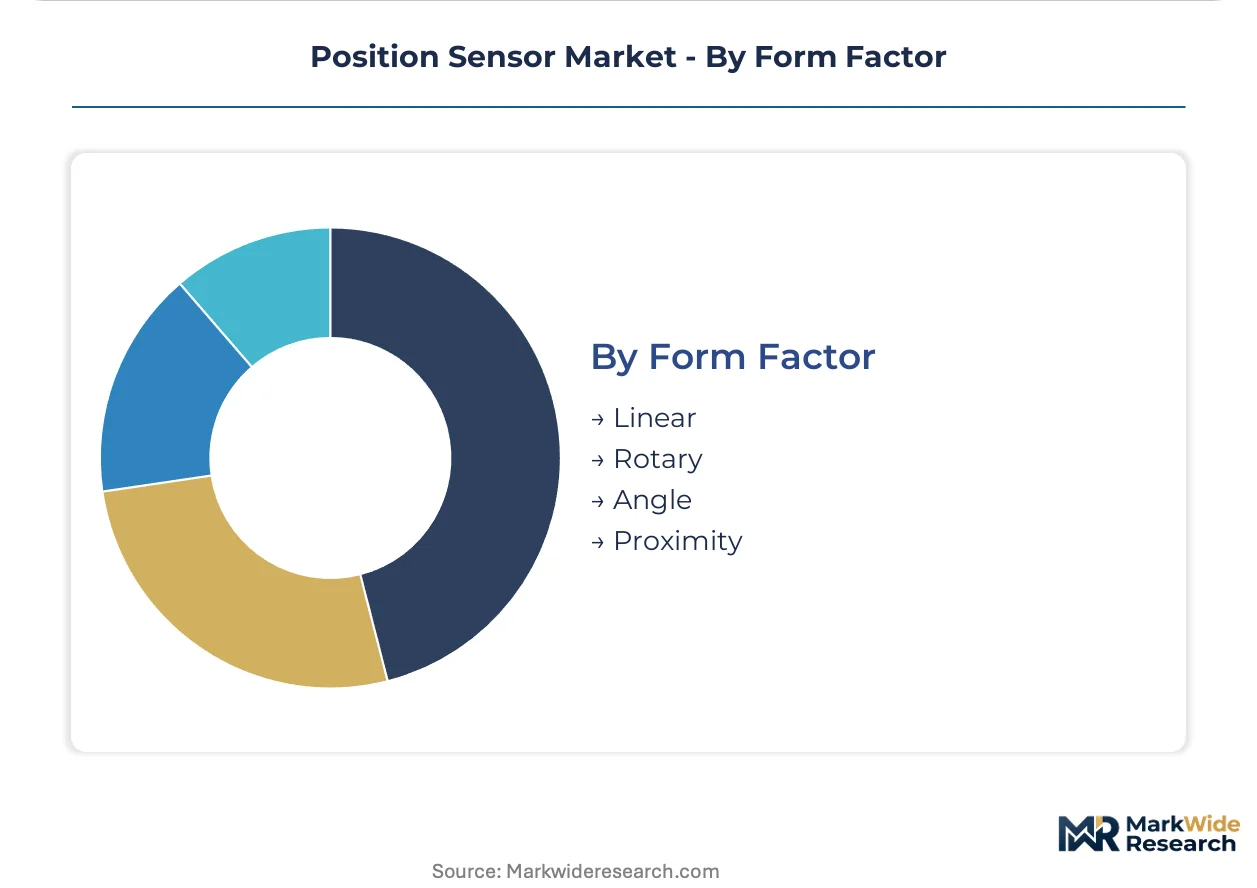
Linear and rotary geometries dominate mechanical integration patterns, with angle sensors capturing the fastest-growing electric vehicle motor feedback segment.
- Linear:Scale-and-reader configurations measure displacement along a single axis with resolutions from micrometers to nanometers. Machine tool and semiconductor equipment applications in Japan and Germany specify exposed or sealed linear encoder variants.
- Rotary:Shaft-mounted encoders and hollow-bore designs accommodate motor and gearbox integration. Multi-turn absolute encoders with geartrain or electronic counting eliminate homing sequences in industrial automation.
- Angle:Two-axis magnetic sensors detect rotor position in brushless DC motors without mechanical contact. Automotive e-axle modules specify angle sensors with sine-cosine analog or digital SPI outputs.
- Proximity:Discrete presence detection and distance measurement applications favor inductive and capacitive non-contact switches. Factory automation safety curtains and level sensing in process industries deploy proximity variants.
Rotary encoders hold the dominant installed position, while angle sensors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Chinese industrial automation integrators represent the dominant buyer archetypes, with procurement authority consolidating around e-axle module suppliers in Stuttgart and Munich, and robotics system integrators in Shenzhen and Shanghai.
United States
EV battery thermal management and wind turbine pitch control drive inductive sensor procurement. NHTSA FMVSS requirements and EPA electrification mandates compress supplier qualification timelines. Detroit-area automotive tier-1s and Texas wind energy clusters anchor magnetic angle sensor deployment.
Germany
Steer-by-wire and brake-by-wire programs at BMW, Mercedes-Benz, and Volkswagen expand ASIL-D certified encoder integration. EU Green Deal fleet targets and KBA type-approval protocols enforce functional safety compliance. Bavarian powertrain engineering centers and Baden-Württemberg automotive supplier parks concentrate design-in authority.
China
Collaborative robot deployments across assembly and logistics operations multiply demand for compact magnetic encoders. MIIT industrial robot industry development guidelines and GB standards for collaborative safety recalibrate encoder specifications. Shenzhen manufacturing clusters and Shanghai automation equipment districts absorb high-volume magnetic sensing shipments.
Japan
Semiconductor lithography equipment and precision machine tools sustain optical encoder demand at nanometer precision tiers. METI semiconductor industry revitalization policies and JIS standards for motion control components shape procurement criteria. Nagoya industrial automation corridors and Tokyo precision equipment districts command premium positioning.
South Korea
EV powertrain integration at Hyundai-Kia and battery manufacturing automation expand angle sensor and linear encoder deployment. MFDS medical device regulations and national EV subsidy programs accelerate sensor qualification. Seoul metropolitan area electronics manufacturing and Busan automotive component clusters drive regional consumption.
Position Sensor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with aerospace heritage, semiconductor specialists with functional safety certification capabilities, and precision equipment heritage manufacturers with lithography-grade optical expertise. Competitive moves concentrate on module-level supplier consolidation by automotive tier-1s and accelerated ASIL-D certification timelines for traction motor feedback.
Within the diversified industrial tier, Honeywell International Inc. and TE Connectivity occupy positions shaped by aerospace and industrial automation heritage respectively. Among semiconductor specialists, STMicroelectronics and Infineon Technologies AG exemplify magnetic sensing platforms with automotive safety certification. SICK AG represents precision equipment heritage with industrial automation encoder specialization. These named entities anchor archetype differentiation rather than exhaust competitive positioning.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| TDK Corporation |
| STMicroelectronics |
| TE Connectivity |
| SICK AG |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Analog Devices Inc. |
| Amphenol Corporation |
| Others |
Supply Flow & Price Mechanics
Jiangxi rare-earth refining clusters concentrate neodymium and dysprosium processing for magnetic sensor cores, granting Chinese suppliers asymmetric leverage over Hall-effect and magnetoresistive device pricing. Automotive OEMs in Stuttgart and Detroit face cost-plus contracts indexed to Shanghai Metal Market rare-earth oxide quotations, compressing margin flexibility for European and North American magnetic sensor assemblers.
Pricing Analysis
Cost-plus contracts with Shanghai Metal Market indexation dominate magnetic sensor procurement, while optical encoders command fixed-price long-term offtakes tied to semiconductor equipment capex cycles. Price differentiation rests on ISO 26262 ASIL certification tier and rare-earth magnet content grade. Pricing pressure intensifies in standard-grade magnetic angle sensors as Chinese producers expand capacity for EV motor feedback applications. Industrial automation integrators in Shenzhen exhibit highest price sensitivity, whereas medical imaging OEMs in the Netherlands accept premiums for vacuum-compatible optical packaging.
Supply Chain Analysis
Export-control regimes limiting gallium arsenide laser diode and precision glass scale shipments constrain optical encoder supply elasticity for semiconductor lithography equipment. Manufacturing concentrates in China, Japan, and Germany, with rare-earth magnet drawing from Jiangxi refiners, optical components from Nagoya precision districts, and inductive coil winding from Bavarian automotive supplier parks. Single-source vulnerability runs through Chinese rare-earth processing concentration. Distribution feeds from tier-1 powertrain integrators in Stuttgart and Munich rather than discrete component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Position sensor demand tracks automotive production cycles with pronounced EV powertrain investment waves, positioning the market for cyclical recovery as German and South Korean OEMs accelerate e-axle platform launches.
For Market Incumbents: Harden ASIL-D certification moats in traction motor feedback through accelerated ISO 26262 validation timelines, closing the 18-24 month gap that emerging Chinese suppliers exploit. Deepen backward integration into rare-earth magnet sourcing via offtake agreements with Australian and Vietnamese mining projects, reducing Jiangxi refinery concentration risk. Channel control through e-axle module supplier partnerships in Baden-Württemberg secures design-in authority against tier-1 consolidation.
For New Entrants and Emerging Players: Establish a beachhead in inductive position sensing for EV battery thermal management, where temperature-stable architectures displace Hall-effect devices and certification barriers remain lower than ASIL-D motor feedback. Target Indian industrial automation under PLI scheme incentives, where greenfield robotics deployments seek cost-optimized magnetic angle sensors without legacy fieldbus integration burdens. Lead with wireless inductive convergence offerings that eliminate cabling in wind turbine and aerospace rotating machinery.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor specialists with functional safety firmware competency over diversified industrial conglomerates with aerospace heritage. Long-term viability in the 5-10 year window rests on embedded software talent acquisition and module-level supplier consolidation capture. Watch for inflection in collaborative robot safety standard IEC 62443 adoption rates across Chinese logistics automation deployments as the demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses 18-24 month validation timelines to match German automotive tier-1 procurement cycles. |
| Rare-Earth Supply Diversification | Reduces Jiangxi refinery concentration risk through Australian and Vietnamese mining offtakes. |
| Inductive Sensing Platform Launch | Captures EV battery thermal management displacement of Hall-effect temperature limitations. |
| Wireless Inductive Convergence | Eliminates cabling maintenance in wind turbine pitch control and aerospace flight surfaces. |
| Module-Level Supplier Consolidation | Aligns with BMW and Hyundai-Kia e-axle integration shifting design-in authority to tier-1s. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with automotive tier-1 procurement directors, industrial automation plant engineers, and semiconductor lithography equipment specialists, combined with secondary validation against SEC 10-K filings, MIIT industrial robot statistics, and EU Green Deal fleet compliance databases. Bottom-up sensor shipment estimates by technology and end-use triangulated against top-down OEM powertrain production forecasts across the analysis window.
Forecast inputs span magnetic, optical, inductive, and capacitive technology segments across automotive, industrial automation, aerospace, and consumer electronics end-uses, with additional modeling for form factor adoption in e-axle angle sensors. CAGRs derive from regression against EV powertrain penetration curves and collaborative robot deployment trajectories, incorporating REACH substance restriction compliance timelines and rare-earth price volatility assumptions.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes or Chinese export license restrictions would shift the trajectory. Forecasts reflect documented assumptions around ISO 26262 certification adoption rates and rare-earth supply concentration persistence. Material shifts in EU Green Deal enforcement stringency or MIIT industrial robot subsidy programs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
PM2.5 Sensors Market