
 Glass-Free HD 3D Display Market | 2026-2036
Glass-Free HD 3D Display Market Size, Share, and Industry Trends Forecast 2026-2036
Glass-Free HD 3D Display Market Analytics
Buyer concentration across entertainment chains and flagship retail networks is recalibrating procurement volumes toward larger-format autostereoscopic installations. Samsung Electronics leverages its semiconductor-to-panel vertical chain to control backlight and lenticular lens supply. LG Electronics anchors its position through OLED-based light field prototypes targeting premium cinema and broadcast applications. AUO Corporation competes on manufacturing scale, sustaining cost advantages in high-resolution barrier-grid panels for commercial digital signage.
Glass-free HD 3D displays render stereoscopic depth without polarized or shutter eyewear, typically employing lenticular lenses, parallax barriers, or directional backlighting to direct discrete images to each eye at resolutions exceeding 1080p per view. These systems serve commercial advertising, medical visualization, and immersive entertainment where user throughput and hygiene concerns render glasses-based systems impractical. Lenticular displays currently occupy the largest installed base among product types due to mature roll-to-roll manufacturing and compatibility with existing LCD fabrication lines. Light field displays represent the fastest-expanding technology segment, as plenoptic arrays enable continuous viewing angles without the sweet-zone limitations of barrier-grid approaches. Holography sustains niche demand in scientific and defense visualization where volumetric fidelity outweighs cost constraints.
FCC equipment authorization rules in the United States govern electromagnetic emissions from integrated 3D display systems, while the EU Green Deal and RoHS directives restrict hazardous substances in backlight assemblies and driver boards. China's MIIT enforces GB standards for display energy efficiency and electromagnetic compatibility, shaping product certification requirements for manufacturers targeting domestic procurement. South Korea's MFDS and KATS frameworks influence medical-grade 3D display specifications for surgical planning applications. Stakeholders must monitor evolving interoperability standards between real-time rendering engines and hardware-specific depth formats as content ecosystems fragment across proprietary platforms.
Market Dynamics
Plenoptic lens arrays and real-time rendering software are compressing hardware complexity while expanding viable use cases for autostereoscopic displays across commercial advertising and medical visualization.
Growth Catalysts
- EU RoHS and Green Deal mandates:Hazardous substance restrictions in backlight assemblies are accelerating LED-based directional backlighting adoption over mercury-laden alternatives in European digital signage procurement.
- Medical visualization demand:South Korea's MFDS framework for surgical planning displays is creating certified product categories that command premium positioning in hospital procurement.
- Roll-to-roll lenticular manufacturing:Compatibility with existing LCD fabrication lines in Chinese and Japanese panel clusters is lowering capital barriers for display makers entering glass-free 3D production.
Market Restraints
- Indium tin oxide supply concentration:Over 80 percent of refined indium processing sits within Chinese state-influenced supply chains, creating input cost volatility for transparent electrode layers.
- Sweet-zone limitations in barrier-grid systems:Discrete viewing angles restrict user positioning flexibility, limiting deployment in high-traffic retail environments where pedestrian movement is unpredictable.
- Content ecosystem fragmentation:Proprietary depth formats across hardware platforms force buyers into single-vendor rendering pipelines, raising total cost of ownership.
Strategic Opportunities
- India's PLI scheme for display manufacturing:Production-linked incentives for semiconductor and display ecosystems are attracting module assembly investments that could serve Middle Eastern and African markets.
- Holographic volumetric displays:Convergence of photorefractive polymers with real-time compute is opening defense and scientific visualization segments where fidelity premiums offset unit economics.
- Experiential retail networks:Flagship store rollouts by luxury automotive and cosmetics brands are creating dedicated channels for large-format autostereoscopic installations with bundled content service contracts.
Industry Challenges
- Optical engineer scarcity:Specialized expertise in wavefront engineering and micro-lens design concentrates within Japanese and South Korean research institutes, constraining R&D scaling for new entrants.
- Multi-jurisdictional certification timelines:Simultaneous FCC authorization, EU CE marking, and China MIIT GB compliance for integrated 3D systems extends product launch cycles by 8-14 months.
- Legacy content conversion:Stereoscopic asset pipelines built for glasses-based cinema formats require complete reconstruction for autostereoscopic output, raising content production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass-Free HD 3D Display Market |
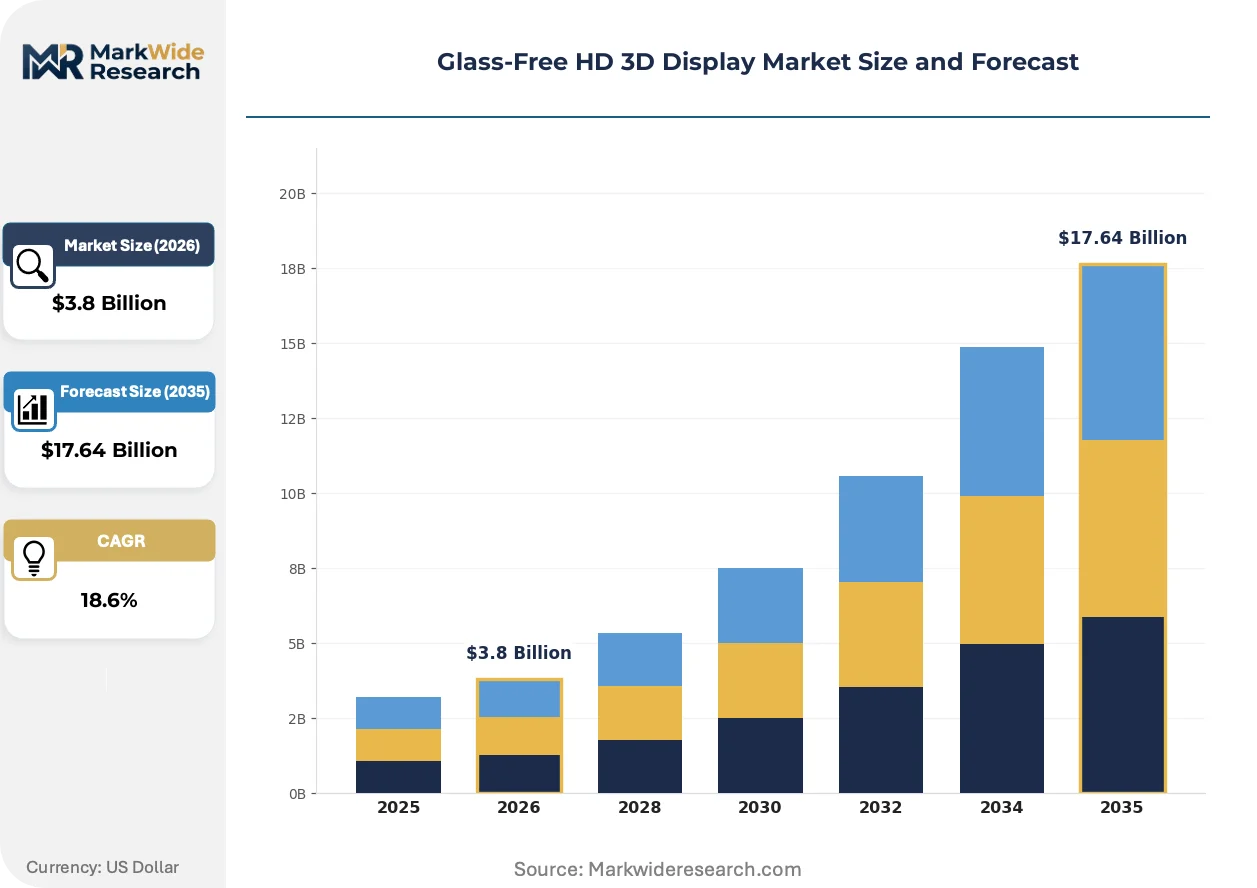
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autostereoscopic Displays, Volumetric Displays, Light Field Displays, Lenticular Displays Technology: Barrier Grid, Plenoptic Technology, Projection Mapping, Holography End User: Aerospace, Retail, Healthcare, Entertainment Installation: Wall-Mounted, Portable, Ceiling-Mounted, Integrated Systems |
| Companies Covered | Samsung Electronics, LG Electronics, Philips, Alioscopy, Holografika, AUO Corporation, Dimenco, Leia Inc., Evistek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass-Free HD 3D Display Market Evolving Landscape
Real-time depth processing and light field capture technologies are dissolving the boundary between content creation hardware and display systems, enabling dynamic viewpoint adaptation without fixed camera positions.
Plenoptic camera arrays are converging with edge-based neural rendering to enable live volumetric capture for broadcast applications. Sports venues and concert promoters are deploying these integrated capture-to-display pipelines for real-time immersive replay experiences. The technology is converging with 5G network slicing to compress transmission latency between venue and remote display installations.
China's MIIT enforcement of updated GB standards for display electromagnetic compatibility is tightening emission thresholds for driver boards in integrated 3D systems. Domestic manufacturers are redesigning power management circuits to meet these specifications ahead of international competitors. Medical-grade display segments targeting China's hospital procurement tenders are absorbing the bulk of compliance-driven R&D investment.
Flagship retail networks are consolidating vendor relationships around integrated hardware-content-service bundles rather than discrete display purchases. Luxury automotive showrooms and cosmetics flagship stores are leading this shift, negotiating multi-year experiential content subscriptions alongside autostereoscopic hardware deployment. This pattern is most visible in Shanghai, Tokyo, and Dubai where experiential marketing budgets concentrate in high-traffic commercial districts.
Glass-Free HD 3D Display Market Segmentation
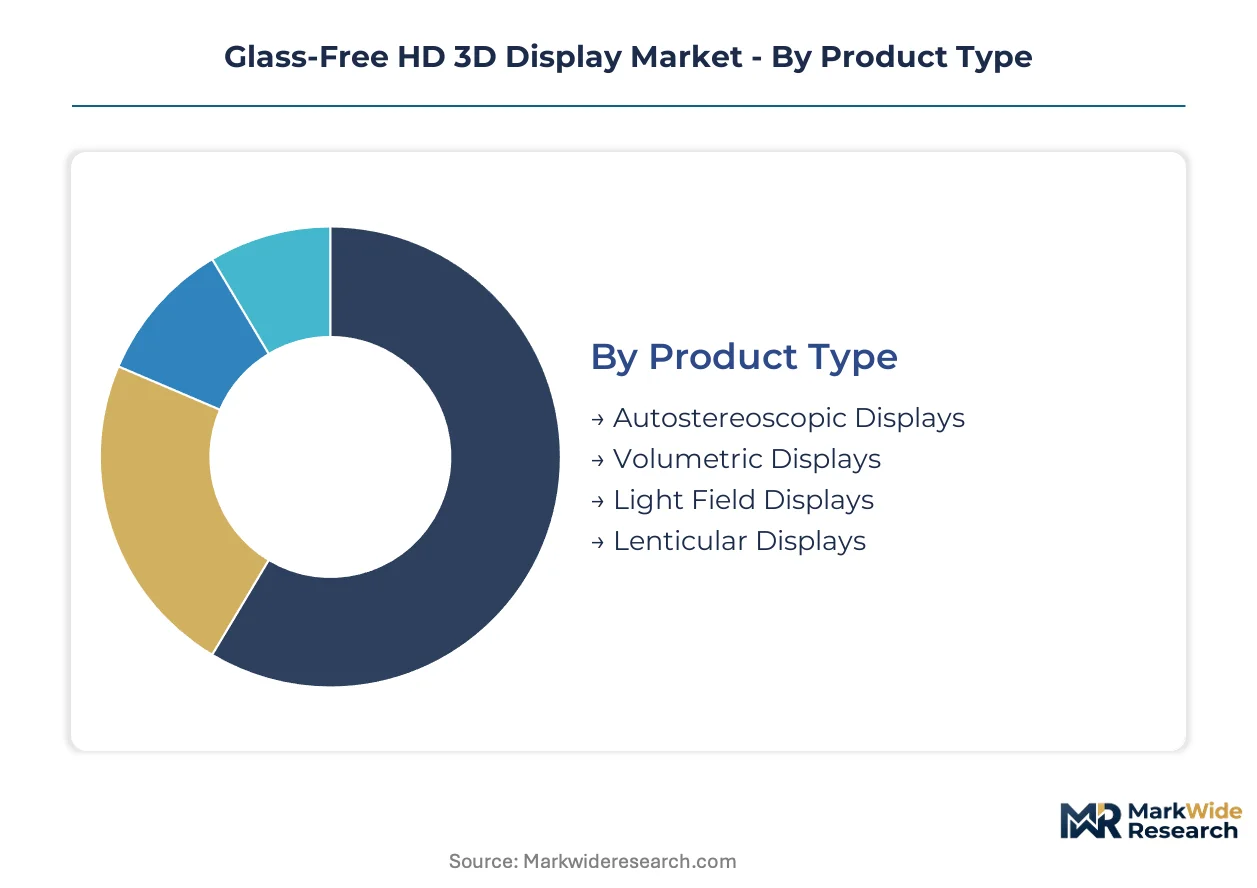
Technology architecture and deployment configuration determine procurement economics for glass-free 3D displays. Buyers select across optical approaches, integration methods, and end-use specifications that reshape total cost of ownership and content pipeline requirements.
Product Type:
Lenticular lens arrays and directional backlighting architectures dominate current manufacturing capacity and commercial deployment.
- Lenticular Displays:Cylindrical lens sheets bonded to LCD panels direct discrete images to each eye using mature roll-to-roll fabrication. Chinese and Japanese panel clusters sustain cost advantages through compatibility with existing TFT-LCD lines, serving high-volume digital signage networks.
- Light Field Displays:Plenoptic arrays generate continuous parallax across viewing positions without sweet-zone constraints. South Korean broadcast infrastructure investments and premium cinema trials in Tokyo are absorbing early production runs as manufacturing yields improve.
- Autostereoscopic Displays:Directional backlighting systems with time-multiplexed scanning enable thin-form-factor integration for kiosks and point-of-sale terminals.
- Volumetric Displays:Swept-volume and static-volume systems render true 3D imagery viewable without head-tracking, occupying niche medical and defense visualization segments.
Lenticular displays lead on scale; light field displays lead on momentum.
Technology:
Optical engine selection governs viewing angle flexibility, hardware thickness, and content rendering complexity.
- Plenoptic Technology:Microlens arrays capture and reproduce light field information, enabling post-capture focus adjustment and continuous viewpoint generation. Real-time neural rendering pipelines from Seoul and San Francisco software vendors are compressing compute requirements for live broadcast deployment.
- Barrier Grid:Parallax barriers block light paths to separate left and right eye images through precision-aligned apertures. Manufacturing simplicity sustains cost competitiveness for price-sensitive retail signage in Indian and Southeast Asian markets.
- Holography:Photorefractive polymers and spatial light modulators reconstruct wavefronts with volumetric fidelity, serving scientific instrumentation and defense simulation where fidelity premiums justify unit costs.
- Projection Mapping:Multi-projector arrays with viewpoint-dependent rendering create large-scale immersive surfaces for concert venues and experiential marketing installations.
Barrier grid dominates unit shipments; plenoptic technology expands most quickly into premium segments.
End User:
Application environment dictates durability specifications, hygiene protocols, and content refresh rates.
- Entertainment:Cinema chains and theme parks deploy large-format autostereoscopic screens for immersive pre-show advertising and queue-line entertainment, with experiential content subscriptions bundled into hardware procurement.
- Retail:Flagship cosmetics and automotive showrooms in Shanghai, Tokyo, and Dubai install wall-mounted systems for product visualization with high pedestrian throughput requirements.
- Healthcare:Surgical planning and radiological visualization under South Korea's MFDS framework command certified product categories with premium positioning in hospital procurement.
- Aerospace:Cockpit simulation and maintenance training applications prioritize reliability and viewing angle stability over cost minimization.
Retail absorbs the highest installation volumes; healthcare commands the steepest pricing tiers.
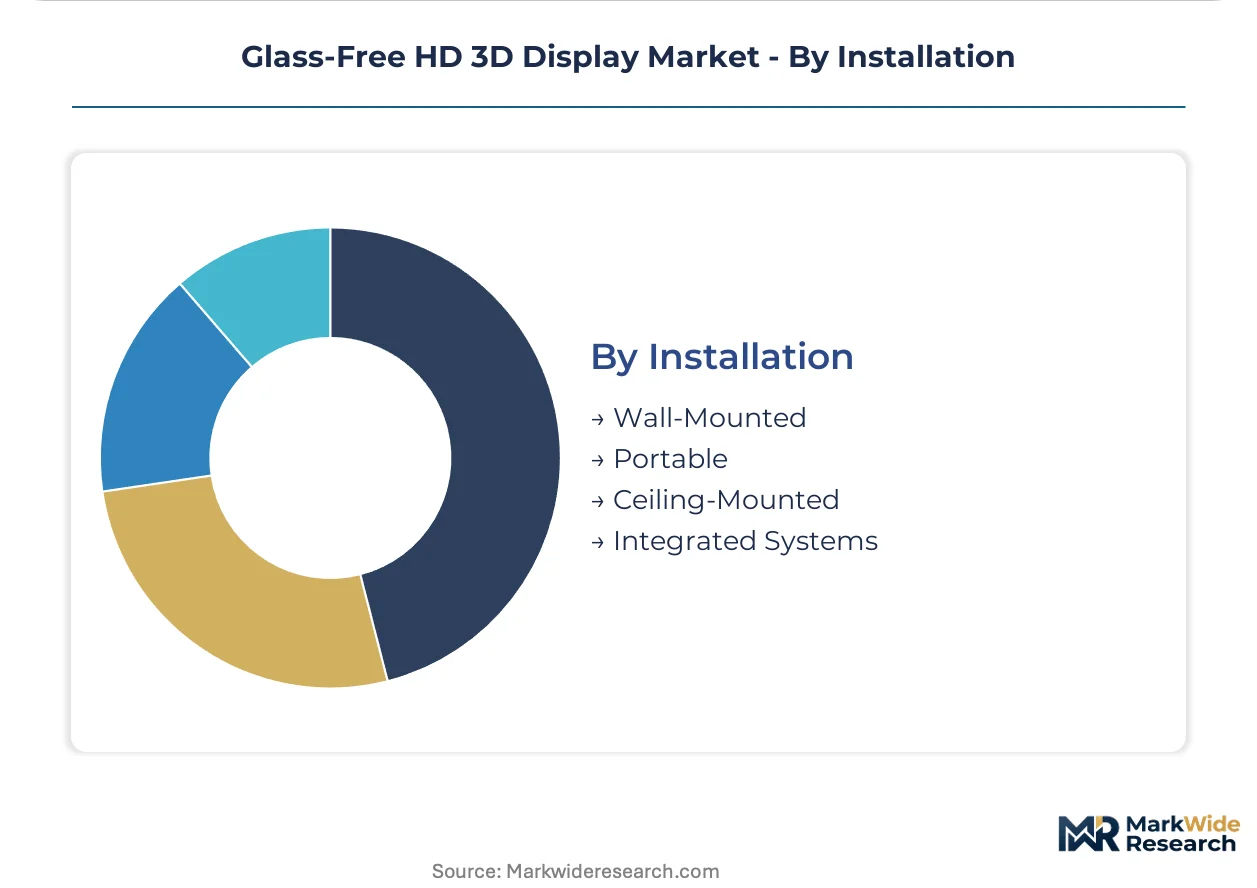
Installation:
Mounting configuration shapes structural requirements, thermal management, and service access design.
- Wall-Mounted:Fixed installations in commercial signage and healthcare corridors dominate current deployment, with standardized VESA mounting and concealed cable management.
- Integrated Systems:Custom architectural integration into retail fixtures and automotive showroom design requires coordinated mechanical, electrical, and content pipeline engineering.
- Portable:Battery-powered and wheeled units serve trade show exhibitions and temporary event installations with rapid deployment requirements.
- Ceiling-Mounted:Suspended configurations for museum exhibitions and atrium displays address floor space constraints in high-traffic public venues.
Wall-mounted configurations lead on installed base; integrated systems gain share fastest in luxury retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of autostereoscopic manufacturing capacity, while South Korea concentrates the most advanced light field R&D pipelines. Japan sustains niche dominance in holographic visualization systems for scientific applications. Germany and the United States anchor European and North American demand through medical imaging and experiential retail procurement.
China
MIIT's GB standards for electromagnetic compatibility and energy efficiency are tightening certification requirements for driver boards in integrated 3D systems. Domestic manufacturers in Shenzhen and Suzhou are redesigning power management circuits ahead of international competitors. The Yangtze River Delta panel cluster sustains cost advantages in high-resolution barrier-grid production for commercial digital signage networks.
South Korea
MFDS certification frameworks for surgical planning displays are creating premium product categories in hospital procurement. Seoul-based broadcast infrastructure investments are absorbing early production runs of plenoptic arrays as manufacturing yields improve. The capital region's semiconductor-to-display vertical integration enables rapid prototyping of OLED-based light field prototypes for cinema applications.
Japan
METI-funded research institutes concentrate specialized expertise in wavefront engineering and micro-lens design that constrains R&D scaling elsewhere. Osaka and Nagoya maintain leadership in holographic volumetric displays for defense simulation and scientific instrumentation. Domestic producers command fidelity premiums in photorefractive polymer systems where unit economics matter less than precision.
Germany
EU RoHS and Green Deal mandates are accelerating LED-based directional backlighting adoption over mercury-laden alternatives in digital signage procurement. Munich and Stuttgart automotive showrooms are negotiating multi-year experiential content subscriptions alongside autostereoscopic hardware deployment. The country's central bank and regional development agencies are co-financing display technology transfer programs.
United States
FCC equipment authorization rules govern electromagnetic emissions from integrated 3D display systems entering commercial distribution. Los Angeles and New York experiential marketing agencies are deploying large-format autostereoscopic installations for luxury cosmetics and entertainment brand activations. Medical visualization demand in Boston and Houston research hospitals is creating certified procurement channels for surgical planning displays.
Glass-Free HD 3D Display Market Competitive Landscape
East Asian producers anchor the manufacturing scale tier; European and North American specialists hold positions in holographic and software-defined rendering systems. The vendor base stratifies across three functional layers: integrated panel manufacturers with captive lens fabrication, pure-play optical component suppliers, and content-technology bundlers serving experiential retail networks. Samsung Electronics exemplifies the first archetype through semiconductor-to-display vertical control; Dimenco and Leia Inc. represent the third through hardware-content-service integration. Competitive dynamics center on manufacturing yield improvement in plenoptic arrays and exclusive content pipeline partnerships with flagship retail networks.
Among the integrated tier, Samsung Electronics and LG Electronics occupy positions defined by upstream control over backlight and lenticular lens supply. AUO Corporation represents the scale-driven manufacturing archetype with cost advantages in high-resolution barrier-grid panels. These three anchors demonstrate how East Asian fabrication clusters translate panel-making expertise into autostereoscopic product categories.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Philips |
| Alioscopy |
| Holografika |
| AUO Corporation |
| Dimenco |
| Leia Inc. |
| Evistek |
| Others |
Value Network & Pricing Analysis
Roll-to-roll lenticular manufacturing migration into Chinese and Japanese panel clusters compresses unit costs while concentrating procurement leverage among integrated display makers. This production-method transition simultaneously reshapes cost economics and supply concentration, as captive lens fabrication capabilities determine margin capture across the value chain.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for barrier-grid panels, forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on MFDS certification tier for medical applications and volume scale for digital signage networks. Pricing pressure stems from indium tin oxide supply volatility, squeezing margins in transparent electrode-dependent tiers. Retail signage buyers exhibit highest price sensitivity; healthcare procurement shows lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Refurbishment flows for lenticular lens sheets and driver board recovery are emerging in South Korean and Taiwanese service networks, extending component lifecycles. Geographic supply concentration centers on China, South Korea, and Japan for panel fabrication and optical engine assembly. Raw material dependencies include refined indium, photoresist polymers, and precision glass substrates. Single-source vulnerability in Chinese state-influenced indium processing creates structural risk. Distribution runs through integrated panel manufacturers with direct-to-OEM channels dominating downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass-free HD 3D display market functions as a geographic-arbitrage play, with South Korea's MFDS certification premiums commanding 40-60% pricing spreads over uncertified alternatives in neighboring manufacturing clusters.
For Market Incumbents: Lock in exclusive content pipeline partnerships with flagship retail networks in Shanghai, Tokyo, and Dubai before emerging entrants replicate bundled hardware-service models. Secure captive supply of lenticular lens arrays through backward integration into roll-to-roll fabrication, neutralizing AUO Corporation's scale advantages in barrier-grid production.
For New Entrants and Emerging Players: Enter via India's PLI scheme for display manufacturing, leveraging module assembly incentives to serve Middle Eastern and African markets with lower certification burdens. Target experiential retail networks in luxury automotive showrooms, where bundled content subscriptions reduce upfront hardware price sensitivity and extend customer lifetime value.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play optical component suppliers lacking integrated rendering software capabilities, as hardware-content convergence accelerates. Long-term viability favors acquisition targets with plenoptic array manufacturing yields above industry averages and exclusive partnerships with Seoul-based broadcast infrastructure deployers. Monitor MFDS certification approval timelines as inflection indicator for medical-grade premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Plenoptic Array Yield Improvement | Samsung Electronics and LG Electronics are investing in Seoul-based R&D to reduce manufacturing defects in light field displays. |
| MFDS Certification Pathway | Domestic South Korean manufacturers are redesigning surgical planning displays to capture premium hospital procurement tiers. |
| Content Pipeline Partnership | Dimenco and Leia Inc. are negotiating multi-year experiential content subscriptions with Dubai luxury retail networks. |
| Backward Integration into Lens Fabrication | Integrated panel makers are acquiring roll-to-roll lenticular manufacturing capabilities to control input costs. |
| Geographic Manufacturing Expansion | Module assembly investments under India's PLI scheme are targeting Middle Eastern and African distribution channels. |
Research Methodology
Direct dialogue with display panel procurement managers, optical engineering directors, broadcast infrastructure planners, and experiential marketing agency executives grounded qualitative findings. Secondary validation drew from MIIT GB standard filings, FCC equipment authorization databases, EU RoHS compliance registries, and SEC 10-K disclosures from listed display manufacturers. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across technology segments.
Segmentation outputs across the analysis window reflect modeling by product architecture, optical engine type, end-use specification, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating plenoptic array manufacturing yield trajectories and content ecosystem maturity indicators. Industry-specific forecast inputs included MFDS certification pipeline data and flagship retail network expansion schedules.
Inputs from hospital procurement databases and broadcast infrastructure deployment records were available through the study window; gaps in real-time rendering engine interoperability standards introduce uncertainty bands around content ecosystem growth assumptions. Forecasts reflect documented assumptions regarding indium supply stability and lenticular lens yield improvement rates. Practitioners should monitor MFDS certification backlog durations and PLI scheme disbursement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
E-Paper Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
OLED Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Display Mask Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
Rugged Display Market
Display Technologies
LCD Panel Market
Display Technologies
United States Microdisplay Market
Display Technologies
Flexible OLED Market
Display Technologies
Light Field Display Market
Display Technologies
Low Power Display Market