
 Fiber Optic Pressure Sensors Market | 2026-2036
Fiber Optic Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Pressure Sensors Market Foresight
Asset-light leasing models for downhole sensing equipment is fragmenting competitive dynamics in the Fiber Optic Pressure Sensors Market. Schlumberger Limited leverages its integrated well services platform to bundle sensor deployment with reservoir characterization contracts. Baker Hughes Company anchors its position through captive manufacturing of specialty fiber cable assemblies for high-pressure environments. Luna Innovations Incorporated differentiates via R&D intensity in signal processing algorithms that extend sensor lifecycles in corrosive media.
Fiber optic pressure sensors translate mechanical pressure into optical signal variation using Fabry-Pérot interferometry or fiber Bragg grating architectures, achieving measurement stability across temperature excursions exceeding 300°C without electromagnetic susceptibility. These devices primarily serve industries where intrinsic safety, spark-free operation, or extreme thermal cycling renders conventional piezoelectric or capacitive transducers unreliable. The Point sensor category dominates current revenue as single-location downhole and catheter-tip applications sustain established procurement patterns, while Distributed configurations represent the fastest-expanding segment as pipeline operators adopt continuous pressure-temperature profiling along tens of kilometers of infrastructure. Interferometric technology leads in precision-critical aerospace and medical segments, whereas FBG platforms capture share in industrial automation where multiplexing multiple sensors on a single fiber reduces installation complexity.
The US Department of Transportation's pipeline safety regulations and the FAA's airworthiness directives for fuel and hydraulic systems shape certification requirements that favor optical isolation in hazardous environments. Europe's ATEX directives and IECEx equipment certification schemes create parallel compliance pathways that sensor manufacturers must navigate for market access across industrial automation and oilfield services. Stakeholders should monitor evolving interoperability standards between fiber sensing networks and digital twin platforms, as this interface determines which suppliers capture recurring software and analytics revenue beyond hardware deployment.
Market Dynamics
The Fiber Optic Pressure Sensors Market is experiencing structural pressure from the substitution of electrical transducers in hazardous environments, where intrinsic safety mandates and extreme thermal cycling requirements favor optical isolation over conventional piezoelectric alternatives.
Growth Catalysts
- FAA Airworthiness Directives:Fuel and hydraulic system certification requirements for commercial aviation are mandating spark-free sensing architectures, creating pull-through demand for interferometric pressure transducers in next-generation aircraft programs.
- Shale field downhole monitoring:Permian Basin operators are deploying point sensors at depths exceeding 300°C where electronic alternatives fail, sustaining procurement volumes for Fabry-Pérot architectures in directional drilling applications.
- Multiplexing fiber Bragg grating platforms:Industrial automation buyers are reducing installation complexity by daisy-chaining multiple pressure measurement points on single fiber runs, lowering per-sensor infrastructure costs in process manufacturing.
Market Restraints
- Specialty fiber cable supply concentration:High-pressure hermetic cable assemblies rely on a limited supplier base concentrated in North American and European manufacturing clusters, creating vulnerability to capacity constraints.
- Signal processing unit cost structure:Interrogator hardware and wavelength-division demodulation electronics carry premium pricing relative to conventional 4-20mA transmitters, compressing adoption in cost-sensitive industrial segments.
- ATEX/IECEx certification timeline friction:Hazardous area equipment approval processes extend product launch cycles by 12-18 months, delaying revenue recognition for manufacturers targeting European oilfield and chemical processing markets.
Strategic Opportunities
- India industrial automation penetration:Process manufacturing facilities under the country's PLI scheme are modernizing sensing infrastructure, creating first-mover advantage for fiber optic suppliers establishing local calibration and service capabilities.
- Digital twin integration:Pipeline operators are demanding real-time pressure-temperature profiling data streams compatible with asset simulation platforms, opening recurring software and analytics revenue beyond hardware deployment.
- Medical catheter miniaturization:Interventional cardiology device manufacturers are specifying sub-millimeter fiber sensors for intravascular pressure measurement, expanding addressable market into high-margin disposable medical applications.
Industry Challenges
- Photonics-hydraulics cross-functional talent scarcity:Field deployment of downhole sensors requires engineers conversant in both optical signal integrity and high-pressure wellbore mechanics, with limited training pipeline producing qualified personnel.
- Legacy SCADA integration complexity:Brownfield industrial facilities operate proprietary communication protocols that resist seamless incorporation of optical sensing networks, forcing costly gateway development or parallel monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Pressure Sensors Market |
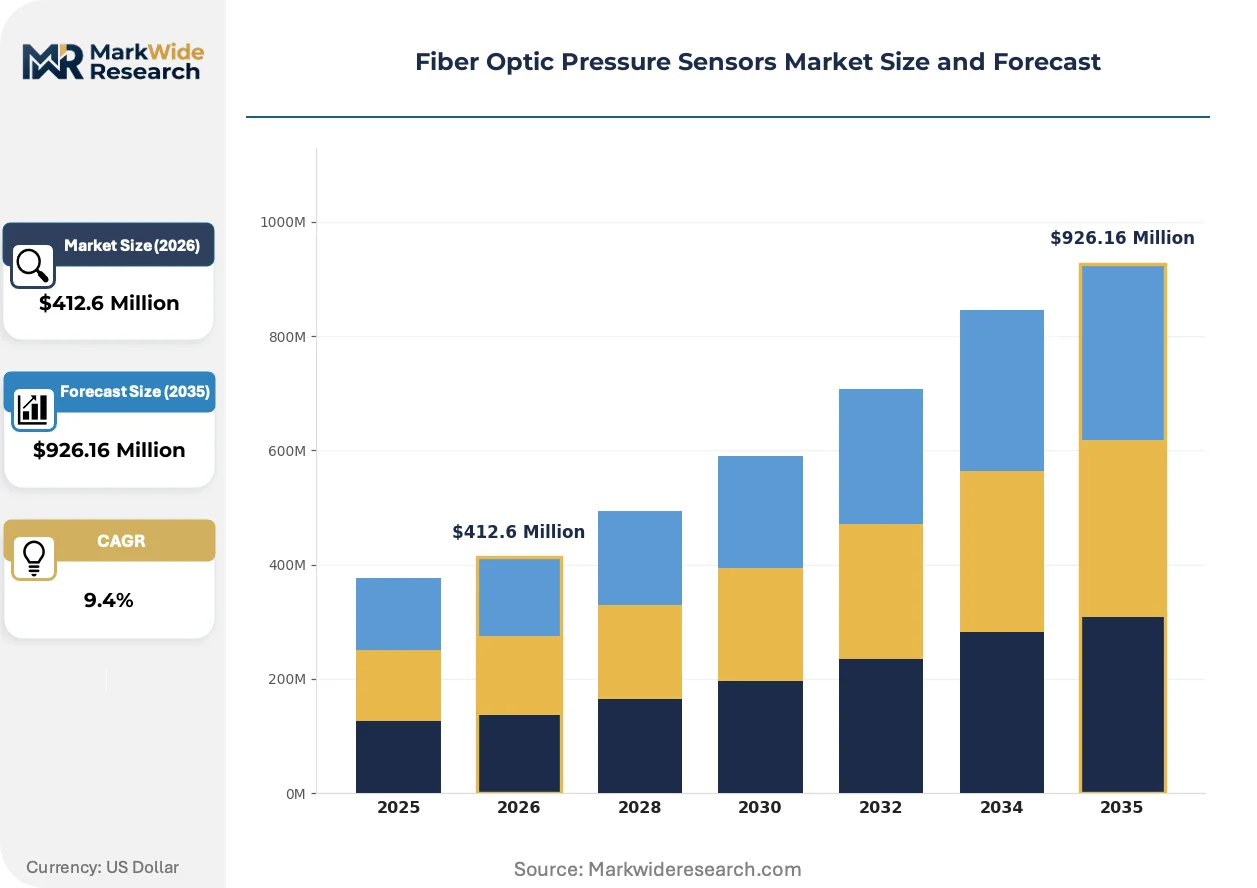
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $926.16 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point, Multipoint, Distributed, Fiber Bragg Grating Technology: Interferometric, FBG, Extrinsic, Electro-Optic Application: Aerospace, Industrial Automation, Medical Devices, Oil & Gas End User: Utilities, Manufacturing, Healthcare, Defense |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Luna Innovations Incorporated, Opsens Inc., AP Sensing GmbH, Honeywell International Inc., Sumitomo Electric Industries Ltd., Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Pressure Sensors Market Shifts & Advancements
Signal processing architectures and interrogation hardware are undergoing rapid evolution as manufacturers compete to extend sensor lifecycles in corrosive media while reducing total cost of ownership for distributed sensing networks.
Fabry-Pérot interferometry is migrating from discrete point measurement applications toward quasi-distributed configurations that combine high precision with limited spatial resolution. Aerospace primes are piloting these hybrid architectures for fuel tank ullage pressure monitoring where single-fiber multiplexing reduces wiring weight. The technology is migrating from laboratory-grade instruments to field-hardened platforms certified for 20-year operational life in subsea production systems.
Europe's CSRD sustainability disclosure requirements are compelling industrial asset operators to document fugitive emission reductions and energy efficiency improvements traceable to pressure monitoring infrastructure. This regulatory pressure is accelerating replacement of pneumatic gauge networks with fiber optic alternatives that eliminate methane venting from instrument air systems. Process manufacturers in Germany and the Netherlands are responding by bundling sensor procurement with carbon accounting software subscriptions.
Buyers in the United States shale patch are unbundling after-sales service contracts from initial hardware procurement, treating calibration and fiber replacement as separate spend categories managed through third-party oilfield service firms. This behavioral shift is compressing manufacturer margins on installation and maintenance while opening channel partnerships with established well intervention providers. The pattern is most visible in the Permian and Eagle Ford formations where operator procurement teams have centralized sensing equipment vendor management.
Fiber Optic Pressure Sensors Market Segmentation
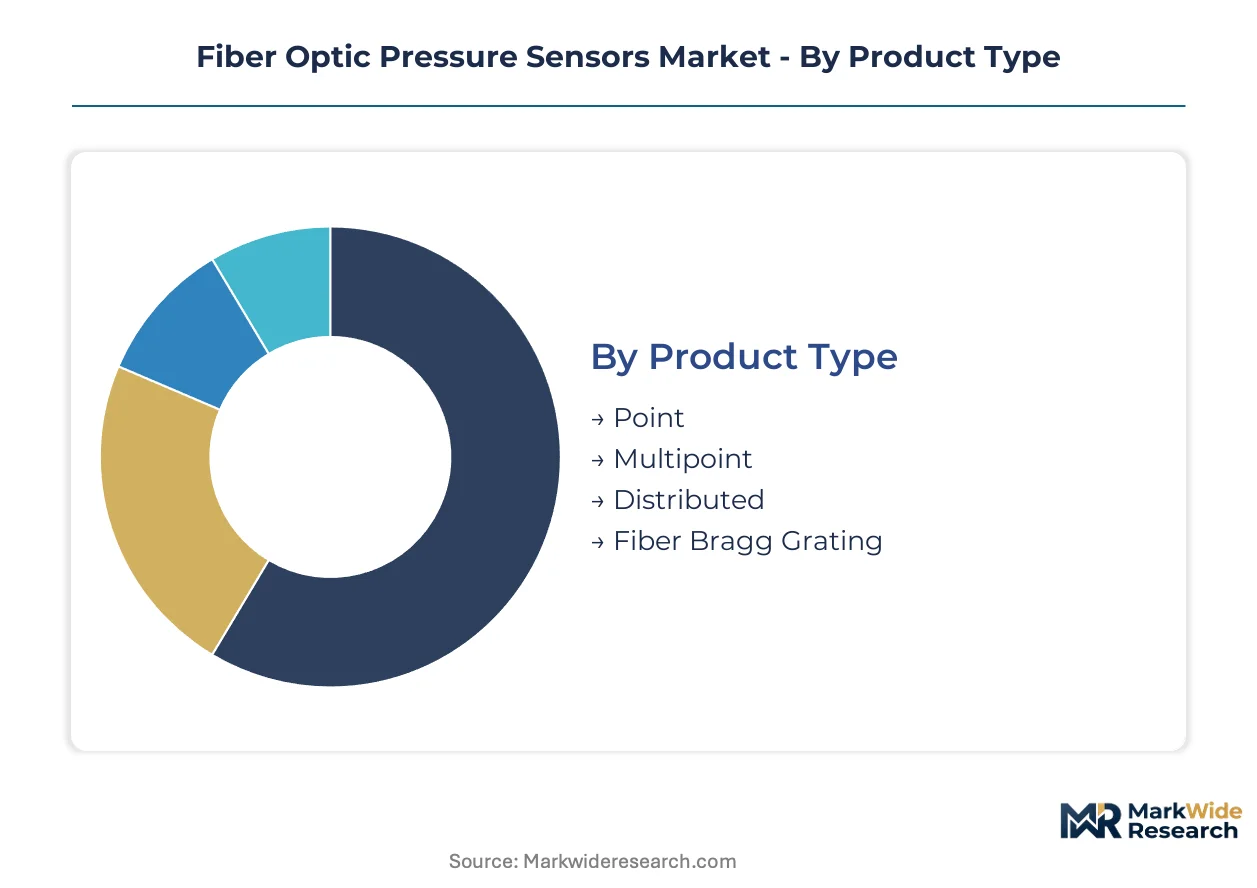
Segmentation in fiber optic pressure sensors reveals distinct procurement cycles across product architectures and end-use environments. Point sensors in oilfield service turn over every 3-5 years under thermal cycling stress, while distributed sensing networks in pipeline infrastructure operate on 15-20 year depreciation schedules.
Product Type:
Replacement velocity varies dramatically across form factors, with disposable medical point sensors cycling fastest and subsea distributed installations representing capital assets.
- Point:Single-location transducers employing Fabry-Pérot cavities deliver precision measurement at discrete wellbore depths or catheter tips. Permian Basin operators specify these for directional drilling applications where temperatures exceed electronic transducer limits, driving recurring replacement demand through thermal degradation.
- Multipoint:Arrays of discrete sensing elements along a single fiber enable pressure profiling across multiple formation zones. North American shale operators deploy these in multistage hydraulic fracturing to optimize cluster efficiency, creating bundled procurement with perforating services.
- Distributed:Continuous pressure-temperature monitoring along tens of kilometers of fiber supports pipeline leak detection and flow assurance. Installation complexity and interrogator capital costs limit adoption to major trunk lines.
- Fiber Bragg Grating:Wavelength-encoded gratings enable multiplexed measurement with passive, all-fiber construction. Aerospace fuel system integrators favor these for electromagnetic immunity in composite airframe applications.
Point sensors anchor the volume base while distributed configurations gain share at the steepest rate.
Technology:
Cost structure separates precision-critical applications from price-sensitive industrial automation, with interferometric platforms commanding premium positioning.
- Interferometric:Fabry-Pérot architectures achieve sub-0.1% full-scale accuracy through optical cavity length modulation. FAA-certified implementations in commercial aviation fuel systems require hermetic sealing and 20-year calibration stability.
- FBG:Fiber Bragg grating platforms enable wavelength-division multiplexing of dozens of sensors on single fiber runs. German process manufacturers adopt these for ATEX-compliant pressure monitoring in chemical reactors.
- Extrinsic:Hybrid designs coupling optical fibers to external diaphragm structures simplify manufacturing but sacrifice thermal stability.
- Electro-Optic:Pockels-effect transducers modulate optical properties under electric field stress, finding niche use in high-voltage transformer monitoring.
Interferometric technology dominates aerospace and medical margins while FBG platforms expand most quickly through industrial multiplexing economics.
Application:
Regulatory certification requirements create divergent time-to-market pathways, with aviation and medical segments demanding longest validation cycles.
- Aerospace:Fuel tank ullage and hydraulic system monitoring in next-generation aircraft programs. FAA airworthiness directives mandate spark-free architectures, locking in optical solutions for new platform development.
- Industrial Automation:Process pressure monitoring in chemical, pharmaceutical, and food manufacturing. European CSRD disclosure requirements accelerate replacement of pneumatic gauge networks to eliminate methane venting.
- Medical Devices:Intravascular pressure measurement in interventional cardiology catheters. Sub-millimeter form factors and disposable economics favor fiber optic miniaturization over MEMS alternatives.
- Oil & Gas:Downhole reservoir monitoring and subsea production system pressure sensing. Extreme temperature and pressure environments exclude electronic alternatives beyond 300°C.
Oil and gas procurement anchors manufacturer revenue while medical applications expand fastest through catheter miniaturization demand.
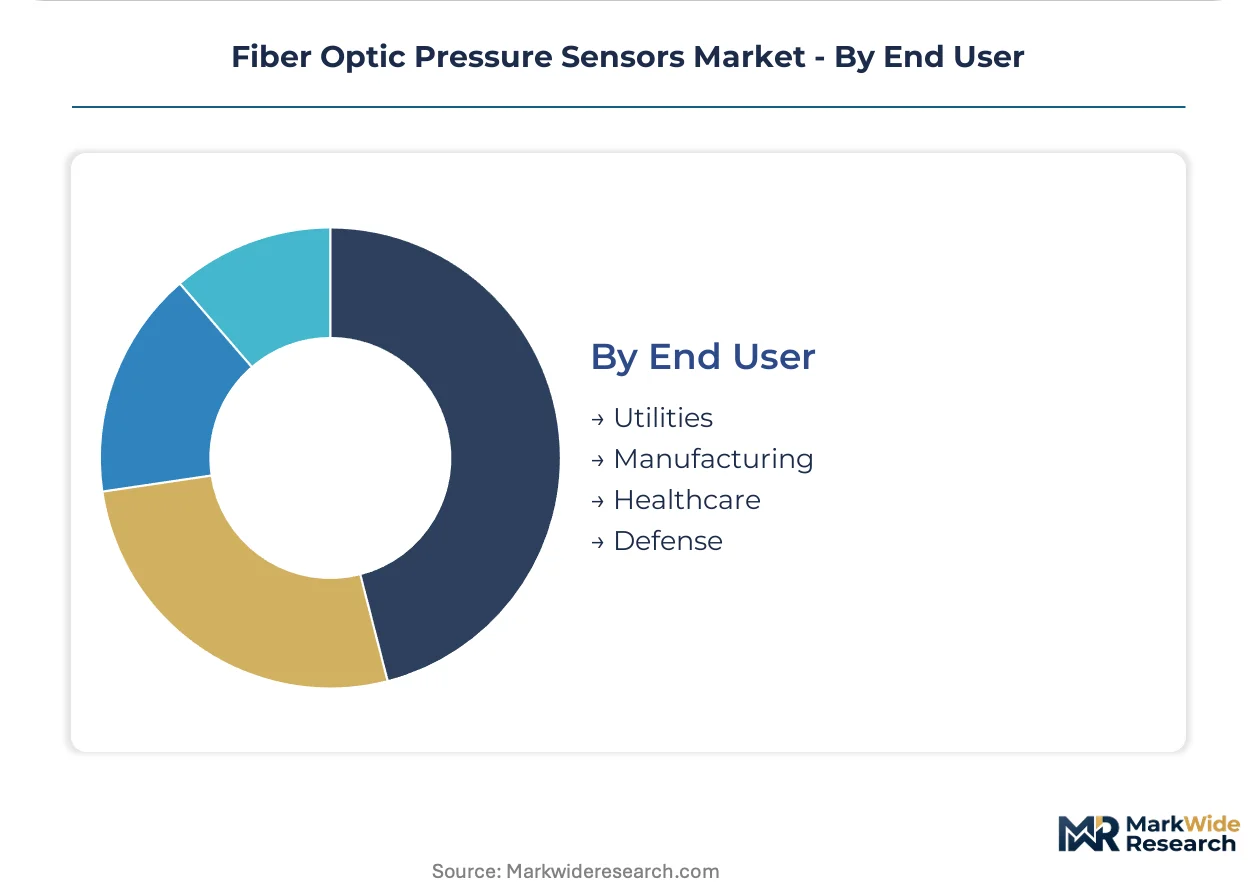
End User:
Capital intensity and technical sophistication of buyer organizations shape contract structures and service attachment rates.
- Utilities:Pipeline operators and electrical grid managers deploy distributed sensing for asset integrity monitoring. Unbundling of hardware procurement from analytics subscriptions is compressing equipment margins.
- Manufacturing:Process industry facilities under India's PLI scheme modernize sensing infrastructure, creating demand for local calibration capabilities.
- Healthcare:Medical device OEMs and hospital systems specify disposable fiber sensors for minimally invasive procedures. Procurement concentrates with interventional cardiology specialists.
- Defense:Military aerospace and submarine programs require ITAR-compliant supply chains with extended operational life certification.
Manufacturing sector procurement anchors volume throughput while healthcare applications command the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented sensor manufacturing clusters in Germany and Japan supply interrogator hardware to North American shale operators, while import dependence for specialty hermetic cable assemblies constrains capacity expansion in emerging markets. Trade flows concentrate on high-precision interferometric platforms from aerospace-certified facilities.
United States
Permian Basin directional drilling sustains procurement volumes for Fabry-Pérot point sensors rated beyond 300°C. FAA airworthiness directives for commercial aviation fuel systems mandate spark-free architectures, locking optical solutions into next-generation aircraft programs. Houston hosts the dominant concentration of oilfield service procurement teams that have unbundled sensing equipment from integrated service contracts.
Germany
Process manufacturers in the chemical corridor along the Rhine replace pneumatic gauge networks to eliminate methane venting under CSRD disclosure requirements. ATEX certification timelines extend product launches by 12-18 months for hazardous area equipment. The Eindhoven-to-Munich photonics corridor anchors FBG multiplexing platform development for industrial automation.
China
Dual carbon goals accelerate pipeline integrity monitoring deployments along west-east gas transmission trunk lines. MIIT standards for smart manufacturing infrastructure create specification pull-through for distributed pressure-temperature profiling. The Yangtze River Delta concentration of subsea equipment fabricators sources interrogator electronics from domestic semiconductor foundries.
India
PLI scheme incentives for process manufacturing modernization drive first-mover advantage for suppliers establishing local calibration capabilities. CEA regulations for electrical grid asset monitoring specify optical isolation in high-voltage substations. Gujarat's petrochemical corridor concentrates demand for ATEX-compliant pressure monitoring in reactor vessels.
Japan
METI funding for hydrogen infrastructure safety systems specifies fiber optic pressure monitoring in high-pressure storage and dispensing equipment. Precision manufacturing clusters in Nagoya supply miniaturized FBG sensors for interventional cardiology catheter OEMs. Domestic aerospace primes integrate interferometric transducers into next-generation regional jet fuel systems.
Fiber Optic Pressure Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in specialty fiber cable and signal processing subsystems. The vendor base organizes around three archetypes: diversified energy service conglomerates bundling sensors with reservoir characterization contracts; captive cable manufacturers controlling hermetic assembly supply; and precision photonics firms differentiating through interrogator algorithm development. Competitive dynamics center on backward integration into specialty fiber production and forward integration into digital twin analytics subscriptions.
Among North American energy service providers, Schlumberger Limited and Halliburton Company exemplify the integrated platform model, anchoring market presence through bundled well services rather than standalone sensor sales. Baker Hughes Company occupies a distinctive position through captive manufacturing of high-pressure cable assemblies. Luna Innovations Incorporated represents the precision photonics archetype, with R&D intensity in signal processing algorithms extending sensor operational life. These three patterns illustrate how competitive advantage distributes across the value chain.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Luna Innovations Incorporated |
| Opsens Inc. |
| AP Sensing GmbH |
| Honeywell International Inc. |
| Sumitomo Electric Industries Ltd. |
| Yokogawa Electric Corporation |
| Others |
Supply & Pricing Matrix
The Houston-to-Rotterdam freight corridor carries specialty hermetic cable assemblies and interrogator hardware at rates that compress margins for distributed sensing network deployments, concentrating pricing power with North American and European cable manufacturers while forcing downstream tiering between aerospace-certified precision platforms and industrial automation-grade alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FAA-certified interferometric transducers commanding substantial premiums over FBG multiplexing platforms adopted by German process manufacturers. Price differentiation hinges on ATEX/IECEx certification grade and volume scale, with single-unit medical catheter sensors priced far above pipeline-multipoint volumes. Cost compression in the standard tier is intensifying because Indian PLI scheme entrants are localizing calibration capabilities. Healthcare device OEMs exhibit the lowest price sensitivity due to disposable economics, while utilities procurement teams drive hardest bargaining through unbundled service contracts.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize supplier-finance arrangements for high-pressure hermetic cable assemblies, reflecting working capital pressure across the tier. Geographic supply concentration centers on Germany, Japan, and the United States for precision interrogator hardware, with specialty fiber drawing and cable termination captive to North American and European manufacturing clusters. Raw material dependencies include germanium-doped silica preforms, hermetic sealing alloys, and wavelength-stabilized laser diodes. Single-source vulnerability around Fabry-Pérot cavity fabrication creates procurement risk for aerospace-qualified sensors. Distribution runs through oilfield service integrators bundling deployment with reservoir characterization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against MEMS pressure transducers advancing thermal tolerance through silicon carbide architectures, threatening fiber optic incumbents in sub-300°C industrial segments.
For Market Incumbents: Insulate core aerospace and downhole positions through backward integration into specialty fiber preform manufacturing, eliminating dependency on external hermetic cable suppliers. Lock in channel control by acquiring calibration service capabilities in the Permian Basin and Gujarat petrochemical corridor, defending against unbundling trends that compress installation margins. For New Entrants and Emerging Players: Establish a beachhead in India's process manufacturing modernization wave under PLI scheme incentives, where local calibration capabilities remain scarce and first-mover advantage is achievable. Target medical catheter miniaturization as the most penetrable segment, leveraging Nagoya precision manufacturing partnerships to supply sub-millimeter FBG sensors for interventional cardiology OEMs. For Investors and Strategic Acquirers: Precision photonics firms with proprietary interrogator algorithms present the most attractive acquisition profile, particularly those extending sensor lifecycles in corrosive media through signal processing IP. Long-term viability hinges on digital twin integration capabilities that capture recurring software revenue beyond hardware deployment. Watch for FAA certification completion timelines on next-generation regional jet programs as inflection indicators for aerospace segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Production | Captive supply of hermetic cable assemblies eliminates single-source vulnerability for downhole deployments. |
| Digital Twin Platform Integration | Pipeline operators in the Permian Basin demand real-time pressure-temperature data streams compatible with asset simulation software. |
| Local Calibration Capability Buildout | Indian PLI scheme process manufacturers require domestic service infrastructure to avoid ATEX certification timeline friction. |
| Medical Catheter Sensor Miniaturization | Interventional cardiology device OEMs specify sub-millimeter form factors for intravascular pressure measurement applications. |
| Interrogator Algorithm R&D Intensity | Signal processing IP extending sensor lifecycles in corrosive media differentiates precision photonics suppliers from commodity hardware vendors. |
Research Methodology
Operator-level perspectives from reservoir engineers at shale field operators, biomedical engineers at interventional cardiology device OEMs, procurement directors at pipeline utilities, and photonics R&D leads at precision sensor manufacturers anchored the qualitative base. Primary interview insights triangulated against FAA airworthiness directive filings, ATEX/IECEx certification databases, SEC 10-K equipment disclosures from oilfield service providers, and customs trade data for specialty fiber cable assemblies. Bottom-up demand modeling across end-use segments reconciled with top-down macroeconomic indicators.
Scenario-bracketing around regulatory timeline variations and technology substitution curves framed the analytical approach across the projection horizon. Segmentation dimensions modeled include sensor architecture (point, multipoint, distributed), technology platform (interferometric, FBG, extrinsic), application vertical (aerospace, oil and gas, medical, industrial automation), and end-user capital intensity. CAGRs derived from unit shipment trajectories and average selling price evolution, with specific inputs from shale field well completion counts and commercial aircraft platform development schedules.
Sensitivities concentrate around FAA certification acceleration or delay for fuel system applications, MIIT smart manufacturing infrastructure spending trajectories in China, and MEMS transducer thermal tolerance breakthroughs. Forecasts reflect documented assumptions regarding substitution elasticities and regulatory compliance cost structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market