
 Global Proximity and Displacement Sensors Market | 2026-2036
Global Proximity and Displacement Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proximity and Displacement Sensors Market Intelligence
Compliance with IECEx and ATEX standards for equipment used in hazardous environments is bifurcating the supplier landscape. Rockwell Automation leverages its extensive industrial automation ecosystem to integrate these certified sensors. OMRON Corporation specializes in high-precision optical and photoelectric sensors for factory automation lines. KEYENCE CORPORATION differentiates through its direct sales model and advanced sensor technology development.
Proximity and displacement sensors are devices that detect the presence or absence of an object, or measure its movement, without physical contact. These sensors operate using principles like eddy currents, which can achieve sub-micron resolution for precise positioning in machine tools. Inductive sensors remain a high-volume, mature segment for standard machine automation. In contrast, demand for ultrasonic sensors is expanding in material handling and robotics applications where target material composition varies.
Manufacturers must navigate a complex web of regional requirements, including CE marking in Europe for safety and electromagnetic compatibility. In China, GB standards dictate product compliance, while in the United States, FCC regulations govern radio frequency interference from sensor electronics. Future supplier success hinges on developing sensors that meet both stringent performance metrics and divergent international certification pathways.
Market Dynamics
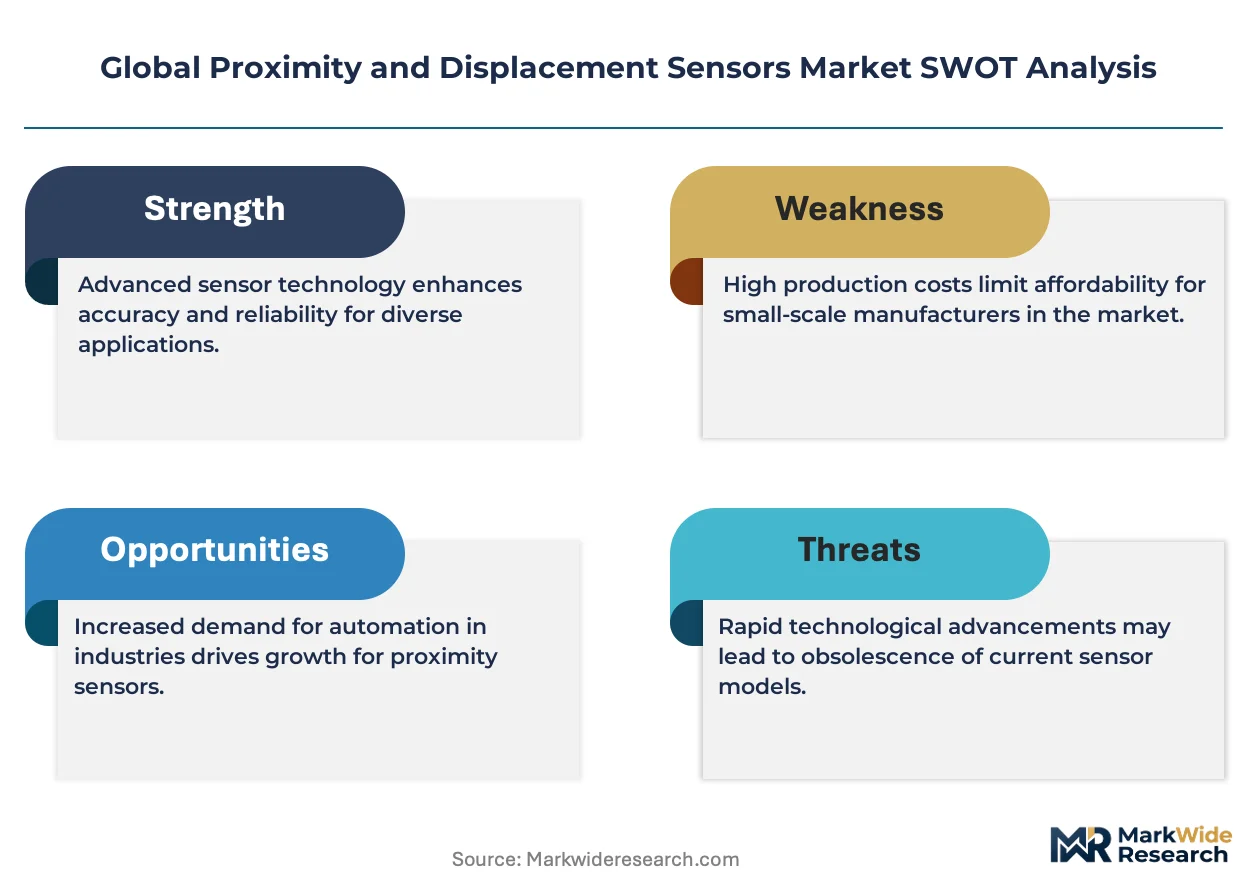
The imperative to meet divergent international standards for hazardous environments is the central force bifurcating the supplier landscape. Compliance with frameworks like ATEX and IECEx creates a distinct, high-value market tier separate from standard industrial-grade sensors.
Growth Catalysts
- IIoT Integration:The incorporation of sensors into Industrial Internet of Things platforms, particularly within Germany's advanced manufacturing clusters, accelerates demand for connected devices that provide real-time positioning and status data for predictive maintenance and process optimization.
- Robotics Expansion:Demand from robotics and automated material handling for ultrasonic sensors is increasing, as these devices can reliably detect targets with varying material compositions, colors, and surface finishes, which is critical for dynamic warehouse environments.
- Precision Manufacturing:The push for sub-micron resolution in machine tools and semiconductor fabrication equipment fuels development of high-performance eddy current and optical sensors, enabling tighter manufacturing tolerances and improved quality control.
Market Restraints
- Technical Trade-offs:Inductive sensors, while mature and cost-effective for standard automation, face inherent limitations in detection range and are susceptible to interference from surrounding metals, restricting their use in more complex or space-constrained machinery designs.
- Cost of Miniaturization:Developing smaller, more powerful sensors with high-resolution capabilities requires significant R&D investment in new materials and microfabrication techniques, presenting a cost barrier for entry into premium application segments like medical devices.
- Substitution from Vision Systems:In certain sorting and inspection applications, lower-cost 2D vision systems are emerging as a viable substitute for arrays of discrete proximity sensors, offering more contextual data, albeit with higher processing overhead.
Strategic Opportunities
- Emerging Automotive Applications:Beyond parking assistance, opportunities are expanding for ultrasonic and inductive sensors in vehicle systems for detecting blind spots, monitoring suspension travel, and ensuring precise alignment of components like charging connectors on electric vehicles.
- Non-Industrial Verticals:Significant white space exists in non-industrial applications, including smart agriculture for monitoring crop height and water levels, and in building automation for occupancy detection that is more reliable than passive infrared technology.
- Sensor Fusion Development:Combining data from different sensor types, such as inductive and optical, through software can create more robust and fault-tolerant detection systems, opening opportunities for value-added solutions that command higher margins.
Industry Challenges
- Certification Bottlenecks:Navigating the complex and time-consuming web of regional certifications, such as CE marking in Europe, GB standards in China, and FCC rules in the United States, creates significant overhead and delays product launches.
- Legacy System Integration:Integrating modern, data-rich sensors into existing factory floors with older PLCs and control architectures presents a significant technical challenge, often requiring custom interfaces or middleware that adds cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proximity and Displacement Sensors Market |
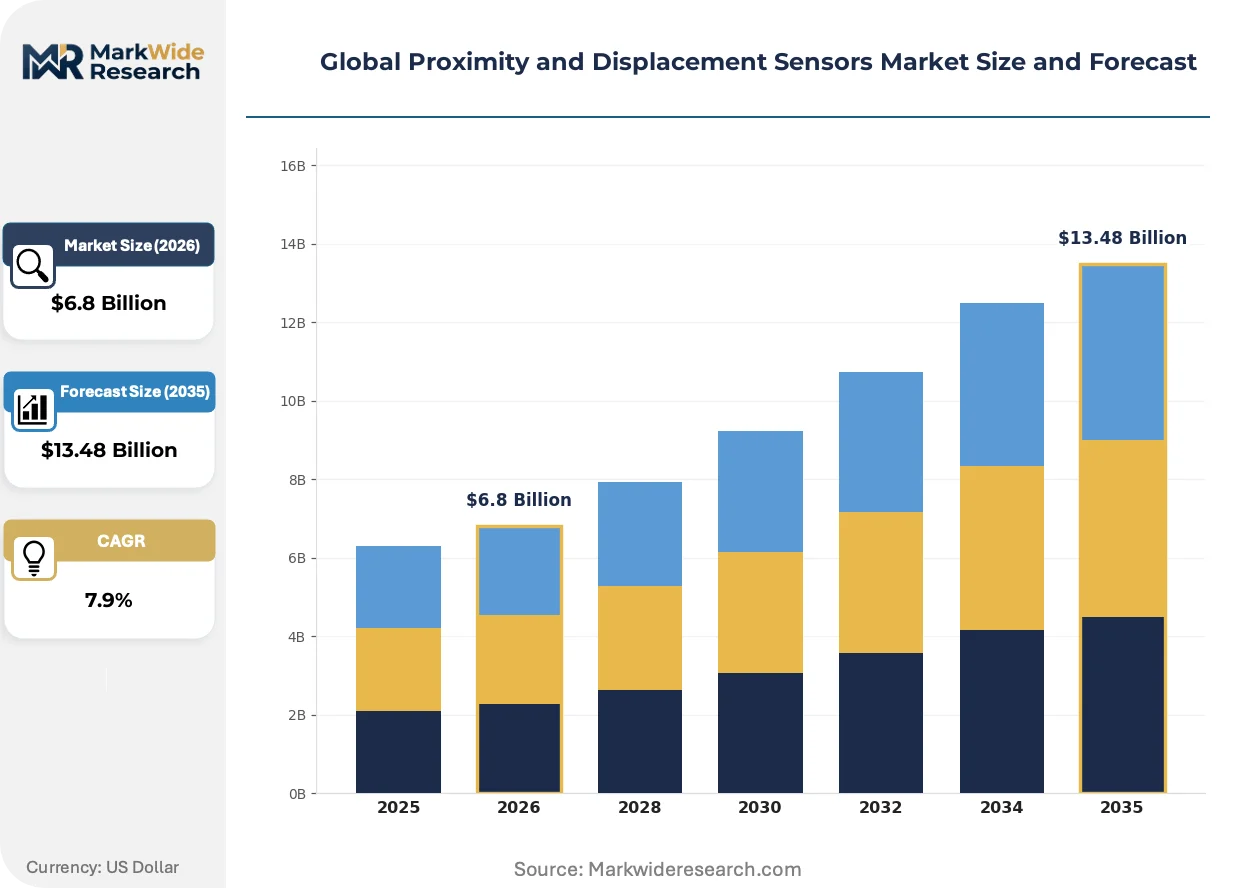
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Inductive, Ultrasonic, Optical, Magnetic, Photoelectric Technology: Laser, Infrared, Eddy Current, Hall Effect, Fiber Optic, Piezoelectric Application: Machine Automation, Robotics, Packaging Lines, Material Handling, Aerospace Systems, Consumer Electronics End User: Manufacturing Plants, Heavy Equipment Firms, Quality Control Labs, Transportation Operators, Energy Providers, Telecommunication Companies |
| Companies Covered | OMRON Corporation, Rockwell Automation, Panasonic Corporation, Hans Turck GmbH & Co. KG, Balluff GmbH, Schneider Electric SE, KEYENCE CORPORATION, ifm electronic gmbh, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proximity and Displacement Sensors Market Strategic Shifts & Innovations
Sensor design is evolving toward greater intelligence and application-specificity. This shift is driven by the dual pressures of achieving higher performance metrics for automation and complying with an increasingly fragmented global regulatory environment for safety and electronics.
Advanced photoelectric sensor technology, utilizing focused laser beams, provides high-speed, non-contact detection essential for modern factory automation. The electronics assembly and pharmaceutical packaging sectors are adopting these sensors for precise small-part verification. This technology is displacing traditional mechanical limit switches and lower-resolution inductive sensors in high-throughput production lines where speed and accuracy are critical.
Compliance with IECEx and ATEX standards for equipment used in explosive atmospheres is reshaping product development for the process industries. This forces manufacturers to engineer and certify specific product lines for oil and gas, chemical, and mining applications. The industrial automation segment is most affected, with suppliers creating distinct portfolios for hazardous-duty sensors that command a price premium.
A shift toward direct-to-engineer sales and support models is gaining traction for highly specialized sensor technologies. This approach bypasses traditional industrial distributors, enabling deeper technical consultation and collaborative problem-solving during the design phase. This trend is most prominent in technically demanding sectors like semiconductor equipment manufacturing and medical device engineering, where off-the-shelf solutions are insufficient.
Global Proximity and Displacement Sensors Market Segmentation
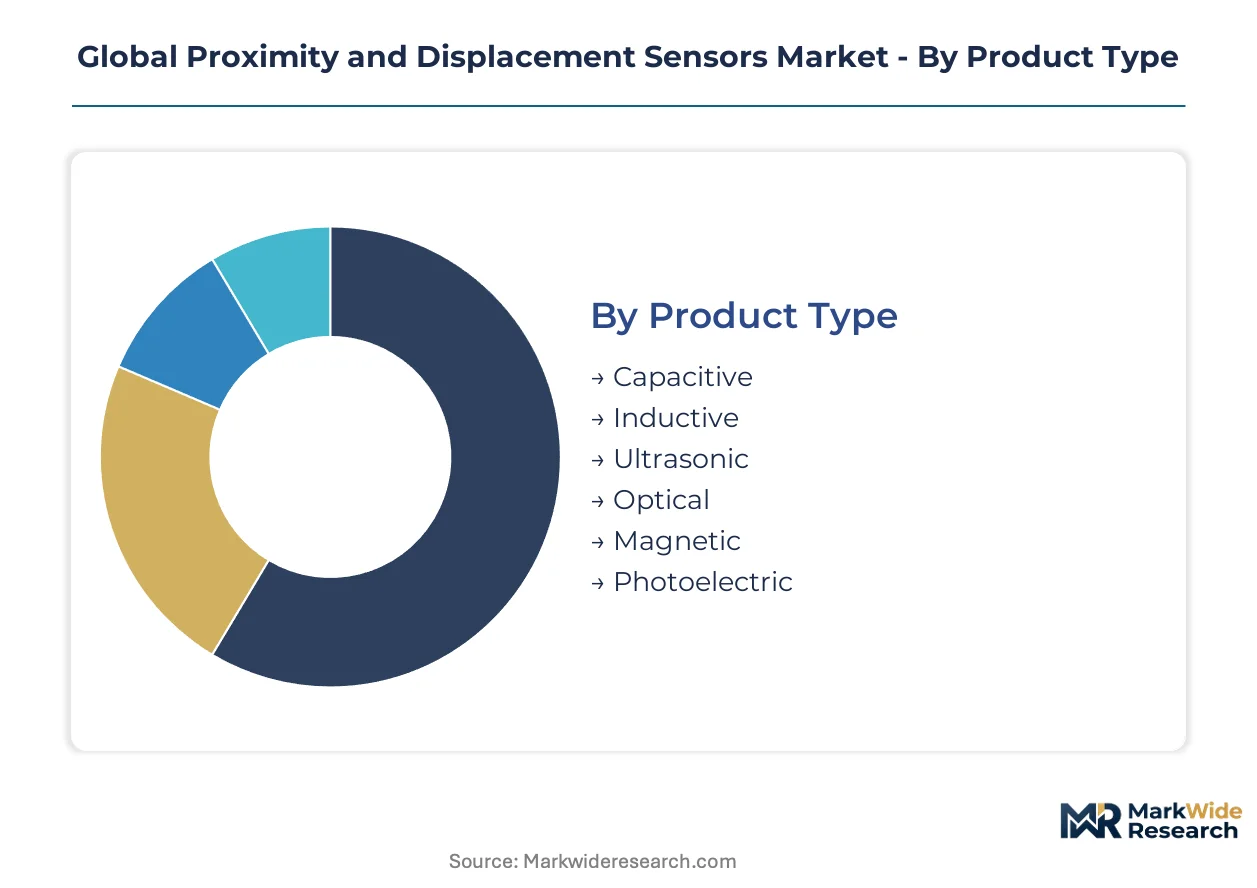
The Global Proximity and Displacement Sensors Market exhibits diverse segmentation across product types, underlying technologies, primary applications, and end-user industries. Understanding these distinct segments is crucial for manufacturers to tailor product development, pricing strategies, and distribution channels to specific market needs and regulatory landscapes.
Product Type:
Margin pools for proximity and displacement sensors often concentrate in specialized product types offering advanced capabilities or hazardous environment compliance.
- Inductive:These sensors detect metallic objects without contact through an electromagnetic field, representing a mature, high-volume segment for standard machine automation tasks across manufacturing plants.
- Optical:Utilizing light for detection, these sensors offer high precision and speed, with strong demand from electronics assembly and pharmaceutical packaging sectors for precise small-part verification and quality control.
- Capacitive:Capacitive sensors detect both metallic and non-metallic objects, finding use in level sensing for liquids and bulk materials within process industries.
- Ultrasonic:These sensors emit sound waves to detect objects, expanding in material handling and robotics applications where target material composition varies significantly.
- Magnetic:Magnetic sensors detect magnetic fields or ferromagnetic materials, commonly employed in position sensing for cylinders and door contacts.
- Photoelectric:Photoelectric sensors use a light emitter and receiver to detect objects, offering versatile detection methods for general factory automation lines.
The dominant share belongs to Inductive sensors, while Optical sensors are closing the gap fastest.
Technology:
Different sensor technologies are engineered for specific application demands, influencing their market penetration and growth trajectories.
- Eddy Current:This technology achieves sub-micron resolution for precise positioning by detecting changes in eddy currents, essential for machine tools and semiconductor fabrication equipment in Germany and Japan.
- Laser:Laser technology provides highly focused beams for high-speed, non-contact detection over longer distances, critical for advanced factory automation and precision measurement in electronics manufacturing.
- Infrared:Infrared sensors detect heat signatures or reflections, commonly used for presence detection and short-range object sensing in consumer electronics and building automation.
- Hall Effect:Hall Effect sensors measure the strength and direction of magnetic fields, frequently integrated into automotive applications for wheel speed detection and engine timing.
- Fiber Optic:Fiber optic sensors transmit light through optical fibers for detection, suitable for harsh environments or applications requiring intrinsic safety, such as in chemical processing.
- Piezoelectric:Piezoelectric sensors generate an electrical charge in response to mechanical stress, often used for vibration monitoring and force sensing in heavy equipment firms.
Volume concentration is highest in Eddy Current technology for precision applications, with Laser technology gaining significant traction in high-speed automation.
Application:
Specific applications drive sensor demand based on required performance metrics, environmental conditions, and integration needs.
- Machine Automation:This segment involves integrating sensors into industrial machinery for real-time positioning, status data, and predictive maintenance, particularly within Germany's advanced manufacturing clusters.
- Robotics:Sensors are crucial for robotic navigation, object detection, and manipulation, with demand expanding for ultrasonic sensors in automated material handling and dynamic warehouse environments.
- Packaging Lines:Sensors ensure precise product handling, counting, and quality inspection, using advanced photoelectric sensors for high-throughput production lines.
- Material Handling:This application includes conveyor systems and automated guided vehicles, relying on sensors for object detection, collision avoidance, and inventory management.
- Aerospace Systems:Sensors provide critical data for flight control, engine monitoring, and structural health, requiring robust and highly reliable components.
- Consumer Electronics:Proximity sensors enable features like automatic screen dimming and touchless gestures in smartphones and other personal devices.
The maturity level of sensor integration is highest in Machine Automation, while Robotics is experiencing the most rapid expansion in sensor deployment.
End User:
End-user industries dictate sensor specifications, compliance requirements, and purchasing volumes, from industrial giants to specialized laboratories.
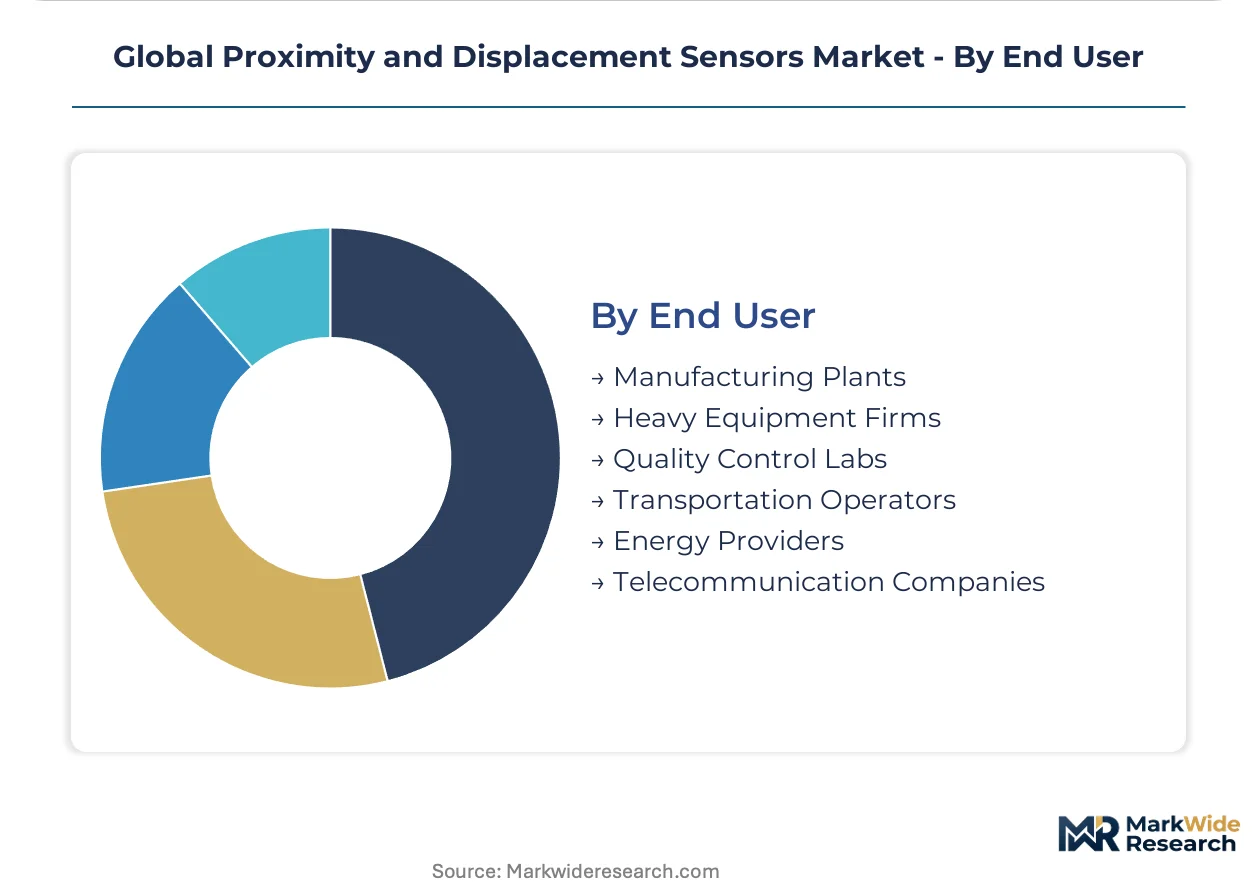
- Manufacturing Plants:These facilities represent the largest end-user segment, integrating a wide range of sensors for process control, quality assurance, and IIoT platforms across global operations.
- Quality Control Labs:These labs utilize high-precision sensors for metrology, material testing, and product validation, demanding sub-micron resolution capabilities from specialized optical and eddy current sensors.
- Heavy Equipment Firms:Sensors monitor operational parameters like position, tilt, and pressure in construction, mining, and agricultural machinery, often requiring ruggedized designs.
- Transportation Operators:This segment includes automotive, rail, and marine, where sensors are used for safety systems, navigation, and vehicle performance monitoring, adhering to specific regional regulations like those from the KBA in Germany.
- Energy Providers:Sensors monitor infrastructure, detect faults, and optimize generation processes in power plants and renewable energy facilities, often requiring ATEX or IECEx certified devices.
- Telecommunication Companies:Sensors manage physical infrastructure, monitor environmental conditions in data centers, and ensure the integrity of network equipment.
Supply concentration is strongest for Manufacturing Plants, while Quality Control Labs are increasingly demanding highly specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes for proximity and displacement sensors are highly concentrated in industrial automation and precision manufacturing segments globally. These sophisticated users, driven by IIoT integration and advanced robotics, demand high-performance sensor solutions for operational efficiency. This concentration drives regional market dynamics and technology adoption across various industrial sectors worldwide.
Germany
Germany's advanced manufacturing clusters drive substantial demand for sensors integrated into IIoT platforms. CE marking ensures product safety and electromagnetic compatibility for sensors deployed across its highly regulated industries. Bavarian and Baden-Württemberg regions, renowned for automotive and machine tool production, lead sensor adoption for predictive maintenance and quality assurance.
United States
Robotics expansion and emerging automotive applications stimulate significant sensor demand in the United States. FCC regulations govern radio frequency interference from sensor electronics, impacting product design and compliance for domestic and imported devices. Manufacturing hubs in the Midwest and aerospace clusters in the Pacific Northwest integrate sensors for automation, critical system monitoring, and advanced vehicle safety.
China
Manufacturing plants and expanding material handling sectors fuel substantial sensor demand across China's industrial landscape. GB standards dictate product compliance for all sensors sold within the country's vast and rapidly developing industrial base. The Yangtze River Delta region, a major manufacturing hub, rapidly deploys sensors for factory automation, smart logistics, and quality inspection on production lines.
Japan
Precision manufacturing and semiconductor fabrication equipment drive demand for high-resolution sensors in Japan's advanced industries. JIS standards ensure quality and performance benchmarks for industrial components, including advanced optical and eddy current sensor technologies. The Kanto region, home to major electronics and automotive manufacturers, integrates these sensors for critical quality control and high-speed automation.
Global Proximity and Displacement Sensors Market Key Industry Players
Player mix skews toward established industrial technology providers and specialized sensor manufacturers with deep expertise across various industries. The market exhibits a tiered structure, where global conglomerates compete against niche players focused on advanced sensor technologies for specific, high-value applications. Strategic archetypes include broad industrial automation suppliers leveraging extensive ecosystems and precision measurement specialists driving innovation. Companies engage in portfolio diversification and strategic partnerships to expand their application reach and integrate new functionalities.
Within the industrial automation and precision sensing tier, Rockwell Automation exemplifies a major player leveraging its extensive industrial automation ecosystem to integrate certified sensors. OMRON Corporation represents a specialist in high-precision optical and photoelectric sensors, particularly for advanced factory automation lines and quality control. KEYENCE CORPORATION occupies a distinct position through its direct sales model and continuous advanced sensor technology development, catering to technically demanding sectors. These firms anchor innovation and market development in their respective strategic domains, influencing technology standards and application trends globally.
| Leading Market Players |
|---|
| OMRON Corporation |
| Rockwell Automation |
| Panasonic Corporation |
| Hans Turck GmbH & Co. KG |
| Balluff GmbH |
| Schneider Electric SE |
| KEYENCE CORPORATION |
| ifm electronic gmbh |
| Honeywell International Inc. |
Cost & Logistics Intelligence
Advanced photoelectric sensor technology displacing traditional mechanical limit switches simultaneously reshapes supply geography and pricing economics. This shift elevates the value proposition of high-precision manufacturers while driving cost optimization in mature sensor segments.
Pricing Analysis
Long-term contracts for specialized sensors often incorporate cost-plus models, frequently indexed to raw material prices for specialized metals or labor costs in high-tech manufacturing hubs. Transactional per-unit pricing dominates for standard inductive sensors in high-volume applications. Certification level, particularly IECEx or ATEX compliance, and custom engineering services drive significant price differentiation. Pricing softness reflects increasing competition in the standard industrial-grade sensor market. Manufacturing plants exhibit high price sensitivity for commodity sensors, whereas quality control labs prioritize performance and accuracy over initial cost.
Supply Chain Analysis
Extended lead times for highly specialized sensors, especially those requiring specific certifications, impact project planning for end-users. Geographic supply concentration for critical components centers on Germany, Japan, and China. Raw material dependencies include specialized silicon wafers for optical sensors and rare earth elements for advanced magnetic sensors. Regulatory restrictions on critical component exports from major producing nations pose a structural supply chain risk. Distribution for advanced sensor technologies increasingly runs through direct-to-engineer sales channels, while traditional industrial distributors handle high-volume standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with IIoT integration accelerating demand for connected devices across industrial sectors.
For Market Incumbents:Shield existing market share from disruptive technologies by continuously investing in advanced sensor fusion R&D. Strengthen global certification pathways, particularly for hazardous environments, to maintain regulatory compliance advantages. A named threat, such as substitution from lower-cost 2D vision systems in inspection, necessitates product portfolio diversification. Deepen vertical integration into microfabrication for critical sensor components to control quality and cost.
For New Entrants and Emerging Players:Certification fast-tracks, such as those for specific regional safety standards, offer a strategic entry point into high-value segments. Target white-space opportunities in non-industrial verticals like smart agriculture for crop monitoring or emerging automotive applications for EV charging alignment. Small-to-medium enterprises in precision manufacturing requiring custom solutions represent a penetrable segment. A direct technical consultation and collaborative design partnership model can serve as an effective go-to-market angle.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mature industrial sensor manufacturers, particularly mid-cap automation component suppliers with established customer bases. The long-term viability of this market, essential for future automation and data-driven industries, extends over a decade. Acquisition targets should include specialized sensor developers with unique intellectual property in optical or eddy current technologies. Increased M&A activity for sensor fusion platforms serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Sensor Fusion R&D | Combines data streams for robust detection in complex industrial settings. |
| Global Certification Streamlining | Accelerates market entry for specialized sensors in regulated regions. |
| Direct-to-Engineer Sales Expansion | Builds deeper customer relationships for custom high-precision solutions. |
| Microfabrication Capacity Investment | Secures supply and controls costs for critical high-resolution components. |
| Partnerships for IIoT Integration | Expands sensor ecosystem compatibility with advanced automation platforms. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather qualitative insights into market dynamics. Primary interviews with automation engineers, plant managers, product development leads, and procurement specialists informed the analysis. These insights were triangulated with secondary data from industrial association reports, patent databases, technical journals, and company annual reports, synthesizing qualitative and quantitative market data through bottom-up and top-down analysis.
The market analysis extends across the projection horizon, utilizing a robust analytical framework. Segmentation dimensions modeled include product type, underlying technology, primary application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included IIoT platform adoption rates, robotics deployment forecasts, and manufacturing output growth across core end-user industries.
Decision-makers should treat outputs as directional under stable global trade policies and sustained industrial investment; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging that sudden shifts in international trade regulations or accelerated substitution from alternative technologies could significantly revise projections. Revision becomes warranted when significant changes in key end-user industry capital expenditure cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
MEMS for Mobile Devices Market