
 Active Sensor Market | 2026-2036
Active Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Active Sensor Market Outlook
Sensor-as-a-service subscription models for predictive maintenance and over-the-air calibration is recalibrating how vendors monetize hardware deployments. Infineon Technologies AG leverages its SiGe-based radar chipset portfolio to dominate automotive 77 GHz frequency bands. Robert Bosch GmbH anchors its competitive position through captive MEMS foundry capacity and tier-one supply relationships with German OEMs.
An active sensor autonomously emits energy—radio waves, laser pulses, ultrasonic bursts, or infrared beams—to detect object presence, distance, velocity, or material composition, with operating frequencies spanning 24 GHz to 1550 nm wavelength depending on modality. Automotive radar and lidar modules serve collision avoidance and highway pilot functions by generating real-time 3D point clouds at refresh rates exceeding 20 Hz. Optical sensors and infrared technology capture the fastest expansion as smart home security and healthcare wearables drive unit volumes. Radar sensors retain the largest revenue pool due to ASP premiums in aerospace terrain-mapping and military targeting applications.
The UNECE World Forum for Harmonization of Vehicle Regulations, the EU AI Act, and China's MIIT GB standards collectively mandate functional-safety certification and electromagnetic-compatibility testing for autonomous sensor systems. These frameworks raise compliance costs for new entrants while locking in incumbent advantage through established homologation pathways. Stakeholders must monitor divergence between European type-approval requirements and Chinese national standard evolution when configuring regional product variants.
Market Dynamics
Automotive OEM procurement consolidation around 77 GHz radar and 1550 nm lidar modules is compressing supplier margins while elevating performance validation requirements under the EU AI Act and UNECE vehicle-type approval frameworks.
Growth Catalysts
- UNECE R79/R157 mandates:European vehicle-type approval rules now require redundant sensor architectures for highway pilot systems, forcing tier-one suppliers to double unit volumes per vehicle platform.
- China's MIIT GB standards:Updated electromagnetic-compatibility testing protocols for autonomous driving systems are accelerating domestic certification timelines for radar and lidar manufacturers in the eastern manufacturing corridor.
- MEMS foundry scaling:Captive silicon-germanium and MEMS production capacity in Germany and Japan is lowering unit costs for automotive radar chipsets below competing gallium-nitride alternatives.
Market Restraints
- Indium phosphide supply concentration:1550 nm lidar transmitter components depend on a narrow supplier base concentrated in East Asian refining operations, exposing module assemblers to input cost volatility.
- Functional-safety certification burden:ISO 26262 ASIL-D validation for automotive radar systems requires 18-24 month qualification cycles that freeze out new entrants lacking established homologation pathways.
- Solid-state lidar substitution:Flash and optical phased array architectures are displacing mechanical scanning units in low-speed urban autonomy applications, eroding ASP premiums in the sub-50 meter range segment.
Strategic Opportunities
- India's automotive sensor gap:Domestic EV production under the PLI scheme lacks local lidar and 77 GHz radar sourcing, creating white space for module assembly partnerships with Pune and Chennai tier-one clusters.
- Healthcare wearables convergence:Photoplethysmography and infrared temperature sensing is integrating with radar-based vital sign monitoring, opening new device categories for continuous patient monitoring.
- EU AI Act compliance services:Mandatory algorithmic transparency documentation for autonomous sensor suites is spawning adjacent revenue streams in validation tooling and third-party audit services.
Industry Challenges
- RF/mmWave engineering scarcity:The talent pool for 77-81 GHz radar frontend design remains concentrated among semiconductor veterans in Germany and Japan, constraining R&D scaling for new entrants.
- Multi-sensor fusion complexity:Time-synchronization between lidar point clouds and radar velocity tracks demands specialized calibration protocols that extend vehicle integration timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Sensor Market |
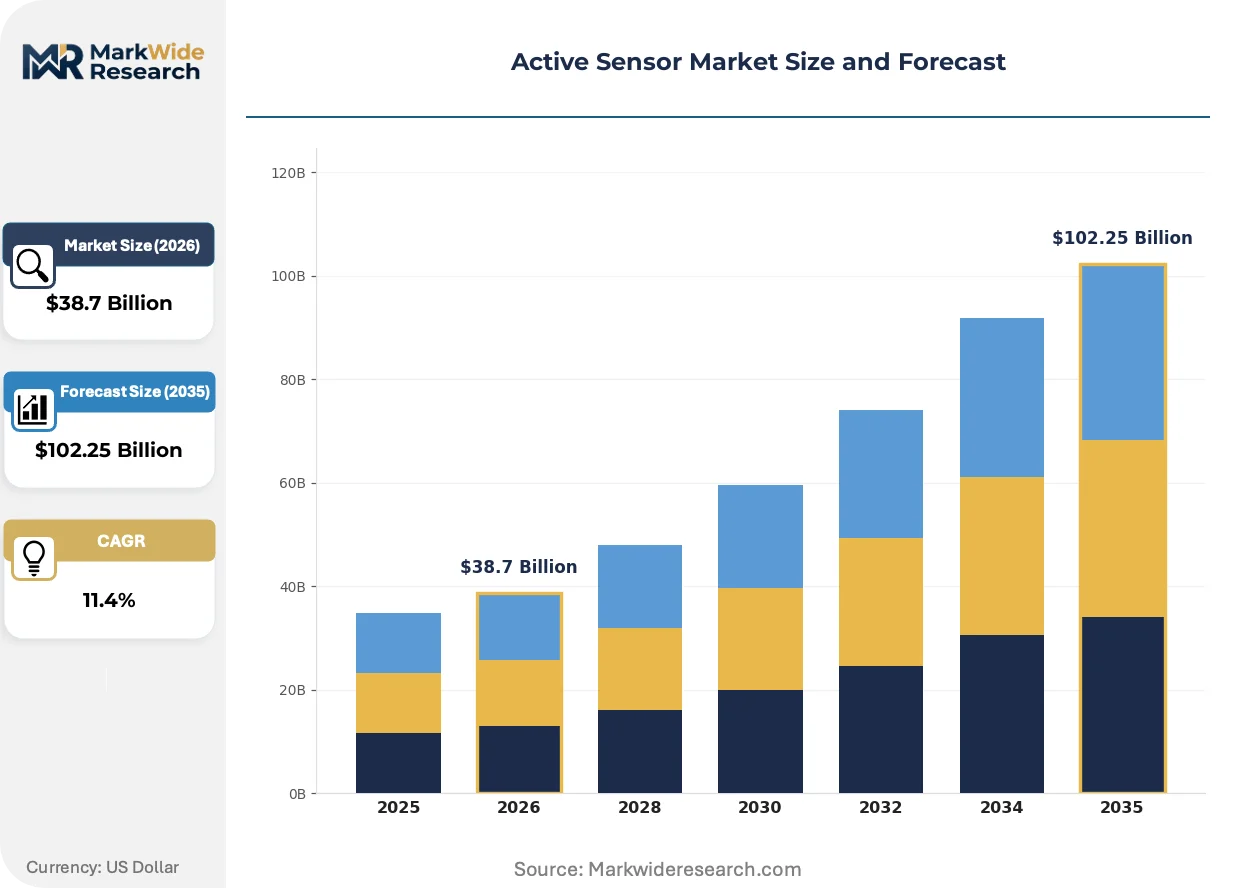
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, Lidar Sensors, Ultrasonic Sensors, Optical Sensors Technology: Analog Technology, Digital Technology, Wireless Technology, Infrared Technology End User: Automotive, Aerospace, Industrial Automation, Consumer Electronics Application: Smart Homes, Robotics, Environmental Monitoring, Healthcare |
| Companies Covered | Honeywell International Inc., Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, Texas Instruments Incorporated, Microchip Technology Inc., TE Connectivity, Robert Bosch GmbH, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Sensor Market Strategic Shifts
Solid-state beam steering and silicon photonics are compressing lidar form factors while software-defined radar architectures are enabling over-the-air performance updates. These shifts are recalibrating how sensor vendors monetize hardware deployments and maintain customer relationships.
Silicon photonics-based frequency-modulated continuous-wave lidar is integrating indium phosphide lasers with CMOS-compatible waveguides to slash transmitter costs below mechanical scanning alternatives. Tier-one automotive suppliers in Germany are adopting these chip-scale packages for 2027 highway pilot programs. The technology is integrating optical and electronic functions onto single substrates, collapsing module footprints by 60 percent while elevating reliability metrics.
REACH restrictions on per- and polyfluoroalkyl substances are forcing MEMS foundries to reformulate wafer-level encapsulation chemistries used in radar resonator cavities. European automotive sensor manufacturers face 12-18 month material requalification cycles that delay new product introductions. The regulation is compressing supplier margins most severely in the 24 GHz industrial radar segment, where cost-sensitive buyers resist price pass-through.
Sensor-as-a-service contracts for predictive maintenance and remote calibration are displacing perpetual hardware sales in fleet management and industrial automation verticals. Buyers in Germany's logistics corridor now prefer per-mile pricing for trailer-mounted radar monitoring systems. This model concentrates recurring revenue with vendors maintaining cloud-connected firmware update infrastructure.
Active Sensor Market Segmentation
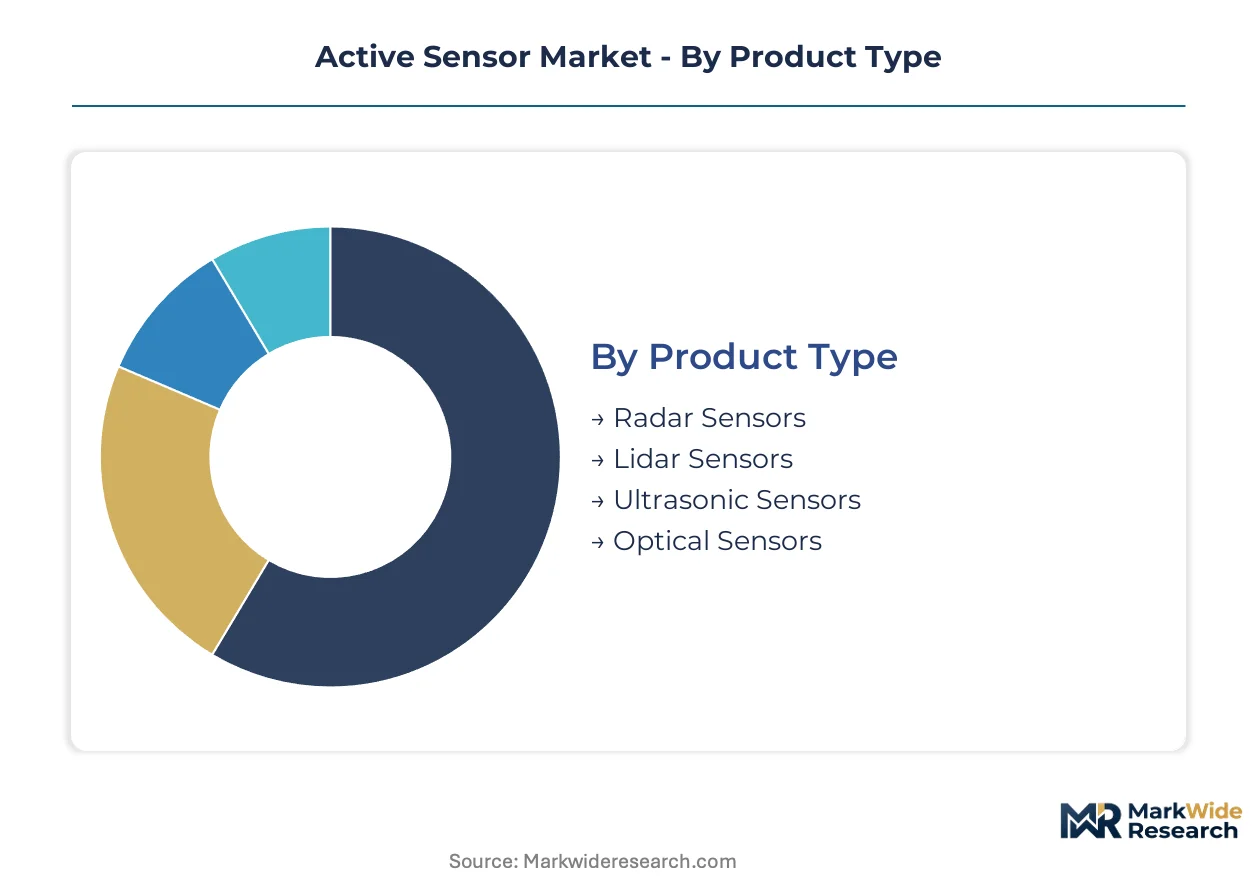
Active sensor architectures diverge sharply across emission modality and signal processing topology, with procurement patterns clustering around automotive validation requirements and industrial reliability benchmarks. Understanding these fault lines exposes where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Supply concentration for finished modules tilts heavily toward 77 GHz radar and 1550 nm lidar, where captive foundry capacity in Germany and Japan locks in tier-one automotive relationships.
- Radar Sensors:These units emit radio waves in 24-81 GHz bands to detect object velocity and range through Doppler shift analysis. Procurement from German and Japanese OEMs concentrates around 77 GHz chipsets for highway pilot systems, with SiGe foundry capacity constraining new supplier entry. Automotive radar retains the largest revenue pool due to ASP premiums in aerospace terrain-mapping and military targeting applications.
- Lidar Sensors:Laser-based systems generate 3D point clouds through time-of-flight or frequency-modulated continuous-wave methods, with 1550 nm wavelength variants dominating automotive long-range perception. Indium phosphide supply concentration in East Asian refining operations exposes module assemblers to input cost volatility for transmitter components.
- Ultrasonic Sensors:Short-range proximity detection for parking assistance and industrial safety interlocks relies on piezoelectric transducers with sub-meter accuracy.
- Optical Sensors:Smart home security and healthcare wearables drive unit volume expansion for infrared and visible-spectrum imaging modules.
Today's leader: Radar Sensors. Tomorrow's challenger: Lidar Sensors.
Technology:
Cost tier stratification separates legacy analog implementations from digital architectures commanding premium pricing in functional-safety-certified deployments.
- Digital Technology:Software-defined architectures enable over-the-air performance updates and algorithmic reconfiguration without hardware replacement. Fleet operators in Germany's logistics corridor now prefer per-mile pricing for cloud-connected radar monitoring systems, concentrating recurring revenue with vendors maintaining firmware infrastructure.
- Analog Technology:Mature signal conditioning circuits dominate cost-sensitive industrial proximity sensing where millimeter-scale precision suffices. Foundry economics in China's eastern manufacturing corridor favor analog CMOS processes for high-volume consumer applications.
- Wireless Technology:RF and mmWave frontends for automotive radar depend on specialized SiGe and gallium-nitride process nodes with limited foundry availability.
- Infrared Technology:Non-contact temperature sensing and photoplethysmography applications integrate with radar-based vital sign monitoring for continuous patient monitoring devices.
Digital Technology commands premium positioning. Infrared Technology climbs fastest on healthcare convergence.
End User:
Application maturity varies dramatically, with automotive demanding ISO 26262 ASIL-D validation cycles that freeze out entrants lacking established homologation pathways.
- Automotive:ADAS and autonomous platforms consume 77 GHz radar and 1550 nm lidar modules under UNECE R79/R157 mandates requiring redundant sensor architectures. EU AI Act algorithmic transparency requirements and updated vehicle-type approval rules tighten performance validation standards.
- Aerospace:Terrain-mapping and military targeting applications sustain ASP premiums for high-reliability radar systems with extended temperature ranges.
- Industrial Automation:Predictive maintenance subscriptions displace perpetual hardware sales as buyers prefer outcome-based pricing for sensor-as-a-service deployments.
- Consumer Electronics:Healthcare wearables and smart home devices drive optical and infrared sensor volumes with compressed margins and rapid product cycles.
Automotive dominates value capture. Healthcare wearables within Consumer Electronics represent the steepest expansion trajectory.
Application:
Customer type fragmentation separates enterprise fleet operators demanding predictive maintenance integration from residential buyers prioritizing installation simplicity.
- Smart Homes:Security and environmental control systems integrate optical and infrared sensors with voice-activated hub architectures. China's MIIT GB electromagnetic-compatibility standards accelerate domestic certification timelines for radar and lidar manufacturers supplying adjacent building automation markets.
- Healthcare:Continuous patient monitoring devices fuse photoplethysmography, infrared temperature sensing, and radar-based vital sign tracking into single wearable form factors.
- Robotics:Autonomous mobile robots and collaborative arms require multi-sensor fusion of lidar point clouds with radar velocity tracks, extending integration timelines through specialized calibration protocols.
- Environmental Monitoring:Industrial emissions and weather sensing applications deploy lidar for atmospheric particulate detection with lower unit volumes than consumer segments.
Smart Homes anchor near-term volume. Healthcare applications gain share fastest on regulatory tailwinds for remote patient monitoring reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEM procurement dwarfs Japan's tier-one supplier base in radar unit volumes, yet China's eastern manufacturing corridor now outpaces both in lidar module assembly capacity.
United States
NHTSA mandates for automatic emergency braking systems drive 77 GHz radar deployment across Detroit's OEM platforms. FCC spectrum allocation rules for 60-64 GHz industrial applications create parallel demand streams. Austin and Phoenix anchor autonomous vehicle testing corridors where lidar validation protocols compress supplier qualification timelines.
Germany
KBA type-approval requirements under UNECE R79 force redundant sensor architectures for highway pilot systems. EU AI Act algorithmic transparency rules extend compliance burdens to sensor fusion software. Stuttgart and Munich host captive MEMS foundry operations that lock in SiGe radar chipset supply for domestic OEMs.
China
MIIT GB electromagnetic-compatibility standards accelerate domestic certification for radar and lidar manufacturers serving NEV platforms. Dual carbon goals pressure foundries to reformulate wafer-level encapsulation chemistries. The Yangtze River Delta manufacturing corridor concentrates module assembly for BYD and NIO vertical integration programs.
Japan
METI subsidies for autonomous driving R&D sustain tier-one supplier investments in 1550 nm lidar transmitters. JIS standards for functional safety create qualification barriers for foreign entrants. Nagoya's automotive cluster hosts precision optics manufacturers supplying Toyota and Honda ADAS programs.
India
PLI scheme incentives for domestic EV production expose sourcing gaps in 77 GHz radar and lidar modules. BIS certification timelines lag European and Chinese equivalents by 8-12 months. Pune and Chennai tier-one clusters seek module assembly partnerships to substitute imported sensor suites.
Active Sensor Market Competitive Environment
Top-tier vendors anchor automotive-grade radar and lidar supply, while mid-scale fabricators compete on industrial proximity sensing and consumer optical modules. Captive MEMS foundry capacity separates premium-tier suppliers from fabless competitors dependent on external wafer allocation. Two strategic archetypes dominate: semiconductor conglomerates leveraging SiGe process nodes, and diversified industrials integrating sensor production with automotive tier-one relationships. Capacity expansion in Germany and Japan proceeds alongside strategic partnerships for indium phosphide supply security.
Within the semiconductor archetype, Infineon Technologies AG and STMicroelectronics exemplify European vendors with captive foundry infrastructure. Robert Bosch GmbH anchors the diversified industrial tier, representing German OEM-integrated suppliers with backward control over MEMS fabrication. These three occupy positions that translate process technology leadership into preferred supplier status under UNECE and EU AI Act certification frameworks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| Microchip Technology Inc. |
| TE Connectivity |
| Robert Bosch GmbH |
| OMRON Corporation |
| Others |
Value Chain & Pricing Dynamics
Solid-state beam steering and silicon photonics integration are collapsing lidar module footprints by 60 percent while simultaneously concentrating transmitter production in East Asian indium phosphide refining corridors, creating asymmetric cost advantages for captive foundry operators and squeezing margins for fabless assemblers dependent on spot market inputs.
Pricing Analysis
Capacity additions in China's eastern manufacturing corridor are reshaping price floors for automotive radar chipsets, with domestic MEMS foundry scaling undercutting gallium-nitride alternatives. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and industrial-grade tiers separates German OEM procurement from cost-sensitive 24 GHz industrial buyers. Cost compression in the sub-50 meter lidar segment is intensifying because flash architectures displace mechanical scanning units. Fleet operators in Germany's logistics corridor exhibit lowest price sensitivity due to sensor-as-a-service subscription preferences, while China's NEV brands drive hardest unit cost negotiations.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai anchor hub-and-spoke patterns for automotive-grade sensor modules, with last-mile delivery to OEM assembly plants averaging 48-72 hours. Geographic supply concentration centers on Germany and Japan for SiGe radar chipsets, Taiwan for MEMS foundry services, and East Asia for indium phosphide laser components. Raw material dependencies draw from silicon-germanium wafers, indium phosphide substrates, and specialized fluoropolymer encapsulation chemistries. Single-source vulnerability in 1550 nm transmitter supply exposes module assemblers to input cost volatility. Distribution runs through tier-one supplier direct-ship arrangements with German and Japanese OEMs, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Active Sensor Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany diverge from China's accelerated MIIT GB certification timelines, creating 12-18 month regulatory cost differentials that favor module assembly partnerships in the eastern manufacturing corridor.
For Market Incumbents: Deploy captive MEMS foundry capacity as the primary defensive lever against solid-state lidar substitution threatening mechanical scanning revenue pools. Lock in indium phosphide supply security through long-term offtake agreements with East Asian refiners before flash architecture adoption accelerates. Reinforce ASIL-D certification moats by extending validation tooling services to OEM customers, converting compliance burden into recurring revenue streams. For New Entrants and Emerging Players: India's PLI scheme for domestic EV production opens a window for module assembly partnerships with Pune and Chennai tier-one clusters lacking local 77 GHz radar and lidar sourcing. Target healthcare wearables convergence as the most penetrable segment, where photoplethysmography-radar fusion devices face lower ISO 26262 barriers than automotive deployments. Pursue sensor-as-a-service go-to-market positioning with per-mile pricing models that concentrate recurring revenue and reduce upfront customer capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale MEMS foundry operators because captive silicon-germanium capacity commands premium tier-one supplier status under UNECE and EU AI Act frameworks. Acquire targets with established homologation pathways rather than technology-only assets, as 18-24 month ISO 26262 qualification cycles freeze out new entrants. Watch for indium phosphide supply disruption signals as the inflection indicator for lidar module pricing volatility and margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Captive SiGe production locks in German OEM supply relationships under UNECE R79 mandates. |
| Indium Phosphide Supply Agreement | Long-term offtake secures 1550 nm lidar transmitter inputs against East Asian refining concentration. |
| EU AI Act Compliance Service Launch | Algorithmic transparency documentation creates adjacent revenue from OEM validation tooling demand. |
| Sensor-as-a-Service Platform Deployment | Per-mile pricing for fleet operators concentrates recurring revenue with cloud-connected firmware vendors. |
| Healthcare Wearables Partnership | Photoplethysmography-radar fusion opens continuous patient monitoring categories outside automotive certification barriers. |
Study Parameters
Coverage spans Germany, Japan, China, and the United States, with primary inputs from each regional cluster combining structured interviews with tier-one supplier procurement directors, OEM platform engineers, MEMS foundry operations managers, and regulatory affairs leads specializing in UNECE and EU AI Act compliance. Secondary validation draws from SEC 10-K filings of semiconductor conglomerates, MIIT GB standard publications, KBA type-approval databases, and IHS Markit vehicle production data. Bottom-up unit volume estimates triangulate against top-down revenue aggregation across the analysis window.
Rate-of-change decomposition separates volume growth from ASP trajectory across radar, lidar, ultrasonic, and optical sensor modalities, with segmentation modeling by product type, technology architecture, end-user vertical, and application. CAGRs derive from regression analysis of historical procurement patterns and forward-looking OEM platform deployment schedules, incorporating foundry capacity expansion timelines and regulatory mandate phase-in curves as industry-specific forecast inputs.
Revisions become necessary when indium phosphide supply disruptions, REACH restriction enforcement timelines, or solid-state lidar substitution rates materially diverge from baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Microseismic Monitoring Technology Market