
 Mass Flow Controller Market | 2026-2036
Mass Flow Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Flow Controller Market Analysis
The Mass Flow Controller Market is pivoting on a widening divergence between premium thermal and Coriolis units engineered for sub-1% accuracy in semiconductor vacuum chambers, and commodity differential pressure controllers serving bulk chemical and water treatment applications. Brooks Instrument leverages proprietary thermal sensor architectures to sustain pricing power in advanced node fabs. Alicat Scientific differentiates through rapid multi-gas calibration capabilities that reduce downtime in research labs and pilot plants.
A mass flow controller is a precision instrument that measures and regulates the flow rate of gases or liquids by comparing actual flow against a setpoint, typically achieving accuracy within 0.5-1.0% of full scale through closed-loop valve modulation. Its primary purpose is to deliver exact quantities of process gases in semiconductor etch and deposition chambers, pharmaceutical bioreactors, and analytical instrumentation. Thermal controllers occupy the dominant share of semiconductor manufacturing applications where ultra-high purity gas handling commands premium margins, while digital and smart technology segments are expanding fastest as fabs replace analog units with Ethernet-enabled devices for predictive maintenance integration. Coriolis technology leads in chemical and food processing end uses where direct mass measurement eliminates density compensation errors inherent to volumetric methods.
The EPA enforces stringent volatile organic compound emission limits that compel chemical processors to upgrade leak-tight gas delivery systems, while the FDA's process analytical technology guidelines push pharmaceutical manufacturers toward validated digital flow control with full audit trails. China's MEE implements GB standards for industrial emissions monitoring that mandate calibrated mass flow measurement in stack gas analysis systems. Stakeholders must weigh the capital cost of smart controller migration against operational gains from reduced calibration labor and tighter process control.
Market Dynamics
Semiconductor foundry expansion in East Asia is forcing thermal mass flow controller suppliers to compress calibration cycles while maintaining sub-1% accuracy specifications for advanced node gas delivery systems.
Growth Catalysts
- China's dual carbon goals:The MEE's tightening industrial emissions standards mandate digital smart controllers in stack gas analysis, accelerating replacement of analog flow control systems across chemical processing clusters.
- Advanced node semiconductor production:Taiwan and South Korean fabs are expanding capital equipment procurement to support 3nm and 2nm process ramps, driving precision gas delivery requirements for etch and deposition chambers.
- Ethernet-enabled predictive maintenance:Smart controllers with embedded diagnostics are integrating into fab-wide SCADA networks, reducing unplanned downtime through real-time valve health monitoring.
Market Restraints
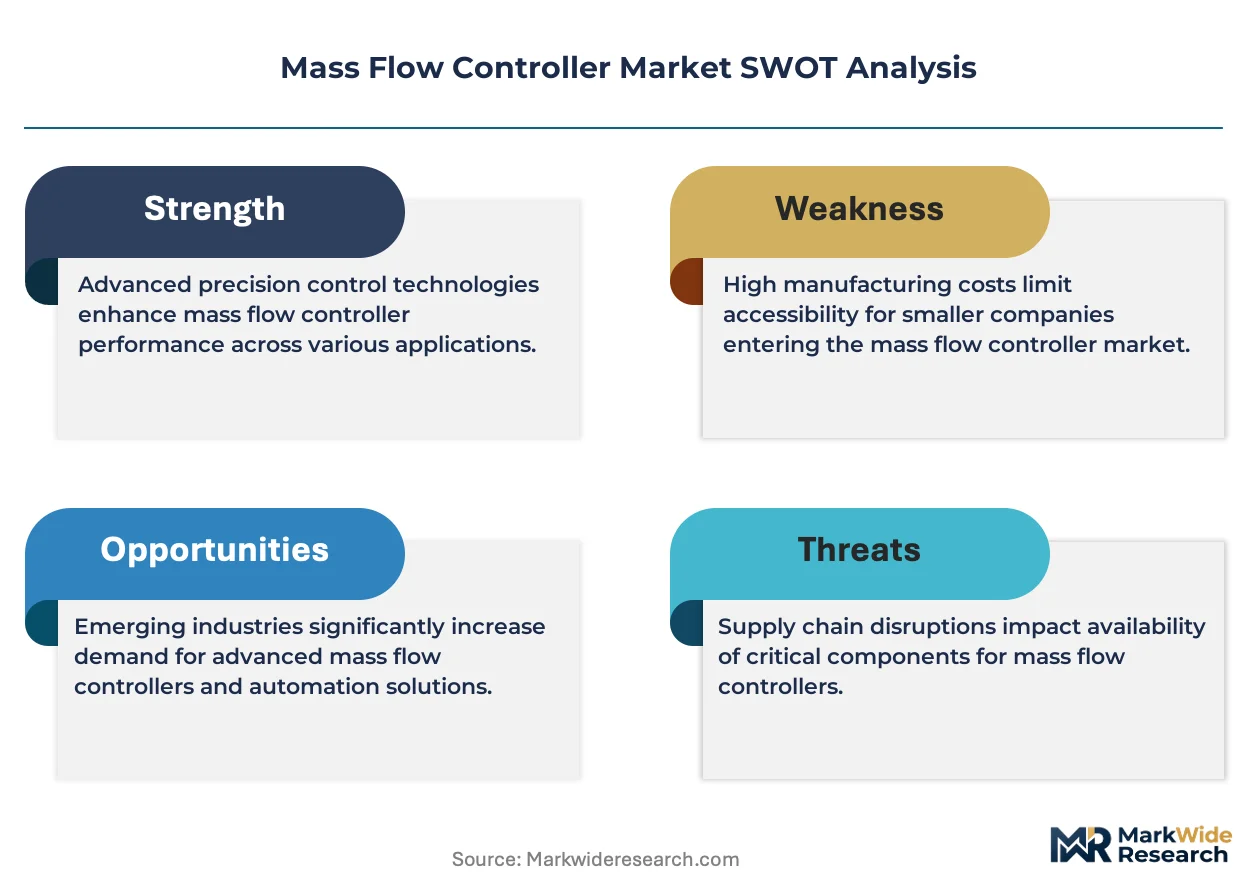
- High-purity sensor material costs:Thermal sensor architectures require specialized platinum alloys and ceramic substrates, exposing margins to precious metal price volatility.
- Supply concentration in East Asia:Precision valve assemblies and ultra-high-purity gas fittings concentrate among Taiwanese and Japanese component suppliers, creating geographic single-source risk.
- Coriolis technology substitution:Chemical and food processing end uses increasingly favor direct mass measurement over volumetric thermal methods, compressing addressable market for traditional thermal controllers.
Strategic Opportunities
- India's PLI scheme for semiconductors:The country's emerging fab ecosystem presents first-mover advantage for suppliers establishing local calibration and service infrastructure.
- Biopharma single-use systems:Disposable bioreactor architectures create demand for compact, gamma-sterilizable mass flow controllers with rapid multi-gas calibration capabilities.
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing require Coriolis controllers certified for high-pressure hydrogen service, opening adjacent industrial gas markets.
Industry Challenges
- Metrology technician scarcity:Advanced node fabs require specialists capable of traceable calibration to NIST standards for 0.5% accuracy validation, creating hiring bottlenecks in Taiwan and South Korea.
- Legacy analog system integration:Brownfield chemical plants face protocol translation complexity when retrofitting 4-20mA controllers to Ethernet/IP networks for predictive maintenance deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Flow Controller Market |
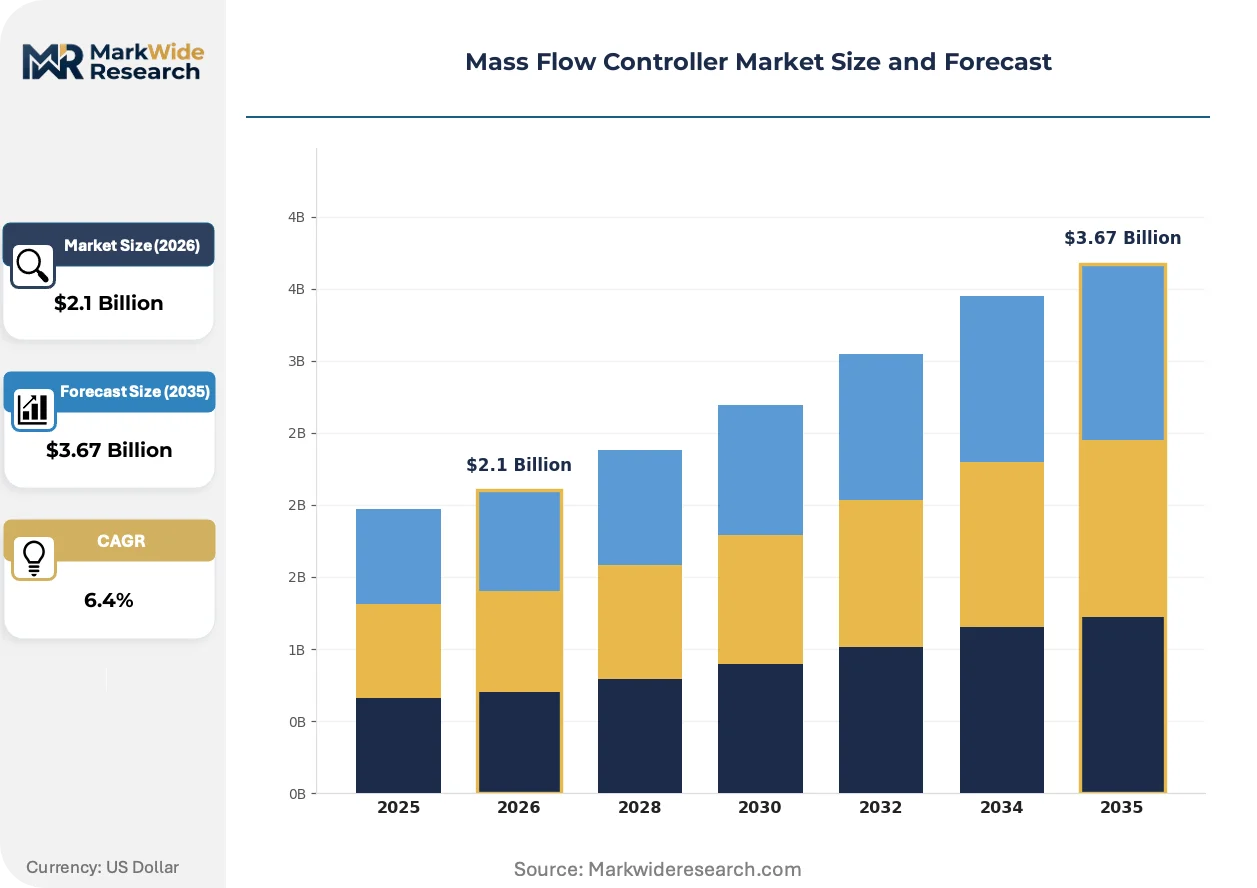
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Coriolis, Differential Pressure, Electromagnetic Technology: Analog, Digital, Smart, Microprocessor-Based End User: Electronics, Chemical, Food & Beverage, Pharmaceuticals Application: Water Treatment, Gas Flow Management, Semiconductor Manufacturing, Research Labs |
| Companies Covered | Brooks Instrument, Alicat Scientific, HORIBA Ltd., Parker Hannifin Corporation, Sierra Instruments, MKS Instruments, Sensirion AG, Teledyne Hastings Instruments, Bronkhorst High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Flow Controller Market Emerging Trajectories
Digitalization of process gas delivery is compressing the traditional divide between precision semiconductor applications and bulk industrial flow control, with smart connectivity becoming the default specification across both tiers.
Multi-gas calibration algorithms are integrating into thermal controller firmware, enabling automatic gas selection without hardware recalibration. Research labs and pilot plants in North America and Europe are adopting these capabilities to reduce downtime between process campaigns. This functionality is compressing the service revenue model traditional suppliers relied upon for recurring calibration business.
The EPA's enforcement of volatile organic compound emission limits is compelling chemical processors to upgrade leak-tight gas delivery systems with validated digital flow control. Facilities in Texas and Louisiana are retrofitting analog differential pressure controllers with Ethernet-enabled units capable of full audit trail documentation. This regulatory pressure is accelerating replacement cycles that historically extended beyond fifteen years.
After-sales service unbundling is reshaping buyer-supplier relationships in the pharmaceutical sector. Large molecule manufacturers are negotiating separate contracts for hardware procurement and calibration services, favoring suppliers with open protocol architectures over vertically integrated service bundles. This pattern is most visible in Massachusetts and North Carolina biotech clusters where multi-site standardization drives purchasing centralization.
Mass Flow Controller Market Segmentation
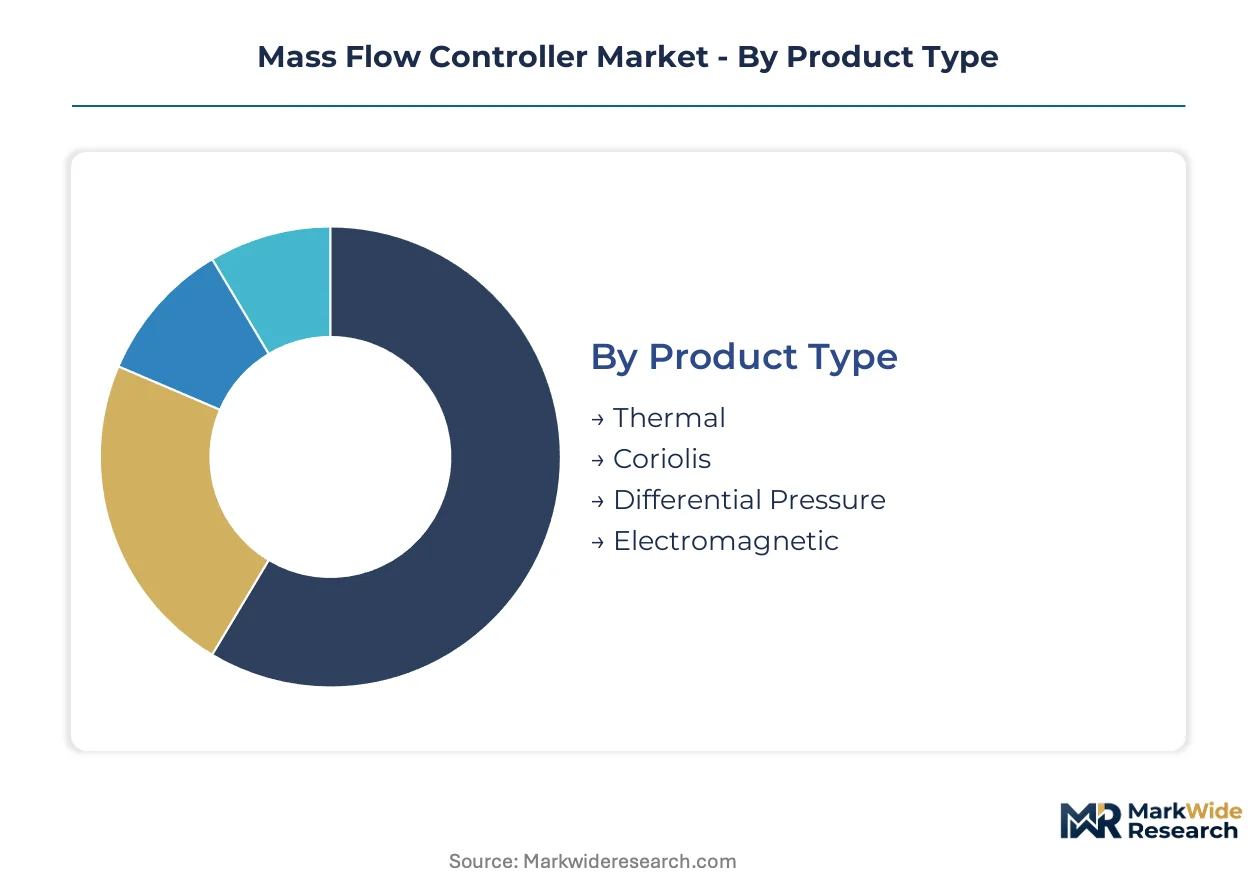
Mass flow controller procurement patterns diverge sharply across technology tiers and end-use certifications, with semiconductor fabs demanding traceable NIST calibration while chemical processors prioritize emissions-compliant digital architectures. Understanding these segment boundaries reveals where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Thermal controllers carry semiconductor-grade certification burdens including SEMI S2 and S8 safety compliance, while Coriolis units face ASME B31.3 pressure vessel codes in chemical service. Differential pressure and electromagnetic variants operate under lighter regulatory frameworks focused on general industrial safety standards.
- Thermal:Platinum-alloy sensor architectures achieve sub-1% accuracy in ultra-high-purity gas delivery, with demand concentrating in Taiwan and South Korean foundries expanding 3nm and 2nm process capacity. These units command premium pricing where vacuum chamber integrity is non-negotiable.
- Coriolis:Direct mass measurement eliminates density compensation errors through oscillating tube physics, with chemical processors in Texas and Louisiana adopting these units for EPA-mandated VOC emission control. The technology is displacing volumetric methods in food processing where recipe consistency is critical.
- Differential Pressure:Orifice-plate and venturi designs serve bulk water treatment and general industrial applications with lower accuracy requirements.
- Electromagnetic:Inductive flow measurement handles conductive liquids in municipal water infrastructure and wastewater treatment facilities.
Leading the category by volume: Thermal controllers. Growing fastest: Coriolis units expanding most quickly into hydrogen economy infrastructure.
Technology:
Smart and digital controllers require cybersecurity certifications for industrial Ethernet deployment, while analog units face no connectivity-related compliance overhead. Microprocessor-based architectures fall between these poles depending on protocol implementation.
- Analog:4-20mA signal architectures dominate legacy installations where retrofit capital is constrained, with brownfield chemical plants in Louisiana maintaining these systems beyond fifteen-year replacement cycles.
- Digital:Ethernet/IP and PROFINET-enabled units integrate into fab-wide SCADA networks, with Taiwan semiconductor clusters driving procurement for real-time valve health monitoring and predictive maintenance deployment.
- Smart:Embedded diagnostics with edge computing capabilities support autonomous calibration adjustment, with Massachusetts biotech manufacturers favoring these units for multi-site standardization.
- Microprocessor-Based:Dedicated processing cores enable rapid multi-gas switching without hardware recalibration, serving research labs and pilot plants in North America.
Highest margin capture: Smart controllers with predictive analytics. Steepest expansion trajectory: Digital units bridging analog legacy and smart connectivity.
End User:
Pharmaceutical and electronics sectors impose the strictest validation requirements, with FDA process analytical technology guidelines and SEMI standards driving documentation intensity. Food and beverage and chemical end users operate under less burdensome but still specific regulatory frameworks.
- Electronics:Semiconductor fabs in Taiwan and South Korea require 0.5% accuracy validation with full NIST-traceable calibration records, creating technician hiring bottlenecks that constrain supplier capacity.
- Pharmaceuticals:Single-use bioreactor architectures in North Carolina and Massachusetts clusters demand gamma-sterilizable controllers with rapid multi-gas calibration and complete audit trail documentation per FDA guidelines.
- Chemical:Processors in Texas and Louisiana retrofit analog systems to meet EPA volatile organic compound emission limits, with validated digital flow control becoming mandatory for permit compliance.
- Food & Beverage:Recipe consistency requirements drive adoption of direct mass measurement in dairy and beverage processing where density variation affects product quality.
Revenue concentration: Electronics sector. Fastest certification-driven replacement: Pharmaceuticals with single-use system adoption.
Application:
Semiconductor manufacturing and research labs demand the highest metrological rigor, with traceable calibration to international standards mandatory. Water treatment and gas flow management applications prioritize reliability and capital efficiency over extreme precision.
- Semiconductor Manufacturing:Etch and deposition chambers in East Asian foundries require thermal controllers with specialized platinum alloys and ceramic substrates, exposing margins to precious metal price volatility.
- Research Labs:Multi-gas calibration algorithms in North American and European pilot plants enable automatic gas selection without hardware recalibration, compressing traditional service revenue models.
- Gas Flow Management:Chemical processing clusters in China adopt digital smart controllers to meet MEE industrial emissions standards under dual carbon policy implementation.
- Water Treatment:Municipal and industrial facilities deploy differential pressure and electromagnetic units where volumetric accuracy suffices for bulk flow management.
Technology premium capture: Semiconductor Manufacturing. Fastest regulatory-driven upgrade cycle: Gas Flow Management with China's emissions monitoring mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors the world's most concentrated mass flow controller procurement activity, with foundry capacity expansion driving precision gas delivery requirements across East Asian manufacturing clusters.
United States
Texas and Louisiana chemical processors retrofit analog differential pressure controllers to meet EPA volatile organic compound emission limits. The EPA's enforcement of leak-tight gas delivery standards accelerates replacement cycles beyond fifteen-year historical norms. Houston's petrochemical corridor drives validated digital flow control adoption for permit compliance.
China
Stack gas analysis systems in Jiangsu and Shandong provinces mandate calibrated mass flow measurement under MEE industrial emissions standards. The country's dual carbon goals compel replacement of analog flow control with digital smart controllers across chemical processing clusters. Shanghai's industrial zones concentrate procurement for emissions monitoring infrastructure.
South Korea
Pyongtaek and Yongin semiconductor complexes expand capital equipment procurement to support 3nm and 2nm process ramps. MFDS guidelines for pharmaceutical manufacturing push validated digital flow control with full audit trails. Seoul Capital Area fabs require 0.5% accuracy validation with NIST-traceable calibration records.
Germany
Baden-Württemberg's automotive and industrial machinery sectors demand Coriolis controllers for direct mass measurement in chemical processing. REACH compliance and CE marking requirements drive certified controller procurement across Rhineland chemical corridors. Bavarian precision engineering clusters favor Ethernet-enabled units for predictive maintenance integration.
India
Maharashtra and Gujarat pharmaceutical manufacturers negotiate separate hardware and calibration service contracts under CDSCO process validation guidelines. The PLI scheme for semiconductors creates first-mover opportunity for suppliers establishing local calibration infrastructure. Bangalore's emerging fab ecosystem drives precision gas delivery requirements.
Mass Flow Controller Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and connectivity-architecture dimensions. The vendor base stratifies between SEMI-certified thermal specialists serving advanced node fabs and general industrial suppliers competing on capital efficiency. Three archetypes dominate: precision semiconductor-grade specialists, multi-gas calibration innovators, and scale-driven industrial flow control houses. Competitive moves concentrate on predictive maintenance software integration and unbundling of after-sales service contracts.
Within the precision semiconductor-grade tier, Brooks Instrument and MKS Instruments occupy positions defined by ultra-high-purity gas handling certification burdens. Alicat Scientific represents the multi-gas calibration innovation vector with rapid gas-switching capabilities. Among European-based fabricators, Bronkhorst High-Tech and HORIBA Ltd. exemplify the precision instrumentation archetype serving research and advanced manufacturing applications.
| Leading Market Players |
|---|
| Brooks Instrument |
| Alicat Scientific |
| HORIBA Ltd. |
| Parker Hannifin Corporation |
| Sierra Instruments |
| MKS Instruments |
| Sensirion AG |
| Teledyne Hastings Instruments |
| Bronkhorst High-Tech |
| Others |
Supply Flow & Price Mechanics
Family-owned Japanese precision component specialists anchor upstream supply for thermal sensor architectures, translating concentrated ownership into disciplined capacity allocation that sustains premium pricing for platinum-alloy controllers serving Taiwan foundries. Their refusal to expand beyond proven demand curves reinforces margin stability across semiconductor-grade tiers while constraining availability for second-source procurement.
Pricing Analysis
Value-based pricing anchored to wafer yield outcomes dominates semiconductor procurement, with thermal controllers commanding premiums tied to sub-1% accuracy validation in 3nm etch chambers. Price differentiation rests on SEMI certification grade and multi-gas calibration capability, with research labs least sensitive and bulk chemical processors most price-conscious. Cost compression in analog-to-digital retrofit tiers is intensifying because EPA emission compliance deadlines compress replacement timelines.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese precision valve assemblers and Japanese ceramic substrate fabricators, exposing thermal controller production to geographic concentration risk. Manufacturing draws from platinum alloy feedstock in South Africa, high-purity gas fittings in Japan, and microprocessor cores from US fabs. Tariff exposure on precision instrumentation intensifies as trade policy shifts, while distribution runs through OEM equipment bundlers and direct fab service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mass flow controller market sits in a technology-transition phase where Ethernet-enabled smart controllers displace 4-20mA analog architectures, with predictive maintenance integration now the default procurement specification rather than premium upgrade.
For Market Incumbents: Anchor semiconductor-grade certification moats through captive NIST-traceable calibration infrastructure in Hsinchu and Pyongtaek, while accelerating firmware development for autonomous gas-switching algorithms that neutralize Alicat's multi-gas speed advantage. Coriolis substitution in chemical processing threatens thermal controller addressable market; defend through backward integration into platinum alloy recycling to offset precious metal volatility. For New Entrants and Emerging Players: The premium-to-economy pricing gap in India's emerging fab ecosystem offers white-space entry before established players deploy local service infrastructure. Target gamma-sterilizable compact controllers for North Carolina single-use bioreactor clusters, where FDA audit trail requirements favor new suppliers with native digital architectures over legacy analog retrofitters. Lead with open-protocol service unbundling to displace vertically integrated incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision instrumentation specialists with SEMI certification assets in East Asia during foundry capital expenditure pauses. Long-term viability hinges on hydrogen economy Coriolis certification for high-pressure service. Watch MEE enforcement intensity in Jiangsu and Shandong as inflection signal for Chinese replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gas Calibration Firmware Development | Automatic gas selection without hardware recalibration compresses competitor service revenue models. |
| Predictive Maintenance Platform Integration | Edge diagnostics embedding into fab SCADA networks locks in long-term semiconductor procurement relationships. |
| Platinum Alloy Supply Security | Captive recycling or long-term offtake agreements hedge against South African feedstock volatility. |
| India Calibration Infrastructure Buildout | First-mover service presence under PLI scheme semiconductor incentives captures emerging fab demand. |
| Hydrogen Service Certification | Coriolis controllers rated for high-pressure electrolyzer applications open adjacent industrial gas markets. |
Methodological Framework
Independent corroboration across fab equipment procurement directors, metrology calibration technicians, and chemical plant maintenance engineers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEMI equipment market data, EPA enforcement disclosure databases, and customs records for precision instrumentation imports. Bottom-up unit demand estimates from foundry capital expenditure disclosures triangulate against top-down market sizing from semiconductor equipment bill-of-materials analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include technology tier, end-use certification intensity, and regional regulatory framework cluster. CAGRs derive from installed base turnover analysis and replacement cycle compression factors. Forecast inputs incorporate MEE enforcement trajectory assumptions and foundry node transition timelines without specific year anchoring.
Underlying measurement precision varies by segment; semiconductor manufacturing and pharmaceutical audit-trail applications carry tighter precision than bulk water treatment. Forecasts reflect documented assumptions about regulatory enforcement intensity and precious metal cost trajectories. Supply concentration in East Asian component sources and technician scarcity in Taiwan represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market