
 Thermal Camera Market | 2026-2036
Thermal Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Camera Market Intelligence
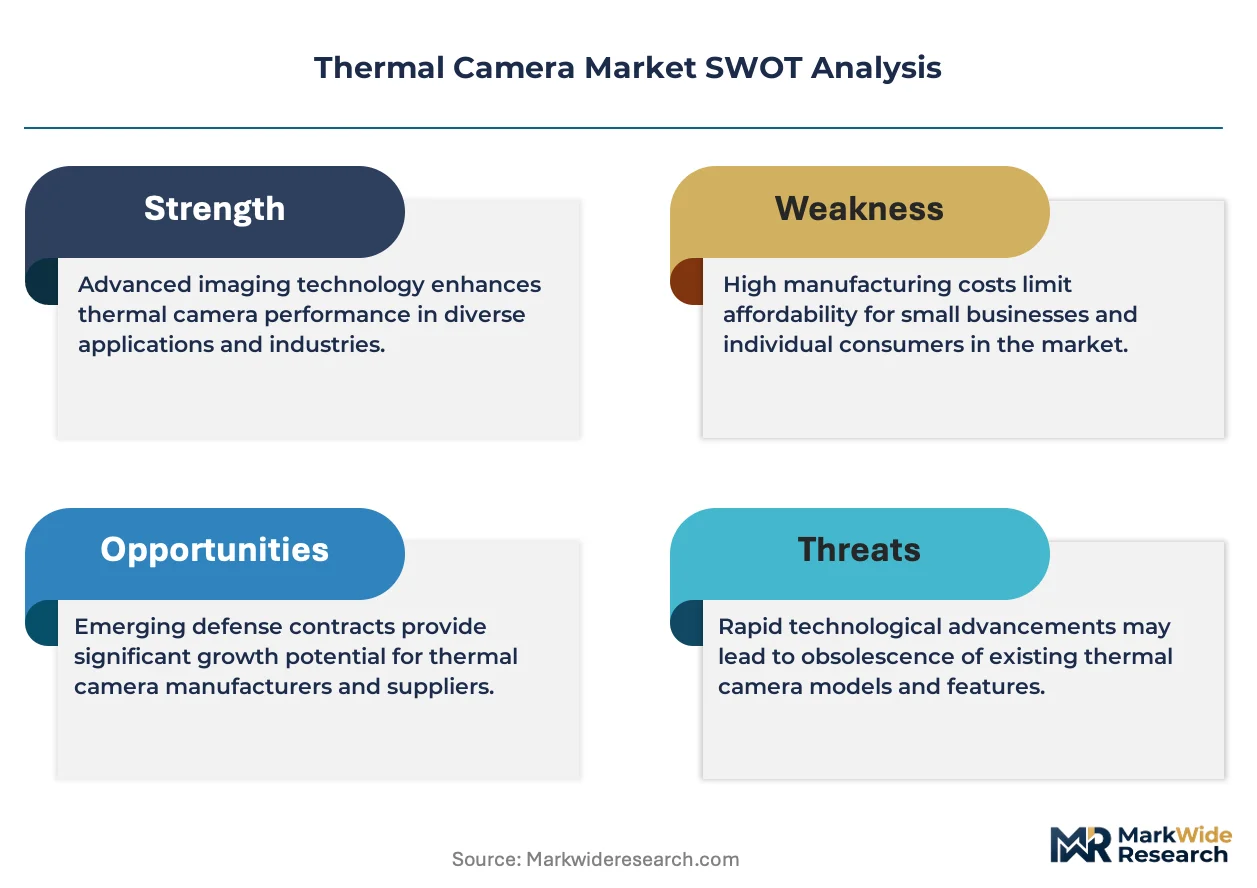
The unbundling of thermal imaging cores from dedicated hardware into smartphone-integrated modules is recalibrating buyer expectations for accessibility and overall system cost. Teledyne FLIR leverages its deep legacy in defense and high-performance industrial systems to maintain a premium market position. Meanwhile, Seek Thermal specializes in the expanding consumer-grade and prosumer device categories. Hikmicro competes on price-performance within the crowded handheld security and inspection segment.
A thermal camera is an instrument that creates a visual image using infrared radiation, similar to a common camera that forms an image using visible light. Its core component, a microbolometer, detects temperature differences as small as 0.01°C and translates them into a thermogram. Uncooled microbolometer technology dominates the market due to its lower cost and portability, especially for handheld products. Within applications, predictive maintenance and building inspection represent mature, high-volume segments.
The European Union's Energy Performance of Buildings Directive (EPBD) mandates thermal inspections, creating sustained demand for building diagnostics. In the United States, National Fire Protection Association (NFPA) standards increasingly recommend thermal imagers for first responders, influencing procurement by fire departments. Future competitive advantage will hinge on integrating thermal data with other sensor inputs and delivering actionable analytics, not just raw imagery.
Market Dynamics
The rapid commoditization of uncooled microbolometer sensors is the central force shaping the market. This technological shift lowers manufacturing costs and enables miniaturization, pushing thermal imaging beyond its traditional high-end industrial and defense strongholds into mainstream applications.
Growth Catalysts
- EU Energy Directive:The European Union's Energy Performance of Buildings Directive (EPBD) mandates thermal inspections for energy audits, creating sustained, regulation-driven demand for cameras in building diagnostics and HVAC system verification across member states.
- Predictive Maintenance Adoption:The embrace of Industry 4.0 principles in manufacturing clusters in Germany and China drives demand for thermal cameras, monitoring critical machinery like motors and electrical panels to prevent unscheduled downtime.
- Firefighter Safety Standards:The influence of National Fire Protection Association (NFPA) standards in the United States is compelling municipal fire departments to equip first responders with thermal imagers for enhanced situational awareness during structural fires.
Market Restraints
- Detector Production Cost:The high capital investment and complex fabrication processes for microbolometer sensor arrays, particularly for high-resolution models, create a significant cost floor, limiting adoption in extremely price-sensitive consumer segments.
- Export Controls:Strict export controls, such as the U.S. International Traffic in Arms Regulations (ITAR), on high-performance thermal cores limit market access and add compliance overhead for manufacturers selling across international borders.
- Material Opacity:The inability of thermal cameras to see through glass presents a fundamental technical limitation in certain security and surveillance applications, requiring alternative sensor placement or complementary technologies.
Strategic Opportunities
- Precision Agriculture:Using drone-mounted thermal cameras for monitoring crop health, irrigation levels, and livestock wellness represents a significant growth area, particularly in large-scale farming regions of the Americas and Australia.
- Technology Convergence:Integrating thermal data with visual, acoustic, or vibration sensor inputs on a single platform creates opportunities for advanced analytics and more accurate diagnostic systems in industrial IoT and autonomous vehicles.
- Southeast Asian Infrastructure:Rapid urbanization and infrastructure development in Southeast Asian nations create new demand for thermal imagers in construction quality control, utility maintenance, and public safety projects.
Industry Challenges
- Thermographer Skill Gap:A shortage of certified thermographers capable of correctly interpreting thermal images and diagnosing underlying issues poses a challenge to effective deployment, leading to potential misapplication and inaccurate findings.
- Software Integration Complexity:Integrating raw thermal data streams into existing enterprise asset management (EAM) or building information modeling (BIM) software requires significant customization, slowing enterprise-wide adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Camera Market |
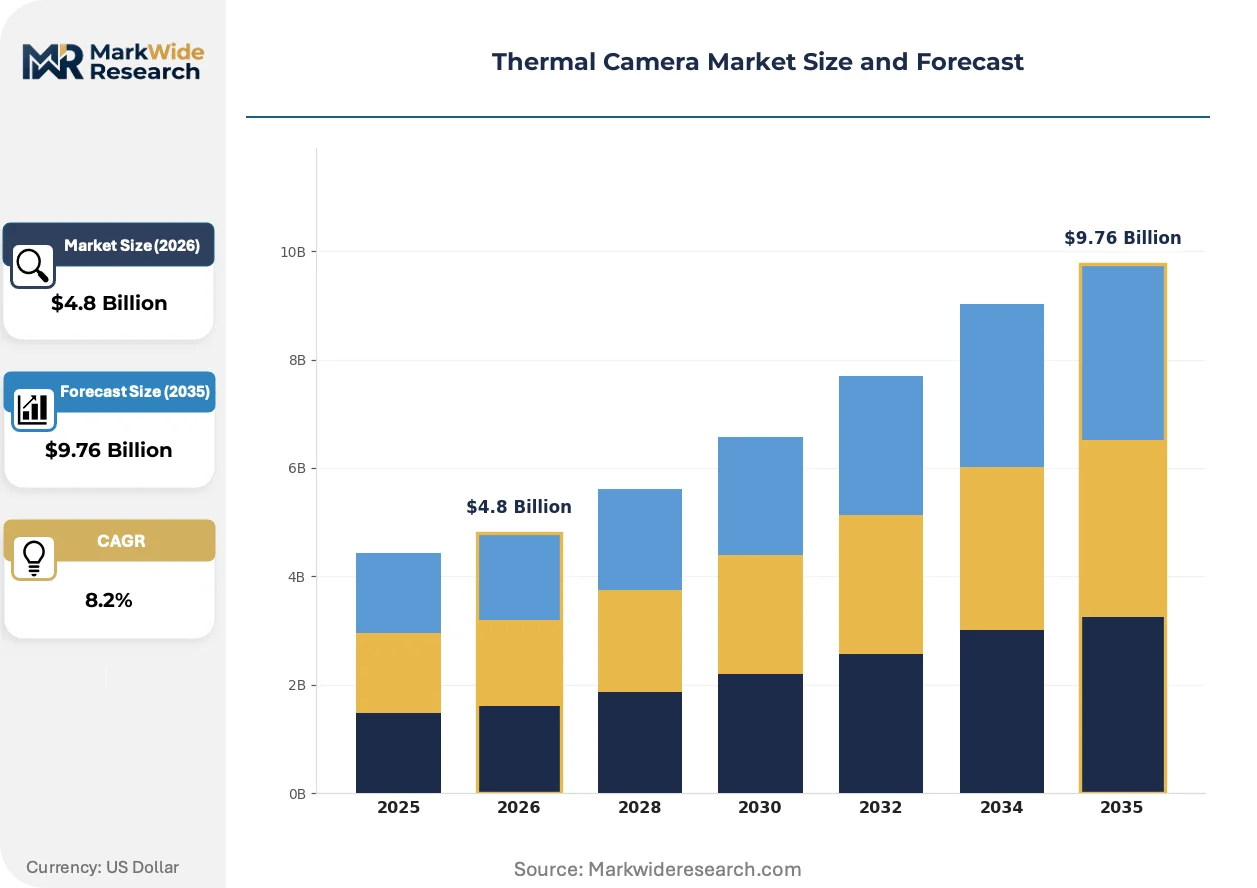
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Pan & Tilt, UAV-mounted, Smartphone-integrated Technology: Uncooled Microbolometer, Cooled Infrared, Quantum Well Infrared Photodetector, Thermopile Application: Building Inspection, Firefighting, Predictive Maintenance, Night Surveillance, Veterinary Diagnostics End User: Security Agencies, Research Laboratories, Fire Departments, Energy Providers, Agricultural Inspectors |
| Companies Covered | Seek Thermal, Hikmicro, Teledyne FLIR, Optris, Lynred, Hikvision, Raytron, Jenoptik, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Camera Market Strategic Shifts & Innovations
A fundamental shift is underway from selling standalone imaging hardware to delivering integrated data solutions. The market's evolution now hinges on software, analytics, and the ability to fuse thermal data with other sensor inputs for automated decision-making.
Uncooled microbolometer technology provides cost-effective, portable thermal detection without cryogenic cooling. Industrial maintenance and building inspection segments are rapidly adopting these smaller, more affordable sensors. This miniaturization is expanding into new form factors, enabling integration within smartphones, drones, and wearable devices for prosumer and field service use.
The European Union's Energy Performance of Buildings Directive (EPBD) is creating a non-discretionary market for thermal imaging. This regulation mandates energy efficiency assessments, making thermal inspections a standard procedure for identifying heat loss and insulation defects. The building diagnostics and HVAC inspection segments in EU member states are most directly impacted, driving procurement of handheld inspection cameras.
Buyer expectations are recalibrating around accessibility and lower system costs, driven by the unbundling of thermal cores from dedicated hardware. This disrupts the traditional model of selling high-cost, all-in-one devices by enabling smartphone-integrated modules and other low-cost peripherals. This trend is most visible in the prosumer and small business segments for electrical and home inspection.
Thermal Camera Market Segmentation
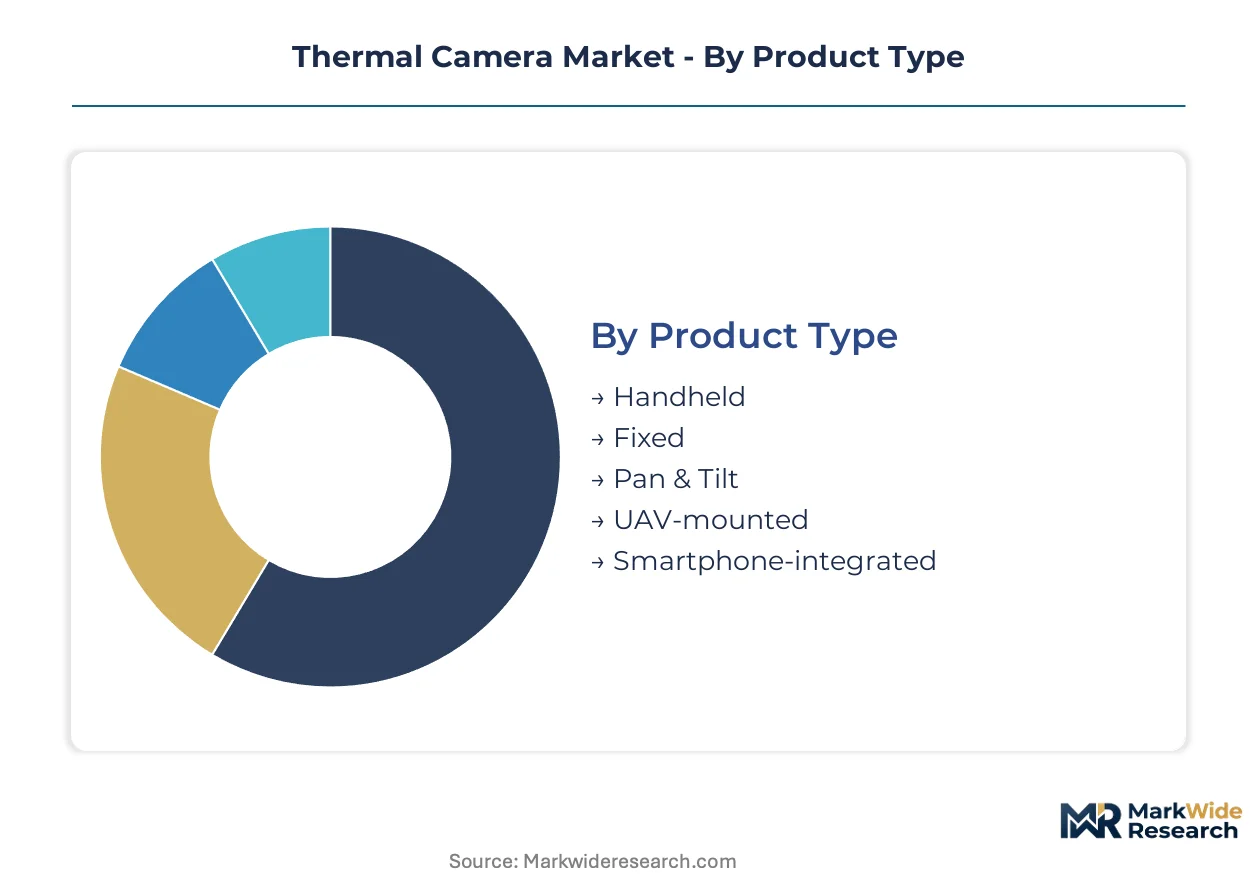
The thermal camera market's segmentation reveals distinct value propositions and user requirements across various product forms, underlying technologies, applications, and end-user groups. Understanding these divisions helps identify key growth vectors and areas of concentrated demand. Each segment addresses specific operational needs, influencing market dynamics.
Product Type:
The capital intensity of thermal camera product types varies significantly, influencing procurement cycles and market accessibility.
- Handheld:These portable devices offer flexibility for on-site inspections across industrial and commercial settings. Widespread adoption in predictive maintenance drives demand.
- Fixed:Permanently installed thermal cameras provide continuous monitoring for critical infrastructure, industrial processes, and security perimeters. They integrate with surveillance networks.
- Pan & Tilt:Featuring motorized bases, these cameras deploy in wide-area surveillance and perimeter security. Operators cover large fields of view from a single point.
- UAV-mounted:Drones equipped with thermal cameras provide aerial inspection capabilities for large-scale infrastructure, agriculture, and search and rescue.
- Smartphone-integrated:Modules that attach to or integrate with smartphones democratize thermal imaging for prosumers and small businesses. This lowers the entry barrier for basic diagnostics.
Handheld absorbs the bulk of installed capacity; Smartphone-integrated is expanding most quickly.
Technology:
The cost tier for thermal camera technologies ranges from specialized, expensive cooled systems to more affordable, mass-produced uncooled detectors.
- Uncooled Microbolometer:These sensors detect infrared without cryogenic cooling, offering cost-effectiveness, portability, and rapid startup. They dominate commercial markets like building inspection.
- Cooled Infrared:Requiring cryogenic cooling for high sensitivity and faster frame rates, these detectors are used in demanding applications. Defense and aerospace leverage superior performance.
- Quantum Well Infrared Photodetector:QWIP technology offers excellent temperature resolution and spectral tunability, primarily used in specialized scientific and military applications.
- Thermopile:Simple and low-cost, thermopile sensors measure temperature without forming a detailed image, found in entry-level consumer devices for basic detection.
Uncooled Microbolometers represent the foundational technology for most commercial cameras, while Cooled Infrared systems retain high-performance niches.
Application:
The volume of thermal camera deployments varies significantly across different applications, influencing manufacturing scale and product development priorities.
- Building Inspection:Thermal cameras identify insulation gaps, moisture intrusion, and HVAC system inefficiencies. Regulations like the EU EPBD drive demand.
- Firefighting:First responders utilize thermal imagers to locate victims, identify hot spots, and navigate smoke-filled environments. NFPA standards influence procurement.
- Predictive Maintenance:Industrial facilities employ thermal cameras to monitor machinery and electrical panels for early signs of overheating. This prevents unscheduled downtime.
- Night Surveillance:Thermal imaging provides visibility in darkness, fog, or smoke, crucial for security, border patrol, and wildlife monitoring.
- Veterinary Diagnostics:Thermal cameras assist veterinarians in detecting inflammation, injuries, and circulatory issues in animals. This non-invasive tool gains traction.
Predictive Maintenance and Building Inspection collectively drive substantial market demand, with Veterinary Diagnostics showing promise.
End User:
The maturity of thermal camera adoption differs across end-user segments, influencing market penetration rates and educational requirements.
- Security Agencies:Government and private security organizations deploy thermal cameras for perimeter defense, surveillance, and threat detection. They require reliable performance.
- Research Laboratories:Scientists and engineers use thermal cameras for material analysis, product development, and academic studies. High-precision imagers are often required.
- Fire Departments:Municipal and volunteer fire services equip first responders with thermal imagers to enhance safety and effectiveness during emergencies. These devices are critical.
- Energy Providers:Utilities and power generation companies use thermal cameras to inspect power lines, substations, and equipment for anomalies.
- Agricultural Inspectors:Professionals in agriculture utilize thermal cameras for crop health monitoring, irrigation assessment, and livestock management. This supports precision farming.
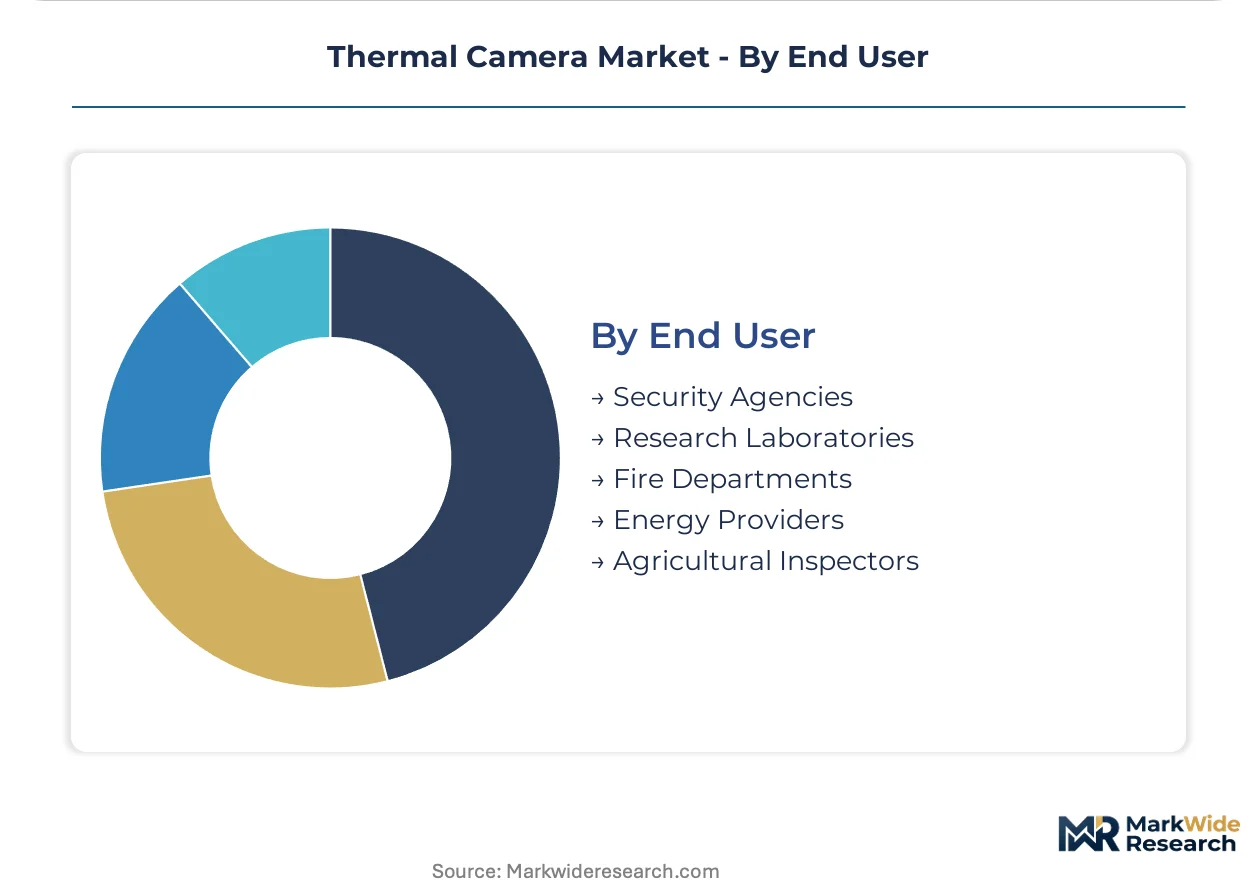
Fire Departments and Energy Providers represent established end-user bases, while Agricultural Inspectors are an emerging segment with significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The thermal camera market exhibits a clear divide between production hubs and key consumption regions. While the manufacturing of core components is concentrated, demand for integrated solutions spans diverse industrial and public safety applications across major economies. This dynamic shapes regional market development.
Germany
Industrial automation initiatives in Germany drive significant demand for thermal cameras in predictive maintenance. The European Union's Energy Performance of Buildings Directive (EPBD) further mandates thermal inspections for energy efficiency. Major manufacturing clusters in Bavaria and North Rhine-Westphalia actively integrate thermal imaging into smart factory operations.
China
Advanced manufacturing zones across China heavily adopt thermal cameras for industrial process monitoring and quality control. Government-led Industry 4.0 principles encourage the use of thermal technology to enhance operational efficiency. Key industrial parks in the Yangtze River Delta region implement thermal solutions for critical infrastructure surveillance.
United States
First responder safety and industrial asset management fuel demand for thermal imagers across the United States. National Fire Protection Association (NFPA) standards increasingly recommend thermal imagers for fire departments. Major industrial facilities in states like Texas and Pennsylvania utilize thermal cameras for electrical and machinery inspection.
Japan
Precision agriculture and advanced industrial monitoring represent key demand drivers for thermal cameras in Japan. The Ministry of Economy, Trade and Industry (METI) supports smart factory initiatives that incorporate thermal sensing. Robotics and automation hubs in the Kanto region integrate thermal vision for quality assurance and process control.
France
Building diagnostics and public safety applications generate consistent demand for thermal cameras throughout France. The European Union's Energy Performance of Buildings Directive (EPBD) mandates thermal assessments for energy audits. Urban development projects in the Île-de-France region increasingly deploy thermal imagers for infrastructure maintenance and security.
Thermal Camera Market Key Industry Players
The competitive structure tilts toward a tiered system, with established premium players alongside an expanding segment of value-driven innovators. The market accommodates specialized providers focusing on high-performance applications and those targeting accessible, prosumer-grade solutions. Strategic partnerships for technology convergence and portfolio diversification are common competitive moves. The rapid commoditization of uncooled microbolometer sensors contributes to a fragmented landscape in the entry-level segments.
Within this landscape, Teledyne FLIR, a prominent US-based entity, represents the premium segment, leveraging its deep legacy in defense and high-performance industrial systems. This company maintains a market position focused on advanced capabilities and specialized applications. Seek Thermal exemplifies innovation in the expanding consumer-grade and prosumer device categories, offering more accessible thermal imaging solutions for a broader user base. Hikmicro, a China-based competitor, occupies a strong position in the price-performance segment, particularly for handheld security and inspection products. Its offerings cater to a market demanding both capability and affordability.
| Leading Market Players |
|---|
| Seek Thermal |
| Hikmicro |
| Teledyne FLIR |
| Optris |
| Lynred |
| Hikvision |
| Raytron |
| Jenoptik |
| Fluke Corporation |
| Others |
Cost & Logistics Intelligence
A clear performance-driven bifurcation between high-end defense systems and accessible uncooled microbolometer devices shapes distinct pricing strategies and supply chain complexities for each thermal camera segment.
Pricing Analysis
Price erosion across consumer-grade and prosumer thermal cameras traces to the rapid commoditization of uncooled microbolometer sensors. The dominant pricing model remains per-unit transactional, often bundled with basic software. Price differentiation stems from quality grade and brand premium, with Teledyne FLIR commanding higher prices for advanced capabilities. Consumer and prosumer segments exhibit high price sensitivity, while defense and high-performance industrial buyers prioritize functionality over cost.
Supply Chain Analysis
Logistics and freight costs influence the final price of thermal cameras, particularly for high-value components shipped internationally. Supply concentration centers on microbolometer sensor arrays from specialized manufacturers in the United States, China, and Germany. The industry relies heavily on raw materials like germanium for optics. Single-source vulnerability for specialized microbolometer fabrication represents a structural supply chain risk. Distribution runs through direct sales channels for premium industrial and defense systems, and through broad retail and e-commerce networks for consumer products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermal camera market is supply-constrained, with the complex fabrication processes for high-resolution microbolometer sensor arrays creating a capacity bottleneck that props up pricing in premium segments. This dynamic presents both challenges and opportunities for market participants.
For Market Incumbents: Cement market leadership by investing in advanced sensor fusion R&D, integrating thermal data with AI for enhanced analytics. Deepen channel partnerships for industrial solutions, leveraging established relationships with maintenance and security integrators. This defends against the commoditization of entry-level devices and reinforces brand equity. Focus on specialized certification investments, such as meeting stringent NFPA standards, to maintain a premium market position.
For New Entrants and Emerging Players: A significant price-point gap exists between high-end industrial systems and basic consumer devices, creating opportunities for value-focused solutions. Target white spaces like precision agriculture in the Americas and infrastructure development in Southeast Asia. The most penetrable segment lies within smartphone-integrated modules for prosumers seeking basic diagnostics. A subscription-based analytics platform could differentiate offerings by delivering actionable insights beyond raw imagery.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated component manufacturers given the ongoing miniaturization trend and expanding application base. The market offers significant growth opportunities over the next decade, driven by regulatory mandates and industrial automation. Target specialized software analytics firms capable of fusing thermal data with other sensor inputs. Increased adoption of thermal imaging in autonomous systems, such as drones and vehicles, will serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Microbolometer Fabrication | Increases supply of core components, meeting growing demand from diverse applications. |
| AI-Powered Thermal Data Analytics Development | Delivers actionable insights, moving beyond raw imagery for industrial and security users. |
| Strategic Partnerships for Sensor Fusion | Integrates thermal data with visual and acoustic inputs for comprehensive diagnostic solutions. |
| Geographic Expansion into Southeast Asia | Captures new demand from rapid urbanization and infrastructure projects in emerging markets. |
| Certification for Building Energy Audits | Aligns products with EU EPBD mandates, securing sustained demand in building diagnostics. |
Research Approach
European Union Energy Performance of Buildings Directive (EPBD) reports, National Fire Protection Association (NFPA) standards documents, and company annual reports formed the secondary backbone of this study. Primary interviews with maintenance managers, fire chiefs, building inspectors, and thermal engineers provided crucial qualitative insights. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
A dual analytical lens, utilizing both bottom-up market summation and top-down validation, was applied across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical data and projected growth drivers. Key industry-specific forecast inputs included uncooled microbolometer production capacity and regulatory compliance rates for thermal inspections.
Inputs from public company filings and regulatory body publications were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding export control stability and material supply chain continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Underwater Camera Market
Imaging
Light Field Market
Imaging
Camera Lens Market
Imaging
Microwave Imaging Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Hyper Spectral Imaging System Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Europe Image Sensors Market
Imaging
Widefield Imaging Systems Market
Imaging
Asia Pacific IP Camera Market
Imaging
Holographic Imaging Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Holotomographic Imaging Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Photography Ring Flash Market