
 US Near Infrared Imaging Market | 2026-2036
US Near Infrared Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Near Infrared Imaging Market Analytics
Hospital surgical departments is rotating toward intraoperative near-infrared fluorescence systems while research institutions cede relative procurement share. Stryker dominates capital equipment placements across academic medical centers. Carl Zeiss Meditec differentiates through integrated microscopy-fluorescence platforms for neurosurgical navigation. Medtronic anchors recurring revenue streams via proprietary contrast agent and device ecosystem lock-in.
Near infrared imaging captures electromagnetic radiation in the 700–1000 nanometer wavelength band, detecting tissue oxygenation, blood flow, and targeted fluorophore distribution through differential photon absorption and scattering. The technology serves real-time surgical visualization and non-destructive quality inspection across biomedical and industrial settings. Continuous wave systems occupy the largest installed base due to simpler hardware architecture and lower per-unit cost. Frequency-domain technology captures the fastest-growing segment as quantitative oxygen saturation mapping gains traction in oncology resections. Devices command concentrated margin pools where proprietary optical path designs and detector arrays create switching costs.
FDA 510(k) premarket notification requirements govern device clearance while the Centers for Medicare and Medicaid Services determines reimbursement codes that dictate hospital purchasing cycles. The National Institutes of Health funds translational research that bridges academic fluorescence probe development to commercial clinical adoption. Stakeholders must monitor CMS technology add-on payment decisions and parallel FDA contrast agent labeling expansions to anticipate demand inflection points for integrated system-consumable platforms.
Market Dynamics
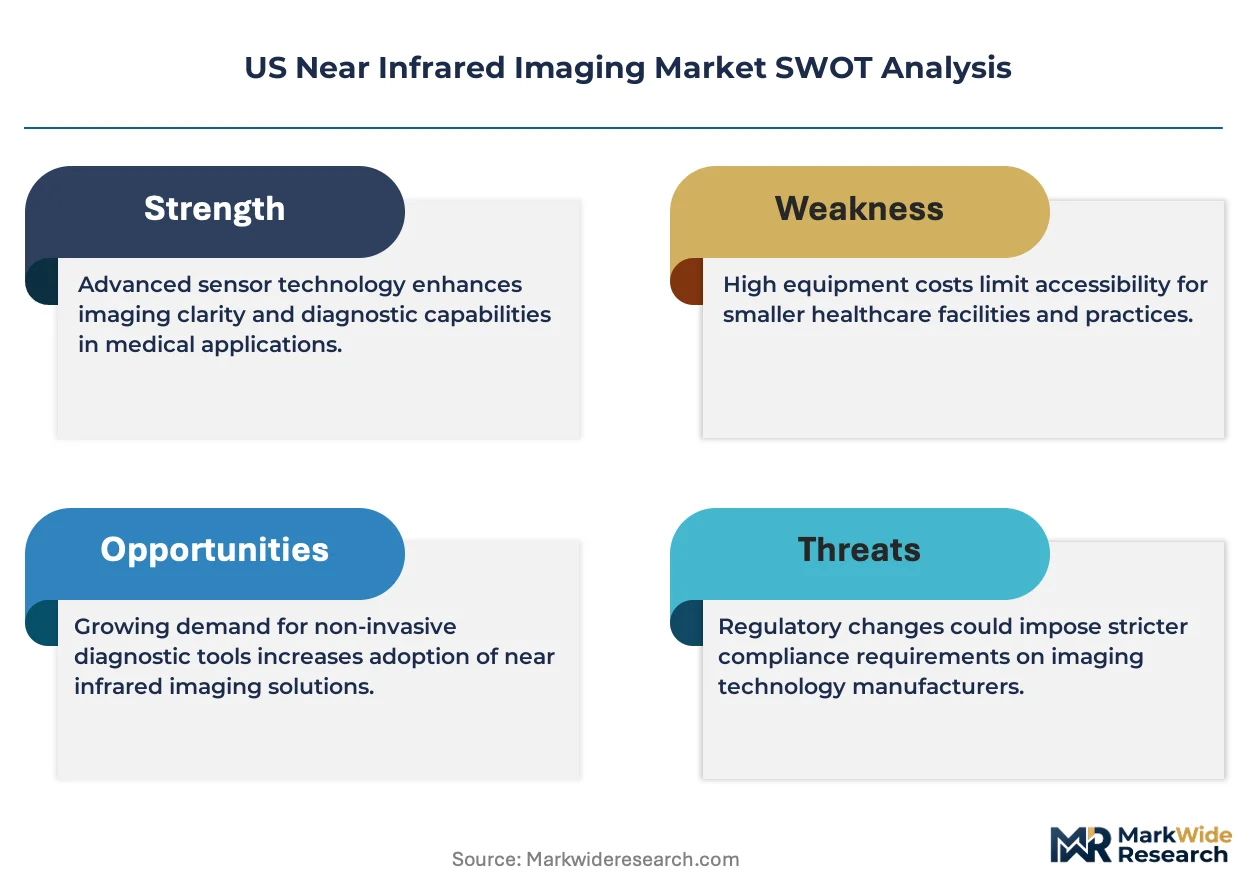
The US Near Infrared Imaging Market pivots on FDA 510(k) clearance velocity for optical imaging agents, which compresses commercialization timelines and concentrates competitive advantage among sponsors with established regulatory infrastructure. Hospital capital committees now weight fluorescence-guided surgery platforms against robotic alternatives, reshaping procurement criteria.
Growth Catalysts
- CMS Technology Add-On Payments:Reimbursement codes for intraoperative fluorescence visualization accelerate hospital adoption cycles in oncology and cardiovascular service lines.
- Massachusetts Biomedical Clusters:Concentrated translational research infrastructure bridges academic probe development to commercial clinical trials, shortening time-to-market for novel contrast agents.
- Frequency-Domain Systems:Quantitative oxygen saturation mapping capabilities expand addressable procedures beyond qualitative perfusion assessment into complex resection margins.
Market Restraints
- Indocyanine Green Supply Concentration:Single-source API dependencies for the dominant NIR fluorophore create vulnerability to pharmaceutical manufacturing disruptions.
- FDA Contrast Agent Labeling:Narrow approved indications restrict off-label clinical expansion and require costly supplemental trials for procedural extensions.
- Capital Equipment Replacement Cycles:Seven-to-ten-year depreciation schedules for installed continuous-wave systems delay upgrade revenue for advanced quantitative platforms.
Strategic Opportunities
- Texas Medical Center Networks:Underpenetrated ambulatory surgical centers in Houston and Dallas-Fort Worth corridors present greenfield installation potential outside established Northeast strongholds.
- Artificial Intelligence Integration:Real-time perfusion algorithm overlays on raw NIR data streams create differentiated software-recurring revenue models independent of hardware commoditization.
- Veterans Health Administration Procurement:Centralized federal purchasing for twenty-two integrated networks offers volume contracting pathways distinct from fragmented private hospital negotiations.
Industry Challenges
- Biomedical Optics Talent Pipeline:Scarcity of engineers with simultaneous expertise in photon transport modeling and clinical workflow design constrains R&D velocity.
- Legacy PACS Integration:Proprietary image formats from competing NIR platforms resist seamless incorporation into hospital radiology archiving systems, requiring costly middleware development.
- Interoperability Certification Delays:Voluntary IEEE 11073 standards compliance extends product launch timelines without guaranteeing procurement preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Near Infrared Imaging Market |
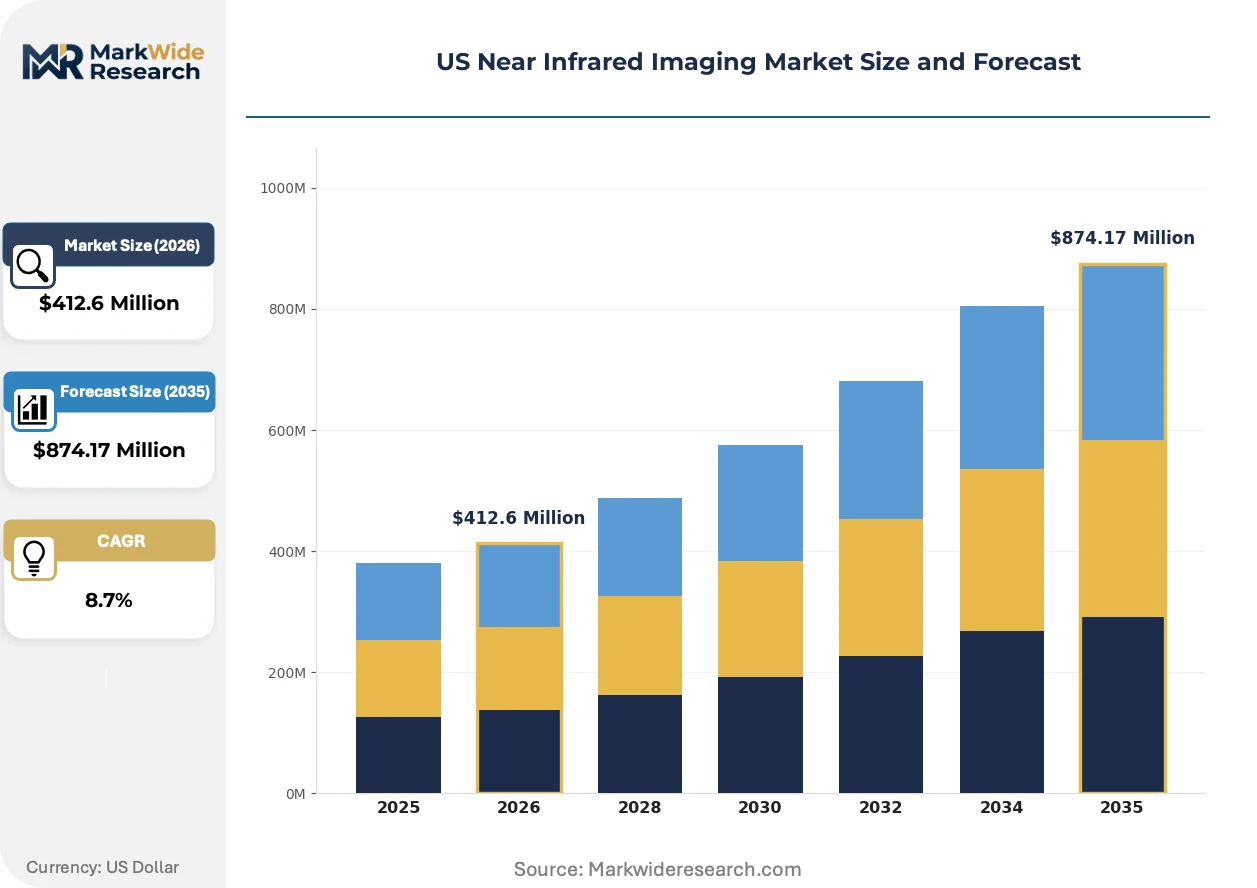
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Software, Accessories, Systems End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Technology: Time-Domain, Frequency-Domain, Continuous Wave, Optical Coherence Application: Biomedical, Industrial, Environmental, Food Safety |
| Companies Covered | Stryker, PerkinElmer, Li-Cor, Leica Microsystems, Intuitive Surgical, Carl Zeiss Meditec, Olympus, Hamamatsu Photonics, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Near Infrared Imaging Market Evolving Landscape
Fluorescence-guided surgery platforms are converging with artificial intelligence and miniature sensor architectures, compressing form factors while expanding quantitative capabilities. These shifts reshape competitive differentiation beyond raw optical performance toward integrated clinical decision support.
Chip-scale NIR detector arrays are miniaturizing from benchtop spectrometers to catheter-integrable footprints. Interventional cardiologists at Cleveland Clinic and Mayo Clinic Rochester are piloting these micro-systems for intravascular plaque characterization. The technology is miniaturizing capital requirements for point-of-care deployment, enabling ambulatory clinic adoption previously blocked by facility infrastructure constraints.
FDA's 2023 guidance on fluorescence imaging device-cleared indications for specific fluorophore combinations tightens labeling requirements for combination product sponsors. Device manufacturers must now synchronize 510(k) submissions with contrast agent label expansions, creating coordinated regulatory strategies. Academic medical centers in the Northeast corridor are prioritizing platforms with pre-aligned FDA clearances to minimize procurement legal review.
Hospital value analysis committees now unbundle capital equipment from consumable contracts, forcing separate negotiations for NIR systems and proprietary contrast agents. This bifurcation disrupts historical ecosystem lock-in models and advantages standalone device vendors with open-agent compatibility. The pattern is most visible in California health systems where Kaiser Permanente and Stanford Health Care have standardized procurement evaluation rubrics around total cost-of-ownership rather than bundled pricing.
US Near Infrared Imaging Market Segmentation
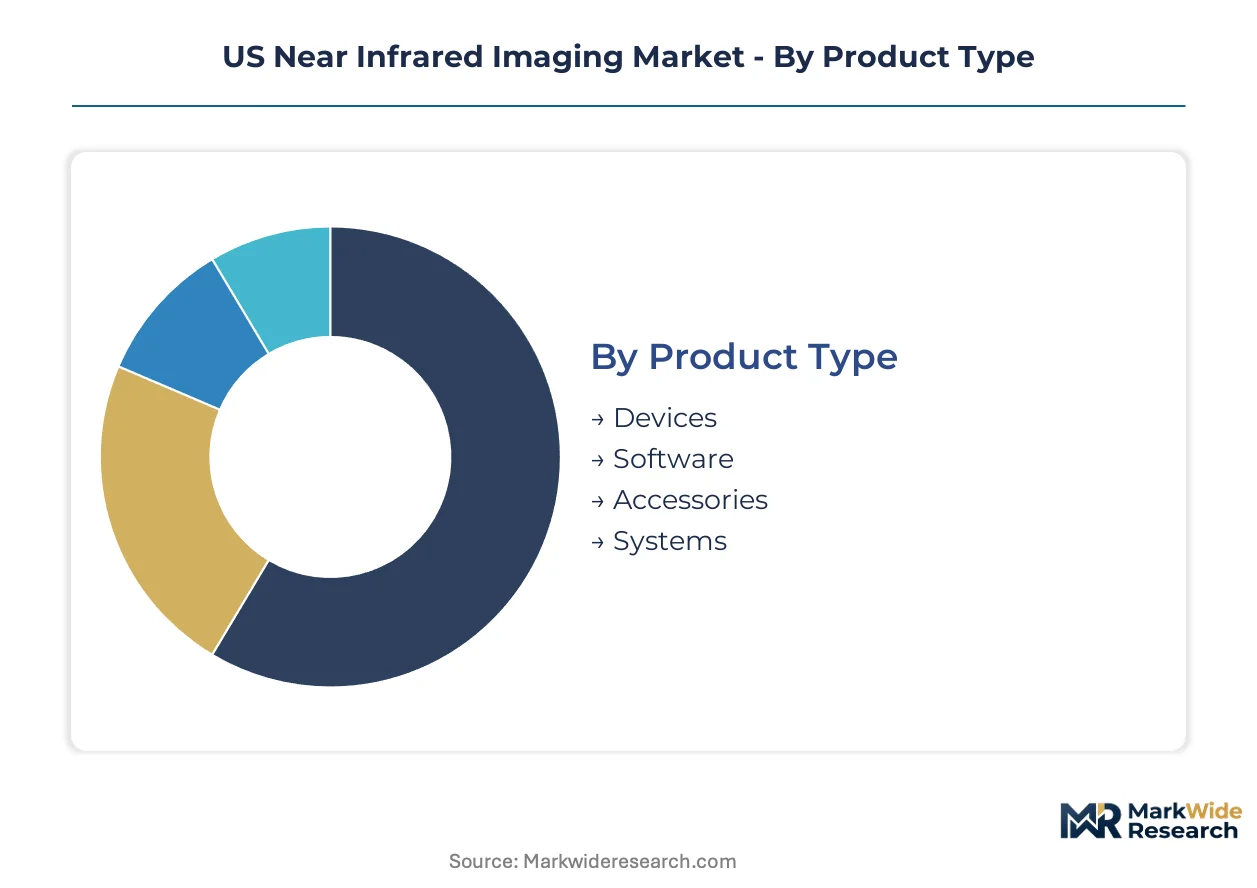
Near infrared imaging market segmentation reveals distinct procurement patterns across product tiers and user categories. Hospital capital committees evaluate technology platforms against reimbursement pathways while research institutions prioritize quantitative capabilities over installed cost.
Product Type:
Domestic manufacturing concentrates capital equipment assembly in Massachusetts and California biomedical corridors, while software development distributes across research triangle hubs.
- Devices:Hardware encompasses excitation light sources, detector arrays, and optical path assemblies. Massachusetts General Hospital and Memorial Sloan Kettering anchor replacement demand for integrated surgical platforms. FDA 510(k) clearance velocity dictates commercialization timelines for new optical configurations.
- Systems:Fully integrated fluorescence-guided surgery platforms combine hardware, software, and proprietary agent compatibility. Texas Medical Center networks and Pacific Northwest hospital systems drive greenfield installations outside established Northeast procurement clusters.
- Software:Real-time perfusion algorithms and image processing modules enable quantitative oxygen saturation mapping.
- Accessories:Disposable optical components and calibration standards support maintenance revenue streams.
Devices command the established base. The steepest expansion runs through Systems.
End User:
Procurement authority concentrates in hospital value analysis committees, while research institutions cede relative share to clinical translation priorities.
- Hospitals:Surgical departments in academic medical centers and community hospital networks deploy intraoperative fluorescence guidance for oncology and cardiovascular service lines. CMS technology add-on payments accelerate adoption cycles in designated procedure codes.
- Research Institutions:NIH-funded translational programs bridge academic probe development to commercial clinical trials. Massachusetts biomedical clusters and Stanford University anchor fluorescence imaging research infrastructure.
- Clinics:Ambulatory surgical centers in underpenetrated corridors present installation growth potential.
- Pharmaceutical Companies:Contrast agent sponsors coordinate device-fluorophore combination product strategies.
Hospitals anchor volume procurement. Research Institutions deliver the fastest technology translation pipelines.
Technology:
Cost tier stratification separates premium quantitative platforms from accessible continuous-wave alternatives.
- Continuous Wave:Simplified hardware architecture with lower per-unit cost dominates installed base. Community hospitals and cost-constrained systems prioritize these systems for qualitative perfusion assessment.
- Frequency-Domain:Quantitative oxygen saturation mapping captures complex resection margin applications. Academic medical centers in the Northeast corridor and Cleveland Clinic anchor demand for advanced oncologic navigation.
- Time-Domain:Temporal photon distribution analysis enables deep tissue characterization.
- Optical Coherence:Cross-sectional microstructural imaging integrates with fluorescence overlays.
Continuous Wave systems retain the largest installed footprint. Frequency-Domain platforms gain share fastest in high-complexity surgical centers.
Application:
Biomedical demand concentrates in FDA-regulated clinical environments, while industrial adoption spreads across non-destructive quality inspection.
- Biomedical:Real-time surgical visualization for tissue perfusion, lymphatic mapping, and tumor margin delineation. FDA-cleared indications govern fluorophore-device combinations in hospital operating suites.
- Industrial:Non-destructive quality inspection for semiconductor and pharmaceutical manufacturing. California and Texas industrial corridors anchor deployment for process analytical technology.
- Environmental:Remote sensing and contaminant detection applications.
- Food Safety:Quality control and authenticity verification in processing facilities.
Biomedical applications dominate revenue concentration. Industrial deployment expands most quickly outside regulated clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component manufacturers supply precision lens assemblies to Massachusetts biomedical clusters, while Japanese photonics firms export detector arrays to Texas Medical Center procurement networks.
Greater Boston
Massachusetts General Hospital and Dana-Farber Cancer Institute drive demand for integrated surgical navigation platforms. NIH translational research grants accelerate fluorescence probe development from academic labs to commercial trials. The Route 128 corridor concentrates device assembly operations alongside venture-backed spectroscopy startups.
New York Metropolitan Area
Memorial Sloan Kettering and NYU Langone anchor oncology service line expansion with intraoperative fluorescence guidance. New York State Department of Health certificate-of-need regulations govern capital equipment procurement in consolidated hospital systems. The Hudson Valley biotech corridor houses contrast agent formulation facilities serving Northeast surgical networks.
Texas Medical Center
MD Anderson Cancer Center and Houston Methodist Hospital pilot frequency-domain systems for complex resection margin assessment. Texas lacks certificate-of-need restrictions, enabling faster ambulatory surgical center equipment deployment. The Dallas-Fort Worth corridor presents greenfield installation potential outside established Northeast procurement clusters.
Cleveland Clinic Corridor
Cleveland Clinic Rochester and University Hospitals drive adoption of quantitative oxygen saturation mapping in cardiovascular surgery. Ohio Medicaid reimbursement policies influence hospital value analysis committee purchasing timelines. The Cleveland biomedical corridor anchors industrial non-destructive testing applications alongside clinical deployment.
Pacific Northwest
University of Washington Medical Center and Oregon Health & Science University prioritize open-agent compatible platforms over proprietary ecosystems. Washington State health technology assessment programs evaluate cost-effectiveness of fluorescence-guided surgery modalities. The Seattle-Tacoma metro area concentrates software development for real-time perfusion algorithms.
US Near Infrared Imaging Market Competitive Landscape
Listed leaders compete with private specialists across regulatory infrastructure and installed base maintenance. The market structure concentrates around three to five dominant capital equipment sponsors with established FDA 510(k) clearance pathways, while mid-tier specialists fragment across software modules and disposable accessories. Strategic archetypes include integrated platform vendors with proprietary agent lock-in, open-system device manufacturers, and standalone software analytics providers. Competitive moves center on coordinated regulatory submissions for device-fluorophore combinations and unbundled procurement negotiations separating hardware from consumable contracts.
Among diversified medical technology conglomerates, Stryker and Medtronic exemplify platform-integrated archetypes with recurring revenue ecosystems, while Carl Zeiss Meditec represents precision optics specialists extending from microscopy into surgical navigation. These three anchors occupy distinct positioning vectors based on heritage capabilities and customer relationship depth across academic medical centers.
| Leading Market Players |
|---|
| Stryker |
| PerkinElmer |
| Li-Cor |
| Leica Microsystems |
| Intuitive Surgical |
| Carl Zeiss Meditec |
| Olympus |
| Hamamatsu Photonics |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Capital equipment utilization rates above eighty percent at Massachusetts and California assembly facilities create substantial scale economies that compress per-unit fixed costs and establish pricing floors for frequency-domain systems. These concentrated manufacturing footprints simultaneously concentrate supplier bargaining power and limit price competition among detector array and optical component vendors.
Pricing Analysis
Next-generation frequency-domain platforms command three-to-fourfold premiums over continuous-wave installed bases, while prior-generation systems face accelerating depreciation-driven price erosion in secondary markets. The dominant pricing structure stratifies across premium quantitative platforms, standard integrated surgical systems, and economy continuous-wave alternatives. Price differentiation rests on FDA 510(k) clearance tier and proprietary agent compatibility certification. Cost compression in the standard tier intensifies as hospital value analysis committees unbundle hardware from consumable contracts. Community hospital networks exhibit highest price sensitivity; academic medical centers prioritize quantitative capability over capital cost.
Supply Chain Analysis
Germany and Japan anchor precision optical component manufacturing, supplying lens assemblies and photodetector arrays to US device integrators. Domestic assembly draws from indocyanine green API sourced through concentrated pharmaceutical suppliers, silicon-based sensor substrates, and rare-earth-doped laser excitation sources. Single-source fluorophore dependencies create vulnerability to pharmaceutical manufacturing disruptions. Distribution runs through direct hospital capital equipment procurement and GPO-negotiated contracts for disposable accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through synchronized FDA 510(k) device clearances and contrast agent label expansions constructs formidable defensive moats for established sponsors. Switching costs from proprietary image formats and surgeon training investments further harden incumbent positions.
For Market Incumbents: Fortify ecosystem lock-in through coordinated regulatory submissions for device-fluorophore combinations before FDA's tightened labeling guidance takes full effect. Expand backward integration into optical component manufacturing to offset German and Japanese supplier pricing power. Prioritize software module development for real-time perfusion algorithms to capture recurring revenue independent of hardware replacement cycles. The unbundling of capital and consumable contracts by hospital value analysis committees threatens historical bundled pricing power. For New Entrants and Emerging Players: Anchor in Texas Medical Center ambulatory surgical centers and Dallas-Fort Worth corridors where certificate-of-need absence enables faster equipment deployment than Northeast procurement clusters. Target open-agent compatible platform development to exploit Kaiser Permanente and Stanford Health Care procurement standardization around total cost-of-ownership evaluation rubrics. Pursue Veterans Health Administration centralized federal contracting as a volume pathway distinct from fragmented private hospital negotiations. For Investors and Strategic Acquirers: Standalone software analytics providers with FDA-cleared perfusion algorithms represent priority acquisition archetypes as hardware commoditization accelerates. Long-term viability in this market hinges on regulatory infrastructure depth and installed base maintenance capabilities rather than optical performance differentiation alone. Monitor CMS technology add-on payment decisions for fluorescence-guided surgery procedure codes as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Synchronized Submission | Aligns device 510(k) clearance with contrast agent label expansion to minimize procurement legal review. |
| Software Companion Development | Enables recurring revenue from real-time perfusion algorithms independent of hardware commoditization. |
| Hospital System Partnership | Secures preferred vendor status with Texas Medical Center networks outside established Northeast strongholds. |
| Reimbursement Strategy | Positions platforms for CMS technology add-on payment codes in oncology and cardiovascular service lines. |
| Backward Integration | Captures optical component manufacturing to reduce dependency on German lens assembly suppliers. |
Research Methodology
A spread of perspectives from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at contrast agent sponsors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, CMS reimbursement coding decisions, NIH translational research grant disclosures, and hospital procurement contract filings. Bottom-up triangulation across equipment installation records and top-down reconciliation against CMS technology add-on payment claims established volume and value estimates.
Segmentation dimensions modeled span product type, end user category, technology tier, and application vertical across the projection horizon. CAGRs derived from equipment replacement cycle analysis, fluorophore consumption trajectories, and procedure volume expansion in FDA-cleared indications. Industry-specific forecast inputs incorporated CMS reimbursement pathway decisions and synchronized regulatory submission timelines for device-fluorophore combinations.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance velocity and continued CMS technology add-on payment support; material deviation in either regulatory lever would warrant model refresh. Specific risk factors include indocyanine green supply disruptions, hospital capital committee preference shifts toward robotic alternatives, and IEEE 11073 interoperability certification delays. Recalibration cycles align with material shifts in CMS reimbursement decisions and FDA contrast agent labeling expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
EUV Mask Inspection System Market
Imaging
Photography Equipment Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Weatherproof Camera Market
Imaging
Light Field Market
Imaging
Biophotonics Market
Imaging
X Ray Tubes Market
Imaging
Handheld Retinal Scanners Market
Imaging
Instaprint Camera Market
Imaging
Global 3D Camera Market
Imaging
Handheld Imager Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Digital Movie Cameras Market
Imaging
Underwater Camera Market
Imaging
Global Camera Module Market
Imaging
In Vivo Imaging Systems Market