
 Capacitive Proximity Sensor Market | 2026-2036
Capacitive Proximity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Proximity Sensor Market Outlook
Automotive manufacturing is rebalancing toward electric vehicle platforms and battery assembly, pulling capacitive proximity sensors into weld monitoring and parts detection stations. Pepperl + Fuchs GmbH anchors its position through ruggedized sensor housings designed for high-temperature automotive environments. Sick AG differentiates via laser-calibrated capacitive arrays that compete on precision in semiconductor wafer handling. Texas Instruments Incorporated leverages integrated signal conditioning ICs that reduce external component counts for sensor OEMs.
A capacitive proximity sensor detects metallic and non-metallic objects through changes in electrostatic capacitance between a sensing electrode and a target, typically operating at switching frequencies from 10 Hz to 5 kHz with sensing distances ranging from 1 mm to 40 mm depending on electrode geometry and dielectric properties. The device serves primarily as a contactless position switch in automated machinery where mechanical wear or contamination would degrade conventional limit switches. Non-contact sensors dominate installed base volumes across industrial automation lines where dust, oil, and vibration would compromise optical alternatives. Analog sensors capture expanding margin pools in robotics end-effector feedback systems requiring continuous position data rather than binary switching. Digital sensors sustain growth in consumer electronics touch interfaces where binary on-off detection meets cost and power constraints.
IEC 60947-5-2 governs low-voltage switchgear performance requirements for proximity sensors in European industrial installations, while the EU Machinery Directive mandates functional safety integration that pushes sensor vendors toward redundant output architectures. OSHA lockout-tagout regulations in the United States shape demand for fail-safe sensor configurations in heavy manufacturing environments. China's GB/T 14048.10 standard aligns domestic production with international electromagnetic compatibility benchmarks, easing export pathways for local manufacturers. Stakeholders must monitor how functional safety certification tiers fragment procurement specifications across automotive, food processing, and pharmaceutical end users.
Market Dynamics
Automotive electrification is restructuring capacitive proximity sensor deployment, pulling sensing architectures toward battery cell inspection and thermal runaway detection stations where legacy inductive sensors fail on non-metallic targets.
Growth Catalysts
- IEC 60947-5-2 compliance mandates:European industrial installations now require certified proximity sensors with redundant output architectures, forcing upgrade cycles across Germany's automotive stamping plants.
- Semiconductor wafer handling precision:Laser-calibrated capacitive arrays capture expanding share in cleanroom robotics where sub-micron positioning tolerance eliminates mechanical contact.
- China's GB/T 14048.10 alignment:Domestic sensor manufacturers gain export pathway equivalence, concentrating new production capacity in Shenzhen and Suzhou automation clusters.
Market Restraints
- Electrode material cost volatility:Copper and silver-palladium alloy prices for sensing electrodes fluctuate with commodity markets, compressing margin on economy-grade sensors.
- Supply concentration in German precision optics:Laser calibration equipment for high-end capacitive arrays depends on a narrow supplier base in Baden-Württemberg.
- Inductive sensor substitution in pure metal detection:Mature inductive technologies retain cost advantage for ferrous-target applications, capping capacitive penetration in traditional metalworking.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for electronics manufacturing draw sensor assembly investments toward Pune and Chennai industrial corridors.
- Food-grade capacitive sensing:Washdown-rated sensors with IP69K sealing capture white space in dairy and beverage packaging where optical contamination risks dominate.
- IO-Link protocol convergence:Unified digital interfaces enable predictive maintenance integration, opening aftermarket service revenue streams for sensor OEMs.
Industry Challenges
- Functional safety certification timelines:SIL 2 and SIL 3 validation for automotive battery assembly lines extends product launch cycles by 8-14 months.
- Legacy PLC integration complexity:Analog voltage-output capacitive sensors require signal conditioning retrofit kits to interface with 1990s-era Allen-Bradley and Siemens controllers.
- Electromagnetic compatibility testing bottlenecks:Multi-frequency interference validation for weld-field immunity strains third-party lab capacity in Detroit and Stuttgart.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Proximity Sensor Market |
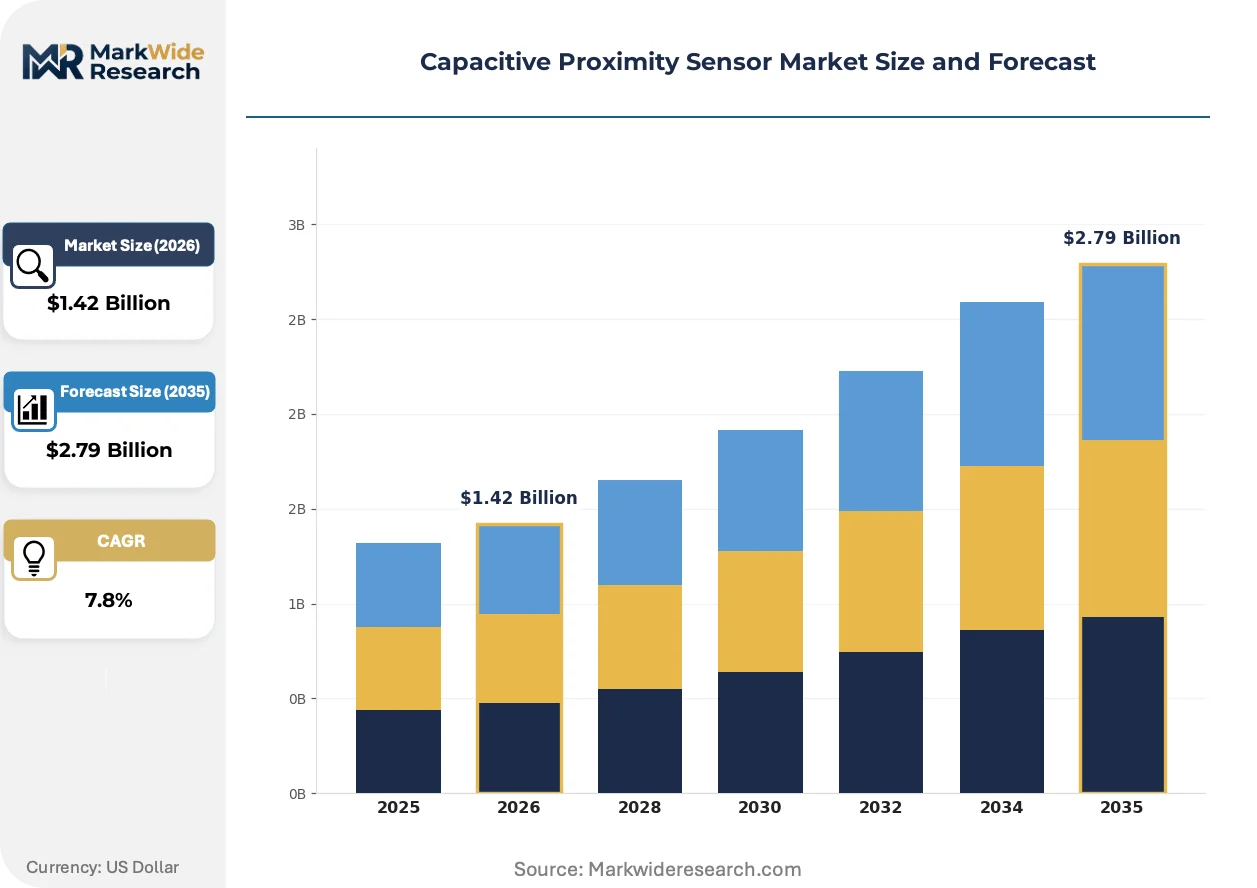
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Contact Sensors, Analog Sensors, Digital Sensors, Dual Output Sensors Application: Industrial Automation, Robotics, Consumer Electronics, Smart Home Devices Technology: Radio Frequency, Microelectromechanical Systems, Optical Sensors, Capacitive Technology End User: Manufacturers, Distributors, Retailers, Installers |
| Companies Covered | Pepperl + Fuchs GmbH, Sick AG, Rockwell Automation Inc., NXP Semiconductors, Texas Instruments Incorporated, Omron Corporation, STMicroelectronics, Renesas Electronics Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Proximity Sensor Market Strategic Shifts
Capacitive proximity sensing is bifurcating toward commodity digital switches and high-value analog feedback systems, with the boundary between these tiers hardening around signal processing sophistication and calibration protocol.
Self-calibrating electrode geometries with embedded temperature compensation are rewriting performance benchmarks in automotive paint shop applications. BMW and Volkswagen assembly plants in Munich and Wolfsburg deploy these sensors for wet-film thickness proximity detection. The technology is compressing commissioning time from hours to minutes while eliminating manual sensitivity adjustments.
REACH restrictions on perfluorinated compounds are forcing reformulation of dielectric coatings for high-humidity industrial environments. Sensor vendors in the EU now qualify ceramic-based and parylene-C alternatives for food processing and pharmaceutical cleanrooms. German manufacturers bear the heaviest compliance burden, with coating validation cycles extending procurement lead times.
Consolidated vendor-managed inventory programs are displacing spot purchasing in tier-one automotive supply chains. Bosch and Continental now mandate blanket-order agreements with quarterly consumption true-ups for proximity sensor procurement. This concentration is most visible in Stuttgart's supplier park ecosystem, where sensor OEMs maintain consignment stock at tier-two integrator facilities.
Capacitive Proximity Sensor Market Segmentation
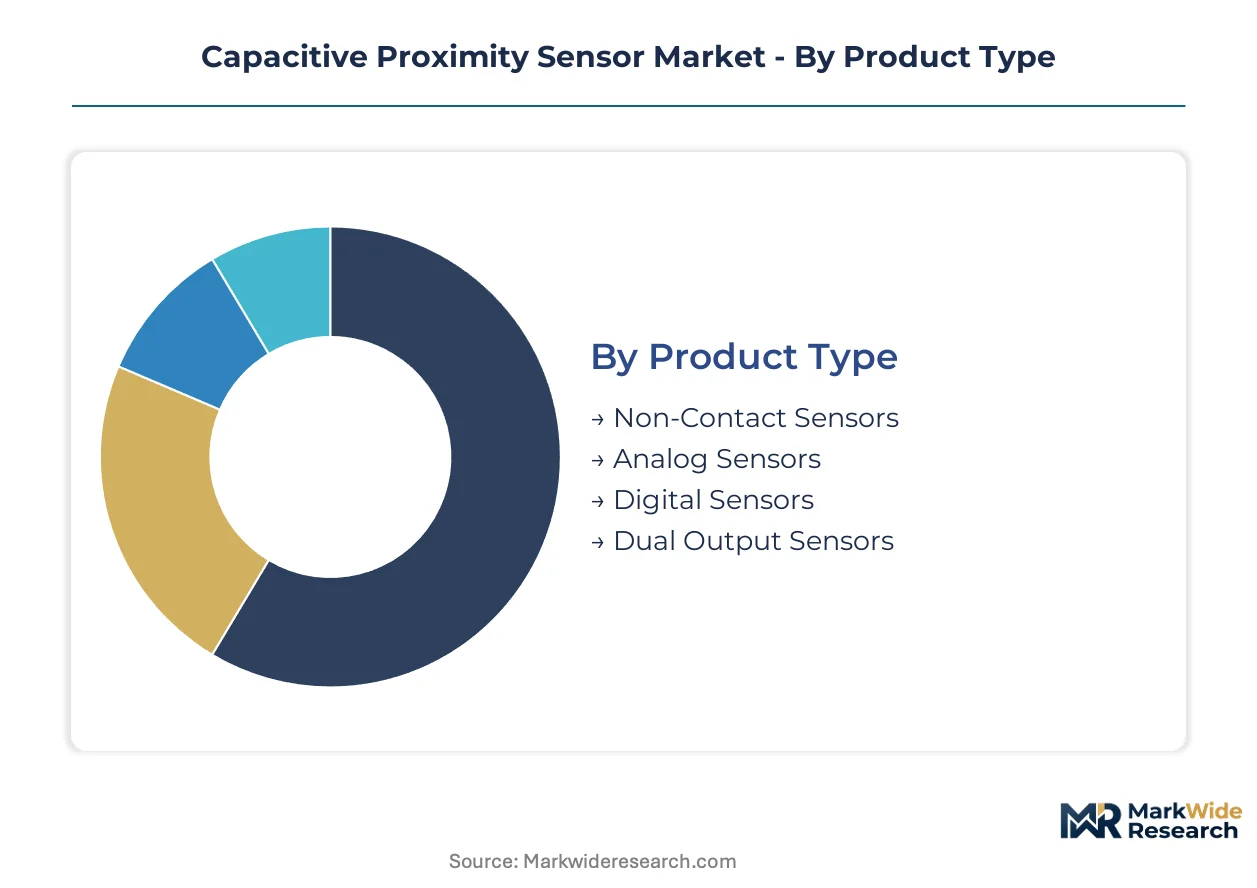
Capacitive proximity sensor procurement fragments across technical architectures, deployment environments, and channel structures. Certification requirements from IEC, OSHA, and GB/T standards reshape competitive positioning within each segment tier.
Product Type:
IEC 60947-5-2 compliance burdens concentrate on dual output and analog variants where redundant architectures and SIL ratings extend validation timelines. Non-contact and digital sensors face lighter certification loads in consumer-facing applications.
- Non-Contact Sensors:Electrode-based detection systems operate at 10 Hz to 5 kHz switching frequencies with sensing distances from 1 mm to 40 mm. Automotive assembly lines in Stuttgart and Wolfsburg deploy these for weld monitoring and parts detection where mechanical wear would degrade conventional limit switches. IEC 60947-5-2 certification anchors procurement specifications for European industrial installations.
- Analog Sensors:Continuous voltage or current output devices capture position data for robotics end-effector feedback systems. Semiconductor wafer handling facilities in Dresden and Hsinchu require laser-calibrated arrays with sub-micron positioning tolerance. Signal conditioning complexity extends product development cycles by 8-14 months for automotive battery assembly applications.
- Digital Sensors:Binary on-off switching devices dominate consumer electronics touch interfaces where cost and power constraints override precision requirements.
- Dual Output Sensors:Redundant-channel architectures satisfy EU Machinery Directive functional safety mandates for fail-critical industrial machinery.
Leading the category by volume: Non-Contact Sensors. Expanding most quickly: Analog Sensors.
Application:
Cost tier stratification separates premium-positioned robotics and semiconductor applications from high-volume consumer electronics deployments. Margin pools concentrate where precision specifications exclude commodity competition.
- Industrial Automation:Dust, oil, and vibration-resistant sensors replace optical alternatives in stamping plants and packaging lines. Germany's automotive supplier parks mandate vendor-managed inventory programs with quarterly consumption true-ups. OSHA lockout-tagout regulations in Michigan and Ohio shape demand for fail-safe configurations.
- Robotics:End-effector feedback systems require continuous position data rather than binary switching. Cleanroom robotics in semiconductor fabrication facilities drive specification toward laser-calibrated capacitive arrays.
- Consumer Electronics:Touch interfaces and proximity detection in smartphones and wearables prioritize unit cost minimization over environmental ruggedization.
- Smart Home Devices:Occupancy sensing and gesture recognition applications expand addressable volume through residential construction integration.
Volume concentration: Industrial Automation. Steepest expansion trajectory: Robotics.
Technology:
Supply concentration in German precision optics and Chinese MEMS foundries determines competitive access to calibration equipment and miniaturized electrode geometries.
- Radio Frequency:High-frequency oscillation circuits detect metallic and non-metallic targets through dielectric property changes. Weld-field immunity validation strains third-party lab capacity in Detroit and Stuttgart.
- Microelectromechanical Systems:Silicon-based electrode miniaturization enables compact form factors for consumer electronics integration. Shenzhen and Suzhou automation clusters concentrate MEMS production capacity.
- Optical Sensors:Competing detection modality faces contamination vulnerability in industrial environments where capacitive alternatives gain preference.
- Capacitive Technology:Core electrostatic detection principle spans all product architectures with electrode geometry and dielectric coating variations.
Dominant by installed base: Capacitive Technology. Gaining share fastest: Microelectromechanical Systems.
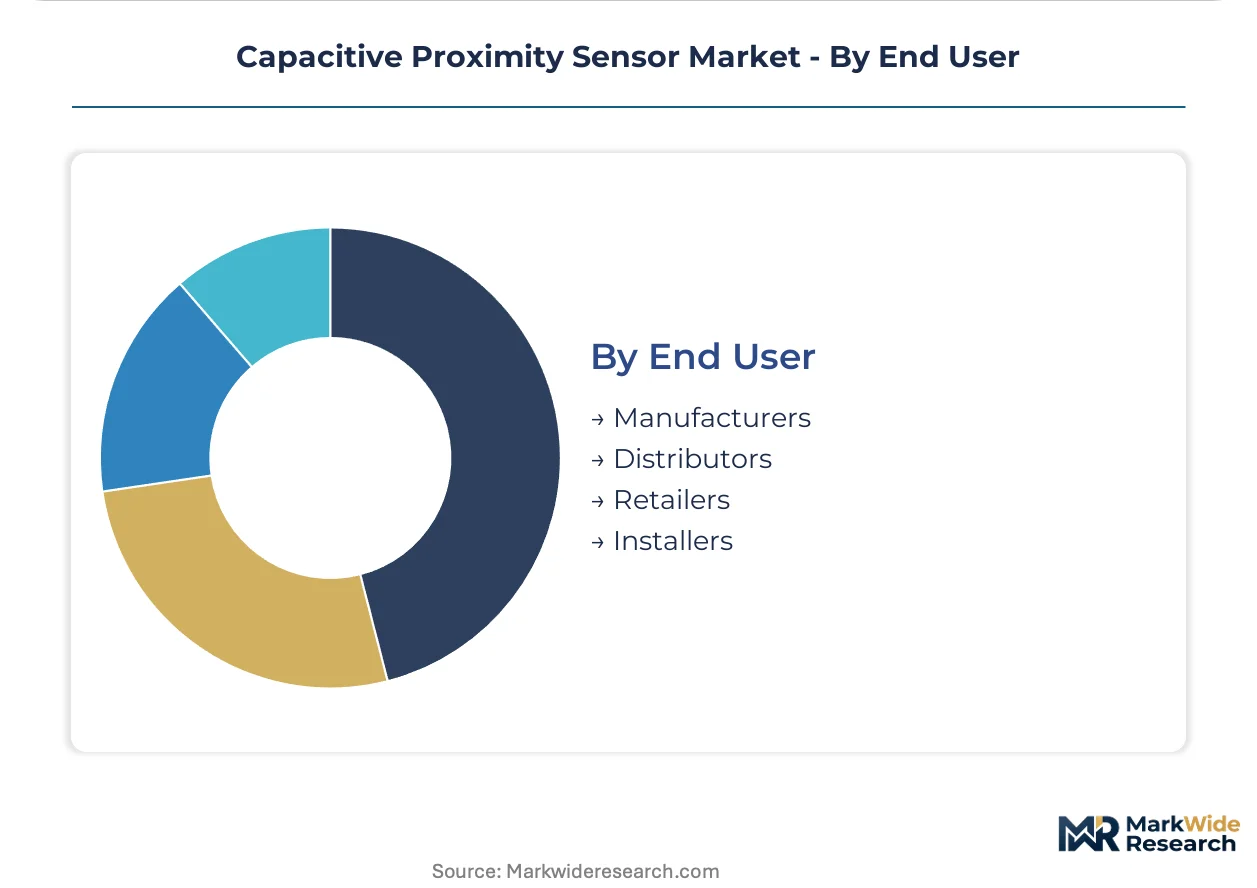
End User:
Customer type determines specification authority and procurement pattern, with manufacturers holding design-in influence and installers capturing aftermarket service revenue.
- Manufacturers:OEM specification authority shapes sensor architecture for automotive, semiconductor, and consumer electronics equipment. BMW and Volkswagen assembly plants mandate self-calibrating electrode geometries with embedded temperature compensation.
- Distributors:Channel intermediaries consolidate procurement for mid-sized automation integrators across Germany's industrial belt.
- Retailers:Consumer electronics and smart home device vendors drive volume through standardized SKU procurement.
- Installers:System integrators and maintenance providers capture IO-Link protocol-enabled predictive maintenance service streams.
Specification control rests with: Manufacturers. Fastest-growing procurement channel: Installers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Suzhou Industrial Park anchors the densest concentration of capacitive proximity sensor manufacturing, drawing component suppliers and calibration equipment vendors into clustered production ecosystems.
China
GB/T 14048.10 electromagnetic compatibility alignment accelerates export certification for Shenzhen and Suzhou automation clusters. The MIIT dual carbon goals pressure foundries toward energy-efficient electrode production. Pearl River Delta contract manufacturers now supply MEMS-based sensors for consumer electronics touch interfaces.
Germany
EU Machinery Directive functional safety mandates force redundant output architectures across automotive stamping plants in Stuttgart and Wolfsburg. REACH restrictions on perfluorinated compounds extend coating validation cycles for Baden-Württemberg sensor vendors. Bavarian assembly plants deploy self-calibrating electrode geometries for wet-film thickness detection.
United States
OSHA lockout-tagout regulations shape fail-safe sensor configurations in Michigan and Ohio heavy manufacturing corridors. Weld-field immunity validation strains third-party lab capacity in Detroit. Tier-one automotive suppliers mandate vendor-managed inventory programs with quarterly consumption true-ups.
Japan
METI industrial automation incentives concentrate precision sensor R&D in Nagoya and Osaka manufacturing belts. JIS standards alignment with IEC benchmarks eases cross-border component sourcing. Cleanroom robotics facilities in Kyushu drive specification toward sub-micron positioning tolerance arrays.
India
PLI scheme production-linked incentives for electronics manufacturing draw sensor assembly toward Pune and Chennai industrial corridors. BIS certification requirements for industrial equipment create domestic testing infrastructure gaps. Maharashtra-based integrators capture IO-Link protocol-enabled predictive maintenance service streams.
Capacitive Proximity Sensor Market Competitive Environment
Top-tier vendors anchor premium-tier precision sensing, while mid-scale fabricators compete on volume throughput for industrial automation. The vendor base clusters around three strategic archetypes: German precision optics specialists, Asian MEMS foundry integrators, and North American semiconductor platform providers. Competitive positioning hardens around M&A activity consolidating calibration equipment access and strategic partnerships securing foundry capacity.
Within the German precision-tier, Pepperl + Fuchs GmbH and Sick AG occupy positions exemplifying ruggedized industrial specialization. Texas Instruments Incorporated represents the semiconductor platform archetype, anchoring integrated signal conditioning supply to sensor OEMs. These three entities collectively illustrate how geographic origin and corporate structure map onto tiered competitive positioning.
| Leading Market Players |
|---|
| Pepperl + Fuchs GmbH |
| Sick AG |
| Rockwell Automation Inc. |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| Omron Corporation |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Others |
Value Chain & Pricing Dynamics
Copper and silver-palladium alloy electrode materials flow from commodity exchanges through German precision optics houses into three-tier pricing structures across premium, standard, and economy levels, with certification-grade sensors commanding spreads that reflect REACH compliance costs and laser calibration equipment access.
Pricing Analysis
Short-lead-time premiums concentrate in automotive battery assembly lines where SIL 2 and SIL 3 validation cycles extend procurement windows by 8-14 months. Pricing stratifies across premium, standard, and economy tiers based on IEC 60947-5-2 certification grade and IO-Link protocol integration depth. Cost compression in economy-grade sensors intensifies because copper electrode material volatility squeezes fabricators without captive supply arrangements. Consumer electronics OEMs exhibit highest price sensitivity, while semiconductor wafer handling facilities absorb premium positioning for sub-micron calibration arrays.
Supply Chain Analysis
Laser calibration equipment supply rests on a narrow precision optics base in Baden-Württemberg, with MEMS electrode miniaturization capacity concentrating in Shenzhen and Suzhou. Sensing electrode substrates draw from Japanese specialty metal suppliers and Chinese rare earth processors. Single-source vulnerability in German calibration systems creates structural risk for high-end array production. Distribution runs through vendor-managed inventory programs at Stuttgart supplier parks and tier-two integrator consignment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
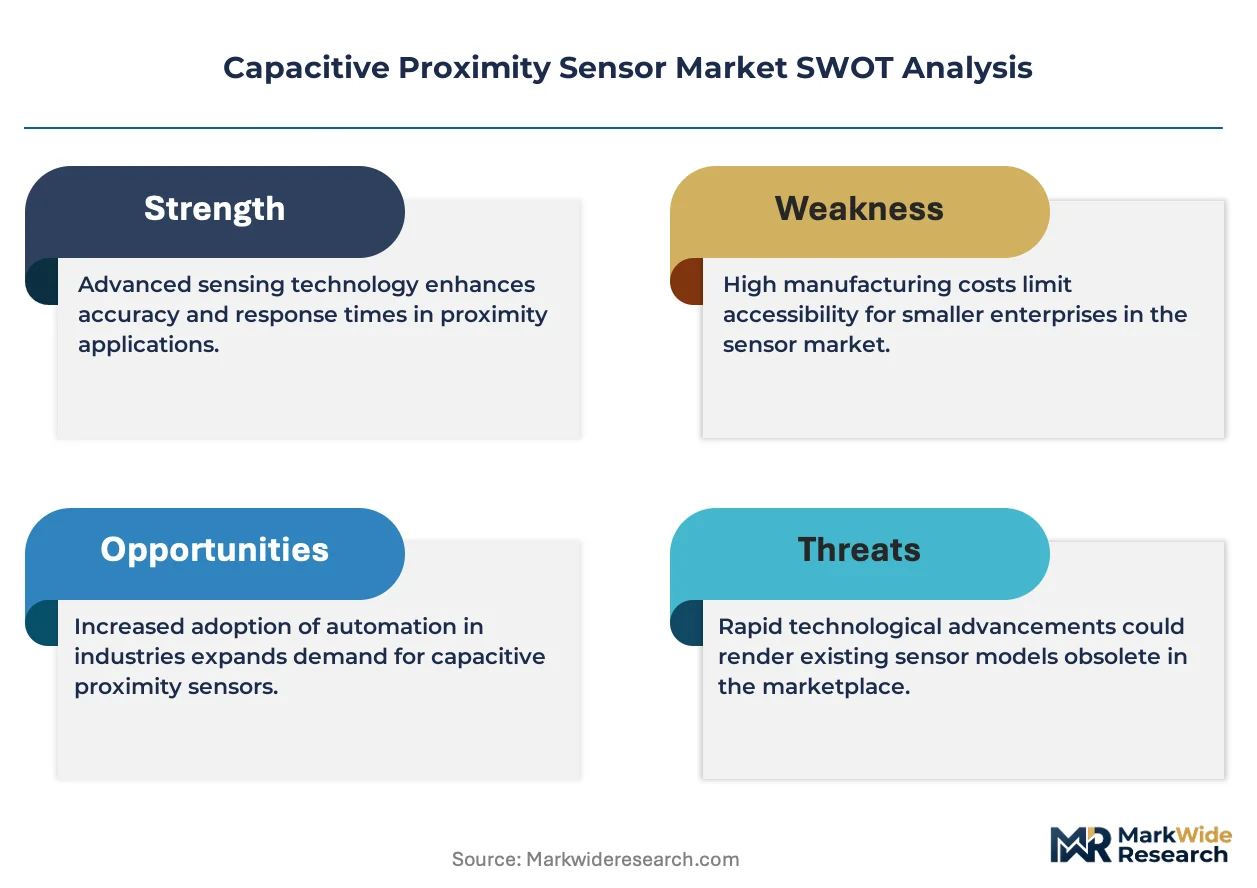
IEC 60947-5-2 functional safety mandates erect a cost-of-compliance barrier that rewards incumbent certification investment while screening out undercapitalized entrants across European industrial automation procurement.
For Market Incumbents: Hedge against inductive sensor substitution in pure metal detection by deepening MEMS foundry partnerships in Suzhou and capturing IO-Link protocol-enabled predictive maintenance service streams. Lock in laser calibration equipment capacity through long-term equipment lease structures with Baden-Württemberg precision optics vendors before capacity constraints harden. For New Entrants and Emerging Players: Capture white space in India's PLI scheme corridors around Pune and Chennai where domestic BIS certification infrastructure gaps delay established vendor entry. Target food-grade washdown-rated sensors with IP69K sealing for dairy and beverage packaging applications where optical contamination risks dominate specification. Lead with aftermarket service bundling rather than unit cost competition to bypass incumbent manufacturing scale advantages. For Investors and Strategic Acquirers: Consolidation of calibration equipment access is the leading indicator that margin pools will concentrate in premium-tier analog sensor arrays over the projection horizon. Prioritize acquisition targets with captive laser calibration relationships and existing SIL 2 validation dossiers. Watch for IO-Link protocol convergence adoption rates in tier-one automotive supplier parks as the inflection signal for predictive maintenance revenue maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Shenzhen and Suzhou automation clusters secure electrode miniaturization supply for consumer electronics integration. |
| SIL 2 and SIL 3 Certification Investment | European automotive battery assembly lines mandate redundant output architectures that exclude uncertified competitors. |
| IO-Link Protocol Platform Development | Unified digital interfaces enable predictive maintenance revenue capture at tier-two integrator facilities. |
| Food-Grade IP69K Sensor Line Launch | Dairy and beverage packaging applications face optical contamination risks that capacitive alternatives resolve. |
| Vendor-Managed Inventory Program Expansion | Stuttgart supplier park ecosystems reward consignment stock arrangements with quarterly consumption true-ups. |
Study Parameters
Document review covered IEC 60947-5-2 certification databases, EU Machinery Directive implementation guidance, and OSHA lockout-tagout regulatory filings, complemented by interviews with plant engineers at German automotive stamping facilities, procurement leads at tier-one battery assembly integrators, aftermarket service heads at industrial automation distributors, and MEMS foundry operations managers in Shenzhen. Secondary validation drew from customs trade data for copper and silver-palladium alloy flows, SEC 10-K disclosures from semiconductor platform providers, and GB/T 14048.10 electromagnetic compatibility test records. Bottom-up sensor unit deployment estimates triangulated against top-down industrial automation capital expenditure tracking.
Historical production capacity expansion patterns cross-referenced against panel input from OEM platform engineers and maintenance directors to anchor growth assumptions across the analysis window. Segmentation modeling spanned product architecture, application environment, technology modality, and end-user procurement authority. CAGRs derived from curve-fitting validated deployment trajectories against regulatory compliance timeline constraints and foundry capacity buildout schedules in Pearl River Delta automation clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrode material commodity volatility and REACH restriction scope expansion on dielectric coating formulations. Forecasts reflect documented assumptions about automotive electrification penetration rates and semiconductor fabrication facility buildout cadence. A small set of named triggers warrants ongoing watch: MIIT dual carbon policy enforcement intensity, Baden-Württemberg precision optics equipment lead time trends, and IO-Link protocol adoption velocity in tier-one automotive supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Spectral Sensor Market