
 ECG Sensor Market | 2026-2036
ECG Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
ECG Sensor Market Intelligence
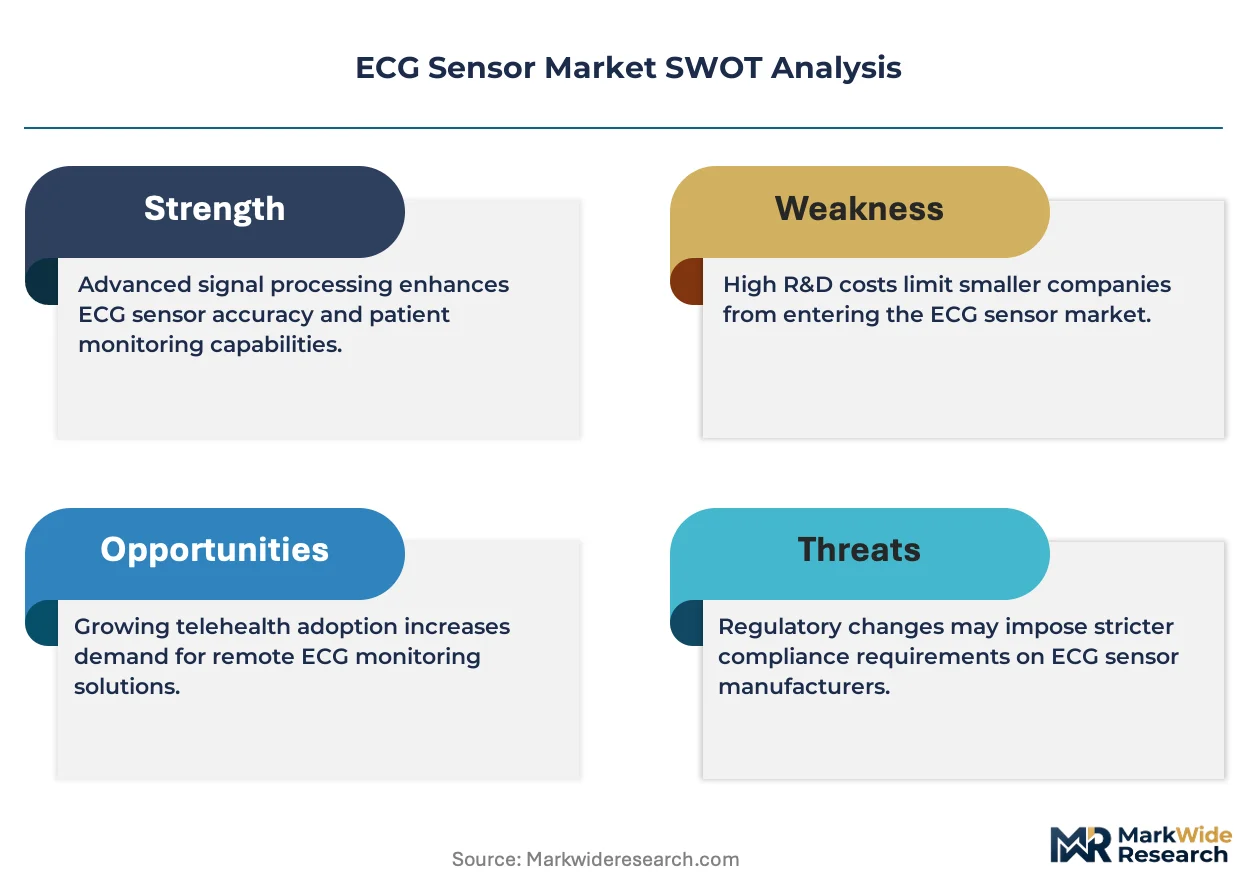
Hospital procurement channels for diagnostic cardiology equipment is reconfiguring around value-based care contracts and remote monitoring bundles. Medtronic plc leverages its integrated care networks to sustain institutional loyalty across cardiac service lines. Nihon Kohden Corporation anchors its position in Asian hospital systems through specialized electrophysiology workstations. AliveCor, Inc. differentiates by dominating direct-to-consumer channels with smartphone-connected ECG peripherals.
An ECG sensor detects and amplifies the heart's electrical activity through electrodes applied to the skin surface, typically capturing signals in the 0.05–100 Hz frequency range with input impedance exceeding 10 MΩ to minimize motion artifact and baseline drift. These transducers convert ionic potentials into processable voltage signals for arrhythmia detection, ischemia monitoring, and cardiac risk stratification in clinical and ambulatory settings. Wearable ECG sensors are capturing the fastest growth trajectory as patients seek continuous monitoring outside traditional diagnostic centers, while Holter monitor segments retain mature, high-margin installed bases in cardiac clinics. Capacitive technology leads consumer-facing applications for its dry-electrode convenience, whereas microelectromechanical systems architectures command premium positioning in multi-parameter diagnostic platforms.
FDA premarket notification requirements and the EU Medical Device Regulation shape product development timelines, with both agencies intensifying scrutiny of algorithm-based arrhythmia detection claims in software-as-medical-device classifications. HIPAA privacy rules and GDPR data governance standards constrain how telehealth providers transmit and store continuous ECG telemetry across cloud platforms. Stakeholders must weigh regulatory compliance investments against the pace of AI-enabled diagnostic automation that vendors are embedding into next-generation sensor platforms.
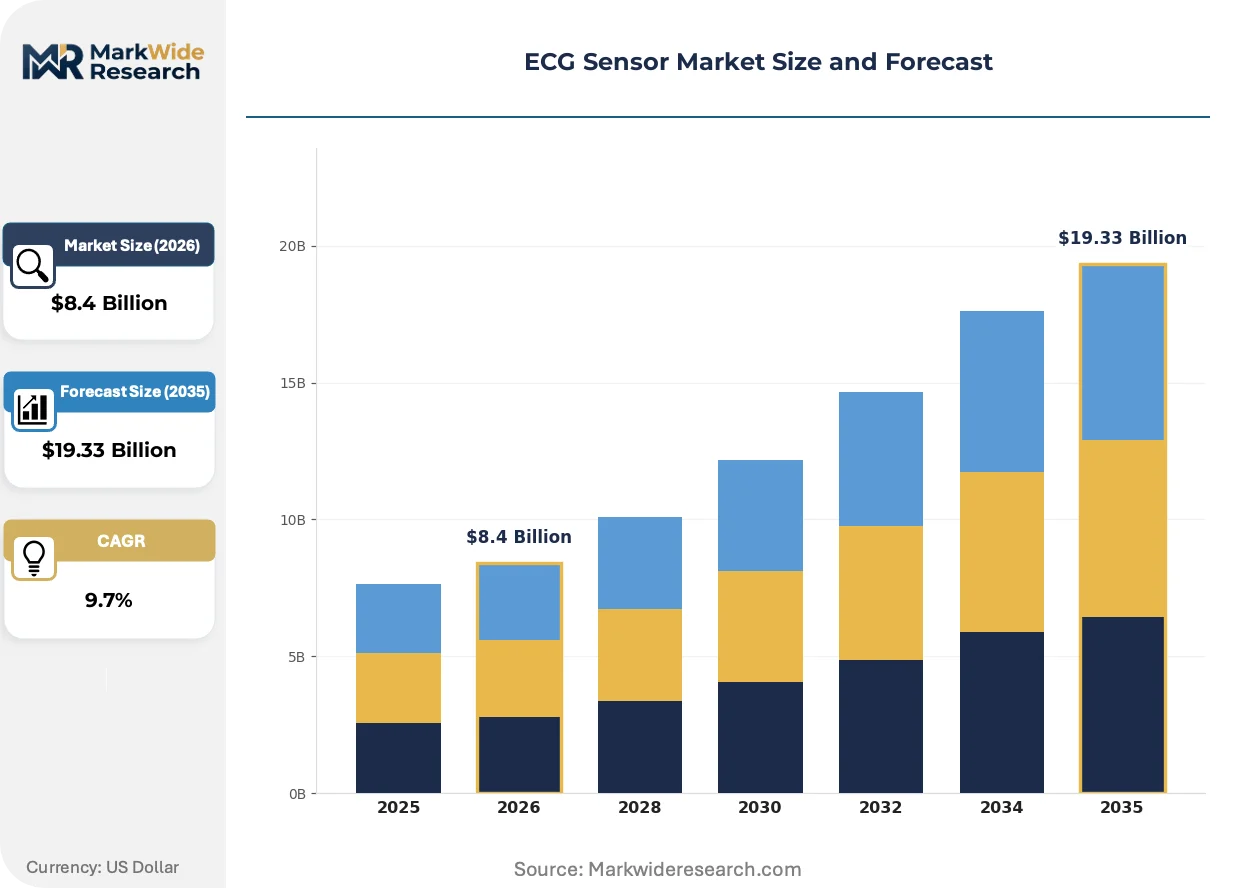
Market Dynamics
Cardiac diagnostic procurement is reconfiguring around continuous monitoring architectures, with institutional buyers bundling ambulatory ECG systems into remote patient monitoring infrastructure rather than purchasing discrete diagnostic equipment.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's evolving software-as-medical-device framework accelerates algorithm-based arrhythmia detection clearances, compressing time-to-market for AI-enabled ECG platforms.
- Capacitive dry-electrode technology:Elimination of conductive gels and adhesives expands patient compliance for multi-day wearables, opening ambulatory monitoring to populations previously excluded by skin irritation barriers.
- German DiGA fast-track:Germany's Digital Health Applications reimbursement pathway reimburses prescribed ECG apps, creating institutional pull for smartphone-connected diagnostic peripherals in statutory health insurance.
Market Restraints
- Silver-silver chloride electrode cost volatility:Precious metal price fluctuations in consumable electrode manufacturing compress margins for high-volume Holter monitor consumable suppliers.
- EU MDR technical documentation burden:The Medical Device Regulation's intensified clinical evidence requirements for Class IIa ECG devices extends recertification timelines by 12-18 months for legacy product portfolios.
- Photoplethysmography substitution:Optical heart rate sensors in consumer wearables capture casual monitoring demand that once flowed toward single-lead ECG peripherals.
Strategic Opportunities
- Japan's super-aging demographic:METI's healthcare robotics and remote monitoring subsidies target 80+ populations with prescription-grade home ECG systems, creating reimbursement-anchored demand.
- AI-ECG cloud convergence:Integration of edge-computing inference with centralized longitudinal analytics enables population-scale arrhythmia screening programs previously uneconomical with manual over-reading.
- Direct-to-employer occupational health channels:Self-insured corporations in the United States are contracting for workforce cardiac risk stratification programs bypassing traditional hospital system intermediaries.
Industry Challenges
- Biomedical signal processing talent scarcity:The intersection of electrophysiology domain expertise and embedded systems engineering commands premium compensation, constraining R&D scaling for mid-tier device manufacturers.
- HIPAA-GDPR cross-border telemetry architecture:Continuous ECG data flows from US patients to EU-located cloud analytics engines trigger complex data localization and processor agreement negotiations.
- Legacy EMR integration complexity:Ambulatory ECG platforms must support fragmented hospital information system protocols, requiring costly adapter development for each major electronic medical record vendor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Sensor Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Patch, Holter Monitor, Resting, Ambulatory Technology: Capacitive, Resistive, Piezoelectric, Optical, Microelectromechanical Systems Application: Cardiology Diagnostics, Sports Performance, Sleep Monitoring, Stress Analysis, Telemedicine End User: Cardiac Clinics, Diagnostic Centers, Telehealth Providers, Sports Institutions |
| Companies Covered | Medtronic plc, Nihon Kohden Corporation, GE Healthcare, AliveCor, Inc., iRhythm Technologies Inc., Koninklijke Philips N.V., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Schiller AG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Sensor Market Strategic Shifts & Innovations
ECG sensor architecture is bifurcating between ultra-low-power consumer wearables and clinical-grade multi-parameter platforms, with algorithm sophistication becoming the primary differentiation vector rather than hardware sensitivity alone.
Multi-lead ECG-on-chip integration is migrating from discrete analog front-end assemblies toward single-die CMOS implementations combining instrumentation amplifiers, ADCs, and digital signal processing cores. Medtronic and Nihon Kohden are incorporating these system-in-package designs into next-generation patch monitors, collapsing board area by 60% and enabling 14-day continuous wear form factors previously impossible with conventional component stacking.
The EU Medical Device Regulation's intensified post-market surveillance obligations are forcing ECG software vendors to implement automated adverse event detection pipelines and periodic safety update reporting. Algorithm developers marketing atrial fibrillation detection claims must now maintain clinical performance registries spanning real-world use across member states, with notified bodies demanding predictive accuracy validation against ethnically diverse electrocardiogram libraries rather than single-site training data.
Hospital procurement committees are unbundling ECG hardware from interpretation services, contracting separately with AI-overreading platforms and reducing reliance on traditional diagnostic service organizations. This disaggregation is most advanced in United States integrated delivery networks, where value-based cardiac care contracts incentivize in-house arrhythmia detection capabilities that compress specialist referral leakage and capture downstream intervention revenue within system boundaries.
ECG Sensor Market Segmentation
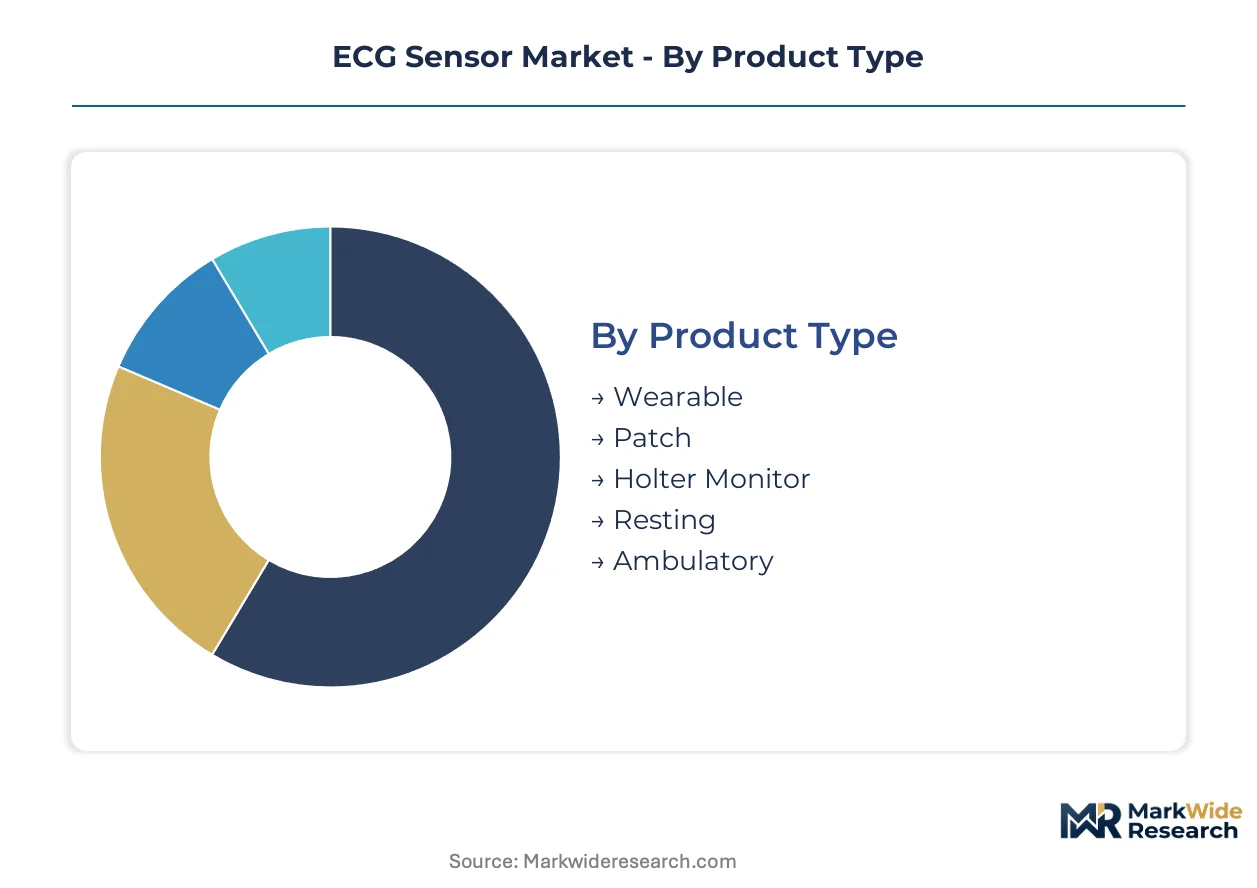
ECG sensor segmentation reflects divergent technical requirements across clinical precision and consumer convenience endpoints. Product architecture, signal acquisition methods, and distribution channels each create distinct competitive arenas with separate margin profiles and regulatory pathways.
Product Type:
Mature diagnostic formats coexist with emerging wearable architectures, creating tiered investment horizons for manufacturers balancing installed base maintenance against new form factor development.
- Wearable:Continuous-wristband and chest-strap designs integrate photoplethysmography-corroborated algorithms for consumer arrhythmia screening. United States telehealth providers are contracting for prescription-grade wearables that bridge FDA 510(k) clearance with direct-to-patient distribution.
- Patch:Single-use adhesive electrodes with embedded Bluetooth Low Energy radios enable 7-14 day ambulatory monitoring without patient-managed electrode replacement. Cardiac clinics in Germany are replacing legacy Holter inventories with patch-based systems under DiGA reimbursement pathways.
- Holter Monitor:Multi-lead portable recorders with patient event markers retain diagnostic gold-standard status for cryptogenic stroke workups and syncope characterization.
- Resting:12-lead stationary systems with automated measurement algorithms dominate hospital admission protocols and preoperative clearance workflows.
- Ambulatory:Event recorders and mobile cardiac telemetry units capture intermittent symptoms through patient-activated or auto-triggered transmission to monitoring centers.
Patch retains volume leadership; wearable holds the steepest expansion curve.
Technology:
Cost tier stratification separates gel-dependent clinical-grade methods from dry-electrode consumer applications, with premium positioning concentrated in multi-parameter integration platforms.
- Capacitive:Dry electrodes detect bioelectric signals through insulating layers without skin preparation or conductive gel. Sports institutions in Japan are deploying capacitive chest bands for team-wide cardiovascular screening programs.
- Resistive:Conventional silver-silver chloride electrodes with hydrogel interfaces deliver lowest-noise signal acquisition for diagnostic-grade 12-lead systems. Precious metal cost volatility constrains margin expansion for high-volume disposable suppliers.
- Piezoelectric:Mechanical stress-to-voltage transducers capture heart sounds and chest wall vibrations as adjunctive cardiomechanical signals.
- Optical:Photoplethysmography modules using green and infrared LEDs substitute for electrical sensing in consumer wellness devices, though PPG substitution threatens single-lead ECG peripheral demand.
- Microelectromechanical Systems:Silicon-fabricated accelerometers and pressure sensors enable multi-parameter fusion with ECG in compact diagnostic platforms.
Resistive technology anchors diagnostic revenue; capacitive methods are expanding most quickly into consumer channels.
Application:
Customer type divergence separates reimbursed clinical indications from discretionary wellness monitoring, with algorithm sophistication becoming the primary value determinant across both domains.
- Cardiology Diagnostics:Arrhythmia detection, ischemia monitoring, and risk stratification for structural heart disease command premium pricing through FDA-cleared and MDR-compliant pathways.
- Sports Performance:Heart rate variability and recovery metrics guide training load management for elite and amateur athletes. United States professional sports franchises are integrating ECG screening into preseason physical protocols.
- Sleep Monitoring:Overnight ECG recording identifies nocturnal arrhythmia burden and sleep-disordered breathing cardiovascular consequences.
- Stress Analysis:Acute cardiac response patterns support occupational health and wellness program enrollment in self-insured employer populations.
- Telemedicine:Remote ECG acquisition with cloud-based overreading extends specialist reach into underserved geographies. German statutory health insurance reimbursement for prescribed ECG apps accelerates telemedicine platform procurement.
Cardiology diagnostics retains volume leadership; telemedicine holds the steepest expansion curve.
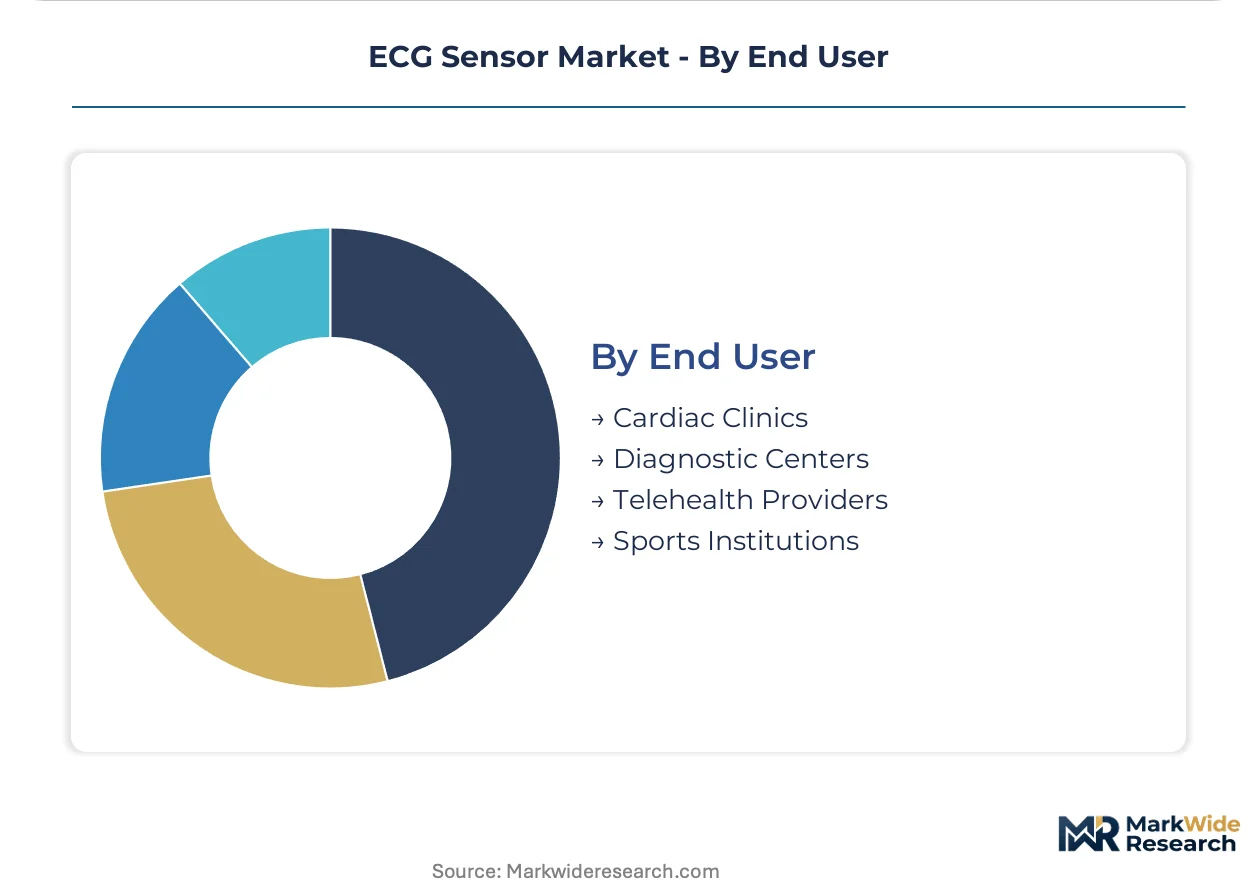
End User:
Procurement authority fragmentation creates parallel sales motions: capital equipment committees for hospital systems, subscription contracts for virtual care platforms, and bulk purchasing for athletic organizations.
- Cardiac Clinics:Electrophysiology-focused outpatient facilities drive ambulatory monitor procurement and interpretation service bundling. United States integrated delivery networks are consolidating cardiac clinic purchasing through value-based care contracts.
- Diagnostic Centers:Independent testing facilities perform resting ECG and stress testing with radiologist or cardiologist overreading for referring physician networks.
- Telehealth Providers:Virtual-first care platforms prescribe and distribute wearable ECG peripherals with asynchronous specialist review. HIPAA-GDPR cross-border telemetry architecture complexity constrains vendor selection for platforms serving transnational patient populations.
- Sports Institutions:Professional teams, collegiate athletic departments, and fitness chains deploy cardiovascular screening for liability mitigation and performance optimization.
Cardiac clinics retain volume leadership; telehealth providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements anchor the United States as the dominant geography for ECG sensor commercialization, while Japan's METI subsidies and Germany's DiGA pathway create parallel demand centers for prescription-grade remote monitoring systems.
United States
Integrated delivery networks in Texas and California are consolidating cardiac clinic procurement through value-based care contracts that bundle ambulatory ECG systems with remote patient monitoring infrastructure. FDA 510(k) pathway streamlining accelerates algorithm-based arrhythmia detection clearances, compressing time-to-market for AI-enabled platforms. The Greater Boston cluster anchors telehealth provider headquarters prescribing wearable ECG peripherals with asynchronous specialist review.
Germany
Statutory health insurance reimbursement through the Digital Health Applications fast-track creates institutional pull for smartphone-connected diagnostic peripherals in Berlin and Munich hospital systems. EU MDR technical documentation burden extends recertification timelines for legacy product portfolios, favoring manufacturers with robust clinical evidence registries. The Baden-Württemberg medical technology corridor concentrates electrophysiology workstation development for Asian export markets.
Japan
METI healthcare robotics and remote monitoring subsidies target 80+ populations in Tokyo and Osaka with prescription-grade home ECG systems. Super-aging demographic dynamics create reimbursement-anchored demand for continuous monitoring outside traditional diagnostic centers. The Kansai region hosts specialized electrophysiology workstation manufacturers supplying domestic hospital systems.
China
NMPA regulatory frameworks for software-as-medical-device classifications intensify scrutiny of algorithm-based arrhythmia detection claims in Shenzhen and Shanghai. Domestic manufacturers leverage CMOS system-in-package designs to collapse board area in patch monitor form factors. The Yangtze River Delta concentrates multi-parameter diagnostic platform assembly for regional hospital procurement.
India
CDSCO medical device regulations shape product development timelines for telemedicine platforms serving underserved geographies through cloud-based ECG overreading. Diagnostic centers in Maharashtra and Karnataka perform resting ECG and stress testing with radiologist overreading for referring physician networks. The Delhi-NCR corridor anchors telehealth provider expansion into cardiac risk stratification programs.
ECG Sensor Market Key Industry Players
Integrated care networks and specialized electrophysiology workstation manufacturers split the market between institutional loyalty programs and technical differentiation in Asian hospital systems. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with cardiac service line breadth, specialized diagnostic equipment manufacturers with regional anchoring, and direct-to-consumer platform vendors bypassing traditional procurement channels. Competitive moves center on AI-overreading service unbundling from hardware sales and cloud analytics engine integration with edge-computing inference capabilities.
Within the diversified medical technology tier, Medtronic plc and GE Healthcare exemplify archetypes leveraging integrated care networks to sustain institutional loyalty across cardiac service lines. Nihon Kohden Corporation occupies a position as a specialized electrophysiology workstation manufacturer anchoring its presence in Asian hospital systems. Among direct-to-consumer platform vendors, AliveCor, Inc. represents the archetype dominating smartphone-connected ECG peripheral channels outside traditional procurement structures.
| Leading Market Players |
|---|
| Medtronic plc |
| Nihon Kohden Corporation |
| GE Healthcare |
| AliveCor, Inc. |
| iRhythm Technologies Inc. |
| Koninklijke Philips N.V. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Schiller AG |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
The Shanghai-Shenzhen electronics corridor's freight cost dynamics amplify supply concentration effects for ECG sensor manufacturers, compressing margins on standard-grade consumables while preserving premium pricing power for FDA-cleared diagnostic platforms with embedded algorithm stacks.
Pricing Analysis
The customization-premium spread between configured-to-order multi-parameter systems and standard single-lead peripherals spans three-tier pricing structure across premium, standard, and economy levels. Premium tiers command valuation anchored in FDA 510(k) clearance and AI-overreading bundling, while economy segments face relentless cost compression from photoplethysmography substitution in consumer wellness devices. Hospital procurement committees exhibit lowest price sensitivity for integrated remote patient monitoring bundles, whereas direct-to-consumer channels demonstrate acute elasticity to disposable electrode recurring costs.
Supply Chain Analysis
Contract-manufacturing concentration for CMOS system-in-package assemblies rests with Taiwan Semiconductor Manufacturing capacity and select Shenzhen-based EMS providers serving mid-tier patch monitor developers. Silver-silver chloride electrode fabrication draws from Japanese and German precious metal processors, while hydrogel adhesive supply hinges on Minnesota and Massachusetts chemical specialists. Single-source vulnerability in analog front-end instrumentation amplifiers threatens production continuity for multi-lead diagnostic platforms. Distribution runs through cardiology-focused GPOs in the United States and statutory health insurance procurement frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECG sensor market sits at a platform-economics inflection where AI-overreading service unbundling from hardware sales is reconfiguring vendor competitive position, with interoperability standards across Epic and Cerner EMR systems determining ecosystem lock-in depth.
For Market Incumbents: Entrench institutional loyalty through exclusive GPO contracting with United States integrated delivery networks and backward integration into CMOS foundry capacity for 14-day patch form factors. Photoplethysmography substitution in Apple Watch and Samsung Galaxy devices threatens single-lead peripheral demand; counter by embedding edge-computing inference that optical sensors cannot replicate for diagnostic-grade arrhythmia detection. For New Entrants and Emerging Players: Establish a beachhead in Japan's super-aging home monitoring segment where METI subsidies offset customer acquisition costs and reimbursement pathways are already institutionalized. Germany's DiGA fast-track offers the most penetrable regulatory channel for smartphone-connected prescription devices. Pursue direct-to-employer occupational health contracts bypassing hospital system intermediaries entirely. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core cardiac monitoring divisions amid portfolio rationalization pressures. Five-to-ten-year viability hinges on cloud analytics engine integration rather than hardware manufacturing scale. Monitor FDA software-as-medical-device enforcement discretion as the critical inflection signal for algorithm-based valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates algorithm-based arrhythmia detection clearance timelines for AI-enabled ECG platforms. |
| EU MDR Class IIa Technical Documentation Pathway | Extends recertification timelines but creates competitive moat for manufacturers with clinical evidence registries. |
| Integrated Delivery Network GPO Partnership | Locks in ambulatory ECG procurement through value-based cardiac care contract bundling. |
| AI-Overreading Cloud Platform Integration | Enables population-scale screening economics previously uneconomical with manual specialist review. |
| Reimbursement Strategy for DiGA/DiPA Pathways | Captures statutory health insurance pull in Germany for prescribed smartphone-connected diagnostic peripherals. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrophysiologists, hospital biomedical engineering directors, cardiac clinic purchasing committee members, and telehealth platform product managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body technical documentation filings, CMS Medicare remote patient monitoring reimbursement schedules, and German BfArM Digital Health Applications registry entries. Bottom-up unit shipment estimates across patch, wearable, and Holter form factors were triangulated against top-down cardiac diagnostic equipment spending data from hospital capital budget disclosures.
Calibration against historical volume trajectories in ambulatory ECG segments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, signal acquisition technology, clinical versus consumer application endpoint, and procurement authority type. CAGRs were derived from regression analysis of installed base replacement cycles and ambulatory monitoring penetration rates in aged populations. Forecast inputs incorporated FDA software-as-medical-device enforcement patterns and METI healthcare robotics subsidy allocation trends.
Sensitivities concentrate around EU MDR post-market surveillance obligation implementation timelines and silver price volatility in disposable electrode manufacturing. Forecasts embed assumptions regarding reimbursement pathway expansion for continuous monitoring in statutory health insurance systems. Quarterly review of FDA 510(k) clearance velocity and DiGA prescription volume data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Sensor Fusion Market