
 Global E-Compass Market | 2026-2036
Global E-Compass Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Compass Market Analysis
Market Context with Strategic Players
South Korea's semiconductor packaging corridor is narrowing the cost gap with legacy European MEMS fabs. STMicroelectronics leverages its vertically integrated 8-inch MEMS foundry in Agrate Brianza to sustain pricing power across automotive-grade e-compass modules. Bosch Sensortec dominates consumer electronics channels through its BMX160 series, while Honeywell International anchors aerospace and defense procurement with radiation-hardened fluxgate designs.
Technical Definition and Structural Segments
An e-compass is an electronic magnetometer that detects magnetic field vectors along X, Y, and Z axes, typically resolving heading accuracy to within one degree using Hall-effect or anisotropic magnetoresistive sensing elements. Its primary commercial purpose is to provide absolute orientation reference for navigation systems, motion-tracking platforms, and attitude-heading reference units where GPS signals degrade or fail. MEMS-based e-compass modules lead unit shipments due to sub-dollar pricing at million-scale volumes, yet fluxgate magnetometers command the margin pool in aerospace and subsea applications where temperature stability exceeds 0.1 degree precision. Digital technology architectures are displacing analog outputs in robotics and virtual reality headsets as I3C and SPI interfaces simplify microcontroller integration.
Regulatory Frame and Forward-Looking Close
The EU REACH regulation and RoHS directive restrict cadmium and lead content in magnetoresistive thin films, compelling foundries to reformulate sputtering targets and validate alternative dopant chemistries. Japan's METI enforces JIS C 0920 environmental sealing standards for outdoor robotics deployments, while the FAA mandates DO-160G magnetic interference testing for e-compass integration in civil avionics. Stakeholders must monitor how China's GB standard harmonization with IEC 60747 semiconductor specifications alters cross-border component qualification timelines.
Market Dynamics
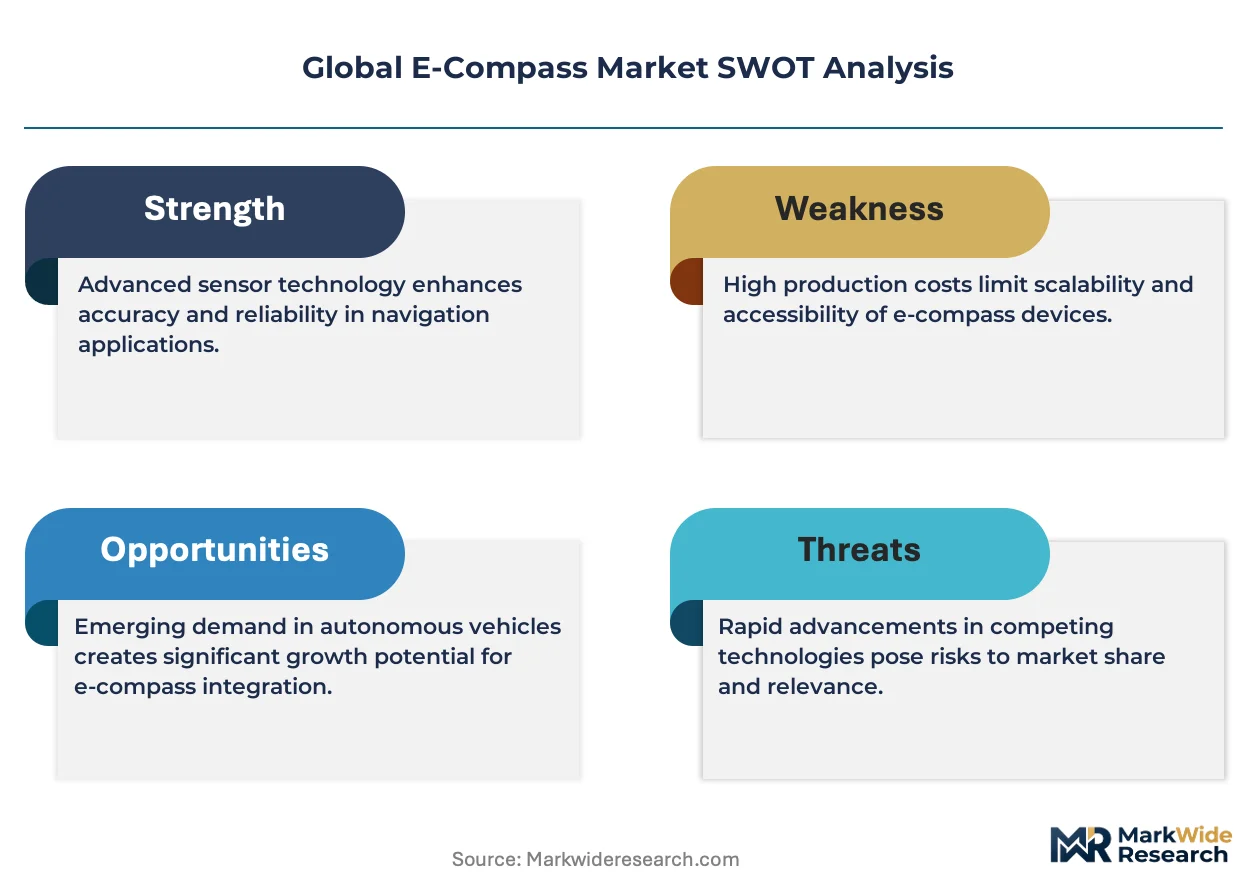
Magnetic interference from high-current electric vehicle powertrains is forcing automakers to source e-compass modules with active shielding and dynamic calibration algorithms, compressing the addressable supply base to vendors with automotive-grade MEMS fabrication capabilities.
Growth Catalysts
- EU Green Deal electronics mandates:Sustainability disclosure requirements under the Corporate Sustainability Reporting Directive accelerate replacement cycles for cadmium-containing magnetoresistive sensors in industrial robotics.
- Indoor navigation proliferation:Smartphone manufacturers in South Korea and Japan integrate 9-axis sensor fusion combining e-compass with gyroscopes and accelerometers for augmented reality wayfinding in GPS-denied environments.
- Drone altitude stabilization:Commercial UAV operators in the United States deploy fluxgate magnetometers for magnetic heading reference during beyond-visual-line-of-sight operations where GPS multipath corrupts position fixes.
Market Restraints
- Rare earth magnet price volatility:Neodymium and dysprosium price swings from Chinese export quota adjustments inflate bill-of-materials costs for anisotropic magnetoresistive thin-film deposition targets.
- MEMS foundry concentration:Eight-inch wafer capacity for consumer-grade e-compass production clusters in Taiwan and South Korea, exposing buyers to single-source disruption risk during regional semiconductor equipment maintenance cycles.
- Temperature drift limitations:Hall-effect sensors exhibit heading error exceeding three degrees across automotive underhood thermal ranges, disqualifying them from engine-bay mounting positions without compensation firmware.
Strategic Opportunities
- Subsea robotics white space:Oilfield services contractors in Norway and Brazil source fluxgate magnetometers for remotely operated vehicle navigation where acoustic positioning fails in deepwater trenching operations.
- India PLI scheme leverage:Production-linked incentives for electronics manufacturing attract MEMS packaging investments to the Noida semiconductor corridor, creating captive supply for domestic smartphone assemblers.
- I3C interface convergence:The MIPI I3C standard unifies sensor bus architectures, enabling e-compass module vendors to reduce pin count and PCB footprint for wearable device integrators.
Industry Challenges
- DO-160G certification timelines:FAA electromagnetic interference testing for civil avionics e-compass integration extends qualification cycles to 18-24 months, freezing design iterations for regional jet programs.
- Multi-axis calibration skill scarcity:Factory floor technicians capable of executing hard-iron and soft-iron compensation algorithms for nine-degree-of-freedom sensor fusion remain concentrated in Agrate Brianza and Grenoble MEMS clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Compass Market |
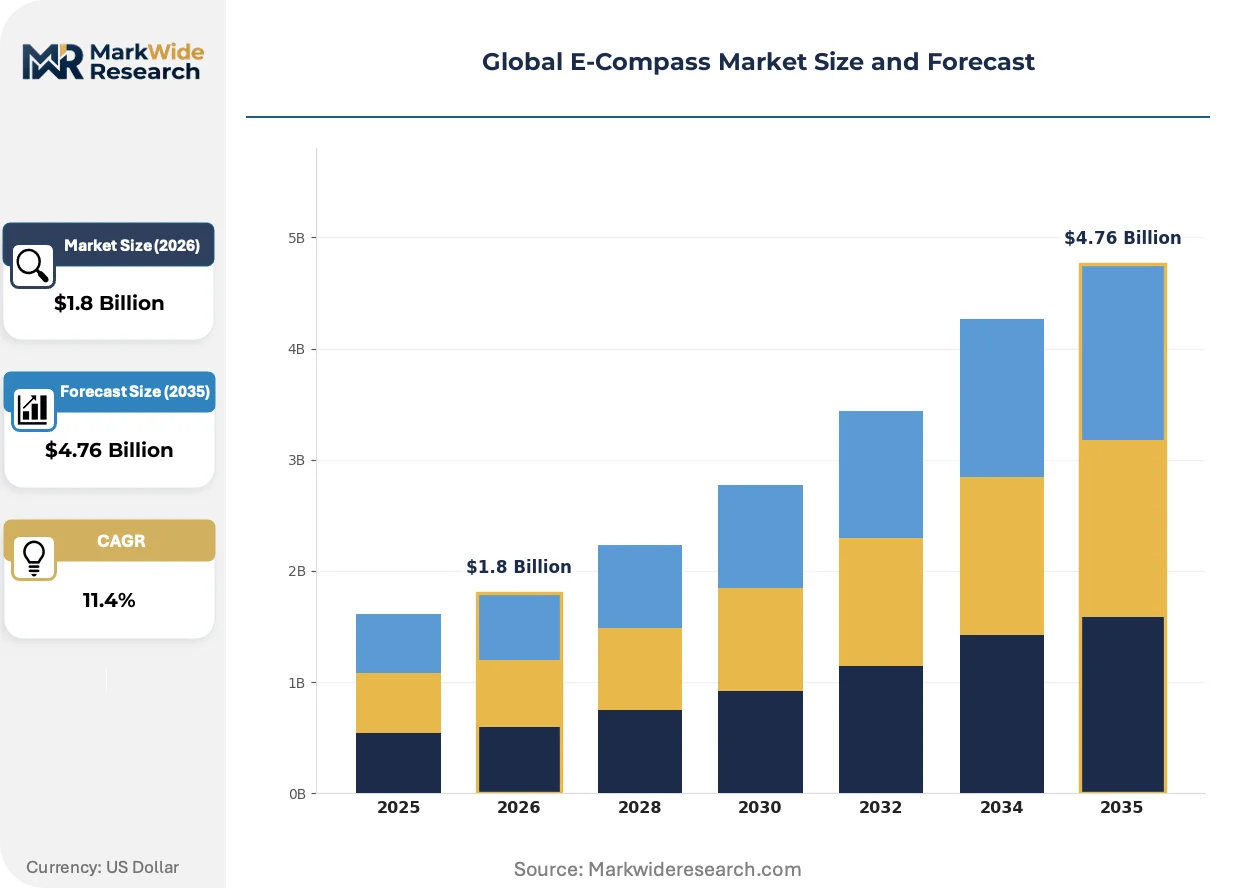
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro-Electro-Mechanical Systems, Fluxgate Magnetometers, Magneto Resistive Sensors, Optical Sensors End User: Aerospace, Automotive, Consumer Electronics, Robotics Technology: Analog, Digital, Hybrid, Inertial Application: Navigation, Motion Sensing, Virtual Reality, Industrial Automation |
| Companies Covered | STMicroelectronics, Honeywell International, Asahi Kasei Microdevices, NXP Semiconductors, TDK Corporation, Bosch Sensortec, Robert Bosch, Murata, PNI Sensors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Compass Market Emerging Trajectories
Tunnel magnetoresistance sensing architectures are compressing the performance gap between consumer MEMS and precision fluxgate designs, while regulatory pressure on hazardous substances accelerates materials science investment across Asian packaging houses.
Tunnel magnetoresistance sensors exploit spin-dependent electron tunneling through ultra-thin insulating barriers to achieve noise floors below 10 nanotesla per root hertz. Automotive tier-one suppliers in Germany and Japan are qualifying TMR-based e-compass modules for electric vehicle chassis control systems where magnetic disturbance from 800-volt battery packs corrupts legacy Hall-effect readings. This sensitivity improvement is rendering obsolete the traditional segmentation between sub-dollar consumer MEMS and hundred-dollar aerospace fluxgate magnetometers.
China's GB standard harmonization with IEC 60747 semiconductor specifications is compressing cross-border component qualification timelines for MEMS magnetometers. The State Administration for Market Regulation now accepts IEC test reports for electromagnetic compatibility and environmental sealing, reducing redundant certification costs for European and Japanese vendors. Industrial robotics OEMs sourcing from Shenzhen contract manufacturers benefit most from this mutual recognition arrangement.
Sensor-as-a-subscription procurement models are displacing perpetual component purchases among fleet robotics operators. Autonomous mobile robot deployers in California and Massachusetts now pay per navigation-hour for calibrated e-compass modules with embedded drift compensation algorithms, transferring obsolescence risk to sensor vendors. This consumption-pattern shift concentrates most visibly in warehouse automation contracts exceeding five hundred unit deployments.
Global E-Compass Market Segmentation
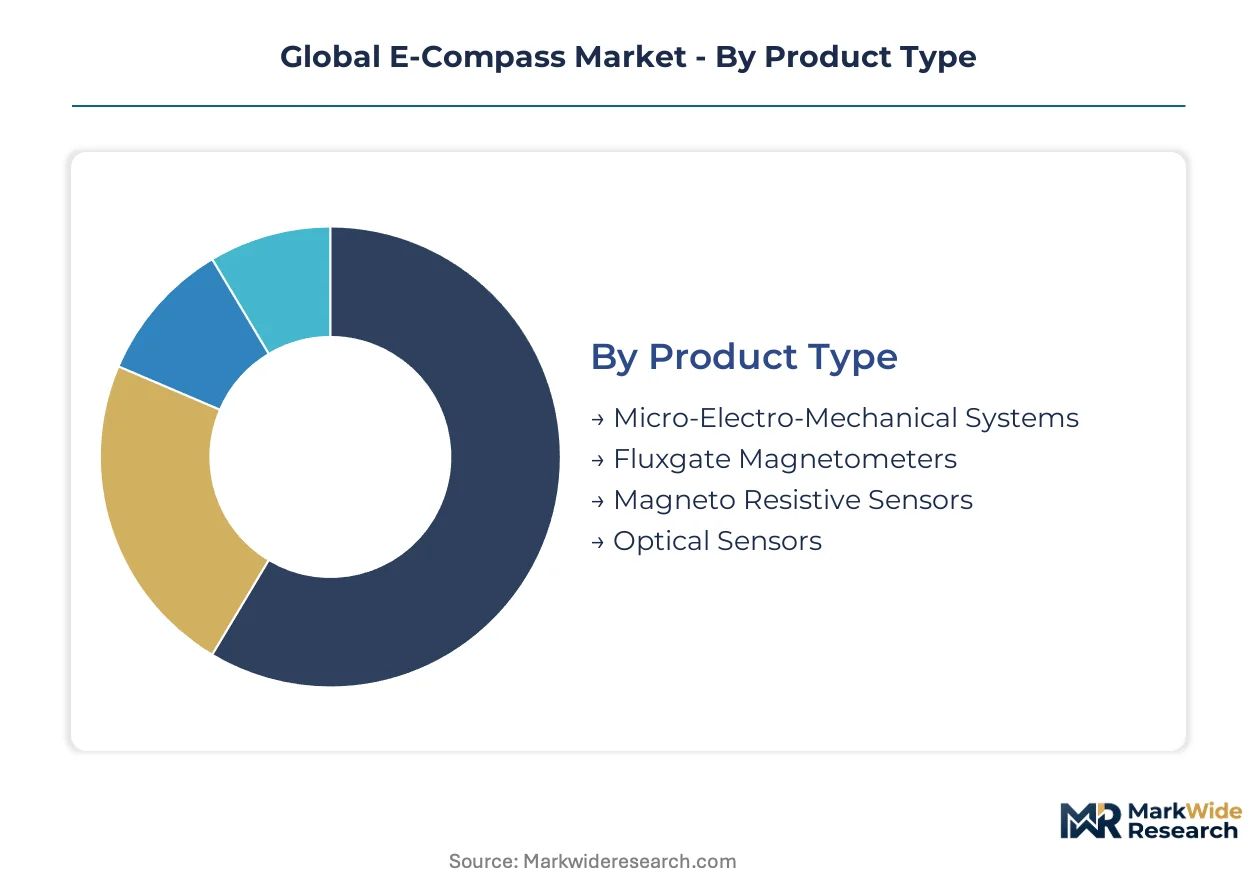
E-compass procurement patterns diverge sharply across product architectures and end-use environments. Segment boundaries determine qualification timelines, margin structures, and foundry capacity allocation for magnetic sensor vendors.
Product Type:
MEMS modules turn inventory fastest in consumer channels while fluxgate designs linger in aerospace qualification pipelines for years. Replacement cycles range from six months in smartphones to fifteen years in satellite attitude systems.
- Micro-Electro-Mechanical Systems:Silicon-based resonant structures fabricated on 8-inch wafers achieve sub-dollar unit economics at million-scale volumes. Samsung and Apple smartphone programs in South Korea and California consume the majority of STMicroelectronics and Bosch Sensortec MEMS foundry output for 9-axis sensor fusion modules.
- Fluxgate Magnetometers:Saturation-core designs wound with precision coils deliver temperature stability below 0.1 degree heading error across −55°C to +125°C ranges. Honeywell International and Bartington Instruments supply radiation-hardened variants to NASA and ESA satellite contractors where MEMS drift rates disqualify silicon alternatives.
- Magneto Resistive Sensors:Anisotropic magnetoresistive thin films dominate automotive chassis stabilization where cost targets sit between MEMS and fluxgate tiers. NXP Semiconductors and TDK InvenSense serve Tier-1 suppliers in Germany and Japan with AEC-Q100 qualified modules.
- Optical Sensors:Fiber-optic gyroscope companions for subsea navigation exploit magnetic immunity at depth. Sonardyne and iXblue deploy these for ROV positioning in Norwegian North Sea oilfields where acoustic multipath corrupts conventional references.
MEMS anchors the volume base while fluxgate gains share at the steepest rate in satellite and defense procurement.
End User:
Customer type determines pricing power and certification burden. Consumer electronics buyers squeeze foundries on wafer pricing while aerospace primes accept 40-week lead times for traceable heritage.
- Aerospace:DO-160G and MIL-STD-461 qualification mandates restrict the vendor base to suppliers with radiation-hardened fluxgate heritage. Boeing and Airbus civil programs source from Honeywell Aerospace facilities in Minnesota and Arizona.
- Automotive:800-volt electric powertrains generate magnetic interference that corrupts unshielded Hall-effect readings. Continental and Denso specify active compensation algorithms from Bosch Sensortec and TDK for chassis control modules.
- Consumer Electronics:Smartphone OEMs in Shenzhen and Seoul integrate 6-axis and 9-axis fusion modules for augmented reality wayfinding. Apple and Samsung design teams specify I3C interface compliance to reduce PCB footprint.
- Robotics:Autonomous mobile robot fleets in California warehouses demand calibrated heading references for SLAM navigation. Locus Robotics and 6 River Systems procure sensor-as-a-subscription contracts with embedded drift compensation.
Consumer electronics commands absolute unit volume while robotics climbs fastest on fleet automation capex.
Technology:
Interface architecture determines microcontroller integration complexity. Analog outputs retain niche presence in legacy industrial equipment while digital buses dominate new robotics designs.
- Analog:Continuous voltage outputs persist in retrofit industrial automation where PLC compatibility trumps precision. Legacy machine tool controllers in Germany and Japan specify 0-5V heading signals.
- Digital:SPI and I3C protocols simplify firmware integration for wearable and VR headset designers. Meta and Pico Interactive specify digital e-compass modules for inside-out tracking systems.
- Hybrid:Combined analog-digital outputs serve automotive tier suppliers bridging legacy and next-generation ECU architectures. Bosch and Continental qualify hybrid modules for platform flexibility.
- Inertial:9-degree-of-freedom fusion with accelerometers and gyroscopes enables attitude estimation without GPS. DJI and Skydio integrate inertial e-compass for drone magnetic heading in BVLOS operations.
Digital technology anchors the volume base while inertial fusion expands most quickly on UAV and robotics demand.
Application:
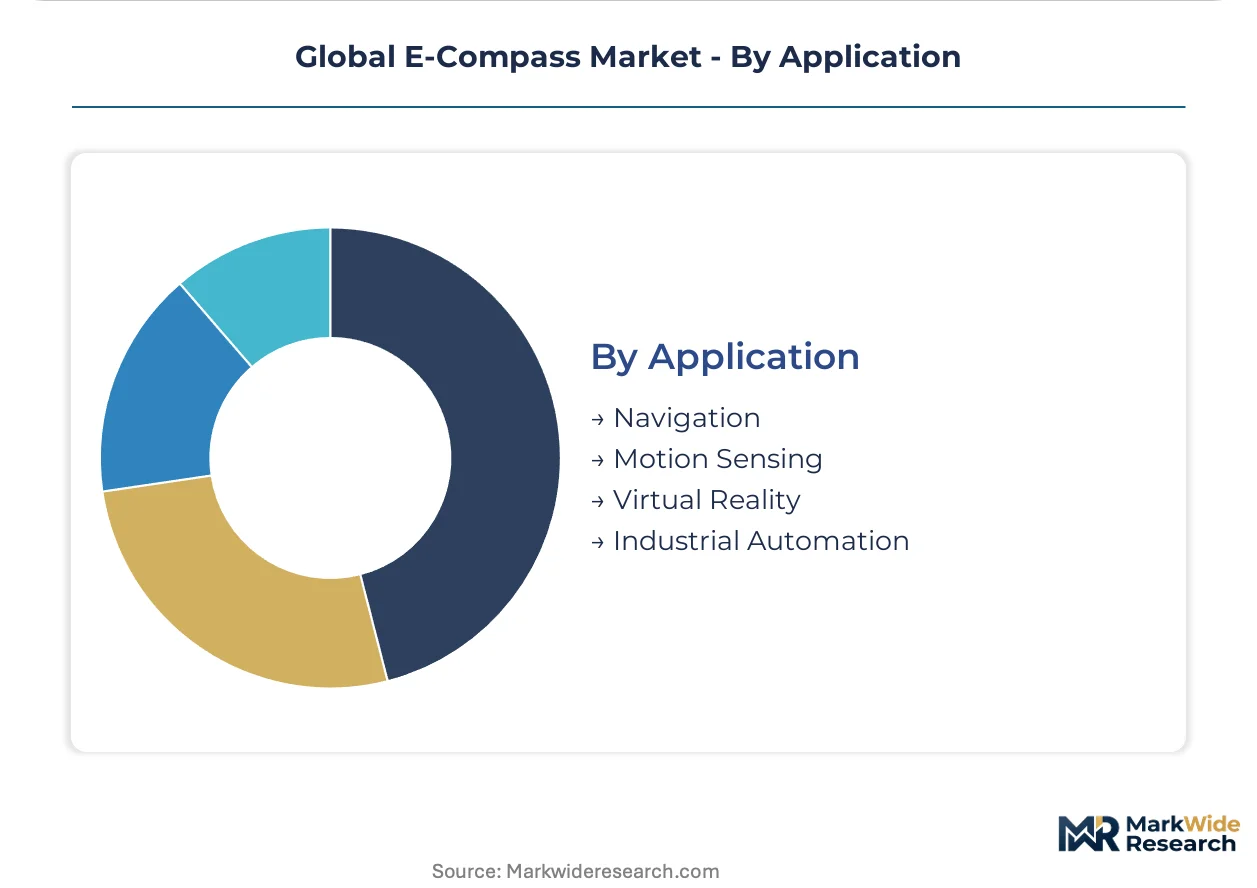
Use case determines accuracy requirements and environmental sealing specifications. Navigation tolerates degree-level error while VR demands sub-degree precision to prevent simulator sickness.
- Navigation:Absolute heading reference for GPS-denied environments drives fluxgate adoption in maritime and aviation. Wärtsilä and Kongsberg specify marine-grade magnetometers for dynamic positioning systems.
- Motion Sensing:Activity classification and gesture recognition in fitness wearables exploit low-power MEMS compass functions. Fitbit and Garmin design teams prioritize microamp current draw over absolute accuracy.
- Virtual Reality:Sub-degree heading precision prevents rotational drift in immersive displays. Sony and Valve source calibrated 9-axis modules from TDK InvenSense for PSVR and Index controllers.
- Industrial Automation:AGV path following and robotic arm calibration demand repeatable magnetic references. KUKA and FANUC specify IP67-sealed e-compass modules for factory floor deployment.
Navigation retains the largest installed base while virtual reality gains share fastest on headset shipment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eight-inch MEMS foundry capacity for e-compass modules clusters in Taiwan and South Korea, exposing procurement chains to regional equipment maintenance cycles and concentrating technical calibration expertise in specific industrial corridors.
United States
Beyond-visual-line-of-sight drone operators in California and Massachusetts deploy fluxgate magnetometers for magnetic heading reference where GPS multipath corrupts position fixes. The FAA mandates DO-160G electromagnetic interference testing for civil avionics integration, extending qualification cycles to 18-24 months. Minneapolis and Arizona host aerospace prime contractors supplying radiation-hardened designs to NASA and defense programs.
Germany
Automotive tier-one suppliers qualify tunnel magnetoresistance e-compass modules for 800-volt electric vehicle chassis control systems where battery pack interference corrupts legacy sensors. The KBA enforces type approval standards for magnetic sensor integration in safety-critical vehicle systems. Stuttgart and Munich anchor development clusters where Continental and Denso specify active compensation algorithms.
South Korea
Samsung Electronics and local robotics firms drive MEMS sensor procurement for 9-axis fusion modules in smartphones and autonomous mobile robots. The MFDS aligns medical device electromagnetic compatibility requirements with IEC 60747 semiconductor specifications. Seoul Capital Area foundries narrow cost gaps with European MEMS fabs through advanced packaging corridors.
Japan
Smartphone manufacturers integrate magnetic sensing for augmented reality wayfinding in GPS-denied indoor environments. METI enforces JIS C 0920 environmental sealing standards for outdoor robotics deployments. Tokyo and Osaka house precision fabrication facilities serving Sony and Nintendo VR headset programs demanding sub-degree heading accuracy.
China
Shenzhen contract manufacturers benefit from GB standard harmonization with IEC specifications, reducing redundant certification costs for cross-border component qualification. The State Administration for Market Regulation now accepts IEC test reports for electromagnetic compatibility. Yangtze River Delta packaging houses accelerate materials science investment under hazardous substance regulatory pressure.
Global E-Compass Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in MEMS fabrication and fluxgate winding. The vendor base organizes into three tiers: vertically integrated semiconductor houses with captive 8-inch foundries, fabless design firms licensing sensor fusion algorithms, and precision instrument specialists serving aerospace heritage programs. Consolidation pressure concentrates most visibly in automotive qualification capabilities and radiation-hardened heritage traceability. Competitive moves center on foundry capacity expansion for automotive-grade MEMS and strategic partnerships for 9-axis sensor fusion IP.
Among European vertically integrated semiconductor houses, STMicroelectronics exemplifies the foundry-capable archetype through its Agrate Brianza MEMS facility. Bosch Sensortec occupies a position within the consumer electronics design tier, while Honeywell International anchors the precision instrument segment serving aerospace and defense procurement channels with radiation-hardened fluxgate heritage.
| Leading Market Players |
|---|
| STMicroelectronics |
| Honeywell International |
| Asahi Kasei Microdevices |
| NXP Semiconductors |
| TDK Corporation |
| Bosch Sensortec |
| Robert Bosch |
| Murata |
| PNI Sensors |
| Others |
Supply Flow & Price Mechanics
Taiwanese 8-inch MEMS foundry concentration funnels pricing power toward automotive-grade module vendors with captive fabrication, while consumer electronics buyers extract sub-dollar unit economics through million-scale smartphone procurement commitments.
Pricing Analysis
EU REACH and RoHS directives dictate the pricing tier structure across hazardous substance compliance grades. Three-tier pricing structure across aerospace-certified fluxgate, automotive-grade TMR modules, and consumer MEMS separates vendors by qualification burden and traceability depth. Cost compression in consumer MEMS is intensifying because smartphone OEMs consolidate 9-axis fusion procurement around I3C-compliant suppliers. Robotics fleet operators exhibit the least price sensitivity due to sensor-as-a-subscription contracts that transfer obsolescence risk to vendors.
Supply Chain Analysis
TSMC and United Microelectronics anchor 8-inch wafer capacity for MEMS compass fabrication, with ASE Technology and Amkor handling advanced packaging for smartphone module integrators. Sputtering targets for magnetoresistive thin films draw from Chinese rare earth processing and Japanese precision coil winding. Single-source vulnerability concentrates in Taiwan equipment maintenance cycles that disrupt consumer-grade output. Distribution runs through Shenzhen contract manufacturers for consumer electronics and direct aerospace prime contracts for radiation-hardened fluxgate heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunnel magnetoresistance sensitivity breakthroughs are compressing the traditional segmentation between consumer MEMS and precision fluxgate tiers, creating margin redistribution opportunities across automotive and robotics procurement channels.
For Market Incumbents: Harden automotive qualification capabilities against 800-volt EV magnetic interference specifications through active compensation algorithm investment. Expand captive 8-inch MEMS foundry output in Agrate Brianza and South Korean packaging corridors to defend against fabless design firms licensing sensor fusion IP. Prioritize DO-160G heritage traceability for aerospace prime retention.
For New Entrants and Emerging Players: Build out subsea robotics navigation modules for Norwegian and Brazilian oilfield services contractors where acoustic positioning fails in deepwater trenching. Target India PLI scheme leverage for MEMS packaging investment in the Noida semiconductor corridor. Pursue sensor-as-a-subscription contracts with California warehouse automation fleets as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated semiconductor houses with automotive-grade MEMS fabrication capabilities and radiation-hardened fluxgate heritage traceability. Long-term viability centers on qualification moats that extend 18-24 month FAA certification cycles. Monitor I3C interface adoption velocity in wearable and VR headset design wins as the inflection indicator for consumer module consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade MEMS Foundry Expansion | Captures 800-volt EV chassis control procurement from Continental and Denso. |
| TMR Module Qualification for EV Applications | Displaces legacy Hall-effect sensors in German and Japanese Tier-1 supply chains. |
| Sensor-as-a-Subscription Model Deployment | Transfers obsolescence risk to vendors in California warehouse automation contracts. |
| Subsea Robotics Navigation Partnership | Supplies fluxgate magnetometers to Norwegian and Brazilian oilfield services contractors. |
| I3C Interface Standard Compliance | Reduces PCB footprint for Meta and Pico Interactive VR headset integration. |
Methodological Framework
A spread of perspectives from MEMS foundry operations managers, automotive Tier-1 procurement leads, aerospace prime subsystem engineers, and robotics fleet deployment specialists converged on the working assumptions. Primary interviews combined with secondary validation from FAA DO-160G filings, ECHA REACH substance restriction updates, SEC 10-K component revenue disclosures, and IHS Markit vehicle production databases. Bottom-up unit shipment modeling and top-down semiconductor equipment capex analysis provided triangulation across the analysis window.
Demand-supply balance framing anchored the forecast framework across product architecture, end-use environment, interface technology, and geographic manufacturing cluster segmentation. CAGRs derived from installed base replacement cycles, smartphone design win cadence, and EV platform rollout schedules. Electric vehicle magnetic interference specifications and GB standard harmonization timelines served as critical industry-specific forecast inputs throughout the modeling period.
Stress conditions across rare earth export quota volatility, Taiwan foundry equipment maintenance disruption, and FAA certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about TMR adoption velocity and I3C interface penetration. Quarterly review of automotive platform design win announcements and robotics fleet deployment scale indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Ozone Meter Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Americas Sensor Market