
 Thermal Imaging Market | 2026-2036
Thermal Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Imaging Market Analysis
The capability gap between defense-grade cooled systems and commercial uncooled arrays is rotating capital toward dual-use platforms. Teledyne FLIR leverages its vertically integrated sensor foundry to sustain pricing power across military and industrial tiers. BAE Systems anchors its position through classified supply relationships with UK and US defense ministries. Leonardo competes in European naval and airborne programs where ITAR-free status opens procurement pathways.
Thermal imaging captures infrared radiation emitted by objects and converts it into visible images using detector arrays sensitive to wavelengths between 7 and 14 micrometers, with uncooled vanadium oxide microbolometers now achieving noise-equivalent temperature differences below 50 millikelvin for commercial applications. The technology serves firefighting, predictive maintenance, perimeter security, and medical fever screening by revealing temperature anomalies invisible to standard cameras. Cameras dominate revenue flows where portable and fixed-mount units command premium pricing in industrial inspection and surveillance applications. Uncooled technology leads volume shipments as falling detector costs enable mass-market penetration in automotive night vision and building diagnostics. Cooled systems retain margin concentration in aerospace and defense where indium antimonide and mercury cadmium telluride detectors deliver superior thermal resolution.
US ITAR regulations and EU dual-use export controls shape competitive access to military-grade focal plane arrays and cryocooler assemblies. FDA 510(k) clearance requirements govern clinical thermography systems deployed for medical diagnostics in US healthcare settings. EAR and REACH compliance burdens favor established manufacturers with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor convergence between autonomous vehicle perception stacks and thermal sensing modules as automotive OEMs evaluate multispectral fusion architectures for pedestrian detection.
Market Dynamics
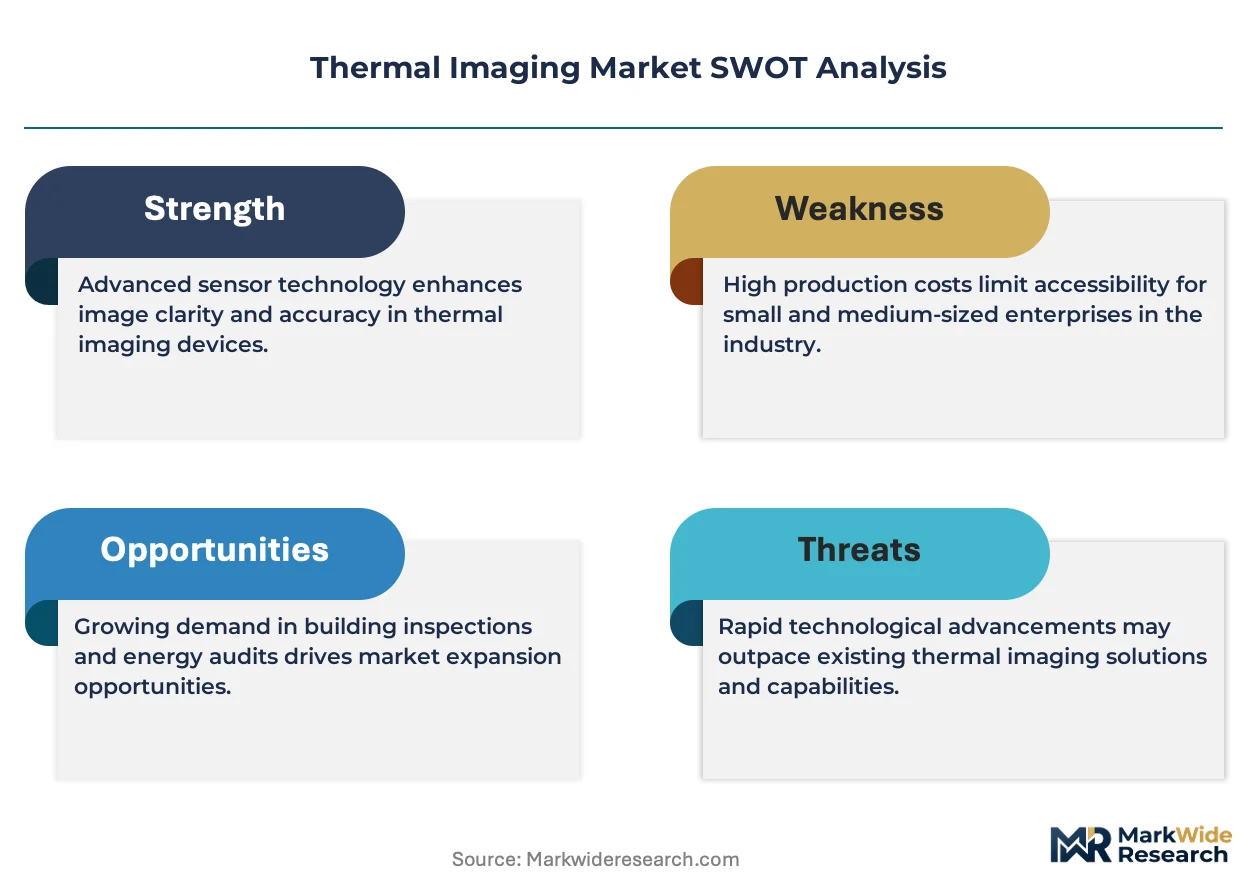
Uncooled microbolometer cost curves are collapsing detector pricing, rotating procurement toward volume applications and compressing margins for legacy cooled-array suppliers serving aerospace and defense primes.
Growth Catalysts
- Automotive night vision mandates:Euro NCAP pedestrian safety protocols are accelerating OEM integration of thermal sensing modules into premium vehicle platforms.
- REACH compliance automation:Industrial facilities across Germany deploy predictive maintenance cameras to monitor heat signatures in solvent-handling equipment and reduce unplanned downtime.
- Wildfire detection networks:California and Australia utility operators install fixed-mount thermal towers along transmission corridors to identify ignition events before propagation.
Market Restraints
- Indium supply concentration:Cooled detector manufacturing depends on Chinese indium refining capacity, exposing focal plane array costs to export quota volatility.
- ITAR licensing friction:US State Department controls on cryocooler assemblies delay foreign military sales approvals by 18-24 months.
- Silicon wafer substitution:Short-wave infrared sensors based on CMOS architectures threaten uncooled microbolometer penetration in machine vision below 2.5 micrometers.
Strategic Opportunities
- Medical thermography expansion:India's Ayushman Bharat digital health infrastructure creates procurement pathways for fever-screening terminals in district hospitals.
- Drone-mounted inspection:Convergence with LiDAR and hyperspectral imaging is opening utility-scale solar farm monitoring contracts.
- EU Green Deal thermal audits:Mandatory building energy certification across France and Italy drives demand for handheld diagnostic cameras among HVAC contractors.
Industry Challenges
- Detector calibration expertise:Field service networks lack technicians trained in non-uniformity correction algorithms for vanadium oxide arrays.
- FDA 510(k) documentation:Clinical thermography system approvals require multi-site temperature accuracy studies consuming 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Imaging Market |
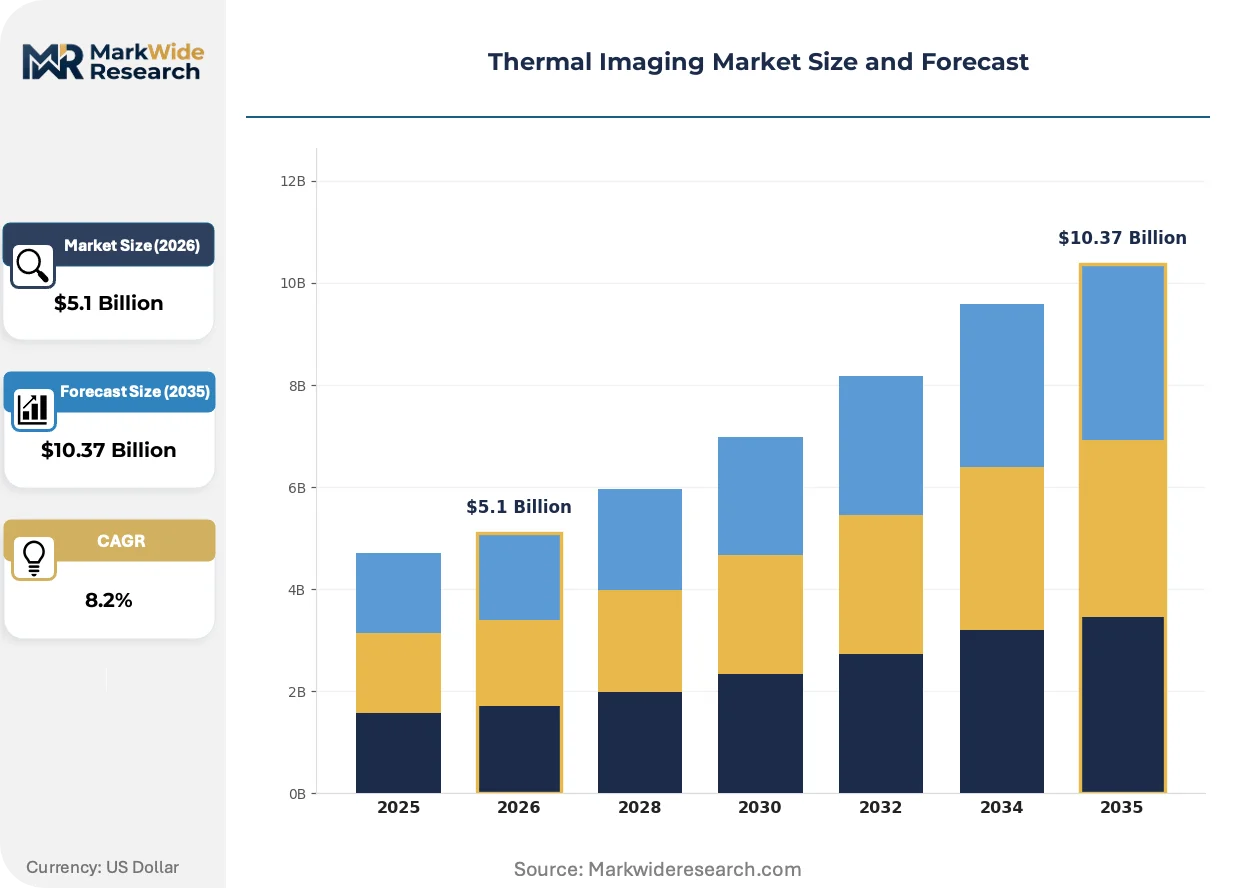
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.37 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Scanners, Software, Accessories Application: Building Inspection, Medical Diagnostics, Surveillance, Industrial Inspection End User: Healthcare, Security, Manufacturing, Automotive Technology: Uncooled, Cooled, Dual-Use, Thermal Sensors |
| Companies Covered | Teledyne FLIR, Fluke Corporation, Leonardo, BAE Systems, L3Harris Technologies, Axis Communications, Testo SE & Co. KGaA, Seek Thermal, Opgal Optronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Imaging Market Emerging Trajectories
Wafer-level packaging and 12-inch MEMS foundry transitions are reshaping cost structures, while regulatory pressure on building efficiency and automotive safety creates new specification tiers.
Wafer-level vacuum packaging for microbolometers is displacing traditional ceramic package assemblies in commercial camera modules. Automotive Tier-1 suppliers in Japan and Germany are qualifying these devices for 10-year operational life. The shift compresses bill-of-materials costs by eliminating discrete vacuum enclosures and hermetic sealing steps.
EU F-Gas Regulation phase-down schedules are accelerating adoption of sterling-cycle cryocoolers in place of reciprocating compressors using hydrofluorocarbon working fluids. Leonardo and Thales naval programs specify these units for maritime surveillance pods. The transition extends maintenance intervals from 2,000 to 8,000 hours but requires redesign of cold-finger interfaces.
Industrial buyers are consolidating supplier relationships around vendors offering integrated analytics platforms rather than standalone hardware. Predictive maintenance contracts in US oil refining now bundle thermal cameras with cloud-based anomaly detection. This bundling concentrates purchasing authority with reliability engineering departments and reduces procurement autonomy at plant level.
Thermal Imaging Market Segmentation
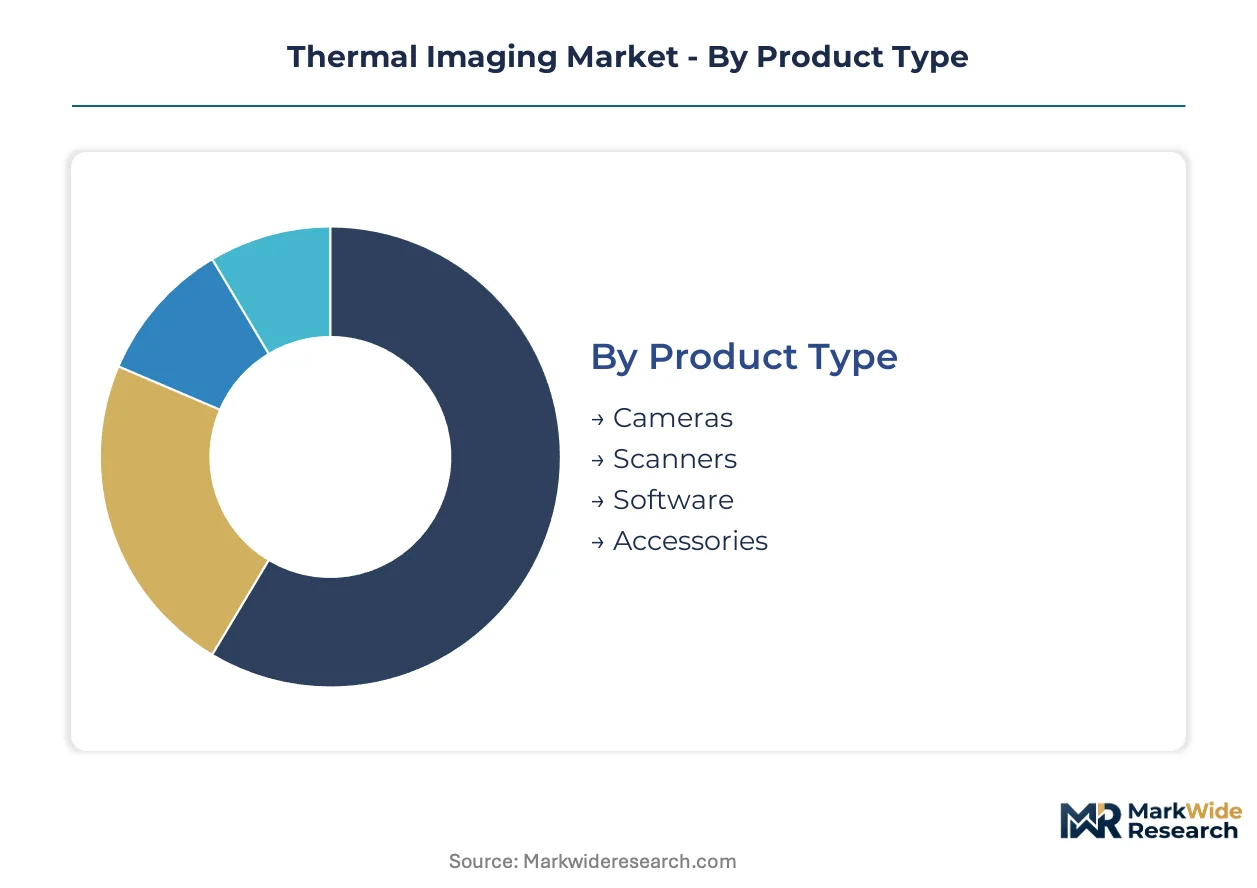
Thermal imaging procurement channels diverge sharply by product complexity and certification requirements. Industrial buyers favor bundled hardware-software solutions through systems integrators, while defense and medical segments demand direct manufacturer relationships for compliance documentation.
Product Type:
Camera systems move through distributor networks serving industrial maintenance contractors, while software and accessories concentrate in direct OEM channels where integration support determines contract awards.
- Cameras:Portable and fixed-mount units incorporate vanadium oxide microbolometer or indium antimonide detector arrays with resolutions from 320x240 to 1280x1024 pixels. Manufacturing facilities in Germany and Japan account for the majority of procurement volume as predictive maintenance programs expand under REACH-mandated equipment monitoring protocols.
- Scanners:Handheld diagnostic devices with integrated temperature mapping software target HVAC contractors and building energy auditors. France and Italy exhibit concentrated demand following EU Green Deal thermal audit mandates for commercial building certification.
- Software:Cloud-based anomaly detection platforms bundle with predictive maintenance contracts.
- Accessories:Lens assemblies, mounting hardware, and calibration targets complete system deployments.
Cameras dominate installed base. Software is where expansion concentrates.
Application:
Margin profiles vary substantially across use cases, with aerospace and defense applications commanding premium pricing for ITAR-compliant systems while building inspection faces commoditization from low-cost Asian suppliers.
- Building Inspection:Energy auditors and HVAC contractors deploy handheld thermal cameras to identify insulation defects and air leakage. German industrial facilities lead procurement volume under automated REACH compliance monitoring requirements for solvent-handling equipment.
- Surveillance:Perimeter security and naval airborne programs specify cooled detector arrays for long-range target identification. UK and US defense ministries anchor demand through classified supply relationships requiring cryocooler assemblies with extended maintenance intervals.
- Medical Diagnostics:Fever-screening terminals and clinical thermography systems require FDA 510(k) clearance or equivalent national regulator approval.
- Industrial Inspection:Predictive maintenance programs in oil refining and utility operations drive recurring camera purchases.
Surveillance commands the highest unit margins. Building inspection is climbing the fastest.
End User:
Customer sophistication determines purchasing authority concentration, with enterprise manufacturing buyers consolidating supplier relationships around analytics platforms while healthcare procurement fragments across district hospital networks.
- Manufacturing:Reliability engineering departments bundle thermal cameras with cloud-based monitoring platforms. US oil refining and German chemical processing operations concentrate demand for integrated predictive maintenance solutions.
- Security:Government agencies and critical infrastructure operators specify ITAR-compliant or ITAR-free systems depending on procurement jurisdiction. NATO member states and allied nations drive cooled system acquisitions for infrared surveillance programs.
- Healthcare:India's Ayushman Bharat digital health infrastructure creates procurement pathways for fever-screening terminals in district hospitals.
- Automotive:Tier-1 suppliers in Japan and Germany qualify wafer-level packaged microbolometers for 10-year operational life in night vision systems.
Manufacturing leads current revenue flows. Automotive represents the steepest expansion trajectory.
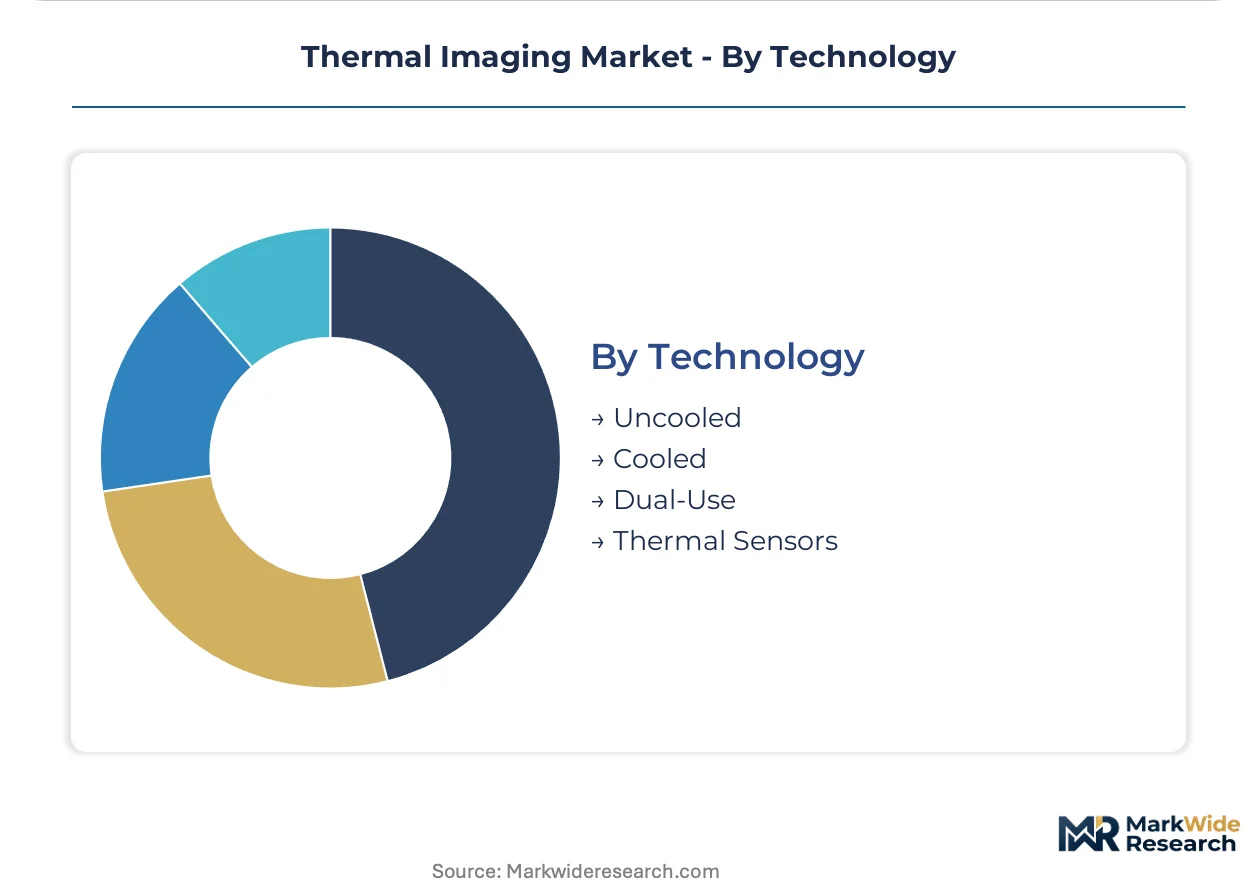
Technology:
Cost tier separation between cooled and uncooled architectures shapes competitive positioning, with wafer-level packaging transitions collapsing microbolometer pricing while indium supply constraints protect cooled system margins.
- Uncooled:Vanadium oxide microbolometers achieve noise-equivalent temperature differences below 50 millikelvin for commercial applications. Wafer-level vacuum packaging eliminates discrete enclosures, compressing bill-of-materials costs and enabling mass-market penetration in automotive night vision and building diagnostics.
- Cooled:Indium antimonide and mercury cadmium telluride detectors deliver superior thermal resolution for aerospace and defense applications. Chinese indium refining capacity concentration exposes focal plane array costs to export quota volatility.
- Dual-Use:Platforms bridge defense-grade performance with commercial cost structures.
- Thermal Sensors:Discrete detector arrays supply integration into autonomous vehicle perception stacks and multispectral fusion architectures.
Uncooled systems dominate volume shipments. Cooled arrays retain margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in thermal imaging hardware tilt toward net importers across NATO defense procurement networks, while wafer-level packaging investments in Japan and Germany rotate regional supply positions. Chinese indium refining concentration shapes cooled detector cost exposure for European and North American integrators.
United States
Defense procurement agencies drive cooled system acquisitions through classified supply relationships with aerospace primes. ITAR licensing controls on cryocooler assemblies constrain foreign military sales timelines. Industrial automation investments in Texas and Louisiana oil refining corridors concentrate predictive maintenance camera deployment.
Germany
REACH-mandated equipment monitoring protocols accelerate thermal camera adoption in chemical processing and solvent-handling facilities. EU F-Gas Regulation phase-down schedules push sterling-cycle cryocooler specifications for naval surveillance programs. Bavarian automotive Tier-1 suppliers qualify wafer-level packaged microbolometers for night vision integration.
Japan
METI-backed industrial automation initiatives channel procurement toward integrated thermal monitoring platforms in precision manufacturing. JIS standards compliance requirements filter supplier qualification for building diagnostic equipment. Nagoya-area automotive clusters drive 10-year operational life specifications for night vision sensor modules.
India
Ayushman Bharat digital health infrastructure creates procurement pathways for fever-screening terminals across district hospital networks. CDSCO regulatory pathways for clinical thermography systems remain underdeveloped relative to FDA 510(k) benchmarks. Maharashtra and Karnataka medical device manufacturing zones attract contract assembly partnerships.
United Kingdom
Ministry of Defence infrared surveillance programs anchor demand for ITAR-compliant cooled detector arrays. Classified supply relationships with BAE Systems and transatlantic primes structure procurement access. Scottish and Northern England industrial zones concentrate predictive maintenance service provider networks for North Sea energy assets.
Thermal Imaging Market Vendor Landscape
Concentration sits with vertically integrated sensor foundries and defense-aerospace conglomerates holding classified supply relationships. The vendor base stratifies across three tiers: premium defense-grade cooled system suppliers, mid-market industrial camera manufacturers, and emerging wafer-level packaging specialists serving automotive volume applications. Dominant competitive moves include M&A activity targeting MEMS foundry capacity and strategic partnerships bundling hardware with cloud-based analytics platforms.
Among defense-aerospace conglomerates, BAE Systems, Leonardo, and L3Harris Technologies occupy positions shaped by ITAR compliance requirements and NATO procurement access. Teledyne FLIR and Fluke Corporation exemplify the industrial-commercial tier where predictive maintenance bundling and distributor network scale determine contract capture. Seek Thermal and Opgal Optronic Industries sit within emerging specialist segments addressing volume automotive and perimeter security applications.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Fluke Corporation |
| Leonardo |
| BAE Systems |
| L3Harris Technologies |
| Axis Communications |
| Testo SE & Co. KGaA |
| Seek Thermal |
| Opgal Optronic Industries |
| Others |
Supply Flow & Price Mechanics
Wafer-level packaging scale economies in Japanese and German MEMS foundries are compressing unit costs for uncooled microbolometers while simultaneously concentrating supply among three dominant substrate suppliers. This scale dynamic establishes price floors that legacy cooled-array manufacturers cannot match without sacrificing cryocooler assembly margins.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade—FDA 510(k) versus industrial CE marking—and volume scale differentiate price bands. Cost compression in the uncooled tier is intensifying because wafer-level vacuum packaging eliminates discrete enclosure assembly. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to 10-year operational life specifications, while HVAC contractors in building diagnostics show highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Chinese indium refining capacity concentration exposes focal plane array costs to export quota volatility. Cooled detector manufacturing draws from Chinese indium, Japanese mercury cadmium telluride substrate production, and US cryocooler assembly operations. Single-source vulnerability in rare earth refining creates procurement risk for aerospace and defense integrators. Distribution runs through defense primes for ITAR-compliant systems and industrial distributors for commercial cameras.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across thermal imaging as automotive night vision mandates and EU Green Deal thermal audit requirements create specialized procurement niches distinct from legacy defense and industrial channels.
For Market Incumbents: Secure MEMS foundry capacity through captive supply arrangements or long-term offtake agreements with Japanese and German substrate manufacturers. Certification investment in FDA 510(k) pathways for clinical thermography creates defensive moats against low-cost Asian suppliers entering medical diagnostics. Vertical integration into wafer-level packaging preserves margin position as standard ceramic assemblies commoditize. For New Entrants and Emerging Players: Differentiate on analytics bundling rather than hardware specifications. India's Ayushman Bharat fever-screening terminal procurement represents the most penetrable geography-application combination. Cloud-based anomaly detection platforms integrated with handheld scanners offer a direct go-to-market angle bypassing established distributor relationships in mature markets. For Investors and Strategic Acquirers: Wafer-level packaging specialists with automotive qualification credentials represent the priority acquisition archetype. Long-term viability hinges on exposure to volume automotive night vision rather than defense program dependency. Sterling-cycle cryocooler adoption rates in EU naval programs signal inflection timing for cooled system margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Japanese MEMS foundries achieving automotive qualification compress bill-of-materials costs below ceramic assembly alternatives. |
| FDA 510(k) Certification Pathway | Clinical thermography system approvals require multi-site temperature accuracy studies consuming 14-18 months. |
| Automotive Tier-1 Partnership | German and Japanese suppliers qualifying 10-year operational life specifications for night vision integration. |
| Cloud Analytics Platform Integration | US oil refining predictive maintenance contracts bundle thermal cameras with anomaly detection software. |
| Sterling-Cycle Cryocooler Transition | EU F-Gas Regulation phase-down extends maintenance intervals from 2,000 to 8,000 hours for naval surveillance pods. |
Methodological Framework
Desk research of customs trade data, SEC 10-K filings, and EU defense procurement notices preceded structured interviews with reliability engineering directors, automotive Tier-1 procurement managers, and thermal camera distributor principals. Primary fieldwork with plant engineers and predictive maintenance service providers combined with secondary validation against FDA 510(k) clearance databases and REACH compliance monitoring protocols. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Variance decomposition across technology type, application vertical, and geographic regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include detector architecture, end-use industry, certification tier, and procurement channel structure. CAGRs derived from curve-fitting historical price elasticity patterns against projected wafer-level packaging cost trajectories. Indium supply quota volatility and Euro NCAP pedestrian safety protocol adoption curves served as industry-specific forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in US ITAR licensing regimes and EU dual-use export controls; material policy shifts would require re-modeling foreign military sales timelines and cryocooler assembly procurement access. Practitioners should keep alternative scenarios live as Chinese rare earth export restrictions and automotive OEM platform standardization decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Short-Wave Infrared Imaging Market
Imaging
Global Waterproof Camera Market
Imaging
Global Microbolometer Market
Imaging
Near Infra-Red Imaging Market
Imaging
Global Mobile Image Sensor Market
Imaging
Hybrid Imaging Market
Imaging
IR Camera Market
Imaging
Video Microscopes Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
India CCTV Camera Market
Imaging
Global Document Scanner Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Global Ingaas Camera Market
Imaging
Global Cell Imagers Market
Imaging
Low-Light Imaging Market