
 IR Camera Market | 2026-2036
IR Camera Market Size, Share, and Industry Trends Forecast 2026-2036
IR Camera Market Outlook
Market Context
Japanese sensor foundries and German optics houses is consolidating the supply base for high-resolution focal plane arrays. L3Harris Technologies leverages captive semiconductor fabrication to sustain margins on military-grade cooled systems. Teledyne FLIR anchors the commercial segment through vertical control over lens-to-software pipelines. Hikvision Digital Technology competes aggressively on uncooled unit economics for perimeter surveillance networks.
Technical Definition and Segment Structure
An IR camera detects infrared radiation emitted by objects and converts thermal energy into visible images, typically operating across wavelengths from 0.75 to 14 micrometers depending on detector material and cooling architecture. These devices serve critical functions in non-contact temperature measurement, night vision, and predictive maintenance across industrial and security environments. Handheld and fixed installations dominate volume, though thermal imaging platforms command premium pricing in aerospace and medical diagnostics where spatial resolution requirements exceed 640x512 pixels. Uncooled technology leads unit shipments for building inspection and security applications, while cooled systems retain structural margin pools in defense and scientific research.
Regulatory Framework
The US FDA governs medical thermal imaging claims for breast cancer screening adjuncts, while the FCC regulates radio-frequency emissions from wireless-enabled surveillance cameras. The EU AI Act and GDPR impose algorithmic transparency and biometric data restrictions on facial recognition deployments using infrared sensors. Stakeholders must monitor divergence between US export control regimes under the Department of Commerce and EU dual-use regulations affecting cooled detector shipments to non-NATO buyers.
Market Dynamics
Defense procurement programs across NATO member states are accelerating cooled infrared sensor deployments while uncooled microbolometer advances compress unit costs for commercial firefighting and building inspection applications.
Growth Catalysts
- EU Green Deal building mandates:Tightened thermal imaging regulations for energy audits across Germany, France, and Italy are mandating IR camera deployment in commercial real estate assessments.
- Automotive night-vision standards:NHTSA pedestrian safety guidelines in the United States are pushing OEM integration of thermal imaging into advanced driver-assistance systems.
- Wildfire management protocols:Extended fire seasons in Australia and California are expanding aerial thermal imaging contracts for hotspot detection and perimeter monitoring.
Market Restraints
- Germanium lens supply concentration:Chinese rare earth processing dominance creates input cost volatility for high-performance IR optics manufacturers.
- Export control divergence:US Department of Commerce dual-use regulations and EU export regimes create compliance friction for cooled detector shipments to non-NATO buyers.
- Visible-light AI substitution:Low-light CMOS sensors with computational enhancement threaten price-sensitive security camera segments.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for electronics manufacturing are attracting IR component assembly investments to offset import dependency.
- Medical diagnostics expansion:FDA-cleared thermal imaging protocols for diabetic foot ulcer screening open clinical reimbursement pathways in US hospital systems.
- Drone-mounted inspection services:Utility-scale solar farm operators are adopting thermal survey subscriptions rather than capital equipment purchases.
Industry Challenges
- Detector fabrication talent scarcity:Compound semiconductor process engineers with mercury cadmium telluride expertise command premium wages across US and European foundries.
- GDPR biometric compliance:Facial recognition deployments using infrared sensors face algorithmic transparency documentation requirements that extend sales cycles in EU markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IR Camera Market |
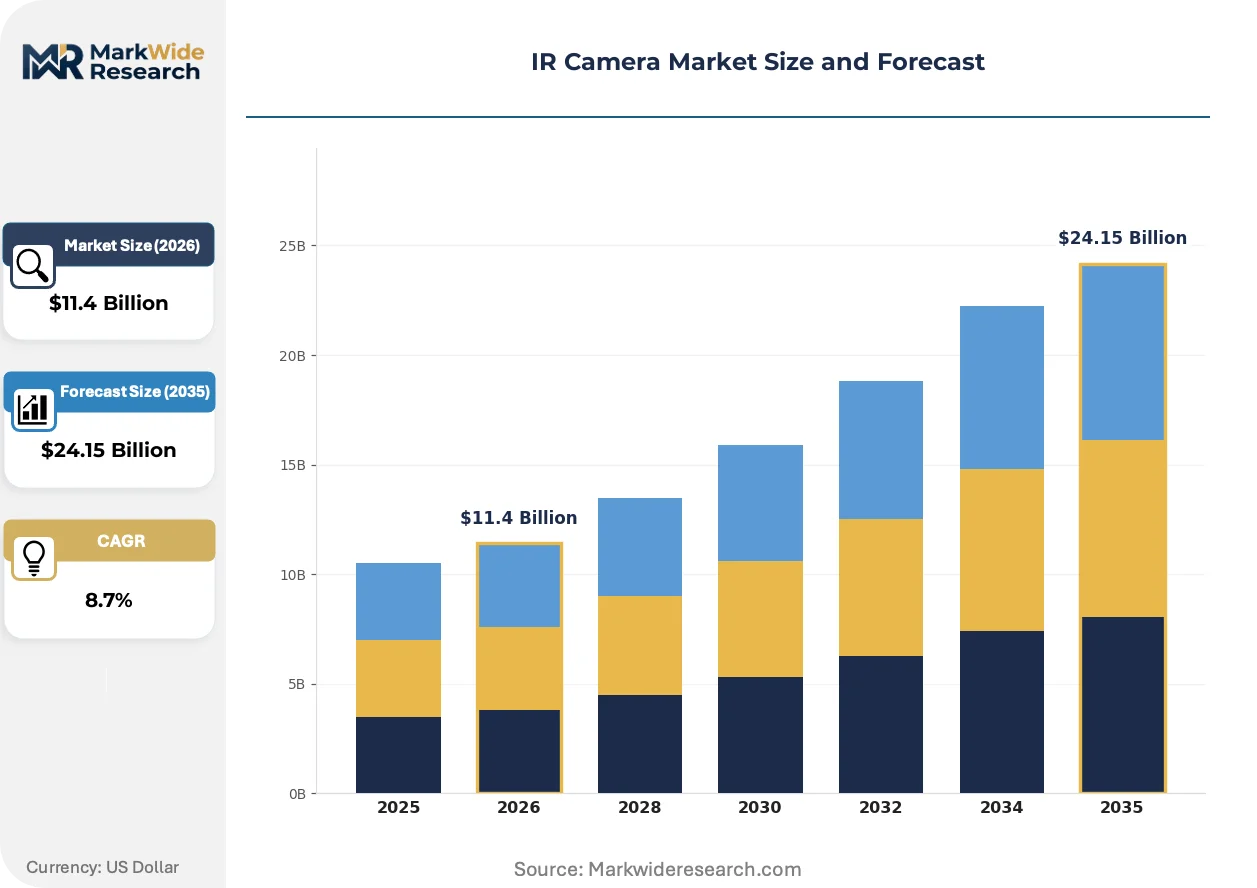
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Thermal Imaging, Mounted End User: Aerospace, Manufacturing, Surveillance, Automotive Technology: Uncooled, Cooled, Near-Infrared, Short-Wave Application: Firefighting, Building Inspection, Medical, Security |
| Companies Covered | L3Harris Technologies, Inc., Hikvision Digital Technology Co., Ltd., Teledyne FLIR LLC, Opgal Optronic Industries Ltd., RTX, Fluke Corporation, Axis Communications AB, Jenoptik AG, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IR Camera Market Strategic Shifts
Silicon-based wafer-level packaging is collapsing form factors and cost structures across the uncooled segment while regulatory mandates in automotive and building sectors create specification pull-through.
Wafer-level vacuum packaging is decentralizing thermal camera manufacturing by enabling foundry-direct module supply to system integrators. Automotive Tier 1 suppliers in Germany and Japan are adopting these modules for night-vision system integration. The technology is decentralizing supply chain control from traditional camera houses to semiconductor fabricators.
The EU AI Act imposes algorithmic transparency and biometric data restrictions on facial recognition deployments using infrared sensors. Industrial security integrators must now document training data provenance and decision logic for thermal-based identification systems. German perimeter surveillance networks are responding by segregating detection-only thermal analytics from identification functions.
Utility procurement teams are unbundling thermal inspection from capital equipment ownership through drone-as-a-service contracts. Solar farm operators in Spain and Texas are replacing handheld camera purchases with subscription-based aerial thermography. This model compresses vendor selection criteria toward flight-hour pricing and data analytics quality rather than hardware specifications.
IR Camera Market Segmentation
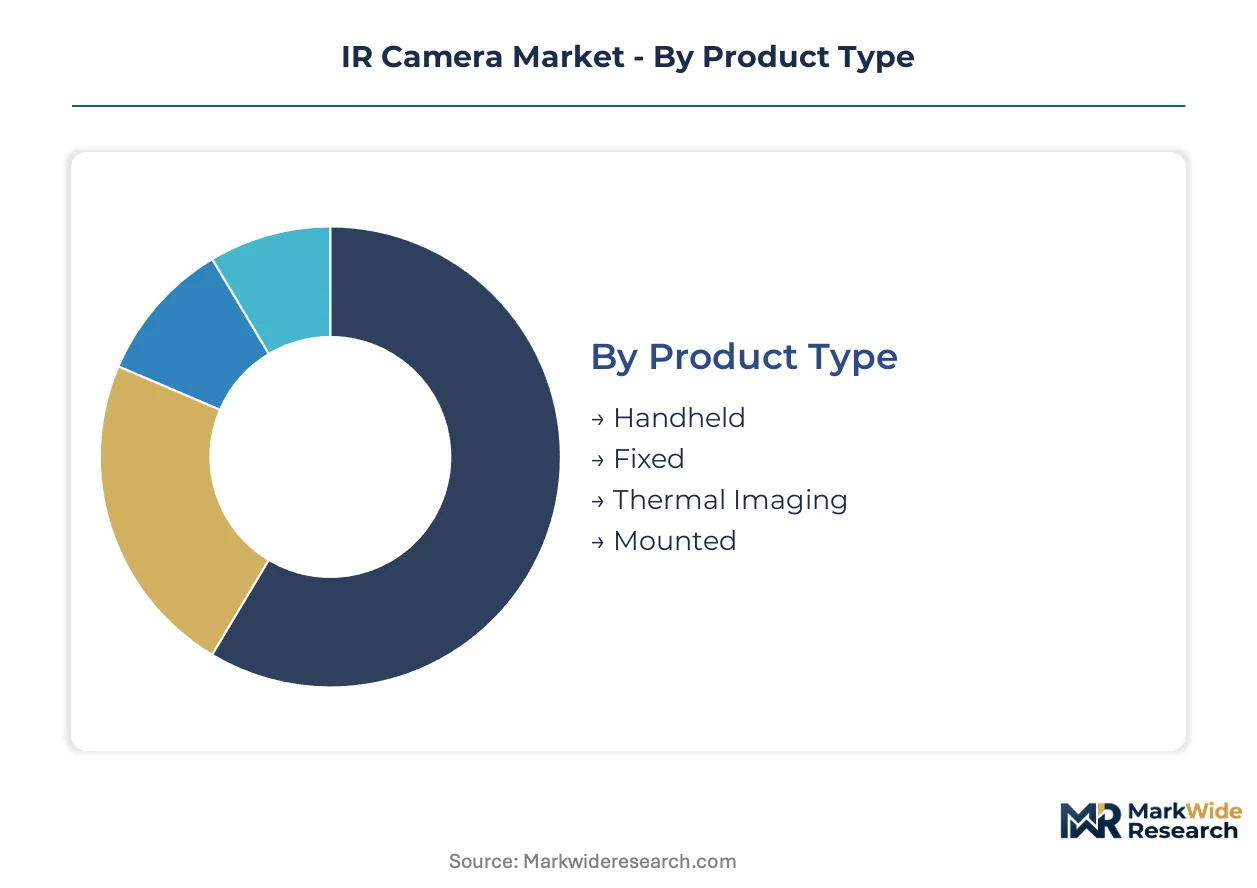
IR camera segmentation reveals divergent margin structures across cooling architectures and mounting configurations. Procurement patterns in defense, automotive, and building sectors pull specifications toward incompatible performance tiers.
Product Type:
Customization intensity varies sharply across portable versus installed configurations, with handheld units demanding ruggedization trade-offs that fixed installations avoid.
- Handheld:Battery-powered portable units with shock-resistant housings and simplified user interfaces prioritize field durability over laboratory precision. Fire departments in California and utility inspectors across Texas concentrate procurement here, driven by OSHA thermal safety mandates for electrical maintenance crews.
- Fixed:Permanently mounted installations with continuous power and network connectivity enable automated alarming and integration with building management systems. Perimeter surveillance networks in Germany and manufacturing facilities across Japan anchor demand, responding to EU AI Act biometric compliance requirements that favor stationary over mobile deployments.
- Thermal Imaging:High-resolution platforms exceeding 640x512 pixels serve aerospace diagnostics and medical screening where spatial discrimination determines utility.
- Mounted:Vehicle-integrated systems with stabilized optics and real-time video output support automotive night-vision and aerial firefighting applications.
Most installed capacity flows through Fixed systems. Expansion is steepest in Mounted configurations.
End User:
Cost tier separation distinguishes mission-critical aerospace specifications from price-sensitive security deployments.
- Aerospace:Cooled detector systems with cryogenic stabilization and MIL-STD-810G qualification support satellite thermal mapping and aircraft engine diagnostics. NASA and ESA procurement programs concentrate demand, constrained by ITAR and EU dual-use export controls on focal plane array technology.
- Manufacturing:Predictive maintenance applications prioritize uncooled microbolometers for electrical panel inspection and process monitoring. Automotive plants across Germany and semiconductor fabs in Japan drive volume, responding to ISO 18434-1 thermal monitoring standards for rotating equipment.
- Surveillance:Perimeter detection and facial recognition systems balance detection range against GDPR algorithmic transparency requirements in EU deployments.
- Automotive:Night-vision integration into advanced driver-assistance systems faces NHTSA pedestrian safety guideline compliance thresholds in the United States.
Manufacturing absorbs the highest unit volumes. Aerospace commands the steepest price premiums.
Technology:
Volume concentration sits with uncooled architectures while margin pools concentrate in cooled systems requiring exotic materials.
- Uncooled:Microbolometer arrays operating at ambient temperature eliminate Stirling cycle coolers and their maintenance burdens. Building inspectors across France and security integrators in India drive adoption, enabled by wafer-level vacuum packaging cost reductions from foundries in Japan.
- Cooled:Mercury cadmium telluride and indium antimonide detectors with mechanical refrigeration achieve noise-equivalent temperature differences below 25 millikelvin. NATO defense procurement programs and scientific research facilities in Germany and the United States sustain demand despite germanium lens supply volatility.
- Near-Infrared:Silicon-based sensors covering 0.75-1.4 micrometers serve semiconductor wafer inspection and agricultural monitoring applications.
- Short-Wave:InGaAs detectors for 0.9-1.7 micrometer spectroscopy and moisture detection in pharmaceutical manufacturing.
Uncooled technology dominates unit shipments. Cooled systems are gaining share fastest in defense modernization cycles.
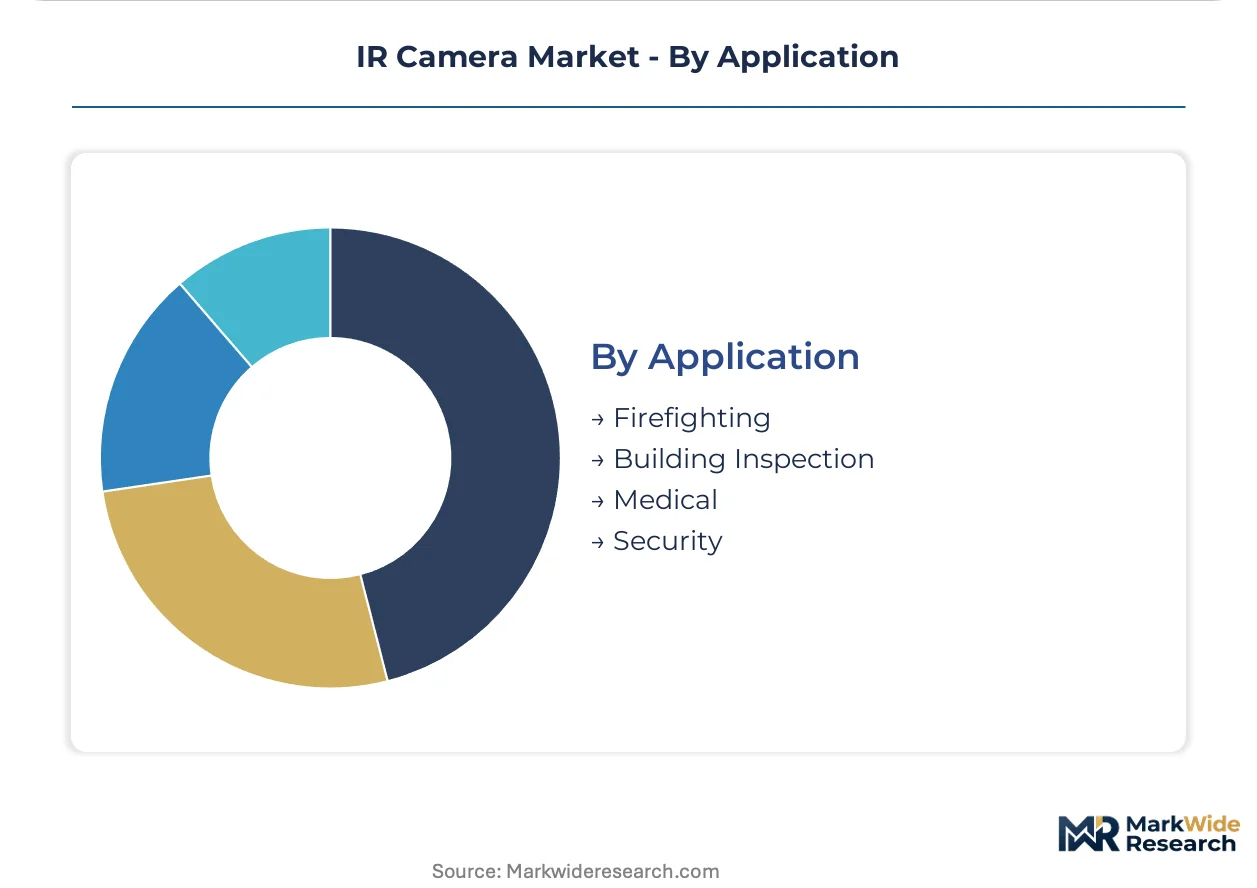
Application:
Customer type separation distinguishes subscription-based inspection services from capital equipment purchasers.
- Firefighting:Thermal imaging cameras penetrating smoke and darkness for victim location and hotspot identification. Extended fire seasons in Australia and California have expanded aerial thermal imaging contracts, with agencies prioritizing TIC durability standards from NFPA 1801.
- Building Inspection:Energy audit compliance under EU Green Deal mandates across Germany, France, and Italy requires IR camera deployment for thermal bridging detection and insulation assessment. Commercial real estate assessors face tightened regulations driving replacement cycles.
- Medical:FDA-cleared thermal imaging for diabetic foot ulcer screening and breast cancer screening adjuncts opens clinical reimbursement pathways in US hospital systems.
- Security:Perimeter monitoring and facial recognition deployments navigate GDPR biometric data restrictions and EU AI Act algorithmic transparency requirements.
Building Inspection represents the largest installed base. Medical applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting IR camera assembly toward jurisdictions with streamlined export licensing and localized semiconductor incentives. Foundries in Japan and assembly operations in India capture investment flows that bypass stricter dual-use controls elsewhere.
United States
Defense modernization programs at the Pentagon and NASA thermal mapping contracts sustain demand for cooled detector systems. The Department of Commerce administers dual-use export controls that constrain focal plane array shipments to non-NATO buyers. Greater Boston hosts scientific research facilities and mercury cadmium telluride process engineering talent pools.
Germany
Automotive Tier 1 suppliers integrate uncooled modules for night-vision systems while building inspectors face EU Green Deal energy audit mandates. The KBA enforces pedestrian safety standards that align with NHTSA guidelines for thermal driver-assistance features. Bavaria concentrates optics houses and focal plane array packaging operations.
China
Perimeter surveillance networks and utility-scale solar farm inspections drive uncooled microbolometer volume. MIIT oversees semiconductor fabrication licensing while SAMR monitors anti-competitive practices in security equipment markets. Yangtze River Delta foundries supply wafer-level vacuum packaging for cost-sensitive export modules.
Japan
Automotive night-vision integration and semiconductor fab process monitoring sustain demand for high-resolution platforms. METI coordinates industrial technology roadmaps that prioritize silicon-based sensor development. Nagoya and Tokyo house sensor foundries consolidating supply bases for microbolometer arrays.
India
Production-linked incentive schemes attract IR component assembly investments to reduce import dependency for perimeter security and firefighting applications. The BIS certifies equipment standards for thermal imaging cameras deployed in electrical maintenance. Gujarat and Maharashtra host emerging electronics manufacturing clusters.
IR Camera Market Competitive Environment
United States producers anchor the defense-tier segment; German and Japanese specialists hold automotive and industrial positions. The vendor base separates into three tiers: integrated defense contractors with captive semiconductor fabrication, commercial camera houses with lens-to-software pipelines, and cost-focused security equipment suppliers. Strategic moves concentrate on backward integration into detector manufacturing and geographic expansion through localized assembly partnerships.
Among defense-anchored contractors, L3Harris Technologies, Inc. exemplifies the captive-fabrication archetype, while Teledyne FLIR LLC occupies a position spanning commercial and dual-use segments. Hikvision Digital Technology Co., Ltd. represents the scale-driven, cost-optimized tier for perimeter surveillance deployments. These three sit within distinct competitive vectors that rarely overlap in procurement specifications.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Hikvision Digital Technology Co., Ltd. |
| Teledyne FLIR LLC |
| Opgal Optronic Industries Ltd. |
| RTX |
| Fluke Corporation |
| Axis Communications AB |
| Jenoptik AG |
| Leonardo S.p.A. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal energy audit mandates across Germany, France, and Italy are forcing commercial real estate assessors toward higher-resolution uncooled systems, compelling foundries in Japan to expand wafer-level vacuum packaging capacity and compressing mid-tier pricing through volume scale effects.
Pricing Analysis
Distributor margins on handheld firefighting and building inspection units absorb 15-25 points before reaching municipal procurement teams and electrical maintenance contractors. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810G qualified cooled systems from commercial microbolometers and entry-level perimeter cameras. Cost compression in the uncooled segment runs through Chinese rare earth processing dominance and silicon-based packaging migration. Municipal fire departments exhibit the highest price sensitivity, while NATO defense procurement programs demonstrate inelastic demand for cryogenically stabilized focal plane arrays.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, pulling component assembly from import-dependent configurations toward Gujarat and Maharashtra electronics clusters. Detector fabrication concentrates in Japan, Germany, and the United States, with germanium lens finishing tethered to Chinese rare earth processing. Mercury cadmium telluride epitaxy, indium antimonide substrates, and vacuum-packaged microbolometer wafers constitute critical input dependencies. Single-source vulnerability in germanium supply creates input cost volatility for high-performance IR optics manufacturers. Distribution runs through defense contractors with captive fabrication, commercial camera houses with lens-to-software pipelines, and cost-focused security equipment suppliers serving perimeter surveillance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities separate India's PLI-driven assembly cost structure from EU regulatory compliance premiums, rewarding localized production for export into Middle Eastern and African perimeter security markets.
For Market Incumbents: To counter visible-light CMOS substitution in price-sensitive security segments, L3Harris Technologies and Teledyne FLIR should deepen backward integration into mercury cadmium telluride fabrication for defense-tier margin defense, while expanding wafer-level packaging partnerships with Japanese foundries to compress uncooled unit costs for commercial firefighting and building inspection procurement cycles. For New Entrants and Emerging Players: Drone-as-a-service thermal inspection providers represent an underserved buyer archetype unbundling hardware ownership from flight-hour subscriptions, offering white-space entry through utility-scale solar farm operators in Spain and Texas seeking data analytics quality over capital equipment specifications, with go-to-market traction through EPC contractor partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with compound semiconductor process engineering talent pools possessing mercury cadmium telluride expertise, where long-term viability over a five-to-ten year window hinges on defense modernization cycles and scientific research facility procurement; acquisition targets should show captive fabrication or exclusive foundry relationships, with ITAR and EU dual-use export control friction as the inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Vacuum Packaging Expansion | Japanese foundries decentralize supply chain control from traditional camera houses to semiconductor fabricators. |
| Backward Integration into Detector Fabrication | L3Harris sustains margins on military-grade cooled systems through captive mercury cadmium telluride production. |
| Drone-as-a-Service Partnership Development | Utility-scale solar farm operators in Spain and Texas adopt subscription-based aerial thermography over capital purchases. |
| PLI Scheme Localization Investment | India's electronics manufacturing clusters attract IR component assembly to reduce import dependency. |
| GDPR-Compliant Analytics Segregation | German perimeter surveillance networks separate detection-only thermal analytics from identification functions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, commercial security integrators, automotive Tier 1 supplier engineers, building inspection contractors, and semiconductor foundry operations managers with secondary validation through SEC 10-K filings, EU dual-use export control registries, FDA 510(k) clearance databases, and customs trade data. Bottom-up unit shipment modeling and top-down value triangulation anchored market size estimates.
Historical reference periods spanning the decade preceding the analysis window established baseline growth trajectories and volatility patterns. The projection framework modeled segmentation dimensions across cooling architecture, mounting configuration, end-use sector, and regional regulatory cluster. CAGRs derived from regression analysis against defense budget cycles, building energy audit mandate implementation timelines, and automotive night-vision integration roadmaps. Forecast inputs incorporated NATO procurement program announcements, EU Green Deal enforcement schedules, and NHTSA pedestrian safety guideline adoption curves.
Underlying measurement precision varies by segment; cooled defense systems and FDA-cleared medical devices carry tighter precision than price-sensitive commercial security deployments. Forecasts reflect documented assumptions regarding export control stability, rare earth supply continuity, and visible-light CMOS substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Instaprint Camera Market
Imaging
EUV Mask Inspection System Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Automotive 3D Imaging Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Wide Field Imaging Devices Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Image Intensifier Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Europe Machine Vision Systems Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Underwater Camera Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Global Digital Binoculars Market
Imaging
Microscopic Camera Market
Imaging
Camera Technology Market